
 Visual Field Testing Equipment Market | 2026-2036
Visual Field Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Visual Field Testing Equipment Market Insights
Hospital procurement of visual field testing equipment is shifting toward outpatient ophthalmology clinics as ambulatory surgical centers expand glaucoma management services. Carl Zeiss Meditec AG leverages its surgical microscope installed base to cross-sell perimetry platforms into integrated eye care workflows. Heidelberg Engineering GmbH sustains R&D intensity in confocal scanning technology for retinal nerve fiber layer analysis. OCULUS, Inc. specializes in compact tabletop perimeters targeting private practice channels.
Visual field testing equipment comprises diagnostic instruments that map a patient's peripheral and central vision sensitivity using projected light stimuli across standardized threshold algorithms. Automated perimetry systems employ static stimulus presentation with software-driven progression analysis to detect glaucomatous field loss patterns. Static perimetry dominates installed base volumes while software-based visual field platforms capture fastest-growing demand through cloud-connected data archiving and remote monitoring capabilities. Kinetic perimetry occupies a mature niche in neuro-ophthalmology assessment where manual Goldmann-style testing persists for irregular visual field mapping.
FDA Class II device regulations govern 510(k) clearance pathways for automated perimeters marketed in the United States, while CE marking under the EU MDR frames conformity assessment for European commercialization. ISO 10993 biocompatibility standards and IEC 60601 electrical safety requirements shape design validation protocols for manufacturers. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic algorithms as machine learning-based progression prediction modules enter clinical validation pipelines.
Market Dynamics
The migration of glaucoma diagnosis from hospital settings to ambulatory ophthalmology clinics is restructuring equipment procurement patterns, with outpatient facilities demanding compact, cloud-integrated perimetry systems that integrate into high-throughput screening workflows.
Growth Catalysts
- FDA 510(k) clearance pathways:Streamlined Class II device review accelerates commercialization timelines for automated perimetry manufacturers targeting the United States market.
- Ambulatory surgical centers:Expansion of outpatient glaucoma management services drives installed base growth for tabletop perimeters in private practice channels.
- Confocal scanning technology:Advancements in retinal nerve fiber layer analysis enhance diagnostic sensitivity for early-stage glaucoma detection protocols.
Market Restraints
- Optical component supply concentration:Precision lens and laser diode manufacturing clusters in Germany and Japan create vulnerability to regional production disruptions.
- Capital equipment replacement cycles:Extended seven-to-ten-year depreciation schedules for existing perimetry systems delay upgrade demand in budget-constrained hospital networks.
- Manual Goldmann perimetry persistence:Kinetic testing retains niche utility in neuro-ophthalmology assessment, limiting complete automation of the installed base.
Strategic Opportunities
- Remote monitoring capabilities:Cloud-connected visual field platforms enable teleophthalmology screening programs reaching underserved rural populations.
- Artificial intelligence integration:Machine learning-based progression prediction modules entering clinical validation pipelines offer differentiation for early movers.
- EU MDR conformity assessment:Enhanced CE marking requirements under the Medical Device Regulation create compliance barriers favoring established manufacturers with robust quality systems.
Industry Challenges
- Software validation complexity:FDA guidance evolution on AI-enabled diagnostic algorithms demands adaptive regulatory strategies for algorithm updates.
- Biocompatibility testing protocols:ISO 10993 compliance requirements for patient contact components extend design validation timelines.
- Legacy system interoperability:Integration of new perimetry platforms with existing electronic health record infrastructures requires customized interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Visual Field Testing Equipment Market |
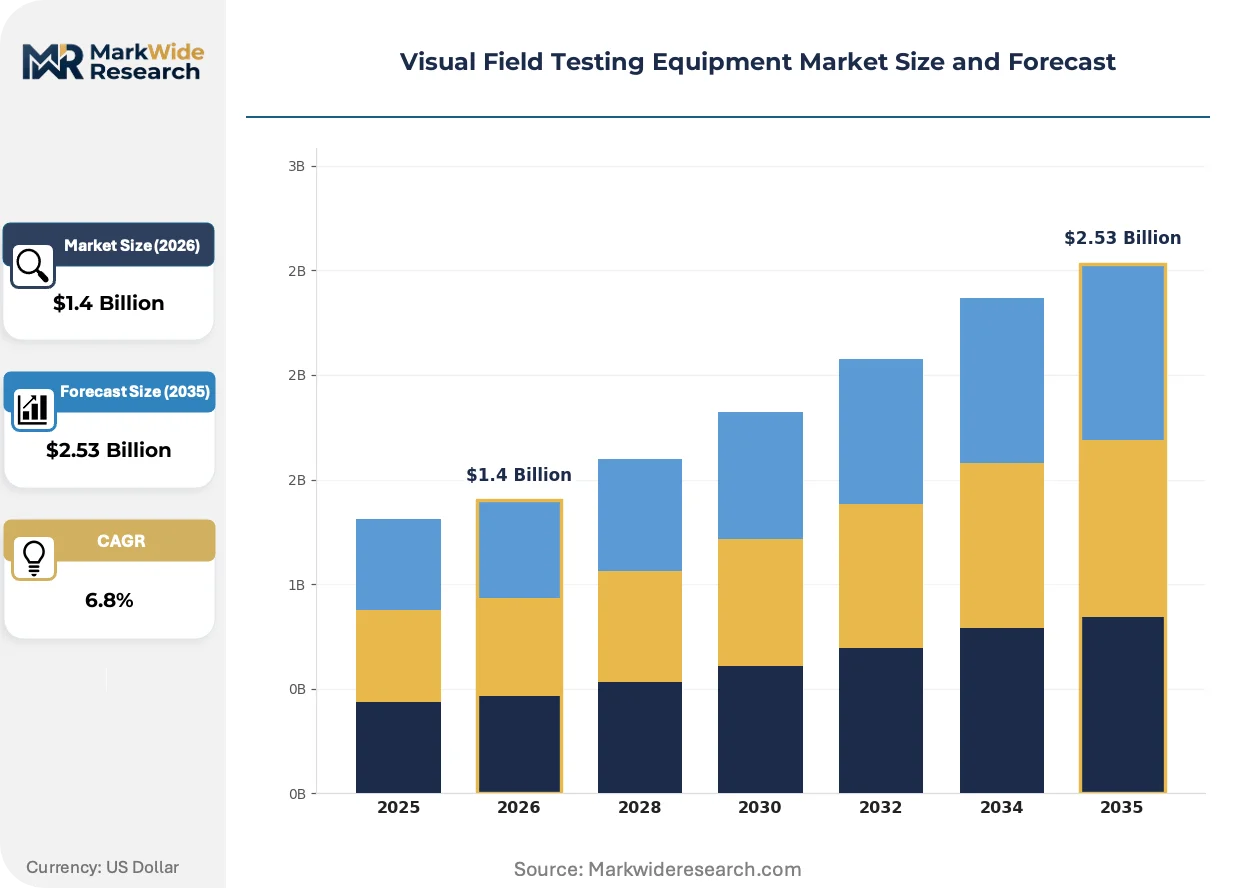
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Perimetry, Kinetic Perimetry, Frequency Doubling Technology, Pachymetry Technology: Static Perimetry, Dynamic Perimetry, Software-Based Visual Field, Networked Systems End User: Ophthalmology Clinics, Hospitals, Research Institutions, Optical Shops Distribution Channel: Direct Sales, Distributors, Online Sales, Specialty Retail |
| Companies Covered | Heidelberg Engineering GmbH, OCULUS, Inc., Carl Zeiss Meditec AG, Canon Inc., Essilor Instruments, Topcon Corporation, NIDEK Co., Ltd., Luneau Technology Group, Haag-Streit AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Visual Field Testing Equipment Market Trends and Innovations
Software-driven diagnostic platforms are displacing hardware-centric perimetry systems, with algorithmic progression analysis and remote data archiving becoming primary value drivers rather than physical instrument specifications alone.
Artificial intelligence is automating visual field interpretation through deep learning models trained on longitudinal glaucoma progression datasets. Ophthalmology clinics in the United States and Germany are adopting these tools to reduce specialist review burden. The technology is automating threshold detection and pattern recognition, compressing the time from test completion to clinical decision.
The EU Medical Device Regulation is tightening conformity assessment requirements for automated diagnostic equipment. Manufacturers must demonstrate clinical evidence for software algorithms beyond traditional hardware safety validation. European notified bodies are extending review timelines, prompting firms to front-load clinical validation investments.
Equipment leasing and managed service contracts are displacing outright capital purchases in hospital procurement. Ambulatory surgical centers prefer bundled perimetry-as-a-service agreements that include maintenance, software updates, and remote technical support. This shift is most visible in the United States, where outpatient facility consolidation creates purchasing leverage for standardized fleet deployments.
Visual Field Testing Equipment Market Segmentation
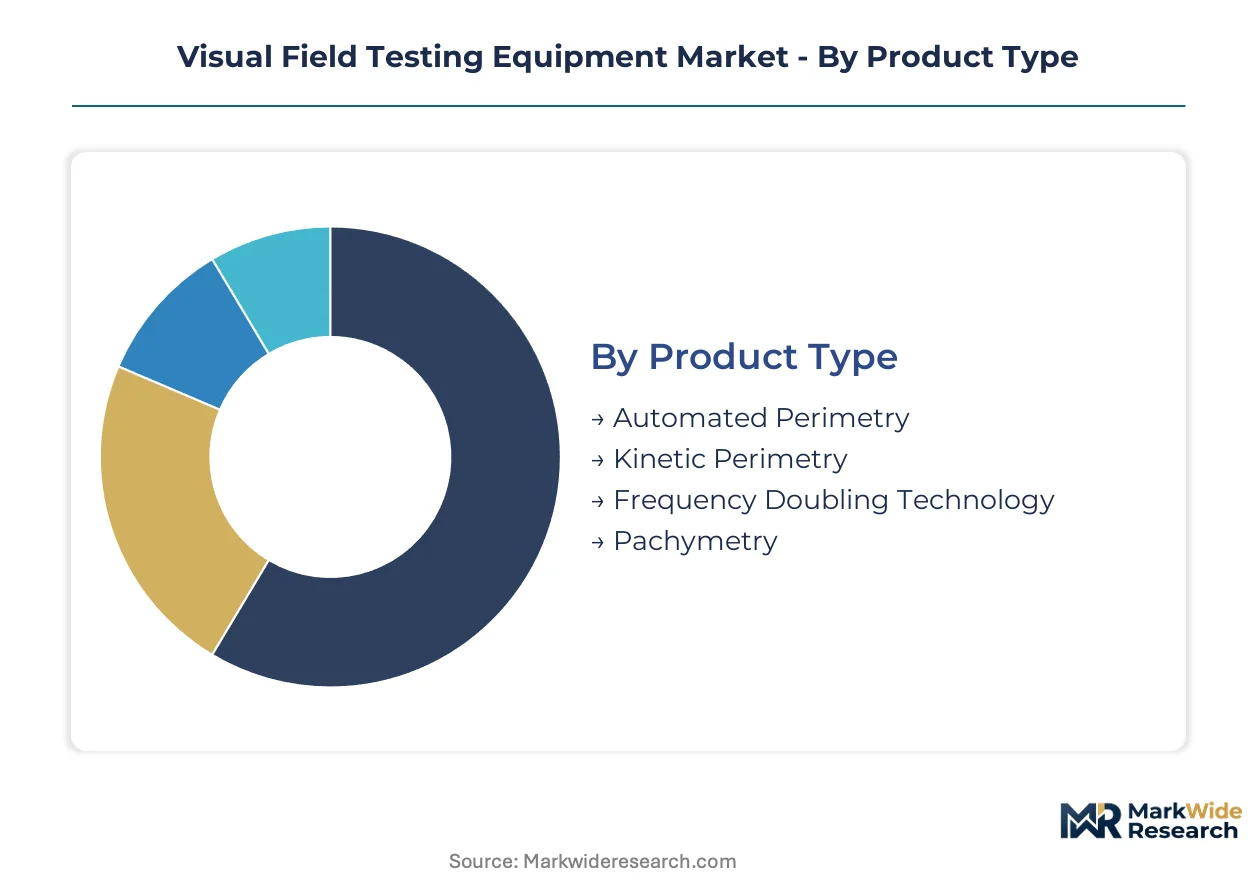
Visual field testing equipment segments diverge sharply by clinical workflow integration and capital intensity. Technology choices determine software upgrade pathways, while end-user channel selection shapes service contract structures and pricing leverage.
Product Type:
Clinical utility and automation depth separate equipment categories, with diagnostic precision requirements driving procurement decisions across ambulatory settings.
- Automated Perimetry:Static stimulus presentation with algorithmic threshold tracking dominates glaucoma screening protocols. Heidelberg Engineering GmbH and Carl Zeiss Meditec AG concentrate manufacturing in Germany, where outpatient ophthalmology clinics expand installed base volumes for high-throughput workflows.
- Kinetic Perimetry:Manual Goldmann-style testing employs moving stimuli across calibrated hemispheric bowls for irregular visual field mapping. Neuro-ophthalmology assessment in research institutions sustains niche demand despite slower throughput compared to automated alternatives.
- Frequency Doubling Technology:Magnocellular pathway assessment enables rapid screening with reduced test duration.
- Pachymetry:Central corneal thickness measurement integrates with perimetry platforms for comprehensive glaucoma risk stratification.
Automated Perimetry leads on scale; Frequency Doubling Technology leads on momentum.
Technology:
Software architecture and connectivity capabilities now differentiate equipment performance more than optical hardware specifications alone.
- Static Perimetry:Fixed-location stimulus presentation with threshold sensitivity mapping constitutes the installed base majority. Cloud-connected data archiving capabilities in newer systems enable remote monitoring programs reaching underserved rural populations in the United States.
- Dynamic Perimetry:Variable stimulus intensity protocols adapt testing parameters based on real-time patient response patterns.
- Software-Based Visual Field:Algorithmic progression analysis and machine learning-based prediction modules compress specialist review burden. FDA guidance evolution on AI-enabled diagnostic algorithms demands adaptive regulatory strategies for manufacturers updating clinical validation pipelines.
- Networked Systems:Multi-device integration across hospital networks requires customized electronic health record interface development.
Static Perimetry retains volume concentration; Software-Based Visual Field gains share fastest.
End User:
Capital deployment patterns and service intensity requirements segment demand by facility type and patient throughput.
- Ophthalmology Clinics:Ambulatory surgical centers drive demand for compact tabletop perimeters with bundled maintenance contracts. OCULUS, Inc. targets private practice channels with space-efficient designs integrating into high-throughput screening workflows.
- Hospitals:Extended seven-to-ten-year depreciation schedules for existing perimetry systems delay upgrade demand in budget-constrained networks.
- Research Institutions:Clinical validation requirements for progression analysis algorithms front-load investment timelines under EU MDR conformity assessment.
- Optical Shops:Lower-acuity screening applications favor cost-optimized equipment configurations with reduced software feature sets.
Ophthalmology Clinics anchor volume expansion; Research Institutions concentrate R&D partnership value.
Distribution Channel:
Customer scale and technical support requirements determine channel economics and manufacturer margin structure.
- Direct Sales:Large hospital networks and consolidated ambulatory chains negotiate fleet deployments with standardized service agreements. Carl Zeiss Meditec AG leverages surgical microscope installed base relationships for cross-selling perimetry platforms.
- Distributors:Regional coverage for mid-sized ophthalmology practices requires inventory holding and technical training capabilities.
- Online Sales:Compact tabletop units with simplified installation protocols penetrate price-sensitive private practice segments.
- Specialty Retail:Optical shop channels demand point-of-sale financing and rapid replacement part availability.
Direct Sales commands premium pricing; Online Sales expands addressable market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are arbitraging compliance costs by concentrating automated perimetry production in jurisdictions with established medical device quality systems while serving price-sensitive markets through regional assembly partnerships. FDA 510(k) pathways and EU MDR conformity assessments create divergent cost structures that reshape investment location decisions.
United States
Ambulatory surgical centers in Texas and Florida are expanding glaucoma screening capacity with compact tabletop perimeters. FDA Class II device regulations govern 510(k) clearance timelines for automated perimetry systems entering commercial distribution. The Research Triangle Park cluster in North Carolina hosts validation facilities for AI-enabled diagnostic algorithms undergoing clinical pipeline review.
Germany
Outpatient ophthalmology clinics in Bavaria and Baden-Württemberg drive installed base expansion for high-throughput screening workflows. EU MDR conformity assessment requirements under the Medical Device Regulation extend review timelines for software-enabled diagnostic platforms. The Heidelberg-Mannheim corridor anchors precision optics manufacturing clusters supplying laser diodes and confocal scanning components.
Japan
Academic medical centers in Tokyo and Osaka sustain demand for kinetic perimetry systems in neuro-ophthalmology research applications. PMDA regulatory frameworks align with international harmonization initiatives for ophthalmic diagnostic equipment. The Nagoya manufacturing belt concentrates optical component fabrication serving domestic perimetry assembly operations.
China
Tier-one hospitals in Shanghai and Beijing are upgrading from manual Goldmann testing to automated static perimetry platforms. NMPA medical device registration requirements are converging with international standards for Class II diagnostic instruments. The Suzhou industrial park hosts contract manufacturing facilities producing cost-optimized perimetry systems for domestic distribution.
India
Private ophthalmology chains in Maharashtra and Karnataka are adopting cloud-connected perimetry systems for teleophthalmology outreach programs. CDSCO medical device rules govern import licensing and local manufacturing registration for automated diagnostic equipment. The Hyderabad medical device cluster is emerging as a regional hub for software-based visual field platform assembly.
Visual Field Testing Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier German and Japanese firms commanding hospital procurement while Asian fabricators penetrate price-sensitive private practice channels. The market structure consolidates around three to five dominant equipment archetypes supported by specialized optical component suppliers. Strategic archetypes include integrated eye care platform vendors, standalone perimetry specialists, and contract electronics manufacturers serving white-label distribution. Competitive moves center on cross-selling into installed surgical microscope bases and bundling perimetry-as-a-service contracts for ambulatory facility consolidation.
Among Germany-based precision instrument manufacturers, Heidelberg Engineering GmbH and Carl Zeiss Meditec AG exemplify the integrated platform archetype, leveraging confocal scanning and surgical visualization technology positions to anchor regional supply relationships. OCULUS, Inc. represents the compact tabletop specialization vector, targeting space-constrained private practice workflows with simplified installation protocols. These three firms illustrate how geographic clustering around regulatory expertise and optical engineering talent creates defensive positioning against cost-optimized entrants.
| Leading Market Players |
|---|
| Heidelberg Engineering GmbH |
| OCULUS, Inc. |
| Carl Zeiss Meditec AG |
| Canon Inc. |
| Essilor Instruments |
| Topcon Corporation |
| NIDEK Co., Ltd. |
| Luneau Technology Group |
| Haag-Streit AG |
| Others |
Pricing and Supply Chain Analysis
Laser diode spot prices in Japan and Germany cascade through three distinct pricing tiers for automated perimetry systems, with precision optical component costs compressing margins at the economy tier while FDA-validated platforms command premium positioning. The Heidelberg-Mannheim corridor's confocal scanning component clusters create geographic pricing power that downstream manufacturers arbitrage through regional assembly partnerships.
Pricing Analysis
Distributor margins of 15-25% separate factory gate from end-user pricing for tabletop perimeters, while direct hospital procurement secures volume discounts off list. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) validation status and software algorithm sophistication. Pricing pressure stems from extended seven-to-ten-year replacement cycles in budget-constrained hospital networks. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while academic medical centers prioritize diagnostic precision over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle consolidated ambulatory chain demand, while regional distributors serve fragmented private practice networks. Precision lens and laser diode manufacturing concentrates in Germany, Japan, and the United States. Supply chains draw from specialized optical glass foundries, semiconductor laser fabs, and precision machining operations. Single-source vulnerability exists for confocal scanning subassemblies sourced from the Heidelberg-Mannheim corridor. Distribution runs through manufacturer-direct sales teams for hospital networks and authorized distributors for mid-market ophthalmology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturers arbitrage compliance costs between FDA 510(k) pathways and EU MDR conformity assessments, with streamlined Class II review in the United States offering faster commercialization against Europe's extended software validation timelines.
For Market Incumbents: Hedge optical component supply concentration by qualifying secondary laser diode sources in Japan and the United States outside the Heidelberg-Mannheim corridor. Lock in long-term service contracts with ambulatory surgical center consolidators to defend installed base against compact tabletop entrants. Prioritize AI-enabled progression prediction modules entering clinical validation pipelines as differentiation against hardware-centric competitors. For New Entrants and Emerging Players: Price-sensitive optical shops in India and Southeast Asia represent the most penetrable buyer archetype for cost-optimized perimetry platforms with reduced software feature sets. Target cloud-connected tabletop units for teleophthalmology outreach programs reaching underserved rural populations. Pursue online sales channels with simplified installation protocols to bypass established distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR software validation requirements extend review timelines beyond smaller competitors' capital reserves. Long-term viability favors firms with integrated confocal scanning technology positions and established regulatory quality systems. Acquisition targets include compact tabletop specialists with private practice channel relationships. Monitor FDA guidance evolution on AI-enabled diagnostic algorithms as inflection indicator for algorithmic differentiation value.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessment for software-enabled platforms front-loads clinical validation investments in Germany. |
| Hospital System Partnership | Fleet deployment agreements with consolidated ambulatory chains in Texas and Florida secure recurring service revenue streams. |
| Software Companion Development | Machine learning-based progression prediction modules undergoing FDA pipeline review differentiate against hardware-centric competitors. |
| Reimbursement Strategy | Alignment with Medicare glaucoma screening coverage policies in the United States accelerates private practice adoption curves. |
| Backward Integration | In-house production of confocal scanning subassemblies mitigates single-source vulnerability from Heidelberg-Mannheim suppliers. |
Research Methodology
Bottom-up ophthalmology clinic procurement modeling reconciled against top-down automated perimetry manufacturing tracking forms the analytical core of this study. Primary interviews with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body records, hospital procurement databases, and CMS Medicare reimbursement data. Triangulation across these sources ensures segment-level precision.
Input-output matrices map static perimetry, kinetic perimetry, and software-based visual field platform volumes against confocal scanning component supply across the projection horizon. Segmentation dimensions include product type, technology architecture, end-user facility category, and distribution channel. CAGRs derive from installed base growth rates, replacement cycle timing, and ambulatory surgical center expansion patterns. Forecast inputs incorporate FDA clearance timeline assumptions and EU MDR review period estimates.
Underlying measurement precision varies by segment; automated perimetry and software-based visual field platforms carry tighter precision than mature kinetic perimetry niches. Forecasts reflect documented assumptions regarding regulatory pathway timelines, ambulatory facility consolidation rates, and optical component supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market