
 Global Cardiovascular Information System Market | 2026-2036
Global Cardiovascular Information System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiovascular Information System Market Foresight
Aftermarket service revenue is fragmenting across hardware maintenance, software subscription renewals, and remote monitoring contracts. Koninklijke Philips N.V. leverages its installed base of imaging systems to capture recurring service income. GE HealthCare Technologies anchors its position through predictive analytics bundled with enterprise CVIS deployments. Siemens Healthineers AG competes by extending its digital health portfolio into AI-assisted cardiac reporting workflows.
A cardiovascular information system integrates cardiac imaging data, hemodynamic measurements, and electrocardiogram records into a unified digital platform, typically supporting DICOM and HL7 FHIR interoperability standards to enable real-time clinical decision support across catheterization labs and echocardiography suites. The platform's primary purpose is to eliminate data silos between diagnostic modalities and electronic health records, reducing manual transcription errors and accelerating treatment pathways for acute coronary events. Cardiac PACS and hemodynamic monitoring systems carry the deepest installed bases, while telecardiology solutions represent the fastest-expanding deployment category as rural networks seek specialist access without capital-intensive infrastructure. Cloud-based platforms are displacing on-premise architectures in mid-sized cardiology clinics where IT staffing constraints limit local server management.
The US FDA governs software-as-medical-device classifications for AI-enabled diagnostic modules within CVIS platforms, while the EU MDR imposes stricter clinical evidence requirements on systems marketed for patient management in European member states. Japan's PMDA maintains distinct approval pathways for cloud-hosted patient data systems, creating compliance complexity for vendors seeking unified product architectures. Stakeholders must monitor evolving cybersecurity mandates from national health regulators, as connected cardiac devices face escalating scrutiny over data breach vulnerabilities and patient privacy protections.
Market Dynamics
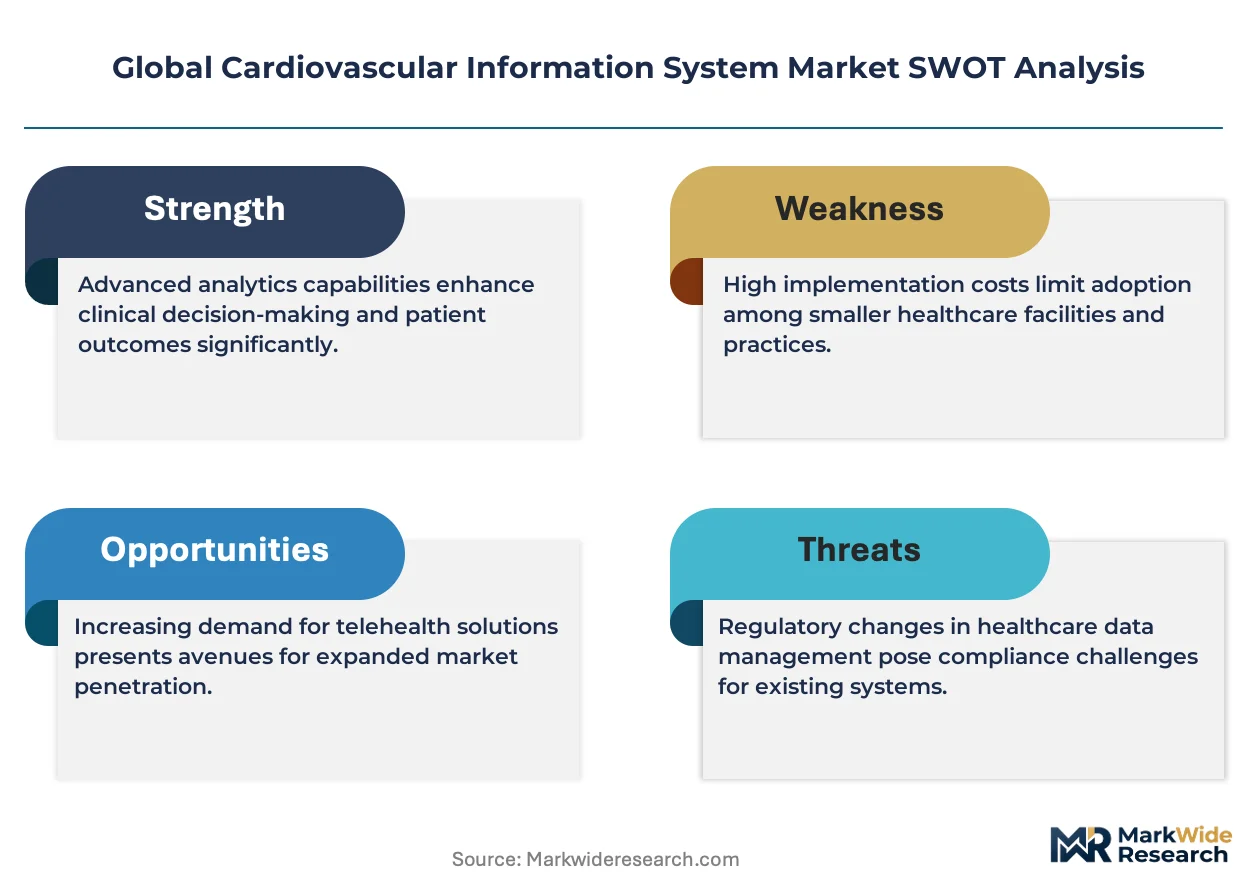
Hospital consolidation into integrated delivery networks is compressing vendor selection cycles, forcing CVIS suppliers to bundle enterprise imaging with hemodynamic monitoring and EHR interoperability under single-contract terms.
Growth Catalysts
- FDA's 21st Century Cures Act interoperability mandates:The framework requires EHR systems to support standardized data exchange, compelling cardiology departments to replace siloed legacy archives with unified platforms.
- Cloud infrastructure maturation:Mid-sized cardiology clinics lacking dedicated IT staff are abandoning on-premise server architectures for SaaS-based CVIS deployments with automatic security patching.
- Acute coronary syndrome treatment acceleration:Cath labs require real-time hemodynamic data integration with imaging to compress door-to-balloon times below guideline thresholds.
Market Restraints
- EU MDR clinical evidence requirements:Systems marketed for patient management in European member states face extended approval timelines and costly post-market surveillance obligations.
- Specialized cardiac informaticist scarcity:Health systems struggle to recruit personnel capable of bridging clinical cardiology workflows with DICOM and HL7 FHIR technical implementation.
- Hybrid cloud complexity:Japan's PMDA maintains distinct approval pathways for cloud-hosted patient data, fragmenting product architectures for vendors seeking unified global deployments.
Strategic Opportunities
- Rural telecardiology networks:Underserved regions in the United States and Germany seek specialist access without capital-intensive infrastructure investments.
- AI-assisted cardiac reporting convergence:Machine learning modules for automated ejection fraction calculation and wall-motion scoring are integrating into standard reporting workflows.
- Subscription-based remote monitoring:Vendors can capture recurring revenue through continuous hemodynamic surveillance contracts extending beyond initial hardware deployment.
Industry Challenges
- Legacy PACS migration complexity:Decades of DICOM archives in proprietary formats resist seamless transfer to modern CVIS platforms without manual data reconciliation.
- Cybersecurity compliance fragmentation:National health regulators impose divergent data breach notification and encryption standards across the United States, Germany, and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiovascular Information System Market |
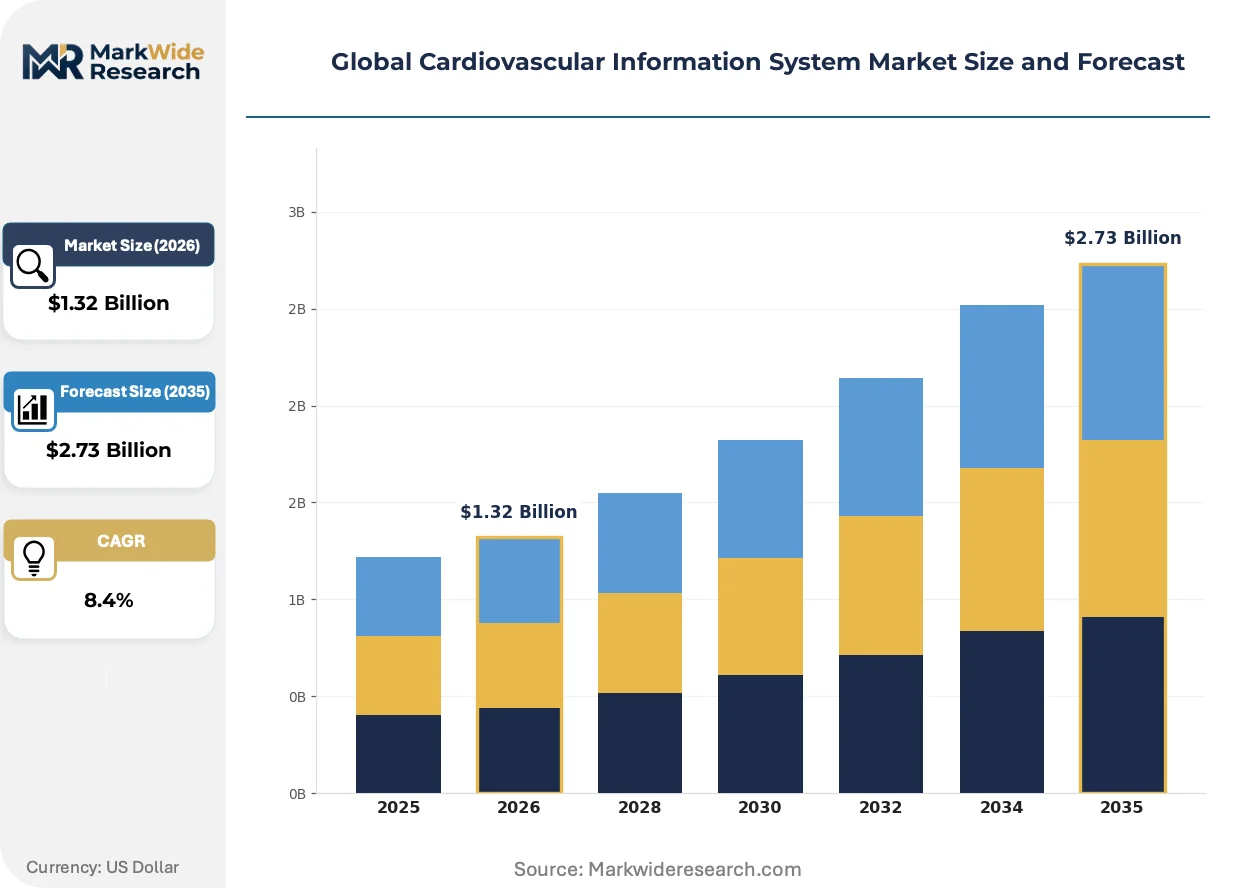
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac PACS, Electrocardiogram Systems, Hemodynamic Monitoring Systems, Telecardiology Solutions Application: Arrhythmia Detection, Heart Failure Management, Coronary Artery Disease, Stroke Risk Assessment End User: Cardiology Clinics, Diagnostic Laboratories, Rehabilitation Centers, Ambulatory Surgical Centers Deployment: On-Premise, Cloud-Based, Hybrid, Web-Based Platforms |
| Companies Covered | Koninklijke Philips N.V., GE HealthCare Technologies, Siemens Healthineers AG, Intelerad Medical Systems, FUJIFILM Holdings Corporation, Cisco Systems, Cerner Corporation, Esaote SpA, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiovascular Information System Market Shifts & Advancements
Artificial intelligence modules and cloud-native architectures are restructuring how cardiac imaging data flows from acquisition to clinical decision support, compressing traditional hardware-centric business models.
AI-enabled diagnostic algorithms embedded within CVIS platforms are rendering obsolete the manual measurement protocols that previously required specialized sonographer expertise for quantitative cardiac function assessment. Community hospitals and outpatient imaging centers are adopting these modules faster than academic medical centers due to staffing constraints. The technology is rendering obsolete the historical premium placed on subspecialty-trained cardiologists for routine echocardiogram interpretation.
The EU MDR imposes stricter clinical evidence requirements on systems marketed for patient management in European member states than predecessor directives. Manufacturers must now generate prospective clinical data for software updates that previously qualified as maintenance releases. Class III device classifications for AI diagnostic modules are forcing vendors to establish European authorized representatives and quality management systems earlier in product lifecycles.
Buying committees now unbundle hardware procurement from software subscriptions and service agreements, reversing the traditional single-vendor bundling model. Health system supply chains are disaggregating imaging equipment from informatics platforms, enabling best-of-breed software selection independent of scanner manufacturer relationships. This pattern is most pronounced in Germany, where hospital procurement cooperatives negotiate enterprise software licenses separately from radiology and cardiology device capital cycles.
Global Cardiovascular Information System Market Segmentation
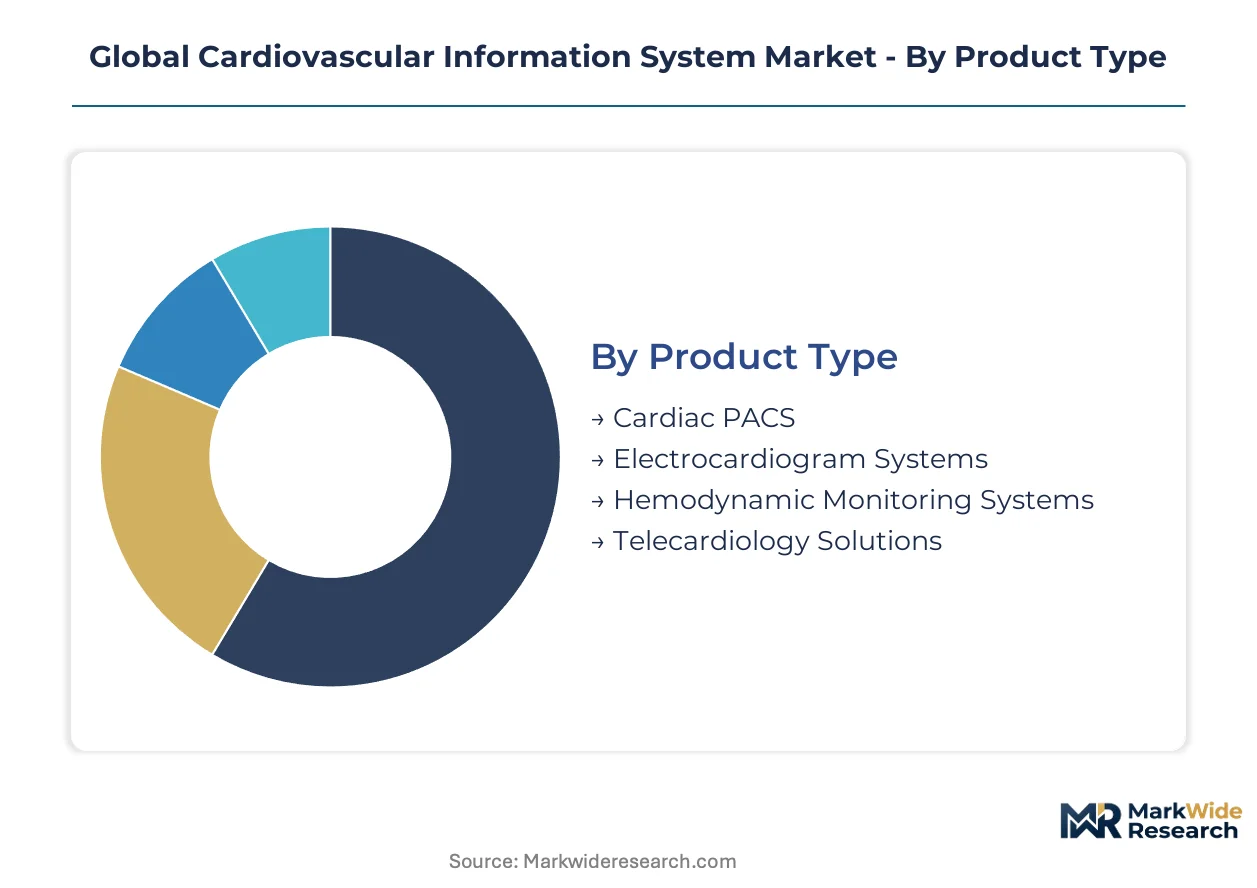
CVIS procurement patterns diverge sharply across product architectures, clinical applications, and facility types. Understanding these segment boundaries reveals where replacement cycles accelerate and where installed bases remain sticky.
Product Type:
Replacement velocities vary dramatically across this category, with imaging archives turning over slowly while remote access platforms refresh rapidly.
- Cardiac PACS:These systems manage DICOM-compliant storage and distribution of echocardiography, cardiac CT, and cath lab angiography datasets. Hospital networks in the United States prioritize PACS consolidation during EHR interoperability upgrades mandated by FDA's 21st Century Cures Act framework.
- Telecardiology Solutions:Cloud-native platforms enabling real-time cardiac consultation and remote monitoring for underserved regions. German rural health networks deploy these fastest to bypass cardiologist staffing shortages without cath lab construction.
- Electrocardiogram Systems:Digital ECG management with automated arrhythmia detection algorithms integrated into enterprise workflows.
- Hemodynamic Monitoring Systems:Real-time physiological data acquisition from catheterization labs supporting interventional cardiology procedures.
Cardiac PACS dominates installed base. Telecardiology Solutions is where expansion concentrates.
Application:
Clinical urgency shapes purchasing authority, with acute syndromes commanding capital budgets while chronic conditions rely on operational funding.
- Coronary Artery Disease:CVIS deployments supporting cath lab workflow optimization and rapid door-to-balloon time reporting. Japanese academic medical centers lead adoption here as PMDA streamlines software-as-medical-device approvals for acute care modules.
- Heart Failure Management:Platforms integrating implantable device data with echocardiographic surveillance for longitudinal patient tracking. United States integrated delivery networks bundle these into value-based care contracts with Medicare Advantage plans.
- Arrhythmia Detection:Automated atrial fibrillation screening through continuous ECG monitoring and AI-enhanced waveform analysis.
- Stroke Risk Assessment:Left atrial appendage occlusion planning tools combined with transesophageal echocardiography reporting workflows.
Coronary Artery Disease commands the largest procurement budgets. Heart Failure Management is climbing the fastest as reimbursement shifts toward episode-based payment.
End User:
Capital availability and IT sophistication create tiered adoption patterns across facility types.
- Cardiology Clinics:Independent and hospital-affiliated outpatient practices requiring streamlined reporting and referral coordination. Mid-sized clinics in Germany's ambulatory care sector are migrating fastest from on-premise servers to SaaS architectures.
- Diagnostic Laboratories:High-volume cardiac testing facilities processing stress echocardiography and nuclear cardiology studies. United States reference labs drive demand for automated measurement tools that reduce sonographer interpretation time.
- Ambulatory Surgical Centers:Freestanding facilities performing diagnostic catheterization and pacemaker implantation with limited IT staffing.
- Rehabilitation Centers:Post-acute facilities monitoring cardiac recovery through telemetry integration and exercise stress testing documentation.
Cardiology Clinics represent the broadest deployment footprint. Diagnostic Laboratories are gaining share fastest through centralized testing consolidation.
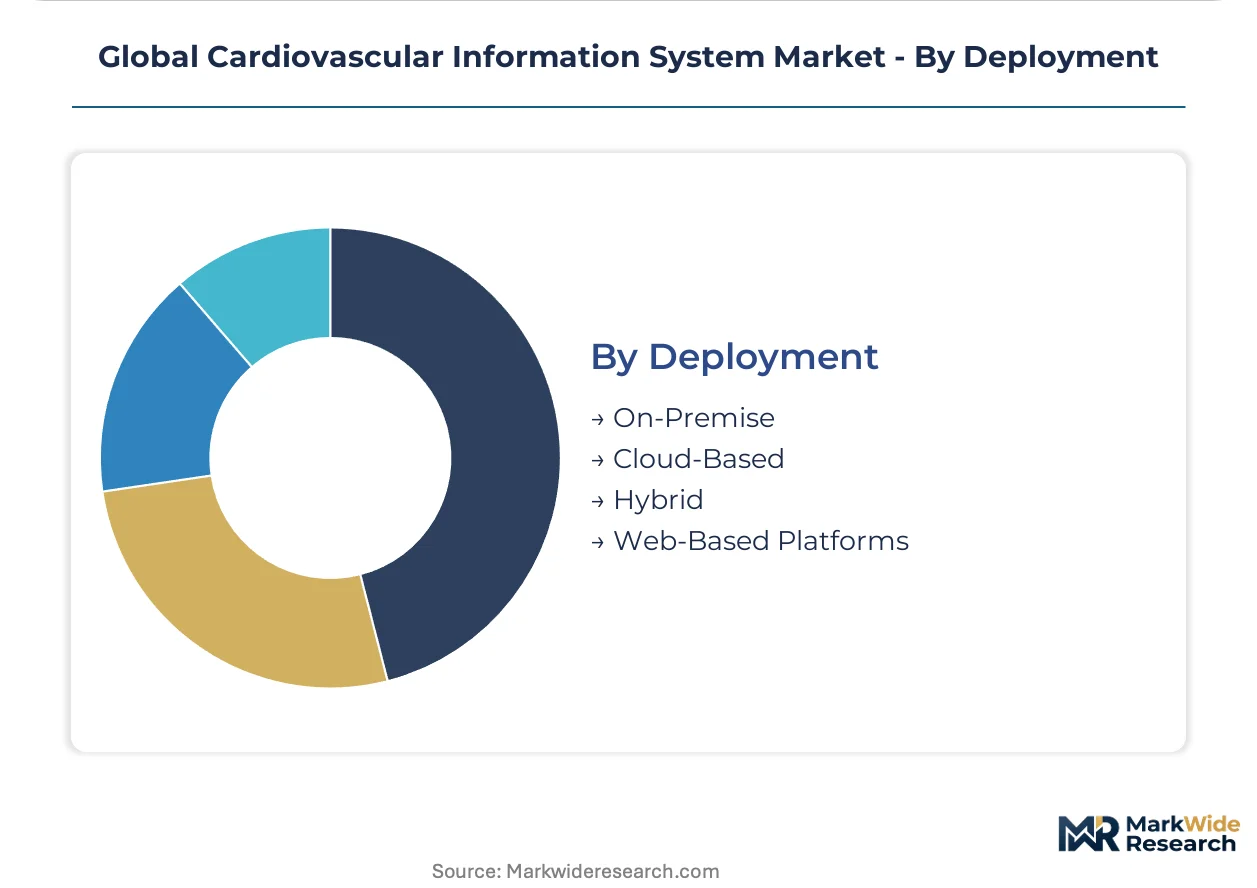
Deployment:
Architecture choices reflect risk tolerance for data sovereignty against operational flexibility needs.
- Cloud-Based:Fully hosted SaaS platforms with automatic security patching and elastic storage scaling. Japan's distinct PMDA approval pathways for cloud-hosted patient data create compliance friction that slows unified global product rollouts.
- On-Premise:Local server installations maintaining physical data control for high-security health systems. German university hospitals retain these for research datasets requiring GDPR-compliant geographic data residency.
- Hybrid:Mixed architectures keeping sensitive patient records local while pushing analytics workloads to cloud infrastructure.
- Web-Based Platforms:Browser-accessible systems requiring minimal endpoint configuration for multi-site access.
On-Premise retains legacy dominance. Cloud-Based is expanding most quickly as mid-sized facilities abandon server management burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CVIS consumption patterns diverge sharply across geographies. United States hospital networks prioritize EHR interoperability mandates, while German procurement cooperatives unbundle hardware from software. Japanese academic centers drive AI diagnostic adoption under distinct regulatory pathways.
United States
Integrated delivery networks dominate procurement, bundling enterprise imaging with hemodynamic monitoring under single-contract terms. FDA's 21st Century Cures Act interoperability mandates compel cardiology departments to replace siloed legacy archives. The Cleveland Clinic and Mayo Clinic anchor adoption clusters in the Midwest, where value-based care contracts with Medicare Advantage plans accelerate heart failure management platform deployment.
Germany
Hospital procurement cooperatives negotiate enterprise software licenses separately from radiology device capital cycles, fragmenting traditional vendor bundling. EU MDR clinical evidence requirements extend approval timelines for systems marketed for patient management. Bavaria's university hospitals retain on-premise architectures for research datasets requiring GDPR-compliant geographic data residency.
Japan
Academic medical centers lead adoption of acute care modules as PMDA streamlines software-as-medical-device approvals. The regulator maintains distinct pathways for cloud-hosted patient data, creating compliance friction that slows unified global product rollouts. Tokyo and Osaka metropolitan clusters concentrate cath lab workflow optimization investments.
United Kingdom
NHS integrated care systems consolidate vendor selection cycles, favoring platforms with predictive analytics capabilities. GDPR and post-Brexit data sovereignty requirements influence cloud deployment decisions. London's tertiary cardiac centers drive telecardiology network expansion into rural England and Wales.
India
Mid-sized cardiology clinics in Maharashtra and Karnataka migrate fastest from on-premise servers to SaaS architectures, bypassing IT staffing constraints. CDSCO oversight of software-as-medical-device classifications remains less prescriptive than FDA or PMDA frameworks. Hyderabad's health technology corridor hosts emerging telecardiology platform development.
Global Cardiovascular Information System Market Competitive Landscape
Capability concentration sits with imaging equipment specialists; scale advantage sits with diversified health technology conglomerates. The vendor base structures around three tiers: full-stack platform providers, imaging-centric informatics specialists, and enterprise software integrators. Strategic moves center on predictive analytics bundling and AI-assisted cardiac reporting workflow extension.
Within the imaging-centric tier, Koninklijke Philips N.V. and Siemens Healthineers AG exemplify equipment-to-informatics extension strategies, leveraging installed bases of imaging systems to capture recurring service income. GE HealthCare Technologies anchors the diversified conglomerate position. Enterprise software integrators including Cerner Corporation occupy workflow interoperability niches.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| GE HealthCare Technologies |
| Siemens Healthineers AG |
| Intelerad Medical Systems |
| FUJIFILM Holdings Corporation |
| Cisco Systems |
| Cerner Corporation |
| Esaote SpA |
| McKesson Corporation |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint fragmentation across FDA, EU MDR, and PMDA approval pathways compresses pricing tier spreads while forcing vendors into region-specific supply chain configurations that duplicate compliance infrastructure. Hardware-software unbundling in German procurement cooperatives and US integrated delivery networks accelerates this bifurcation, with subscription-based SaaS tiers displacing capital-intensive perpetual licenses.
Pricing Analysis
Long-term enterprise contracts dominate CVIS procurement, with hospital networks negotiating multi-year SaaS subscriptions bundled with predictive analytics and remote monitoring services. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by AI module depth, HL7 FHIR interoperability certification, and after-sales service intensity. Cost compression in mid-tier cloud deployments intensifies because mid-sized cardiology clinics lack IT staffing to negotiate customization. Diagnostic laboratories exhibit lowest price sensitivity due to centralized testing volume scale, while independent cardiology clinics in India's ambulatory sector drive hardest bargain hunting.
Supply Chain Analysis
Contract manufacturing for CVIS hardware concentrates in Taiwan and South Korea for imaging system components, with software development anchored in the United States and Germany. The supply chain draws from specialized semiconductor foundries for GPU-accelerated AI modules, medical-grade display panels, and DICOM-compliant storage arrays. Single-source vulnerability sits with cloud infrastructure providers hosting patient data under divergent national sovereignty requirements. Distribution runs through hospital procurement cooperatives in Germany, group purchasing organizations in the United States, and academic medical center consortia in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CVIS vendors must treat service-attach revenue as the primary expansion vector, with remote monitoring contracts and AI-assisted reporting subscriptions outpacing hardware deployment growth across all major markets.
For Market Incumbents: Insulate installed base positions by deepening predictive analytics bundling with existing imaging system deployments, while accelerating backward integration into cloud infrastructure to reduce third-party hosting dependency. The threat of AI-native entrants with software-first architectures demands defensive certification investment in FDA software-as-medical-device pathways and EU MDR quality management systems. Channel control through exclusive hospital system partnerships remains the priority lever for margin defense. For New Entrants and Emerging Players: Establish a beachhead in telecardiology solutions for rural German health networks and US Medicare Advantage regions, where specialist staffing shortages create immediate deployment urgency without cath lab capital requirements. The most penetrable white space sits in AI-assisted cardiac reporting for community hospitals lacking subspecialty-trained cardiologists. A direct SaaS go-to-market model bypasses traditional hardware vendor relationships that dominate academic medical center procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform consolidators with proven EHR interoperability integration. Long-term viability over the next decade hinges on recurring revenue share exceeding hardware attach rates. Acquisition targets should demonstrate FDA 21st Century Cures Act compliance readiness and cloud-native architecture. The signal to watch is hospital network RFP unbundling velocity, where software selection separates from imaging equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| AI Module FDA Submission | Software-as-medical-device classification unlocks Medicare reimbursement for automated ejection fraction calculation. |
| Hospital System Partnership | Integrated delivery network exclusivity contracts compress competitor access across multi-site cardiology departments. |
| Cloud Infrastructure Backward Integration | In-house hosting capacity bypasses PMDA compliance friction for unified global product architectures. |
| Remote Monitoring Service Launch | Continuous hemodynamic surveillance contracts extend customer lifetime value beyond initial hardware deployment. |
| EU MDR Quality System Certification | CE marking pathway for patient management modules accelerates market access across German procurement cooperatives. |
Research Methodology
Operator-level perspectives from hospital purchasing committee chairs, biomedical informatics directors, GPO contracts managers, and cath lab operations heads anchored the qualitative base. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA medical device registration databases, CMS Medicare reimbursement schedules, and hospital procurement cooperative contract disclosures. Bottom-up deployment tracking across cardiology clinics and top-down vendor revenue analysis triangulated market sizing.
Scenario-bracketing around interoperability mandate acceleration and cloud security incident frequency shaped the analytical framework across the projection horizon. Segmentation modeling incorporated deployment architecture, clinical application urgency, facility IT sophistication, and regional regulatory cluster. CAGRs derived from replacement cycle velocity analysis and SaaS subscription renewal rate trajectories. Forecast inputs included PMDA cloud approval pathway timeline shifts and EU MDR post-market surveillance cost escalation.
Sensitivities concentrate around cybersecurity breach disclosure mandates and AI diagnostic module reclassification events. Forecasts embed assumptions regarding hospital consolidation pace and rural telecardiology reimbursement policy stability. Quarterly review of FDA software-as-medical-device submission volumes and German procurement cooperative RFP unbundling patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Information Systems
Medical Coding Market
Medical Information Systems
US Healthcare ERP Market
Medical Information Systems
Global Medical Decision Support Systems for Sepsis Market
Medical Information Systems
Global Medical Transcription Software Market
Medical Information Systems
Global Pharmacy Information System Market
Medical Information Systems
Mobile Medical Apps Market
Medical Information Systems
Global Medical Writing Market
Medical Information Systems
Post-Marketing Pharmacovigilance and Medical Information Market
Medical Information Systems
Global Clinical Documentation Improvement Market
Medical Information Systems
OBGYN EHR Market
Medical Information Systems
Dentistry EMR Software Market
Medical Information Systems
Medical 3D Software Market
Medical Information Systems
Donor Management Software Market
Medical Information Systems
Middle East Secure Messaging in Healthcare Market
Medical Information Systems
Global Healthcare Information Systems Market
Medical Information Systems
Medical Alert Systems Market