
 Lower GI Series Market | 2026-2036
Lower GI Series Market Size, Share, and Industry Trends Forecast 2026-2036
Lower GI Series Market Foresight
The USPSTF expanded colorectal cancer screening recommendations is restructuring procurement priorities across hospital systems and imaging networks. GE Healthcare leverages its installed base of fluoroscopy suites to sustain service contract renewals in acute care settings. Siemens Healthineers anchors its position through integrated CT colonography workflows that reduce patient prep burden. Fujifilm Holdings Corporation specializes in dual-contrast barium enema systems for cost-sensitive outpatient clinics.
A lower GI series encompasses fluoroscopic and cross-sectional imaging procedures examining the colon and rectum, typically employing barium sulfate contrast administered via enema to visualize mucosal patterns, strictures, and filling defects at spatial resolutions of 0.5-1.0 mm. These examinations serve primary diagnostic and screening functions for colorectal pathologies where endoscopic alternatives carry elevated risk or patient refusal. CT colonography leads product type demand growth due to superior sensitivity for polyps ≥6 mm and expanding Medicare coverage, while optical colonoscopy retains the largest revenue pool through therapeutic intervention capability. Hospitals dominate end user consumption by procedure volume, though imaging centers capture margin expansion through dedicated non-invasive screening programs.
The FDA governs 510(k) clearance pathways for contrast agents and imaging devices, while the CMS National Coverage Determination framework directly shapes reimbursement accessibility for screening populations. State-level certificate-of-need regulations in New York, Illinois, and California constrain capital equipment deployment, concentrating service availability around established health systems. Stakeholders must monitor evolving AI-assisted polyp detection algorithms and their potential to displace conventional radiologist interpretation models.
Market Dynamics
CMS reimbursement policy for CT colonography screening is restructuring capital allocation across hospital imaging departments and outpatient radiology networks, compressing traditional barium enema volumes while elevating cross-sectional modality procurement priorities.
Growth Catalysts
- USPSTF guideline expansion:Updated colorectal cancer screening recommendations lower the starting age to 45 years, expanding the addressable patient population for non-invasive imaging alternatives across United States health systems.
- Medicare coverage determination:The CMS National Coverage Determination for CT colonography as a screening modality removes prior authorization barriers for beneficiaries, accelerating procedure volume growth in Medicare Advantage networks.
- Fluoroscopy suite upgrades:Hospital capital replacement cycles are modernizing analog barium enema systems with digital subtraction capabilities, sustaining equipment refresh demand in acute care settings.
Market Restraints
- Barium sulfate supply concentration:Active pharmaceutical ingredient production for high-purity contrast agents clusters among three European chemical manufacturers, creating vulnerability to pharmaceutical-grade raw material allocation disruptions.
- Optical colonoscopy substitution:Therapeutic capability during index procedures and established gastroenterologist referral patterns limit radiologic screening penetration in integrated delivery networks with captive endoscopy capacity.
- Radiologist workforce constraints:Fellowship-trained abdominal imager availability fails to match CT colonography volume growth in non-metropolitan United States counties, creating interpretation bottlenecks.
Strategic Opportunities
- AI-assisted polyp detection:Computer-aided detection algorithms are unifying with standard CT colonography workstations, reducing perceptual error rates and enabling less experienced readers to maintain diagnostic accuracy thresholds.
- Direct-to-consumer screening channels:Employer wellness programs and retail health clinics are establishing self-referral pathways for CT colonography, bypassing traditional primary care gatekeeping in United States commercial populations.
- Low-dose protocol standardization:Sub-millisievert CT acquisition techniques are converging with iterative reconstruction software, expanding screening eligibility to radiation-sensitive patient cohorts previously excluded from cross-sectional surveillance.
Industry Challenges
- Legacy PACS integration complexity:CT colonography datasets with specialized 3D visualization requirements encounter interoperability friction with hospital enterprise imaging archives, necessitating costly vendor-neutral archive middleware deployment.
- Quality assurance standardization:Bowel preparation adequacy metrics and polyp measurement variability across imaging centers complicate multi-site screening program accreditation under American College of Radiology CT Colonography practice parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lower GI Series Market |
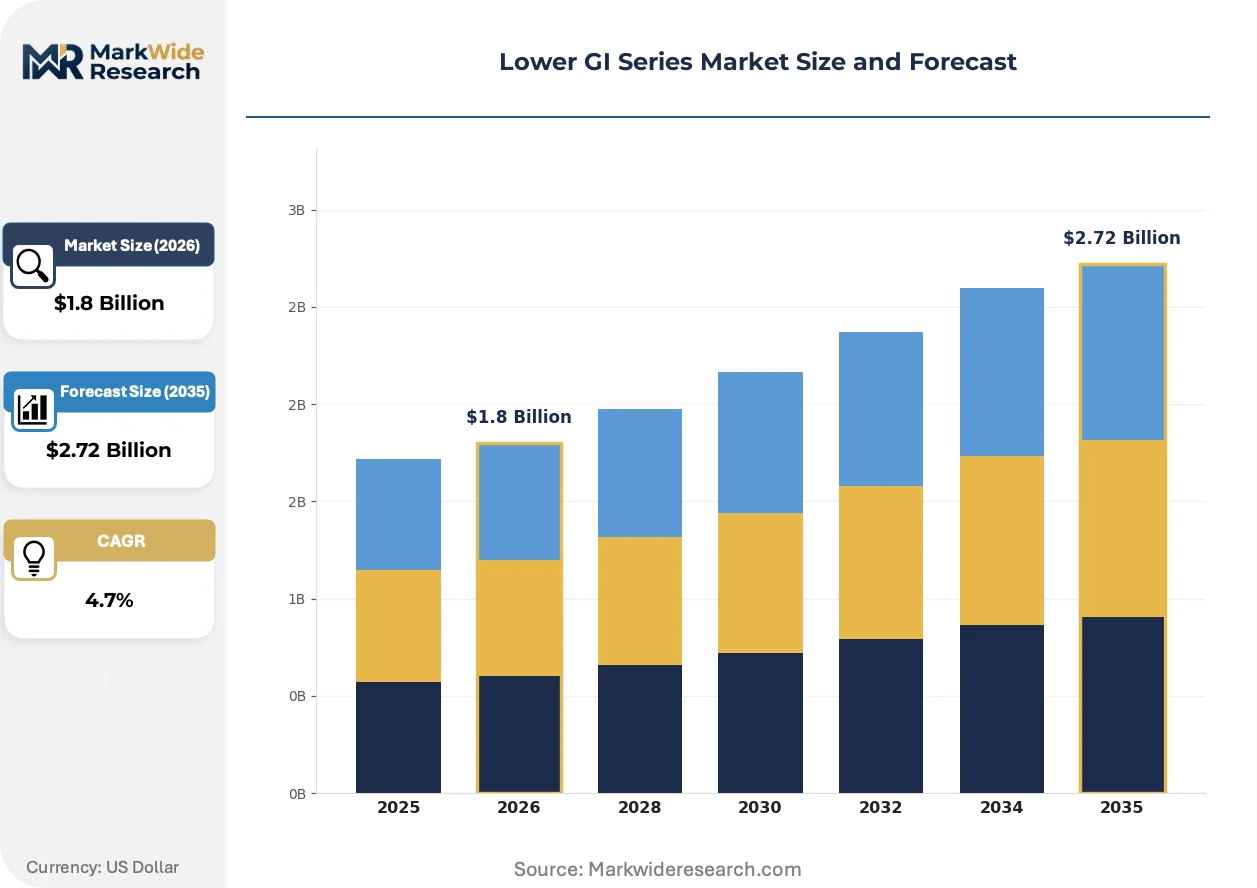
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barium Enema, CT Colonography, MRI Colonography, Optical Colonoscopy End User: Hospitals, Imaging Centers, Diagnostic Laboratories, Outpatient Clinics Delivery Mode: Invasive, Non-Invasive, Contrast Enhanced, Standard Imaging Application: Colorectal Cancer Screening, Inflammatory Bowel Disease, Diverticulitis Diagnosis, Routine Check-ups |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Fujifilm Holdings Corporation, Medtronic, Boston Scientific, Hologic, Olympus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lower GI Series Market Shifts & Advancements
Artificial intelligence integration and low-dose acquisition protocols are compressing the traditional trade-off between diagnostic sensitivity and patient accessibility, while regulatory coverage determinations restructure competitive positioning across screening modalities.
Computer-aided detection software for CT colonography is unifying polyp identification workflows with standard radiologist interpretation, reducing reading time burdens in high-volume screening programs. Academic medical centers and large community hospital networks are deploying these tools to extend reader capacity without proportional staffing expansion. The structural consequence is enabling smaller imaging centers to achieve diagnostic accuracy benchmarks previously requiring subspecialist interpretation, compressing competitive differentiation around radiologist credentialing alone.
The CMS National Coverage Determination for CT colonography screening is removing Medicare beneficiary cost-sharing barriers, triggering capital equipment procurement cycles across United States outpatient imaging networks. Private payer coverage mandates in several state insurance markets are following the federal precedent, expanding addressable volume for non-invasive alternatives. Integrated delivery systems in Florida, Texas, and Arizona are responding by consolidating CT colonography service lines into dedicated screening centers with standardized patient navigation protocols.
Self-referral pathways through employer-sponsored wellness platforms are displacing traditional primary care gatekeeping for colorectal cancer screening in United States commercial populations. Large self-insured employers and benefits administrators are contracting directly with imaging networks for bundled screening packages, compressing the role of gastroenterology referral networks. This channel shift is most visible in technology and financial services sectors with concentrated employee populations in metropolitan corridors, where on-site or near-site imaging partnerships reduce logistical friction for screening completion.
Lower GI Series Market Segmentation
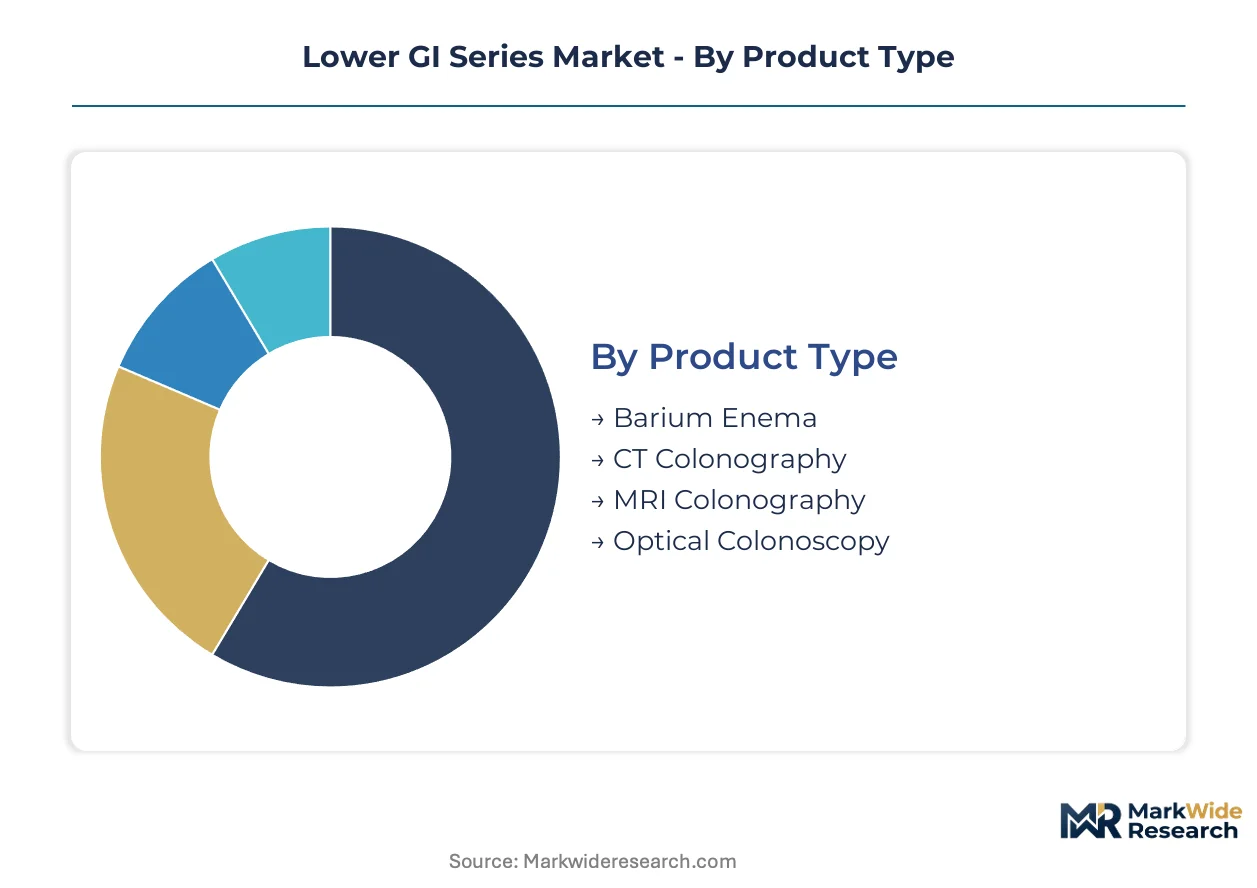
Lower GI series modalities occupy distinct positions along the cost-sensitivity and diagnostic capability spectrum. Procurement patterns diverge sharply between acute care systems prioritizing therapeutic integration and outpatient networks optimizing throughput per square foot.
Product Type:
Supply concentration among fluoroscopy suite manufacturers and contrast agent producers shapes competitive dynamics across imaging modalities.
- CT Colonography:Cross-sectional volumetric acquisition generates 3D endoluminal fly-through reconstructions with polyp detection thresholds at 6 mm. United States Medicare Advantage networks are driving procedure volume expansion following coverage determination updates.
- Barium Enema:Fluoroscopic examination employs barium sulfate suspension administered via enema to visualize mucosal contour and filling defects at 0.5-1.0 mm spatial resolution. Cost-sensitive outpatient clinics in rural United States counties sustain demand where CT scanner availability remains constrained.
- MRI Colonography:Non-ionizing modality utilizing T2-weighted sequences with fecal tagging eliminates radiation exposure for younger screening cohorts. Academic medical centers deploy this technology for surveillance in hereditary colorectal cancer syndromes.
- Optical Colonoscopy:Direct mucosal visualization with therapeutic polypectomy capability retains the largest revenue pool through intervention during index procedures. Gastroenterology-integrated delivery networks prioritize this modality for captive referral capture.
Optical colonoscopy absorbs the bulk of installed capacity; CT colonography is expanding most quickly.
End User:
Capital equipment deployment patterns reflect reimbursement accessibility and patient navigation infrastructure maturity.
- Hospitals:Acute care settings command procedure volume through emergency department diversion pathways and inpatient consultation services. Certificate-of-need regulations in New York, Illinois, and California concentrate service availability around established health systems.
- Imaging Centers:Dedicated outpatient facilities capture margin expansion through standardized non-invasive screening programs with direct-to-consumer marketing channels. Employer wellness contracting in Texas and Florida metropolitan corridors accelerates volume growth.
- Diagnostic Laboratories:Pathology-integrated operations focus on stool-based screening triage with imaging reserved for positive fecal immunochemical test follow-up. United States commercial laboratory networks leverage existing phlebotomy infrastructure for specimen collection.
- Outpatient Clinics:Federally qualified health centers and community health centers serve safety-net populations with barium enema alternatives where endoscopy capacity is limited. Rural health clinic designation enables cost-based reimbursement optimization.
Hospitals retain the dominant share of procedure volume; imaging centers are gaining share fastest.
Delivery Mode:
Patient preparation burden and procedural risk profile determine modality selection across screening and diagnostic indications.
- Non-Invasive:CT and MRI colonography eliminate sedation requirements and perforation risk, enabling same-day return to activity. United States employer wellness programs favor this category for occupational health compliance.
- Invasive:Endoluminal procedures including optical colonoscopy and flexible sigmoidoscopy provide tissue acquisition capability. Medicare coverage mandates sustain volume in beneficiary populations despite prep burden.
- Contrast Enhanced:Barium sulfate and iodinated contrast administration improves mucosal delineation in fluoroscopic and CT protocols. European pharmaceutical-grade raw material concentration creates supply vulnerability.
- Standard Imaging:Non-contrast CT and MRI sequences serve radiation-sensitive or renal-impaired cohorts with modified detection sensitivity. Pediatric and young adult surveillance protocols prioritize this approach.
Non-invasive modalities command the steepest expansion trajectory; invasive procedures retain therapeutic revenue concentration.
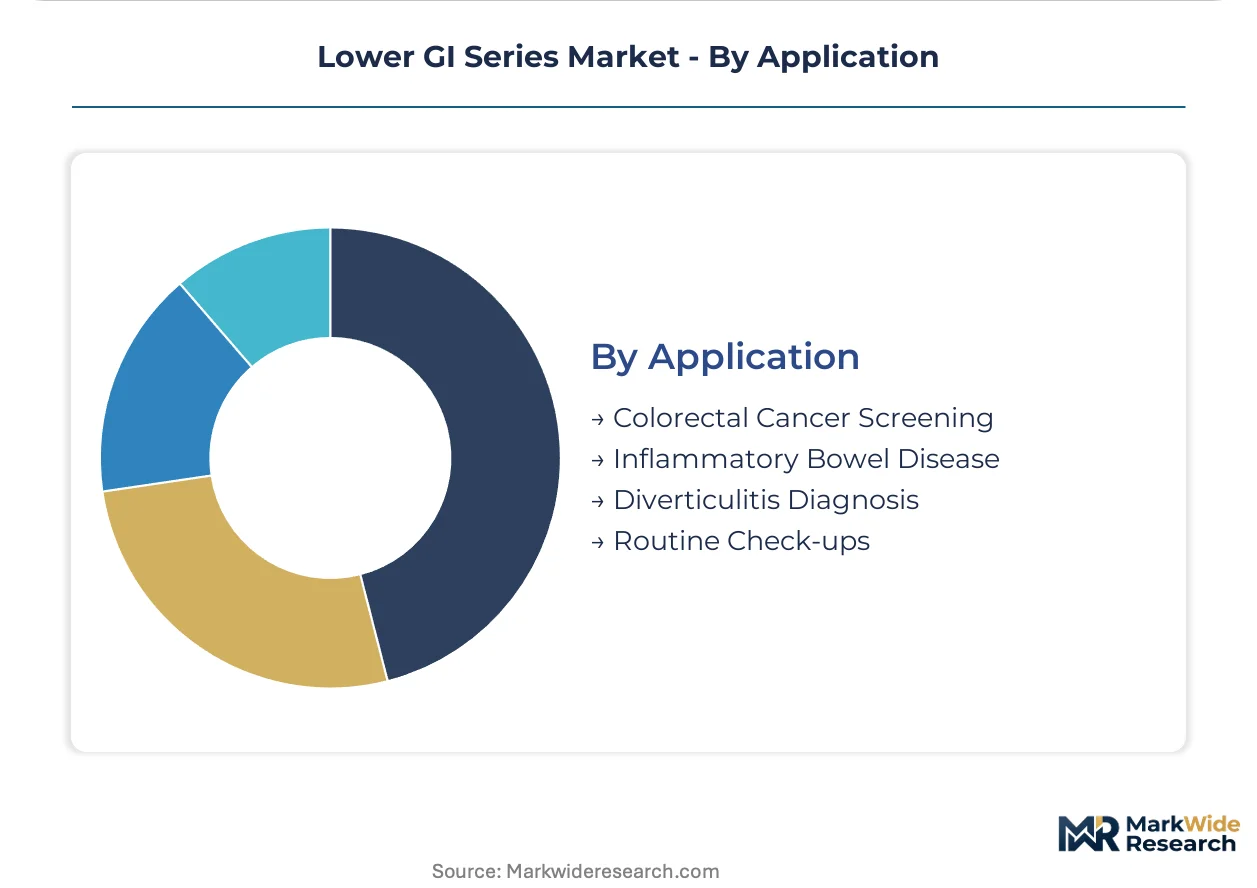
Application:
Clinical indication severity and surveillance interval requirements structure equipment utilization rates and reimbursement coding.
- Colorectal Cancer Screening:Asymptomatic population surveillance drives volume economics through high-throughput protocol standardization. USPSTF guideline expansion to age 45 years enlarges the United States addressable cohort.
- Inflammatory Bowel Disease:Crohn's disease and ulcerative colitis surveillance requires interval monitoring for dysplasia detection with chromoendoscopy or cross-sectional alternatives. Academic medical centers specialize in this high-complexity segment.
- Diverticulitis Diagnosis:Acute presentation imaging differentiates uncomplicated from complicated disease course for surgical triage. Emergency department CT utilization dominates this indication.
- Routine Check-ups:Opportunistic screening during unrelated abdominal imaging encounters captures incidental colorectal pathology. United States health system quality metrics increasingly incentivize this capture.
Colorectal cancer screening absorbs the bulk of capital allocation; inflammatory bowel disease applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany and Japan supply imaging systems to United States health networks, while domestic service revenue concentrates in metropolitan hospital corridors with dense Medicare populations.
United States
Hospital networks in Florida, Texas, and Arizona are consolidating CT colonography services into dedicated screening centers. The USPSTF guideline expansion to age 45 years enlarges the addressable screening cohort. The CMS National Coverage Determination removes cost-sharing barriers for Medicare beneficiaries. Greater Houston and Dallas-Fort Worth imaging networks are capturing employer wellness contract volumes through direct-to-consumer channels.
Germany
Fluoroscopy suite manufacturers in Baden-Württemberg and Bavaria export digital subtraction systems to North American acute care settings. The EMA medical device regulation framework governs contrast agent quality standards for barium sulfate exports. The Stuttgart industrial corridor hosts precision engineering clusters supplying X-ray tube components to global OEMs.
Japan
Endoscopic imaging specialists in Tokyo and Osaka prefectures develop optical colonoscopy platforms with integrated therapeutic capabilities. The PMDA governs 510(k)-equivalent device approvals for export markets. The Nagoya medical device cluster concentrates manufacturing of high-resolution CCD sensors for colonoscopic visualization systems.
China
Domestic CT scanner production in Shenzhen and Beijing is displacing imported equipment in tier-two hospital procurement. The NMPA streamlined Class III device registration pathways for locally manufactured imaging systems. The Yangtze River Delta region is expanding fluoroscopy component supply chains for Southeast Asian export markets.
United Kingdom
NHS England bowel cancer screening program procurement is shifting toward CT colonography alternatives in London and Manchester health systems. The MHRA post-Brexit regulatory framework maintains alignment with MDR standards for contrast agent imports. The Cambridge-Oxford corridor hosts AI-assisted polyp detection software development for integration with standard workstations.
Lower GI Series Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with cross-modal imaging portfolios. Tier-one participants command fluoroscopy and CT platform integration, while mid-tier specialists concentrate on contrast agent formulation and disposable accessories. Three archetypes dominate: integrated imaging system OEMs, contrast media chemical manufacturers, and endoscopic device specialists. Strategic moves center on AI software licensing partnerships and service contract bundling rather than hardware price competition.
Among diversified imaging conglomerates, GE Healthcare, Siemens Healthineers, and Fujifilm Holdings Corporation occupy positions spanning fluoroscopy suites, CT platforms, and contrast agent supply. These entities exemplify the integrated-system archetype through combined hardware-software-consumable offerings. Their market presence anchors procurement decisions in United States hospital networks seeking single-vendor standardization. The contrast between their installed base maintenance strategies and emerging AI-native competitors is reshaping competitive positioning.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| Fujifilm Holdings Corporation |
| Medtronic |
| Boston Scientific |
| Hologic |
| Olympus |
| Others |
Supply & Pricing Matrix
EMA medical device regulation compliance gates qualified supply access for barium sulfate contrast agents and fluoroscopy components, restricting premium-tier pricing to manufacturers meeting pharmaceutical-grade purity standards. Buyers in United States hospital networks face tiered cost structures where FDA-cleared imaging systems command substantial premiums over uncertified alternatives, while supply scarcity in European API production tightens margin flexibility across downstream procurement.
Pricing Analysis
Outcome-based pricing anchors procurement decisions, with United States Medicare reimbursement rates for CT colonography screening setting the ceiling for commercial payer negotiations. Price differentiation separates FDA-cleared contrast agents from compounding pharmacy alternatives, while volume scale discounts dominate imaging center purchasing. Cost compression in barium enema systems is intensifying because rural outpatient clinics prioritize capital efficiency over diagnostic throughput. Federally qualified health centers exhibit highest price sensitivity; academic medical centers prioritize therapeutic integration over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with European pharmaceutical-grade barium sulfate production concentrated in Germany, France, and Italy. Active pharmaceutical ingredient manufacturing draws from baryte mining operations in China and India, with purification chemistry resting on German and Swiss specialty chemical houses. Tariff exposure on imported contrast agents creates procurement risk for United States imaging networks. Distribution runs through regional medical device distributors with GPO contract aggregation for hospital system purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with control over AI-assisted polyp detection software emerging as the decisive downstream lever for equipment manufacturers seeking to displace radiologist-dependent service models.
For Market Incumbents: Hedge against AI-native workstation competitors by acquiring computer-aided detection algorithm licenses and embedding them into standard CT colonography platforms. Consolidate service contract bundling across fluoroscopy suite installed bases to raise switching costs for hospital procurement committees evaluating multi-vendor architectures. Defensive patent filings around low-dose acquisition protocols protect margin structures in radiation-sensitive screening segments. For New Entrants and Emerging Players: Rural United States counties with radiologist workforce shortages present the most penetrable buyer archetype for teleradiology-integrated CT colonography services. Employer wellness programs in Texas and Florida metropolitan corridors offer direct contracting pathways bypassing traditional GPO channels. A software-as-a-service polyp detection overlay targeting mid-tier imaging centers provides the lowest capital barrier to market entry. For Investors and Strategic Acquirers: CMS National Coverage Determination expansion for additional screening indications is the leading indicator that reimbursement tailwinds will sustain capital equipment procurement cycles. Five-to-ten year viability favors diversified imaging conglomerates with cross-modal portfolios over pure-play contrast agent manufacturers. Monitor FDA 510(k) clearance velocity for AI-assisted detection algorithms as the signal that radiologist interpretation models face displacement pressure.| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Licensing Partnership | GE Healthcare and Siemens Healthineers embed detection algorithms into standard workstations to reduce radiologist reading time. |
| Hospital System Partnership | Integrated delivery networks in Florida consolidate CT colonography into dedicated screening centers with standardized navigation protocols. |
| Reimbursement Strategy | Private payer coverage mandates in several state insurance markets follow federal Medicare precedent for screening accessibility. |
| CE Marking Pathway | European manufacturers navigate EMA medical device regulation to maintain export access for fluoroscopy component supply. |
| Backward Integration into API Supply | Contrast agent formulators pursue captive production of pharmaceutical-grade barium sulfate to reduce European supplier dependency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across radiology department heads, hospital purchasing committee members, biomedical equipment planners, GPO contracts managers, and contrast agent procurement leads. FDA 510(k) clearance databases, CMS National Coverage Determination records, American College of Radiology practice parameter documentation, and European medical device registration filings supplied validation benchmarks. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Granularity-level modeling captured product type splits at the modality level, end user segmentation across hospital and imaging center archetypes, and application-level demand for screening versus diagnostic indications. Deployment mode differentiation between non-invasive and invasive protocols provided an additional segmentation dimension. CAGRs derived from logistic adoption curves fitted to reimbursement policy inflection points and capital replacement cycle timing. Forecast inputs incorporated USPSTF guideline expansion cohort sizing and Medicare Advantage network penetration assumptions.
Revisions become necessary when AI-assisted polyp detection algorithms achieve regulatory clearance for standalone interpretation, or when barium sulfate API supply disruptions alter contrast agent pricing structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Global Point of Care Ultrasound Market