
 Global Cell Surface Markers Detection Market | 2026-2036
Global Cell Surface Markers Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Surface Markers Detection Market Foresight
Reagent subscription programs is pivoting how vendors monetize cell surface markers detection, shifting capital expenditure into recurring operational budgets. Becton, Dickinson and Company leverages its instrument-installed base to lock in multi-year consumable contracts. Thermo Fisher Scientific Inc. anchors its position through integrated workflow bundles spanning antibodies, cytometers, and informatics. Danaher Corporation differentiates via operational excellence programs that compress turnaround times for contract research customers.
Cell surface markers detection encompasses the identification and quantification of proteins expressed on cellular membranes, typically employing fluorochrome-conjugated antibodies with specificity measured in nanomolar affinity ranges, to characterize cell lineage, activation status, or disease state. The technique serves fundamental roles in hematological malignancy classification, immune monitoring, and stem cell identity verification. Flow cytometry kits command the largest revenue share among product types due to their indispensability in clinical diagnostics laboratories, while mass spectrometry is gaining traction in proteomics-driven drug development applications where multiplexing depth exceeds traditional fluorescence limits. Immunophenotyping remains the dominant application segment, though cancer diagnostics is expanding fastest as CAR-T therapy programs proliferate across biopharmaceutical pipelines.
The FDA regulates cell surface markers detection products as in vitro diagnostics or analyte-specific reagents depending on intended use, while the EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked products entering European laboratories. ISO 13485 certification and GMP compliance for companion diagnostic co-development partnerships are becoming non-negotiable for vendors serving regulated biopharmaceutical end users. Stakeholders must monitor how evolving WHO prequalification pathways for flow-based CD4 testing in resource-limited settings may create parallel product specifications diverging from wealthy-country standards.
Market Dynamics
Companion diagnostic co-development mandates from the FDA and EMA are restructuring vendor-customer relationships in cell surface markers detection, forcing reagent suppliers to embed quality systems earlier in biopharmaceutical pipelines.
Growth Catalysts
- CAR-T therapy pipelines:Biopharmaceutical manufacturers require expanded immunophenotyping panels to characterize patient-derived T-cell populations before infusion. Contract research organizations in the United States, Germany, and Japan are scaling flow cytometry capacity to match.
- FDA companion diagnostic guidance:Evolving evidentiary standards for CDx co-labeling create durable demand for analytically validated antibody clones with locked manufacturing processes.
- Mass cytometry multiplexing:Metal-isotope labeling systems enable 40-plus parameter panels that fluorescence flow cytometry cannot match, attracting proteomics-driven drug discovery programs.
Market Restraints
- Fluorochrome supply concentration:Rare-earth chelates and proprietary organic dyes depend on limited chemical synthesis capacity concentrated in Switzerland and Germany, exposing panel manufacturers to input volatility.
- EMA IVDR clinical evidence requirements:Stricter performance studies and post-market surveillance for CE-marked IVDs extend product launch timelines and inflate regulatory compliance costs.
- Mass spectrometry capital intensity:CyTOF instrumentation demands seven-figure capital commitments and specialized facility infrastructure, restricting adoption to well-capitalized reference laboratories.
Strategic Opportunities
- WHO prequalification pathways:Flow-based CD4 testing programs for resource-limited settings may create parallel product specifications suited to decentralized African and Southeast Asian health systems.
- Single-cell multi-omics convergence:Integration of surface marker detection with transcriptomic readouts opens new service revenue streams for academic core facilities.
- Reagent subscription models:Multi-year consumable contracts anchored to installed instrument bases convert capital expenditure into predictable recurring revenue.
Industry Challenges
- Cytometry specialist talent scarcity:Qualified flow cytometrists capable of panel design, compensation, and quality control are concentrated in Boston, San Francisco, and Basel, constraining laboratory expansion.
- ISO 13485 certification timelines:Biopharmaceutical end users demand quality system documentation that extends supplier onboarding by 12-18 months.
- Legacy LIS integration complexity:Proprietary data formats from instrument manufacturers complicate connectivity with hospital information systems and delay clinical deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Surface Markers Detection Market |
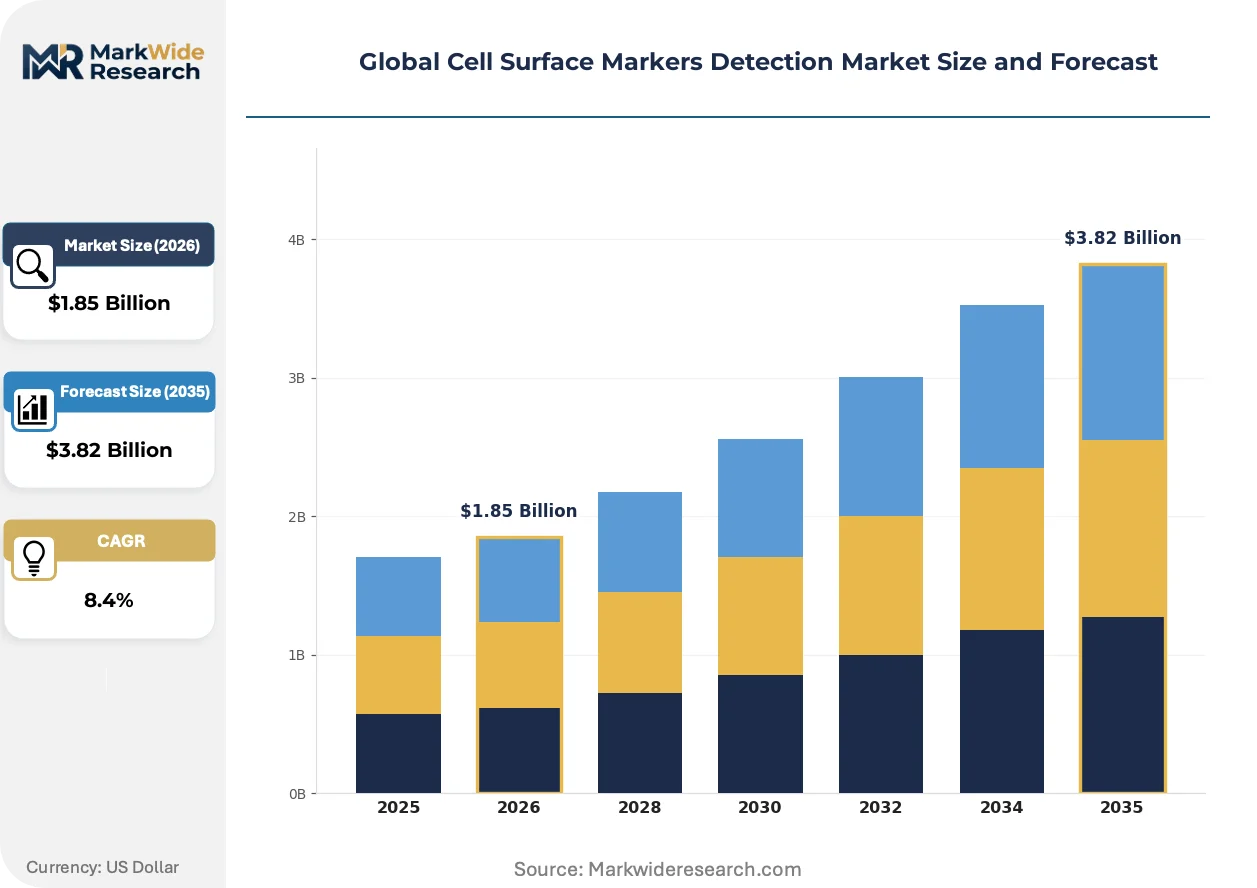
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescent Antibodies, Magnetic Beads, Enzyme-linked Assays, Flow Cytometry Kits, Chemiluminescent Reagents Detection Technology: Flow Cytometry, Immunofluorescence, Western Blotting, Mass Spectrometry, ELISA, Microarrays Application: Immunophenotyping, Cancer Diagnostics, Stem Cell Research, Infectious Disease Testing, Drug Development End User: Research Laboratories, Diagnostic Centers, Biopharmaceutical Companies, Academic Institutes, Contract Research Organizations |
| Companies Covered | Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Abbott Laboratories, Danaher Corporation, Bio-Rad Laboratories Inc., Sysmex Corporation, Nihon Kohden Corporation, F. Hoffmann-La Roche Ltd, Miltenyi Biotec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Surface Markers Detection Market Shifts & Advancements
Spectral unmixing algorithms and machine learning-assisted gating are compressing the expertise barrier for complex panel analysis, enabling broader deployment of high-parameter cytometry outside traditional academic centers.
Spectral flow cytometry is decentralizing analytical capacity by replacing conventional optical filters with continuous wavelength detection, allowing 30-plus color panels on mid-range instruments. Community hospitals and regional reference laboratories in the United States and Germany are adopting these systems to retain oncology specimen volume that previously flowed to major academic centers. The technology is decentralizing diagnostic hierarchy by collapsing the capability gap between tertiary and secondary laboratory settings.
EMA's In Vitro Diagnostic Regulation imposes clinical performance studies and post-market surveillance obligations that exceed predecessor directives, compelling manufacturers to rebuild technical documentation for legacy antibody clones. European laboratories face supply interruptions as vendors rationalize product portfolios to concentrate resources on high-volume markers. CD4 and CD8 enumeration products for HIV monitoring are experiencing the most acute compliance-driven restructuring.
Biopharmaceutical procurement teams are consolidating antibody sourcing through preferred supplier agreements that bundle reagents, instruments, and informatics, displacing spot purchasing from multiple vendors. Contract research organizations in the United States and Japan are centralizing cytometry services under single-source master service agreements to streamline audit burden. This concentration is most visible in CAR-T therapy sponsors seeking integrated quality systems across preclinical and clinical stages.
Global Cell Surface Markers Detection Market Segmentation
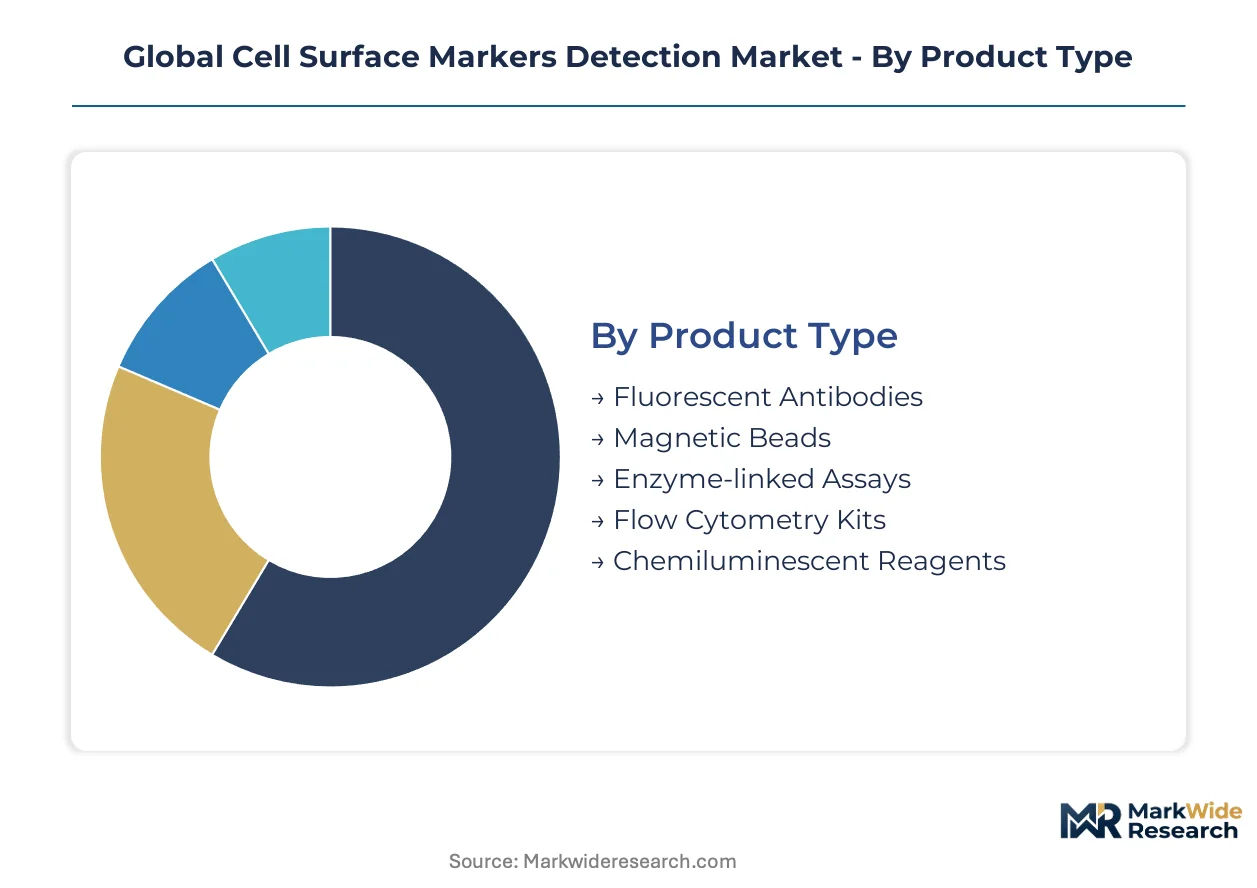
Cell surface markers detection fragments across multiple technical axes that determine procurement patterns, regulatory pathways, and margin structures. Product form factor shapes inventory economics. Detection modality dictates capital intensity and skill requirements. Application focus drives validation standards and customer concentration.
Product Type:
Supply concentration among fluorochrome manufacturers in Switzerland and Germany directly constrains panel economics and availability windows for derivative reagent formats.
- Flow Cytometry Kits:Pre-configured antibody cocktails with standardized fluorochrome ratios eliminate lot-to-lot variability for clinical laboratories. Demand concentrates in United States oncology networks and German reference laboratories where CAR-T therapy monitoring requires locked manufacturing processes.
- Fluorescent Antibodies:Individual conjugates with nanomolar affinity specifications enable custom panel assembly for research applications. Biopharmaceutical companies in Boston and Basel clusters drive procurement for exploratory immunophenotyping before regulatory submission.
- Magnetic Beads:Iron oxide core particles coated with capture antibodies streamline cell isolation workflows.
- Enzyme-linked Assays:Chromogenic substrate systems for bulk screening applications where fluorescence detection is impractical.
- Chemiluminescent Reagents:Acridinium ester and luminol derivatives for high-sensitivity detection in automated analyzers.
Flow Cytometry Kits absorb the bulk of installed capacity; Chemiluminescent Reagents are expanding most quickly through diagnostic platform integration.
Detection Technology:
Cost tier stratification separates capital-intensive mass spectrometry installations from benchtop fluorescence systems accessible to mid-sized laboratories.
- Flow Cytometry:Fluidic systems measuring light scatter and fluorescence emission remain the clinical standard for CD4/CD8 enumeration. United States hospital networks and Japanese academic medical centers anchor instrument placement for HIV monitoring and leukemia classification.
- Mass Spectrometry:Metal-isotope labeling enables 40-plus parameter panels without fluorescence spillover compensation. Proteomics-driven drug discovery programs in Germany and Massachusetts concentrate demand for CyTOF capacity.
- Immunofluorescence:Microscopy-based detection for tissue section analysis and spatial biology applications.
- Western Blotting:Semi-quantitative protein detection for research validation of surface marker expression.
- ELISA:Plate-based colorimetric assays for high-throughput screening in resource-limited settings.
- Microarrays:Parallel detection of hundreds of markers on spotted antibody surfaces.
Flow Cytometry captures the largest installed base; Mass Spectrometry shows the steepest expansion trajectory among capital equipment categories.
Application:
Volume distribution tracks the migration of cell therapy programs from academic origins into regulated biopharmaceutical manufacturing.
- Immunophenotyping:Lineage marker panels defining cell populations by surface protein expression profiles. Diagnostic centers in the United States and Japan process routine specimens for hematological malignancy classification.
- Cancer Diagnostics:Minimal residual disease detection and CAR-T product characterization. Contract research organizations in Germany and Massachusetts scale capacity to match sponsor pipeline expansion.
- Stem Cell Research:Pluripotency and differentiation marker verification for regenerative medicine applications.
- Infectious Disease Testing:CD4 T-cell enumeration for HIV disease staging in WHO prequalification programs.
- Drug Development:Pharmacodynamic biomarker measurement across preclinical and clinical trial phases.
Immunophenotyping maintains the broadest deployment footprint; Cancer Diagnostics is climbing the fastest as cellular therapy approvals accumulate.
End User:
Customer type determines pricing architecture, with biopharmaceutical procurement teams demanding multi-year master service agreements that commoditize spot purchasing.
- Biopharmaceutical Companies:Integrated antibody sourcing spanning discovery through companion diagnostic co-development. Sponsors in the United States and Japan consolidate spend under preferred vendor arrangements with locked quality systems.
- Contract Research Organizations:Centralized cytometry services offering regulatory-compliant data packages for FDA submission. CROs in Germany and Massachusetts compete on turnaround compression and audit readiness.
- Research Laboratories:Academic core facilities with flexible panel design for exploratory studies.
- Diagnostic Centers:High-volume clinical laboratories requiring ISO 13485-certified reagents for IVD use.
- Academic Institutes:Grant-funded investigators prioritizing publication-grade data over regulatory compliance.
Biopharmaceutical Companies command the deepest contract value; Contract Research Organizations are gaining share fastest through sponsor outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of fluorochrome-conjugated antibodies clusters in Switzerland and Germany, while clinical consumption concentrates in the United States, Germany, and Japan where CAR-T therapy programs and reference laboratory networks drive specimen volume.
United States
FDA companion diagnostic guidance and CAR-T therapy pipelines create dual demand for analytically validated antibody clones. The agency's evolving evidentiary standards for CDx co-labeling lock in multi-year procurement contracts. Boston and San Francisco host the densest concentrations of contract research organizations scaling flow cytometry capacity.
Germany
EMA's In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for CE-marked products entering European laboratories. The country's chemical synthesis capacity in Basel-adjacent regions supplies rare-earth chelates and proprietary organic dyes. Reference laboratories in Munich and Heidelberg anchor regional diagnostic hierarchy.
Japan
PMDA oversight of companion diagnostic co-development aligns with METI industrial policy supporting regenerative medicine commercialization. Academic medical centers in Tokyo and Osaka process routine specimens for hematological malignancy classification. Domestic instrument manufacturers face pressure from integrated workflow bundles.
Switzerland
Swissmedic certification requirements for IVD products intersect with the country's dominance in fluorochrome chemical synthesis. Basel and Zurich host quality system documentation capabilities that extend supplier onboarding timelines. The concentration of rare-earth chelate production exposes panel manufacturers to input volatility.
China
NMPA regulatory pathways for in vitro diagnostics are converging with international standards through harmonization initiatives. Yangtze River Delta bioclusters in Shanghai and Suzhou are expanding immunophenotyping capacity for domestic CAR-T programs. WHO prequalification pathways for flow-based CD4 testing create parallel product specifications for resource-limited settings.
Global Cell Surface Markers Detection Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the cell surface markers detection landscape. The market exhibits tiered consolidation with integrated life science conglomerates commanding installed instrument bases while specialized reagent suppliers fill niche panel gaps. Three archetypes dominate: workflow bundlers leveraging cytometer placements to lock in consumable contracts, operational excellence specialists compressing turnaround times for contract research customers, and precision chemistry houses controlling fluorochrome supply. M&A activity concentrates on antibody clone portfolios and informatics capabilities, while geographic expansion targets WHO prequalification pathways in resource-limited settings.
Among integrated conglomerates, Becton Dickinson and Company and Thermo Fisher Scientific Inc. exemplify the workflow bundler archetype through instrument-installed base strategies. Danaher Corporation occupies a position within the operational excellence tier. These three anchors represent distinct competitive vectors: capital deployment against recurring revenue conversion, vertical scope against specialization, and speed-to-result against analytical depth.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Danaher Corporation |
| Bio-Rad Laboratories Inc. |
| Sysmex Corporation |
| Nihon Kohden Corporation |
| F. Hoffmann-La Roche Ltd |
| Miltenyi Biotec |
| Others |
Supply & Pricing Matrix
Rare-earth chelate synthesis costs in Swiss and German chemical facilities cascade through fluorochrome-conjugated antibody pricing tiers, compressing margins for mid-range panel manufacturers while locking premium-tier suppliers into long-term offtake contracts with biopharmaceutical procurement teams.
Pricing Analysis
Margin tightening in standard-grade reagent tiers reflects EMA IVDR compliance investments and locked manufacturing process documentation requirements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated companion diagnostic clones from research-use-only conjugates and bulk unlabeled antibodies. Cost-down pressure on economy-tier fluorescent antibodies accelerates because WHO prequalification programs for CD4 testing demand stripped-down specifications. Contract research organizations exhibit highest price sensitivity; integrated biopharmaceutical sponsors prioritize locked quality systems over unit cost.
Supply Chain Analysis
Fluorochrome chemical synthesis rests on Swiss and German specialty chemical producers, with rare-earth chelate purification concentrated in Basel-adjacent facilities and proprietary organic dye manufacturing anchored in southern Germany. Downstream panel assembly draws from Chinese antibody production bioreactors and Japanese precision fluidic component suppliers. Single-source vulnerability in rare-earth element processing exposes manufacturers to export restriction risk. Distribution runs through authorized distributor networks serving United States hospital networks, German reference laboratories, and Japanese academic medical centers with ISO 13485-certified cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in cell surface markers detection hinges on captive control over fluorochrome supply or locked instrument-installed bases that convert capital expenditure into recurring consumable revenue.
For Market Incumbents: To counter spectral flow cytometry disruption from mid-range instrument manufacturers, deepen backward integration into fluorochrome chemical synthesis through Basel-adjacent facility investments or exclusive rare-earth chelate supply agreements. Prioritize multi-year reagent subscription contracts anchored to installed cytometer bases in United States oncology networks and German CAR-T therapy monitoring programs. For New Entrants and Emerging Players: The price-point gap between premium companion diagnostic-grade panels and economy research-use reagents opens white-space opportunity in ISO 13485-certified mid-tier products for Asian contract research organizations scaling immunophenotyping capacity. Target Yangtze River Delta bioclusters with bundled antibody-informatics offerings that bypass capital-intensive instrument manufacturing. Penetrate through WHO prequalification pathway specialization for decentralized African and Southeast Asian CD4 testing programs. For Investors and Strategic Acquirers: FDA companion diagnostic co-development announcement velocity is the leading indicator that locked manufacturing process documentation capabilities will command acquisition premiums. Long-term viability favors precision chemistry houses with rare-earth chelate expertise or informatics platforms compressing panel analysis expertise barriers. Watch for spectral unmixing algorithm patent filings as inflection signal for machine learning-assisted gating commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA evidentiary standards for CDx co-labeling lock in multi-year antibody procurement contracts with biopharmaceutical sponsors. |
| Fluorochrome Chemical Synthesis Acquisition | Captive rare-earth chelate production in Basel-adjacent facilities insulates panel manufacturers from Swiss supply concentration risk. |
| Spectral Flow Cytometry Platform Launch | Continuous wavelength detection instruments collapse capability gaps between tertiary and secondary United States laboratory settings. |
| WHO Prequalification Pathway Specialization | Parallel product specifications for resource-limited settings open African and Southeast Asian health system procurement channels. |
| Machine Learning-Assisted Gating Development | Algorithmic panel analysis compression reduces cytometry specialist talent scarcity constraints in Boston and San Francisco clusters. |
Research Methodology
Independent corroboration across primary interviews with flow cytometry core facility directors, biopharmaceutical regulatory affairs leads, diagnostic laboratory procurement managers, and fluorochrome chemical synthesis specialists underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA IVDR technical documentation databases, ISO 13485 certification registries, and WHO prequalification assessment reports. Bottom-up instrument placement tracking and top-down reagent revenue estimation triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product form factor, detection modality, application focus, and end-user procurement archetype. CAGRs derive from instrument installed base expansion curves, reagent consumption per test trends, and companion diagnostic co-development pipeline counts. Forecast inputs incorporate CAR-T therapy approval velocity, EMA IVDR compliance timeline slippage, and spectral cytometry adoption curves in United States community hospital networks.
Inputs from biopharmaceutical sponsor pipeline disclosures and contract research organization capacity announcements were available through the study window; gaps in private-company reagent pricing data introduce uncertainty bands around economy-tier market estimates. Forecasts reflect documented assumptions regarding fluorochrome supply stability and regulatory harmonization progress. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market