
 Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market | 2026-2036
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market Insights
The migration from benchtop reference methods to miniaturized optical engines is narrowing the performance gap between central laboratory and bedside testing platforms. Abbott Laboratories leverages its vertically integrated sensor manufacturing to control optical pathway precision. Siemens Healthineers anchors its position through proprietary nephelometry calibration architectures. Danaher Corporation competes across electrochemical and fluorescence detection modalities with modular instrument designs.
Point-of-care diagnostic analyzer accuracy and interference test equipment comprises validated reference materials, synthetic interferent panels, and traceable calibrators used to verify analytical performance under clinically relevant interference conditions such as hemolysis, lipemia, and icterus. These systems ensure that portable analyzers maintain total error budgets within clinician-actionable thresholds before deployment in emergency care centers and mobile clinics. Immunoassay analyzers command the largest revenue share due to the complexity of antibody cross-reactivity validation, while molecular diagnostic systems represent the fastest-growing category as PCR-accurate platforms decentralize into pharmacy and ambulatory settings. Spectrophotometry technology dominates installed base volumes, though fluorescence detection captures premium positioning in oncology identification applications.
FDA 21 CFR Part 820 quality system regulations and CLIA complexity classification standards shape product development roadmaps and commercial access for manufacturers targeting the US market. EMA In Vitro Diagnostic Regulation 2017/746 performance evaluation requirements are accelerating European demand for standardized interference test panels with documented metrological traceability. Stakeholders must monitor evolving harmonization between FDA and EMA post-market performance monitoring frameworks to anticipate validation burden shifts.
Market Dynamics
The transition from centralized laboratory validation to distributed bedside verification protocols is compressing test equipment deployment cycles and forcing manufacturers to miniaturize reference-grade metrology into portable form factors.
Growth Catalysts
- EMA In Vitro Diagnostic Regulation 2017/746:Post-market surveillance mandates for point-of-care devices in Germany, France, and Italy are accelerating procurement of standardized interference test panels with documented metrological traceability.
- Decentralized PCR platforms:Pharmacy and ambulatory settings deploying molecular diagnostic systems require validated synthetic interferent panels for hemolysis, lipemia, and icterus verification.
- CLIA waived complexity test expansion:United States emergency care centers and mobile clinics are driving demand for pre-validated accuracy verification kits that streamline FDA 510(k) clearance pathways.
Market Restraints
- Optical component supply concentration:Precision photodetectors and narrow-band filters for fluorescence detection modalities concentrate among Japanese and German component specialists, creating single-source vulnerability.
- Platinum-group metal volatility:Electrochemical sensor electrodes depend on ruthenium and iridium thin-film deposition, with price swings directly impacting calibrator production economics.
- Metrological traceability bottlenecks:ISO 17511-compliant reference material certification requires 18-24 month validation timelines at national metrology institutes, constraining new product introduction velocity.
Strategic Opportunities
- Home-based chronic disease monitoring:Diabetes and anticoagulation self-testing protocols in the United States are creating demand for consumer-grade accuracy verification consumables with simplified interferent detection.
- AI-assisted calibration architectures:Machine learning algorithms for real-time interference pattern recognition are converging with miniaturized spectrometers to enable predictive quality control in distributed settings.
- Brazil ANVISA harmonization pathway:Emerging alignment between Brazilian in vitro diagnostic regulations and FDA technical standards is opening streamlined market access for pre-validated test equipment originally certified for US deployment.
Industry Challenges
- Multidisciplinary validation engineering:Recruiting personnel fluent in both clinical chemistry and optical system design remains difficult, particularly for fluorescence detection oncology applications requiring antibody cross-reactivity expertise.
- Legacy analyzer integration:Hospital systems with installed bases of 2015-2019 spectrophotometry platforms face firmware incompatibility when connecting to cloud-based interference monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market |
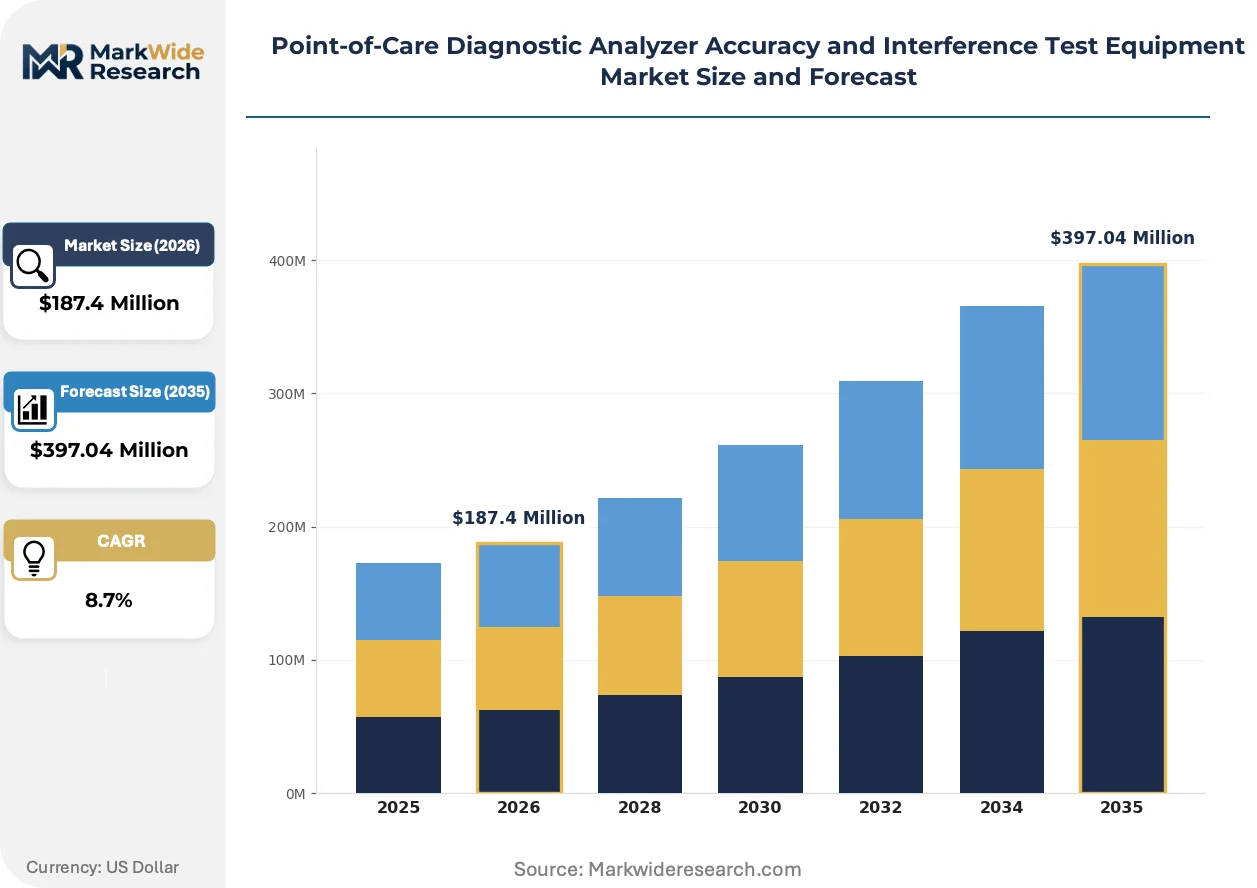
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Chemistry Analyzers, Hematology Analyzers, Immunoassay Analyzers, Molecular Diagnostic Systems Technology: Spectrophotometry, Electrochemical Detection, Fluorescence, Nephelometry Application: Cardiometabolic Screening, Infectious Disease Testing, Oncology Identification, Coagulation Monitoring End User: Diagnostic Laboratories, Research Institutes, Emergency Care Centers, Mobile Clinics |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Siemens Healthineers, Danaher Corporation, QuidelOrtho Corporation, Becton, Dickinson and Company, bioMérieux, Thermo Fisher Scientific, Sysmex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market Trends and Innovations
Digital twin architectures and synthetic biology-derived reference materials are displacing traditional physical calibrator production, while regulatory pressure for real-world performance data is forcing test equipment makers to embed continuous monitoring capabilities.
Cloud-native reference material libraries are virtualizing the distribution of validated interferent spectra and calibration algorithms. Clinical laboratories in the United States and Germany are adopting subscription-based access to centrally maintained synthetic panel databases, eliminating cold-chain logistics for perishable hemolysis and lipemia surrogates. This virtualization is compressing the traditional 6-8 week reference material procurement cycle into same-day digital credentialing.
EU MDR Article 56 performance evaluation requirements are mandating post-market clinical follow-up data for all Class C and D in vitro diagnostic devices. Manufacturers targeting European Union member states must now embed interference monitoring capabilities directly into point-of-care analyzers rather than relying on external validation protocols. Siemens Healthineers and Roche Diagnostics are restructuring their European service contracts to include continuous accuracy verification as a bundled compliance deliverable.
Hospital procurement departments are unbundling accuracy verification services from capital equipment purchases, creating standalone consumables contracts with 3-5 year performance guarantees. Academic medical centers in Massachusetts and California are pioneering outcome-based validation agreements where test equipment vendors bear financial risk for analytical failures detected during regulatory inspections. This reconfiguration is most visible in immunoassay analyzer categories where antibody lot variability creates ongoing interference detection burdens.
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market Segmentation
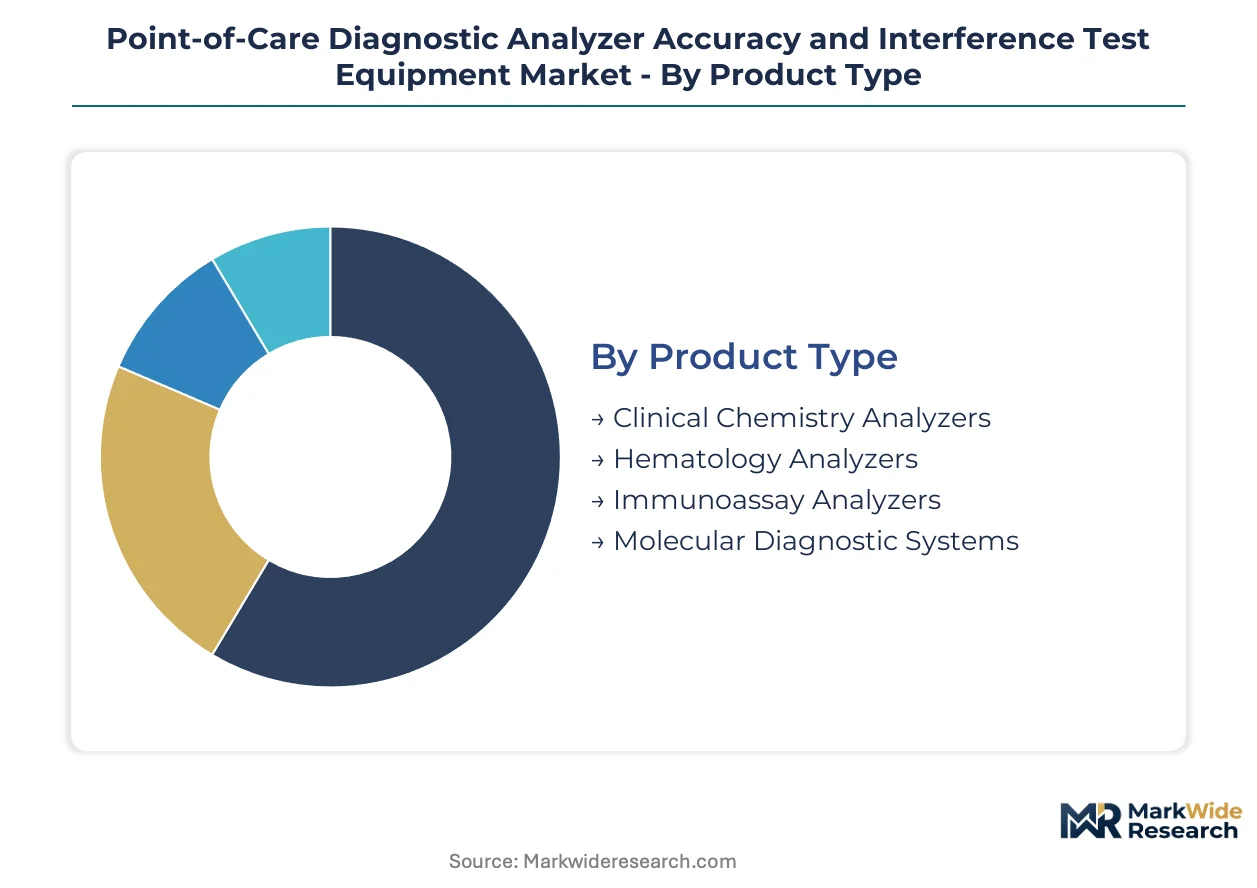
Segmentation in this market reveals how validation protocols diverge across device architectures and care settings. Procurement cycles for immunoassay accuracy kits stretch longer than molecular diagnostic panels due to antibody lot complexity. Understanding these temporal patterns helps manufacturers align production capacity with replacement demand.
Product Type:
Replacement cycles vary sharply across analyzer categories, with consumable-intensive platforms turning over faster than capital-heavy installations.
- Immunoassay Analyzers:These platforms require synthetic interferent panels for antibody cross-reactivity validation under CLIA waived complexity protocols. Emergency care centers in the United States drive recurring demand for pre-validated accuracy kits that streamline FDA 510(k) clearance timelines.
- Molecular Diagnostic Systems:PCR-accurate platforms decentralizing into pharmacy settings demand traceable calibrators for hemolysis, lipemia, and icterus verification. Germany's clinical laboratories are expanding procurement of standardized panels to meet EMA post-market surveillance mandates.
- Clinical Chemistry Analyzers:Benchtop-to-bedside migration narrows performance gaps through miniaturized optical engines.
- Hematology Analyzers:Cell-counting precision requires validated reference materials for hemolysis interference detection.
Immunoassay Analyzers anchor the volume base while Molecular Diagnostic Systems gain share at the steepest rate.
Technology:
Cost tier stratification separates premium fluorescence modalities from commodity spectrophotometry installations.
- Fluorescence:Narrow-band filter precision and photodetector sensitivity enable oncology identification applications with elevated accuracy thresholds. Japanese component specialists concentrate supply of precision optical elements, creating single-source vulnerability for manufacturers.
- Spectrophotometry:Dominant installed base volumes reflect mature calibration architectures and lower per-test economics. Hospital systems with 2015-2019 platform installations face firmware incompatibility when integrating cloud-based interference monitoring.
- Electrochemical Detection:Ruthenium and iridium electrode deposition ties production economics to platinum-group metal price volatility.
- Nephelometry:Proprietary calibration architectures from Siemens Healthineers anchor turbidimetric protein measurement accuracy.
Spectrophotometry commands the widest deployment while Fluorescence captures premium positioning in high-accuracy segments.
Application:
Customer type concentration shapes procurement patterns, with acute care settings demanding faster validation turnaround than chronic monitoring programs.
- Infectious Disease Testing:Decentralized PCR platforms in ambulatory settings require validated synthetic interferent panels for real-time quality control. Cloud-native reference material libraries are compressing procurement cycles from weeks to same-day digital credentialing.
- Oncology Identification:Fluorescence detection modalities with antibody cross-reactivity expertise command specialized validation engineering talent. Academic medical centers in Massachusetts are pioneering outcome-based validation agreements with vendor financial risk-sharing.
- Cardiometabolic Screening:Home-based chronic disease monitoring creates demand for consumer-grade accuracy verification consumables.
- Coagulation Monitoring:Anticoagulation self-testing protocols require simplified interferent detection for patient-operated devices.
Infectious Disease Testing leads deployment velocity while Oncology Identification expands most quickly on precision diagnostic demand.
End User:
Geographic clustering concentrates demand in regulated markets with stringent post-market surveillance frameworks.
- Diagnostic Laboratories:EMA In Vitro Diagnostic Regulation 2017/746 performance evaluation requirements are accelerating European demand for ISO 17511-compliant reference materials with documented metrological traceability. Certification timelines at national metrology institutes constrain new product introduction velocity.
- Emergency Care Centers:CLIA waived complexity test expansion drives demand for pre-validated accuracy verification kits in the United States. FDA 21 CFR Part 820 quality system regulations shape product development roadmaps for manufacturers targeting this channel.
- Research Institutes:AI-assisted calibration architectures for real-time interference pattern recognition converge with miniaturized spectrometers in pilot deployments.
- Mobile Clinics:Brazil ANVISA harmonization with FDA technical standards opens streamlined market access for pre-validated test equipment.
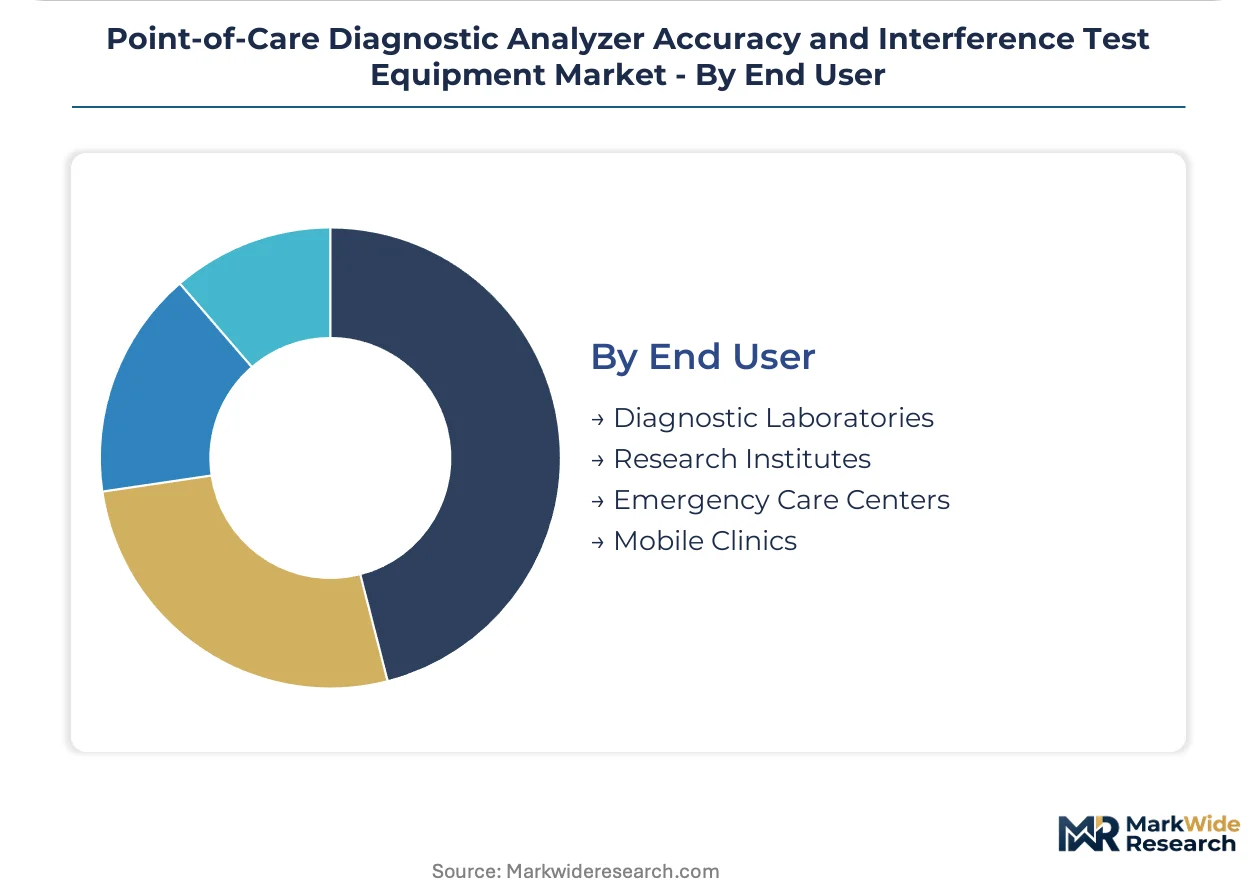
Diagnostic Laboratories anchor the revenue base while Emergency Care Centers climb the fastest on decentralization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clinical laboratories export standardized interference test panels to French and Italian verification facilities under EMA harmonized procurement frameworks. This trade corridor channels ISO 17511-compliant reference materials across Central European metrology networks while US-based manufacturers supply pre-validated accuracy kits to Canadian emergency care centers through FDA-aligned CLIA pathways.
United States
Emergency care centers in Massachusetts and California drive procurement of pre-validated accuracy verification kits for CLIA waived complexity tests. FDA 21 CFR Part 820 quality system regulations shape product development roadmaps for manufacturers targeting decentralized PCR platforms. The Greater Boston academic medical cluster pioneers outcome-based validation agreements with vendor financial risk-sharing for analytical failure detection.
Germany
Clinical laboratories in Bavaria and North Rhine-Westphalia expand procurement of interference test kits to meet EMA In Vitro Diagnostic Regulation 2017/746 post-market surveillance requirements. The country's national pharmaceutical regulator mandates documented metrological traceability for Class C and D device performance evaluations. Siemens Healthineers anchors turbidimetric protein measurement capabilities through proprietary calibration architectures developed in Erlangen.
Japan
Precision photodetector and narrow-band filter specialists concentrate supply for fluorescence detection modalities, creating single-source vulnerability for test equipment manufacturers. METI industrial standards guide optical component quality certification timelines. The Nagoya-Chubu manufacturing corridor houses thin-film deposition facilities for ruthenium and iridium electrochemical sensor electrodes.
Brazil
Mobile clinics in São Paulo and Minas Gerais access streamlined market entry for pre-validated test equipment through ANVISA harmonization with FDA technical standards. The national pharmaceutical regulator's emerging alignment with US clearance pathways reduces duplicate certification burdens for manufacturers. Rio de Janeiro research institutes pilot AI-assisted calibration architectures for real-time interference pattern recognition.
India
Diagnostic laboratories in Maharashtra and Karnataka accelerate adoption of cloud-native reference material libraries to compress procurement cycles from weeks to same-day digital credentialing. CDSCO performance evaluation requirements for imported IVD devices drive demand for ISO-compliant traceability documentation. The Bangalore-Telangana medtech corridor attracts pilot deployments of miniaturized spectrometers with machine learning-enabled quality control.
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. Consolidated diagnostic conglomerates with vertically integrated sensor manufacturing anchor premium positioning through captive optical pathway control. Mid-scale modular instrument designers capture share in electrochemical and fluorescence detection niches. Strategic moves concentrate on backward integration into precision photodetector supply and geographic expansion through regulatory harmonization pathways.
Within the vertically integrated tier, Abbott Laboratories and Siemens Healthineers exemplify archetypes controlling optical pathway precision through in-house manufacturing capabilities. Danaher Corporation occupies a position across multiple detection modalities with modular instrument architectures. These three entities represent contrasting strategic postures: captive component supply versus portfolio diversification versus detection-modality breadth.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Siemens Healthineers |
| Danaher Corporation |
| QuidelOrtho Corporation |
| Becton, Dickinson and Company |
| bioMérieux |
| Thermo Fisher Scientific |
| Sysmex Corporation |
| Others |
Pricing and Supply Chain Analysis
The Nagoya-Chubu manufacturing corridor's freight cost volatility compresses margins for precision photodetector shipments while amplifying price differentiation between fluorescence detection systems and commodity spectrophotometry platforms. Japanese optical component specialists leverage extended logistics timelines to extract premium positioning, forcing test equipment manufacturers to absorb upstream cost pressure or pass differentiation downstream to CLIA-waived complexity test buyers.
Pricing Analysis
Current-generation fluorescence detection platforms command three-tier pricing structure across premium oncology identification systems, standard infectious disease panels, and economy-grade clinical chemistry analyzers. Price differentiation rests on ISO 17511 metrological traceability certification tier and captive optical pathway control, with Japanese component supply concentration intensifying cost compression in mid-tier spectrophotometry. Emergency care centers exhibit highest price sensitivity due to bundled consumables procurement, while academic medical centers tolerate premium positioning for outcome-based validation guarantees.
Supply Chain Analysis
Extended payment terms from Japanese photodetector specialists and German narrow-band filter manufacturers now stretch 90-120 days, straining working capital for modular instrument designers. Geographic supply concentration centers on Japan for precision optical elements, Germany for calibration architectures, and the United States for cloud-native reference material distribution. Ruthenium and iridium electrode deposition draws from South African and Russian platinum-group metal flows, exposing electrochemical sensor production to commodity price volatility. Distribution runs through hospital procurement departments unbundling accuracy verification services from capital equipment purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where cloud-native reference material subscriptions expand faster than hardware replacement cycles, with Massachusetts academic medical centers pioneering continuous accuracy verification as a bundled compliance deliverable.
For Market Incumbents: Entrench proprietary calibration architectures through backward integration into precision photodetector supply, securing captive optical pathway control against modular instrument competitors. Siemens Healthineers exemplifies this posture in turbidimetric protein measurement. Expand ISO 17511-compliant reference material certification capacity at national metrology institutes to constrain new entrant velocity. Defend against cloud-native disruptors by embedding interference monitoring capabilities directly into analyzer firmware rather than external validation protocols. For New Entrants and Emerging Players: Build out AI-assisted calibration architectures for real-time interference pattern recognition, targeting research institutes in Rio de Janeiro and Bangalore-Telangana as pilot deployment sites. Brazil ANVISA harmonization with FDA technical standards creates the most penetrable regulatory pathway for pre-validated test equipment. Pursue home-based chronic disease monitoring segments with consumer-grade accuracy verification consumables, leveraging simplified interferent detection protocols for patient-operated devices. For Investors and Strategic Acquirers: Modular instrument designers with electrochemical and fluorescence detection breadth represent the most defensible acquisition archetype, capturing share across fragmented procurement hierarchies without single-technology concentration. Long-term viability over the projection horizon hinges on regulatory harmonization momentum between FDA and EMA post-market surveillance frameworks. Monitor EMA In Vitro Diagnostic Regulation 2017/746 enforcement intensity in German clinical laboratories as the inflection indicator for standardized interference test panel demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Photodetector Supply | Abbott Laboratories controls optical pathway precision through captive Japanese component manufacturing. |
| Cloud-Native Reference Material Library Deployment | Subscription-based synthetic panel databases eliminate cold-chain logistics for perishable hemolysis surrogates. |
| AI-Assisted Calibration Architecture Development | Machine learning-enabled quality control converges with miniaturized spectrometers in distributed settings. |
| Regulatory Harmonization Pathway Exploitation | ANVISA alignment with FDA technical standards reduces duplicate certification burdens for Brazilian market entry. |
| Outcome-Based Validation Agreement Structuring | Vendor financial risk-sharing for analytical failure detection reconfigures hospital procurement contracts. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, biomedical engineers, hospital purchasing committee members, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews with point-of-care device manufacturers and regulatory affairs specialists combined with secondary validation against FDA 510(k) clearance databases, EMA In Vitro Diagnostic Regulation submission records, hospital procurement databases, and ISO 17511 certification registries. Bottom-up segment sizing across product type, technology, application, and end user triangulated against top-down market boundary checks.
Scenario-bracketing framed analytical outputs across the projection horizon, with sensitivity testing on regulatory enforcement intensity and platinum-group metal price volatility. Segmentation dimensions modeled include detection modality, CLIA complexity classification, and regional regulatory cluster alignment. CAGRs derived from installed base turnover analysis and replacement demand curves, incorporating EMA post-market surveillance mandate implementation timelines and decentralized PCR platform deployment rates as industry-specific forecast inputs.
Practitioners should monitor EMA In Vitro Diagnostic Regulation 2017/746 enforcement patterns, Japanese photodetector supply allocation shifts, and cloud-native reference material adoption velocity for early signals requiring forecast reassessment. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Lower GI Series Market