
 US Medical Thermometer Market | 2026-2036
US Medical Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
US Medical Thermometer Market Intelligence
China is narrowing its cost advantage in infrared sensor manufacturing, prompting domestic producers to emphasize FDA-compliant clinical-grade accuracy. Exergen Corporation leverages proprietary arterial heat balance technology to sustain premium positioning in hospital procurement channels. McKesson Corporation anchors distribution scale across integrated delivery networks, while Cardinal Health competes through formulary breadth and logistics infrastructure.
A medical thermometer measures body temperature through thermal sensing elements—thermistors, thermopiles, or liquid crystals—with clinical units requiring accuracy within ±0.1°C per ASTM E1965 standards for infrared devices and ±0.05°C for digital oral units. These instruments serve diagnostic triage, treatment monitoring, and infectious disease containment across acute and ambulatory settings. Digital thermometers occupy the largest revenue share due to replacement cycles and unit economics, while smart thermometers with Bluetooth connectivity represent the fastest-expanding margin pool as remote patient monitoring platforms integrate continuous temperature streams. Infrared contactless devices command premium placement in fever screening protocols, though pediatric applications still favor tympanic and temporal artery formats for speed and tolerance.
FDA 510(k) premarket notification and ASTM E1965 infrared thermometer standards govern clinical accuracy claims and market access, with OSHA workplace health guidelines additionally driving institutional procurement of non-contact screening devices. HIPAA data handling requirements constrain smart thermometer ecosystem design, forcing cloud architecture choices that burden smaller technology entrants. Stakeholders must weigh sensor supply chain reliability against the pace of software-enabled diagnostic integration.
Market Dynamics
Bluetooth-enabled smart thermometers are compressing replacement cycles while forcing incumbents to rebuild software architectures around HIPAA-compliant data pipelines. This convergence of clinical hardware with remote patient monitoring platforms is redrawing competitive boundaries between device manufacturers and health IT vendors.
Growth Catalysts
- OSHA workplace health guidelines:Institutional procurement of non-contact screening devices is accelerating across manufacturing and logistics facilities seeking fever detection protocols.
- Pediatric home care:Parents are prioritizing tympanic and temporal artery formats for speed and tolerance, expanding the addressable household base beyond acute settings.
- Infrared thermopile sensors:Advances in MEMS fabrication are lowering bill-of-material costs while preserving ASTM E1965 accuracy thresholds.
Market Restraints
- FDA 510(k) clearance timelines:Premarket notification requirements extend product development cycles and freeze capital deployment for smaller technology entrants.
- China sensor supply concentration:Domestic thermopile manufacturing dominance creates single-source vulnerability for US device assemblers.
- Disposable probe cover economics:Recurring consumable costs for tympanic units erode total cost-of-ownership advantages against contactless alternatives.
Strategic Opportunities
- Remote patient monitoring integration:Continuous temperature streaming into Epic and Cerner platforms opens subscription revenue models for device-software bundles.
- Geriatric ambulatory care:Medicare Advantage plans are expanding home-based monitoring benefits, creating pull-through demand for connected devices.
- California and Northeast metropolitan corridors:Dense hospital networks and integrated delivery systems offer concentrated deployment opportunities for clinical-grade units.
Industry Challenges
- HIPAA cloud architecture:Health data handling requirements force expensive infrastructure choices that burden smaller technology entrants against established health IT vendors.
- ASTM E1965 calibration drift:Infrared device accuracy degradation over time requires field recertification protocols that strain service organizations.
- Bluetooth firmware integration:Legacy hospital IT systems demand complex middleware development for seamless device connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Medical Thermometer Market |
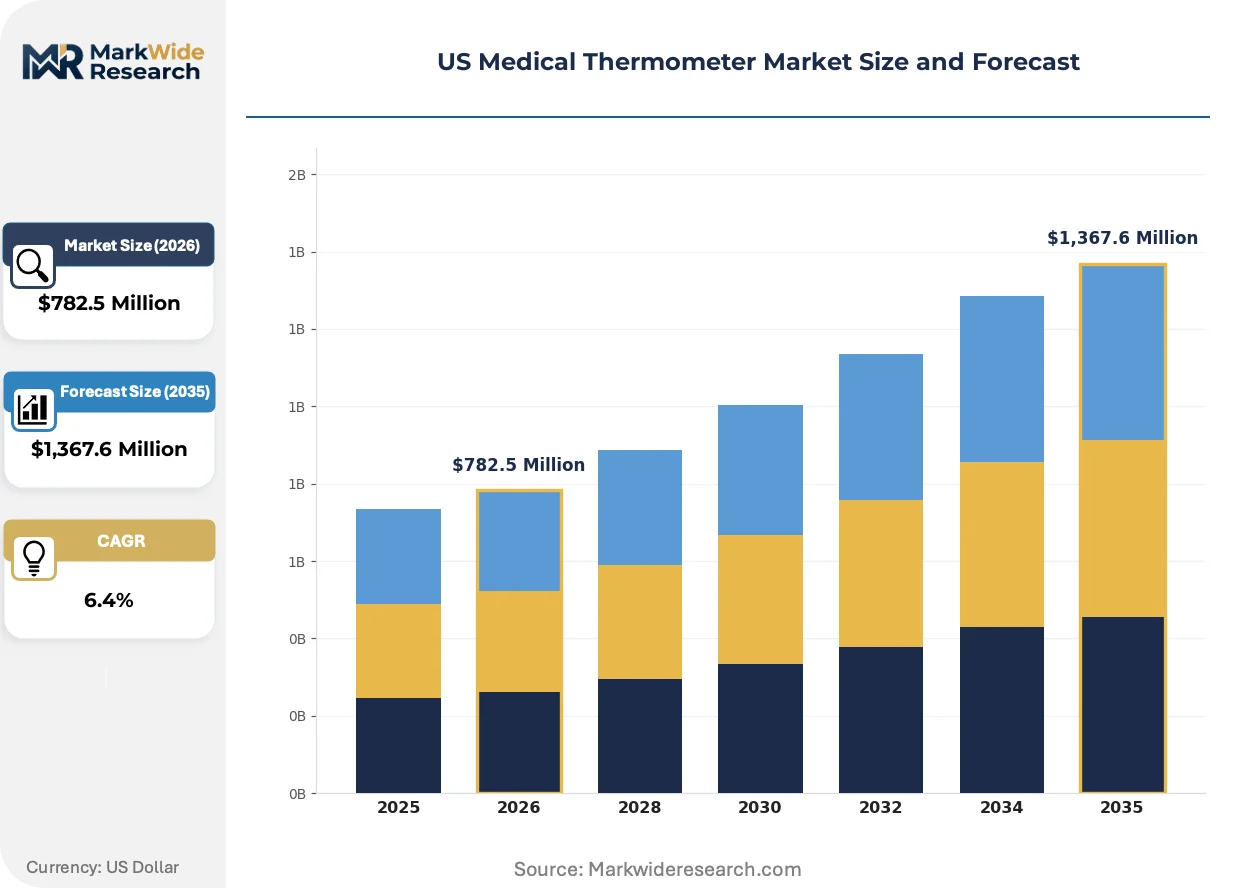
| Market Size in 2026 | $782.5 Million |
| Market Size in 2035 | $1,367.6 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Thermometers, Infrared Thermometers, Mercury Thermometers, Smart Thermometers End User: Hospitals, Clinics, Home Care, Pharmacies Technology: Contactless, Clinical, Wireless, Bluetooth Application: General Diagnosis, Fever Monitoring, Pediatric Care, Geriatric Care |
| Companies Covered | American Diagnostic Corporation, McKesson Corporation, Exergen Corporation, Baxter, Medline Industries, Inc., Cardinal Health, Microlife Corporation, Innovo Medical, 3M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Medical Thermometer Market Strategic Shifts & Innovations
Sensor miniaturization and wireless protocol standardization are enabling thermometer form factors that disappear into daily hygiene routines. This hardware commoditization is pushing margin capture toward data analytics and platform subscription layers.
Multi-spectral infrared arrays are collapsing the distinction between consumer wellness and clinical diagnostic tiers. Hospital systems are piloting these sensors for ward-based continuous monitoring, eliminating spot-check nursing workflows. The technology is collapsing price premiums previously commanded by wired bedside units.
FDA guidance on software-as-a-medical-device is tightening validation requirements for algorithmic fever detection. Developers must submit clinical performance data for machine learning models embedded in smart thermometers. Pediatric applications face heightened scrutiny given the narrow physiological range distinguishing normal from elevated temperatures in infants.
Direct-to-consumer channels are displacing traditional durable medical equipment distribution for home-use segments. Amazon and CVS Health are capturing thermometer volume through same-day fulfillment and pharmacy integration. This shift is most visible in suburban markets where convenience overrides brand loyalty established through pediatrician office sampling programs.
US Medical Thermometer Market Segmentation
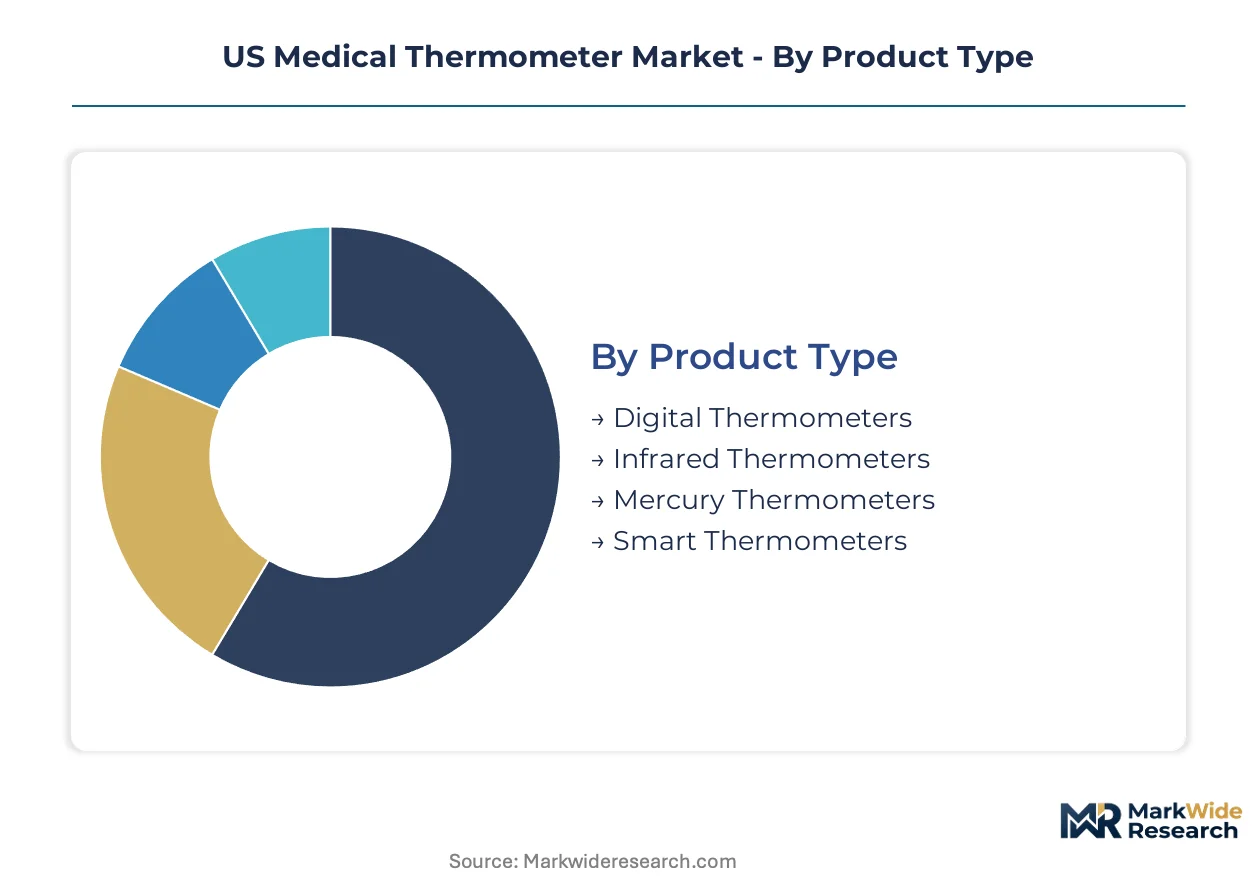
Thermometer segmentation reveals distinct procurement patterns across acute care, ambulatory, and consumer channels. Product architecture, connectivity protocols, and end-use setting determine pricing power and replacement velocity for manufacturers competing across FDA-regulated clinical tiers and direct-to-consumer wellness segments.
Product Type:
Cost tier differentiation separates commodity replacement units from premium clinical-grade systems with validated accuracy protocols.
- Digital Thermometers:Thermistor-based oral, rectal, and axillary units deliver ±0.05°C precision per ASTM standards. Hospital procurement in the Northeast and California integrated delivery networks sustains volume demand despite compressed margins from Asian contract manufacturers.
- Infrared Thermometers:Thermopile sensors enable non-contact temporal artery and tympanic measurements with ±0.1°C clinical accuracy. OSHA workplace screening mandates in manufacturing corridors accelerate institutional deployment beyond traditional healthcare settings.
- Mercury Thermometers:Glass column devices with mercury filling face EPA disposal regulations and state-level bans. Residual demand persists in rural clinics with limited capital budgets and legacy calibration infrastructure.
- Smart Thermometers:Bluetooth-enabled units stream continuous temperature data to HIPAA-compliant cloud architectures. Pediatric home care adoption in suburban markets drives subscription revenue models.
Digital thermometers command the established base. The steepest expansion runs through smart thermometers.
End User:
Customer type determines regulatory burden, purchasing authority, and total cost-of-ownership calculations across the value chain.
- Hospitals:Acute care systems require FDA 510(k)-cleared devices with documented clinical accuracy for diagnostic triage. Epic and Cerner EHR integration specifications drive procurement decisions in metropolitan hospital networks.
- Clinics:Federally qualified health centers and urgent care chains prioritize speed and throughput over premium feature sets. Tympanic units with disposable probe covers dominate workflow design.
- Home Care:Medicare Advantage home monitoring benefits create pull-through demand for connected devices. Parents prioritize temporal artery formats for pediatric tolerance and speed.
- Pharmacies:CVS Health and Walgreens capture impulse purchase volume through pharmacy counter placement and same-day fulfillment integration.
Hospitals anchor procurement scale. Home care is climbing the fastest as reimbursement shifts toward ambulatory monitoring.
Technology:
Connectivity architecture and measurement modality determine software integration requirements and margin capture potential.
- Contactless:Infrared thermopile arrays enable fever screening without physical patient contact. Manufacturing facility adoption across Texas and Ohio logistics hubs extends addressable demand beyond healthcare.
- Clinical:Wired bedside units with continuous monitoring capability face displacement from wireless multi-spectral arrays piloted in ward-based deployments.
- Wireless:Proprietary RF protocols enable hospital-grade continuous monitoring without Bluetooth interference in dense device environments.
- Bluetooth:Standardized Low Energy stacks force middleware development for legacy hospital IT systems. Firmware integration complexity burdens smaller technology entrants against established health IT vendors.
Clinical technology holds the installed base. Bluetooth is gaining share fastest through consumer wellness and remote patient monitoring convergence.
Application:
Use case specificity dictates accuracy requirements, form factor constraints, and reimbursement eligibility across patient populations.
- General Diagnosis:Adult outpatient temperature screening supports infectious disease triage protocols. Emergency departments in urban medical centers drive replacement cycles for high-throughput units.
- Fever Monitoring:Continuous temperature tracking for immunocompromised and post-surgical patients enables early sepsis detection. FDA software-as-a-medical-device guidance tightens validation for algorithmic alert systems.
- Pediatric Care:Infants present narrow physiological ranges distinguishing normal from elevated temperatures. Temporal artery and tympanic formats prioritize speed and tolerance over rectal measurement accuracy.
- Geriatric Care:Medicare Advantage plans expanding home-based monitoring benefits create dedicated demand for connected devices with medication adherence integration.
General diagnosis captures routine volume. Fever monitoring shows the steepest trajectory through remote patient monitoring platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the US regulatory environment, shaping product development timelines and market access across all domestic sub-regions. Hospital procurement networks and integrated delivery systems concentrate demand in metropolitan corridors with dense healthcare infrastructure.
Northeast Corridor
Massachusetts General Hospital and New York-Presbyterian anchor acute care procurement for clinical-grade infrared devices. OSHA workplace health guidelines drive institutional screening deployments across Connecticut and New Jersey manufacturing facilities. Boston's medical device cluster sustains innovation pipelines for arterial heat balance technology.
California
Kaiser Permanente and Sutter Health integrated networks standardize procurement specifications for Bluetooth-enabled smart thermometers. FDA software-as-a-medical-device guidance tightens validation requirements for algorithmic fever detection systems. San Diego's wireless health technology corridor attracts remote patient monitoring platform developers.
Texas
Houston Methodist and Baylor Scott & White drive replacement cycles for high-throughput emergency department units. OSHA mandates accelerate non-contact screening adoption across Dallas-Fort Worth logistics hubs. Austin's health technology startup ecosystem incubates HIPAA-compliant cloud architecture ventures.
Midwest
Cleveland Clinic and Mayo Clinic procurement standards influence formulary decisions across Ohio and Minnesota hospital networks. Medicare Advantage home monitoring benefits create pull-through demand in Michigan's aging industrial cities. Chicago's medical distribution infrastructure anchors McKesson and Cardinal Health logistics operations.
Southeast
Emory Healthcare and Duke Health systems prioritize pediatric temporal artery formats for speed and tolerance. Florida's retirement corridor generates concentrated geriatric ambulatory care demand for connected devices. Atlanta's CDC proximity shapes infectious disease containment procurement protocols.
US Medical Thermometer Market Key Industry Players
Capability concentration sits with specialized clinical-grade manufacturers; scale advantage sits with diversified health distribution conglomerates. The market structure tiers into three distinct archetypes: proprietary technology specialists, integrated distribution platforms, and contract manufacturing assemblers. Dominant competitive moves include strategic partnerships with EHR vendors and backward integration into sensor supply chains.
Among technology specialists, Exergen Corporation exemplifies proprietary positioning through arterial heat balance intellectual property. McKesson Corporation and Cardinal Health occupy scale-driven distribution roles across integrated delivery networks. American Diagnostic Corporation represents mid-tier clinical-grade manufacturing with hospital procurement channel access.
| Leading Market Players |
|---|
| American Diagnostic Corporation |
| McKesson Corporation |
| Exergen Corporation |
| Baxter |
| Medline Industries, Inc. |
| Cardinal Health |
| Microlife Corporation |
| Innovo Medical |
| 3M |
| Others |
Cost & Logistics Intelligence
Single-source thermopile sensor dependency on Chinese MEMS fabrication determines both three-tier pricing spreads across clinical-grade, institutional, and consumer tiers and the fragmented assembly structure of US device manufacturers. FDA 510(k) clearance timelines compound this structural vulnerability by freezing capital deployment and compressing margin recovery windows for premium positioning.
Pricing Analysis
Domestic clinical-grade units command 40-60% premiums over Asian contract-manufactured equivalents in Northeast hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated infrared systems with ASTM E1965 certification from unvalidated wellness devices and commodity digital replacements. Cost compression in the standard tier is intensifying because Chinese sensor producers are narrowing cost advantages while preserving accuracy thresholds. Federally qualified health centers exhibit highest price sensitivity; integrated delivery networks with formulary standardization programs demonstrate lowest.
Supply Chain Analysis
Thermopile sensor wafers and Bluetooth Low Energy chipsets feed from concentrated manufacturing bases in China, Taiwan, and South Korea. US device assemblers draw from these upstream sources for thermal sensing elements, lithium coin cells, and medical-grade plastic housings. Single-source vulnerability in Chinese MEMS fabrication creates tariff exposure and geopolitical disruption risk. Distribution runs through McKesson and Cardinal Health integrated delivery networks for institutional channels, while Amazon and CVS Health capture direct-to-consumer volume through same-day fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Medical Thermometer Market functions as a defensive-moat story anchored in FDA regulatory entrenchment, where 510(k) clearance pathways create switching costs that freeze out unvalidated competitors and protect incumbent pricing power.
For Market Incumbents: Pre-empt sensor supply disruption by securing captive thermopile sourcing through backward integration or long-term offtake agreements with Taiwanese MEMS foundries. Accelerate software-as-a-medical-device FDA submissions for algorithmic fever detection to lock out health IT vendors encroaching on remote patient monitoring integration. Hospital procurement committee consolidation represents the critical threat vector; defend through exclusive EHR integration partnerships with Epic and Cerner. For New Entrants and Emerging Players: Establish a beachhead in pediatric home care subscriptions, where temporal artery format tolerance advantages and Medicare Advantage reimbursement expansion create white-space opportunity. Target geriatric ambulatory monitoring through pharmacy channel partnerships with Walgreens and CVS Health, bypassing hospital procurement gatekeepers. Direct-to-consumer wellness positioning with HIPAA-compliant cloud architecture offers the most penetrable go-to-market angle against entrenched clinical-grade incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors proprietary technology specialists with FDA-cleared arterial heat balance IP over distribution-scale conglomerates. Long-term viability over the next decade hinges on software-enabled diagnostic integration and remote patient monitoring platform convergence. Acquisition target archetype: mid-tier clinical-grade manufacturers with hospital procurement channel access and underexploited Bluetooth firmware development capabilities. Watch FDA software-as-a-medical-device enforcement intensity as the inflection signal for margin compression in algorithmic fever detection segments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Shortens time-to-revenue for infrared clinical-grade accuracy claims against ASTM E1965 standards. |
| Hospital System Partnership | Locks in formulary placement with Kaiser Permanente and Sutter Health integrated networks. |
| Software Companion Development | Enables Epic and Cerner EHR integration for continuous temperature streaming subscription models. |
| Backward Integration into Sensors | Reduces single-source vulnerability to Chinese thermopile manufacturing concentration. |
| Reimbursement Strategy | Captures Medicare Advantage home monitoring benefit expansion for connected device pull-through. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, hospital procurement contract filings, and ASTM E1965 calibration records. Clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided operational perspective on institutional procurement workflows. Bottom-up unit shipment estimates triangulate against top-down revenue validation from distributor financial disclosures and customs import records for thermopile sensor components.
Forecast inputs span product type segmentation across digital, infrared, and smart thermometer categories; end-user channels from acute care through home care; and technology architectures including Bluetooth, wireless proprietary RF, and contactless infrared arrays. CAGRs derive from installed base replacement cycle analysis and remote patient monitoring platform adoption curves across the projection horizon. Modeling incorporates OSHA workplace health guideline enforcement trajectories and Medicare Advantage home monitoring benefit expansion patterns as demand-side drivers.
Stress conditions across Chinese sensor supply disruption scenarios, FDA software-as-a-medical-device enforcement intensity, and Bluetooth firmware integration complexity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement policy stability and MEMS fabrication cost trajectories. Cross-checking against hospital capital expenditure surveys and GPO contract renewal rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Auto Chemistry Analyzers Market