
 Personal-Use Facial and Skin Therapy Devices Market | 2026-2036
Personal-Use Facial and Skin Therapy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Personal-Use Facial and Skin Therapy Devices Market Outlook
The EU Green Deal is shifting demand toward energy-efficient, repairable personal-use facial devices across European markets. Koninklijke Philips N.V. leverages its clinical heritage to bridge professional credibility with home-use accessibility. YA-MAN Ltd. anchors its competitive position through radiofrequency specialization in the Japanese and broader Asian markets. Beurer GmbH competes on manufacturing scale and German engineering standards that appeal to safety-conscious European consumers.
Personal-use facial and skin therapy devices encompass handheld or wearable instruments engineered for non-invasive dermatological treatment, typically operating at wavelengths between 400-700 nanometers for LED therapy or frequencies below 1 MHz for ultrasound modalities, designed to deliver cosmetic outcomes previously restricted to clinical settings. LED mask and ultrasonic cleanser categories command the largest installed base among home users, while radiofrequency and electroporation technologies capture disproportionate margin pools due to higher price positioning and perceived efficacy in anti-aging applications. The anti-aging application segment sustains premium pricing power, whereas acne treatment represents the fastest-growing entry point for first-time buyers transitioning from topical regimens to device-based routines.
The FDA regulates these devices as Class I or II medical devices depending on intended claims, while the EU MDR and CE marking requirements impose stricter clinical evidence standards for products marketed with therapeutic outcomes. Japan's PMDA maintains parallel oversight for radiofrequency and laser-emitting devices, creating a fragmented compliance landscape that favors multinationals with dedicated regulatory affairs capacity. Stakeholders must monitor evolving classification boundaries between cosmetic and medical claims, as regulator reinterpretation could force reformulation of marketing strategies or trigger additional clinical study obligations.
Market Dynamics
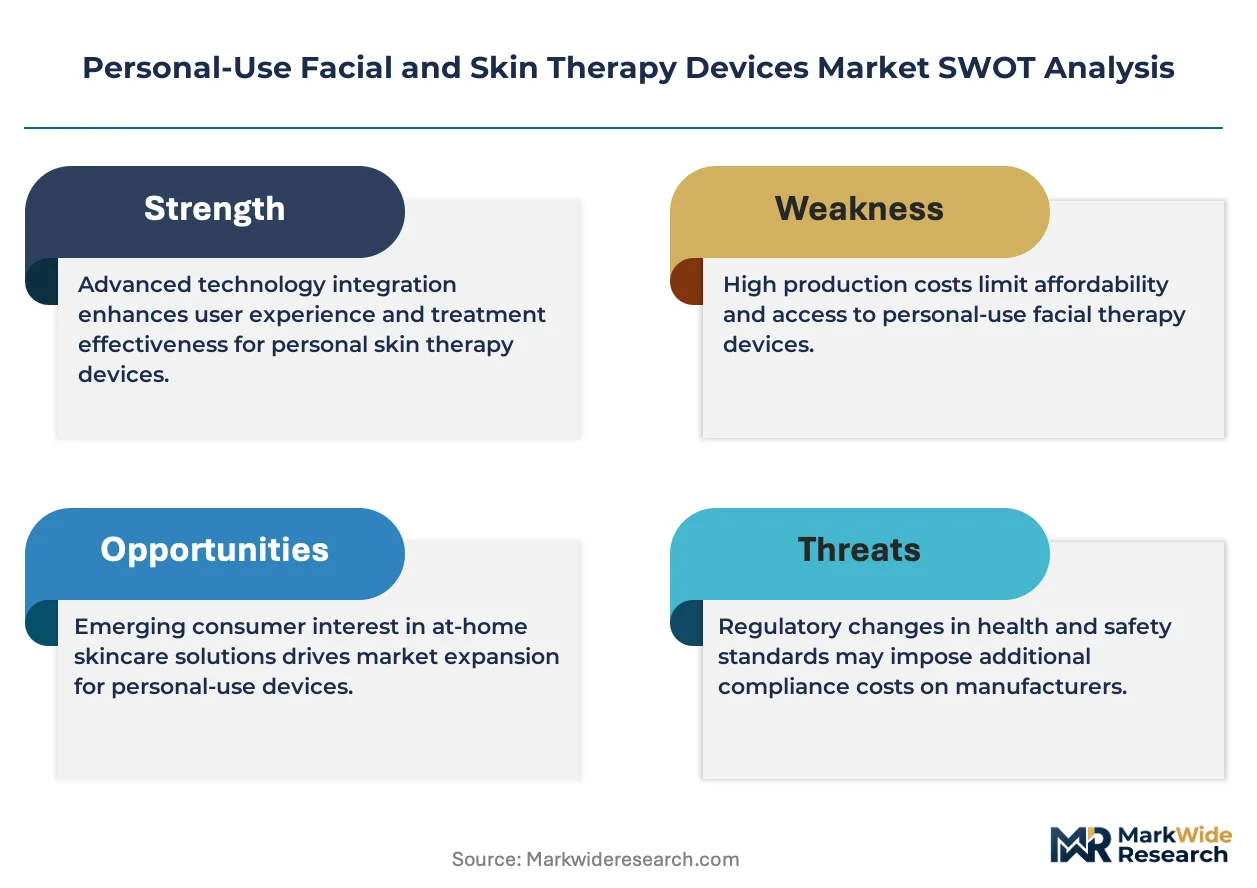
Clinical-grade miniaturization is compressing the performance gap between professional dermatological equipment and home-use alternatives, forcing incumbent manufacturers to defend premium positioning through proprietary wavelength patents and dermatologist endorsement networks.
Growth Catalysts
- EU Green Deal electronics mandates:Repairability requirements and recyclable material quotas are accelerating design refresh cycles across European manufacturers, creating upgrade demand among sustainability-conscious consumers.
- Radiofrequency wavelength optimization:Precision-tuned RF emitters delivering controlled dermal heating at 1-3 MHz frequencies are expanding treatable skin types and reducing adverse event rates in home settings.
- United States:Direct-to-consumer dermatologist endorsement channels are collapsing traditional clinic-mediated purchase pathways, shortening decision cycles for first-time device buyers.
Market Restraints
- Gallium arsenide LED chip supply:Concentrated sourcing from East Asian foundries exposes manufacturers to input cost volatility and geopolitical supply interruptions for high-intensity red and near-infrared emitters.
- FDA Class II reclassification risk:Therapeutic outcome claims trigger medical device evidentiary standards that extend time-to-market by 18-24 months and require clinical trial investment beyond cosmetic-grade budgets.
- Professional clinic service bundling:Dermatology practices are counter-positioning through subscription-based in-office treatment packages that undercut home device value propositions for severe acne and deep wrinkle indications.
Strategic Opportunities
- India:Underpenetrated premium beauty device markets present first-mover advantage for brands establishing BIS-certified manufacturing partnerships and localized clinical validation protocols.
- Electroporation-LED convergence:Combined transdermal delivery and photobiomodulation platforms are opening professional-grade serum infusion applications previously restricted to med-spa environments.
- Social commerce livestreaming:Real-time demonstration formats on platforms targeting beauty enthusiasts are compressing customer acquisition costs and enabling direct manufacturer-consumer relationships outside traditional retail markup structures.
Industry Challenges
- Biomedical photonics engineering talent:Scarcity of professionals combining optical physics expertise with dermatological safety assessment is constraining R&D velocity for wavelength optimization and thermal control algorithms.
- MDR clinical evidence compilation:EU medical device regulation technical documentation requirements for RF and laser-emitting products demand substantial post-market surveillance infrastructure that mid-tier manufacturers struggle to operationalize.
- Multi-jurisdiction labeling harmonization:Divergent cosmetic versus medical classification thresholds across FDA, PMDA, and EU MDR frameworks complicate global product portfolio architecture and marketing claim standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal-Use Facial and Skin Therapy Devices Market |
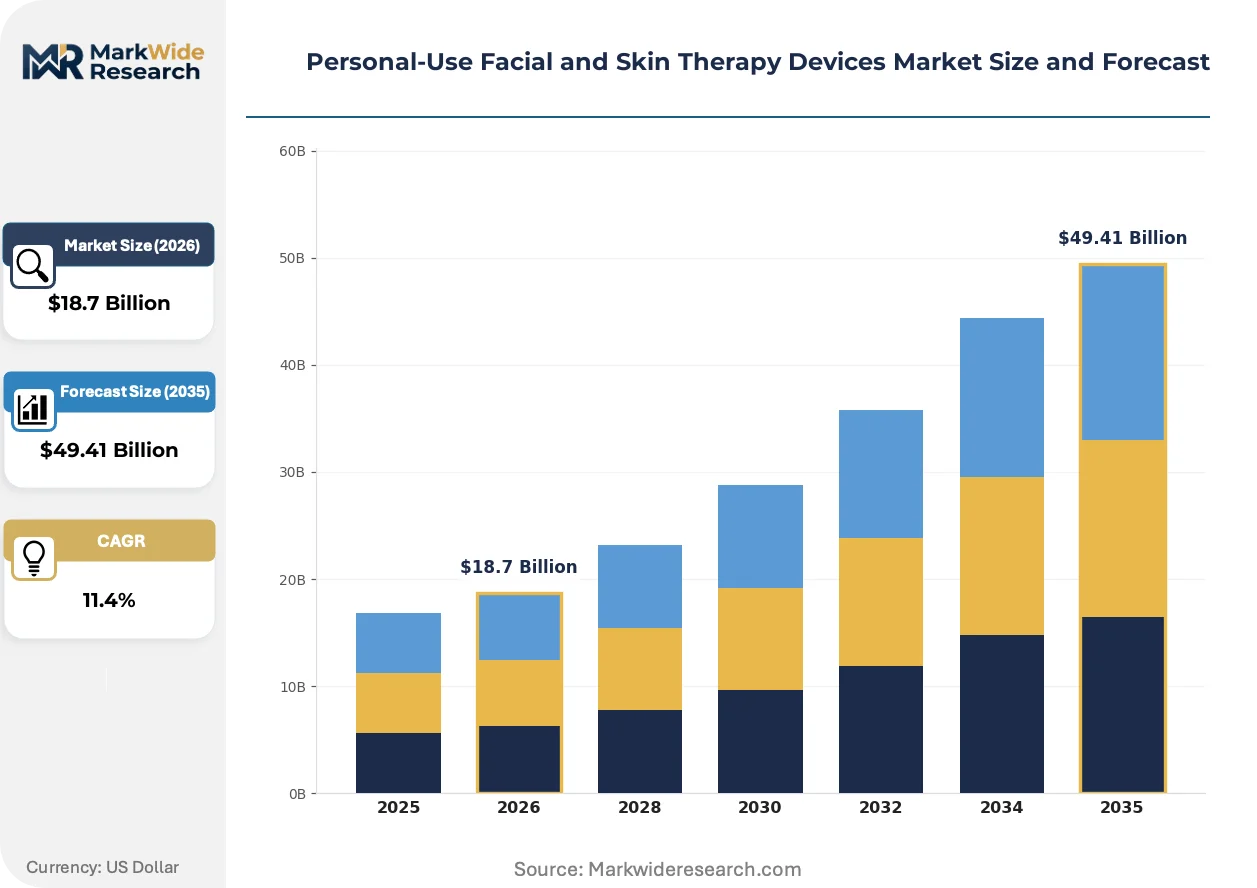
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: LED Mask, Ultrasonic Cleanser, Microdermabrasion Machine, Galvanic Device Application: Anti-Aging, Acne Treatment, Skin Hydration, Brightening Technology: Radiofrequency, Light Therapy, Ultrasound, Electroporation End User: Home Users, Beauty Enthusiasts, Skincare Professionals, Wellness Centers |
| Companies Covered | Conair Corporation, NuFACE, Panasonic Corporation, Beurer GmbH, FOREO, Koninklijke Philips N.V., YA-MAN Ltd., Silk’n, L’Oréal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal-Use Facial and Skin Therapy Devices Market Strategic Shifts
Wavelength-specific treatment protocols and connected device ecosystems are redefining consumer expectations for measurable outcomes and personalized regimen management in at-home dermatological care.
Microcurrent waveform technology is modularizing across price tiers through standardized circuit board architectures and open-source frequency programming interfaces. Budget-conscious entrants in Southeast Asian markets are adopting these reference designs to launch sub-premium alternatives within 8-12 month development cycles. This standardization is compressing proprietary hardware margins and shifting competitive differentiation toward software-guided treatment protocols and companion application ecosystems.
EU MDR clinical evidence requirements for therapeutic claims are tightening substantiation standards for radiofrequency and laser-emitting devices marketed with collagen remodeling outcomes. Manufacturers must now compile post-market surveillance data and periodic safety update reports that mirror pharmaceutical-grade vigilance systems. Anti-aging device portfolios face the steepest compliance burden, with several brands narrowing claims to cosmetic-only positioning to avoid medical device classification timelines.
Beauty enthusiasts are consolidating purchase decisions around dermatologist-validated efficacy data rather than influencer endorsement or brand heritage. This verification-driven preference is elevating clinical study investment as a competitive prerequisite and compressing marketing budgets for awareness-heavy, evidence-light positioning strategies. The United States exhibits the most pronounced shift, with direct-to-consumer brands publishing peer-reviewed outcomes to capture premium price positioning.
Personal-Use Facial and Skin Therapy Devices Market Segmentation
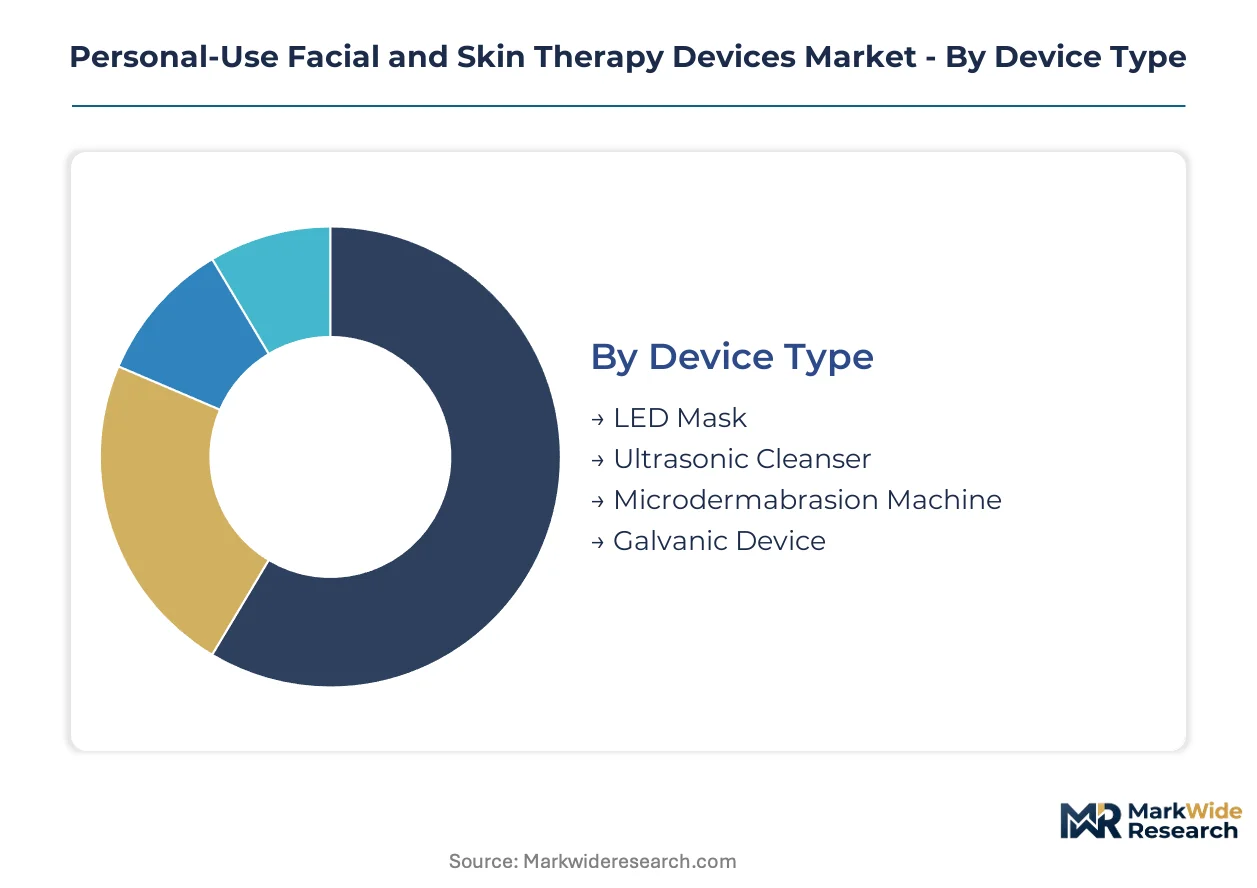
Device architecture and treatment modality fragmentation creates distinct competitive arenas within personal-use facial therapy. Each segmentation dimension reveals divergent margin structures, regulatory exposure, and customer acquisition economics that reshape portfolio prioritization for manufacturers.
Device Type:
Standardization dominates at mass-market price points while customization concentrates in dermatologist-validated premium tiers.
- LED Mask:Wearable arrays emitting 400-700 nanometer wavelengths for photobiomodulation, with red and near-infrared configurations commanding premium positioning. Demand clusters among United States beauty enthusiasts seeking clinical-grade outcomes without clinic visits, driven by direct-to-consumer endorsement networks collapsing traditional retail pathways.
- Ultrasonic Cleanser:Handheld devices operating below 1 MHz frequencies for cavitation-based pore cleansing and serum penetration. Adoption accelerates in European markets where EU Green Deal repairability mandates accelerate replacement cycles among sustainability-conscious consumers.
- Microdermabrasion Machine:Mechanical exfoliation systems for at-home resurfacing protocols.
- Galvanic Device:Low-current iontophoresis instruments for active ingredient delivery enhancement.
Leading the category by volume: LED Mask. Growing fastest: Ultrasonic Cleanser.
Application:
Margin capture inverses with addressable market breadth across cosmetic versus therapeutic positioning.
- Anti-Aging:Collagen stimulation and wrinkle reduction protocols sustaining premium pricing power through perceived efficacy in dermal remodeling. United States consumers demonstrate strongest willingness-to-pay for radiofrequency and LED combinations targeting fine lines, though FDA Class II reclassification risk looms for therapeutic claims.
- Acne Treatment:Blue light phototherapy and ultrasonic extraction routines representing the fastest-growing entry point for first-time device buyers transitioning from topical regimens. Demand concentrates among younger demographics in direct-to-consumer channels bypassing dermatologist gatekeeping.
- Skin Hydration:Electroporation and ultrasound-assisted moisture retention applications.
- Brightening:Pigmentation modulation and tone-evening protocols using specific wavelength targeting.
Highest margin capture: Anti-Aging. Steepest expansion trajectory: Acne Treatment.
Technology:
Patent density and component sourcing complexity stratify competitive moats across modalities.
- Radiofrequency:Precision-tuned 1-3 MHz emitters delivering controlled dermal heating for collagen contraction, with wavelength optimization expanding treatable skin types. Japanese and broader Asian markets anchor specialist positioning through YA-MAN Ltd. heritage, while EU MDR clinical evidence requirements tighten substantiation standards for therapeutic claims.
- Light Therapy:LED and laser-based photobiomodulation with gallium arsenide chip supply concentration exposing manufacturers to East Asian foundry volatility.
- Ultrasound:Sub-1 MHz mechanical wave systems for cleansing and penetration enhancement.
- Electroporation:Transdermal delivery platforms converging with LED for professional-grade serum infusion.
Most defensible IP position: Radiofrequency. Convergence opportunity: Electroporation.
End User:
Channel economics and purchase authority diverge sharply between self-directed and professionally mediated acquisition.
- Home Users:Self-directed consumers seeking clinic-equivalent outcomes through direct-to-consumer channels, with United States demand concentrating around dermatologist-endorsed brands. Social commerce livestreaming compresses customer acquisition costs outside traditional retail markup structures.
- Beauty Enthusiasts:Early-adopter segment validating efficacy data over influencer endorsement, elevating clinical study investment as competitive prerequisite.
- Skincare Professionals:Aesthetician and cosmetologist channels for client home-use recommendations.
- Wellness Centers:Spa and holistic health facilities bundling devices with service protocols.
Volume concentration: Home Users. Fastest channel shift: Beauty Enthusiasts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while consumption tilts toward North American and European households seeking clinic-grade outcomes. The United States absorbs disproportionate premium volumes through direct-to-consumer channels, whereas European markets respond to sustainability mandates with accelerated replacement cycles.
United States
Dermatologist-endorsed direct-to-consumer brands capture premium positioning among beauty enthusiasts seeking clinical-grade outcomes without clinic visits. FDA Class I and II medical device classifications govern LED and radiofrequency products marketed with therapeutic claims. California's Silicon Valley and Los Angeles metro areas host concentrated brand headquarters and influencer marketing ecosystems that compress customer acquisition cycles.
Germany
EU Green Deal repairability mandates accelerate design refresh cycles among sustainability-conscious consumers prioritizing durable electronics. CE marking under EU MDR imposes stricter clinical evidence standards for products with therapeutic outcome claims. Bavaria and Baden-Württemberg anchor manufacturing operations where German engineering standards appeal to safety-conscious European buyers.
Japan
Radiofrequency specialization heritage in the Japanese market sustains premium positioning for precision-tuned dermal heating devices. PMDA oversight for RF and laser-emitting devices creates parallel compliance requirements that favor established multinationals with dedicated regulatory affairs capacity. Tokyo-Osaka corridor concentrates R&D facilities and specialist retail distribution for advanced home-use modalities.
China
Domestic brands leverage gallium arsenide LED chip supply proximity and rapid prototyping capabilities to compress development cycles for mass-market alternatives. NMPA medical device registration requirements tighten for products crossing into therapeutic claim territory. Shenzhen and Dongguan manufacturing clusters supply component ecosystems and contract assembly for global brand portfolios.
India
Underpenetrated premium beauty device markets present first-mover advantage for brands establishing localized clinical validation protocols. BIS certification requirements for electronics imports create entry barriers that favor partnerships with domestic manufacturing facilities. Maharashtra and Karnataka concentrate urban demand in Mumbai and Bangalore metros where direct-to-consumer penetration remains nascent.
Personal-Use Facial and Skin Therapy Devices Market Competitive Environment
The competitive structure tilts toward diversified healthcare conglomerates with clinical credibility and specialized RF engineering houses with wavelength optimization expertise. Consolidation pressure intensifies as clinical-grade miniaturization compresses performance gaps between professional and home-use equipment. Three archetypes dominate: dermatologist-endorsed direct-to-consumer brands, precision RF specialists with Japanese heritage, and diversified electronics manufacturers leveraging scale. Dominant competitive moves include dermatologist endorsement network construction and proprietary wavelength patent accumulation.
Within the diversified healthcare conglomerate tier, Koninklijke Philips N.V. exemplifies clinical heritage translation into home-use accessibility, while Panasonic Corporation occupies a position bridging consumer electronics scale with dermatological device credibility. Among precision RF specialists, YA-MAN Ltd. anchors Japanese market positioning through controlled dermal heating expertise. Beurer GmbH represents German engineering standards that appeal to safety-conscious European consumers seeking MDR-compliant manufacturing.
| Leading Market Players |
|---|
| Conair Corporation |
| NuFACE |
| Panasonic Corporation |
| Beurer GmbH |
| FOREO |
| Koninklijke Philips N.V. |
| YA-MAN Ltd. |
| Silk'n |
| L'Oréal Group |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up dermatology device specialists anchor pricing discipline through captive gallium arsenide LED sourcing and exclusive wavelength patent portfolios, while family-owned German engineering houses defend premium positioning via vertical integration into precision RF component manufacturing.
Pricing Analysis
Margin tightening in mass-market tiers reflects gallium arsenide chip cost volatility from East Asian foundry concentration. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared therapeutic devices from cosmetic-grade alternatives, with dermatologist endorsement commanding brand premiums in United States direct-to-consumer channels. Cost-down pressure on ultrasonic cleansers accelerates because Southeast Asian contract manufacturers replicate microcurrent reference designs. Home users in acne treatment segments exhibit highest price sensitivity, whereas anti-aging radiofrequency buyers demonstrate lowest elasticity.
Supply Chain Analysis
Gallium arsenide LED chip supply rests on Taiwanese and Chinese specialty semiconductor foundries with secondary Japanese precision optics sourcing. Critical component dependencies span RF emitter modules, biocompatible silicone mask substrates, and rechargeable lithium-polymer cells. Single-source vulnerability concentrates in high-intensity red and near-infrared emitter arrays. Distribution runs through direct-to-consumer brand websites, dermatologist endorsement networks, and social commerce livestreaming platforms bypassing traditional retail markup structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum intensifies as manufacturers pursue backward control over gallium arsenide LED supply and forward integration into companion serum formulations, compressing margin capture for non-integrated assemblers.
For Market Incumbents: Anticipate FDA Class II reclassification risk for collagen remodeling claims by narrowing therapeutic positioning or accelerating clinical evidence compilation. Defend wavelength patent moats through litigation against Southeast Asian reference design adopters. Secure exclusive gallium arsenide supply agreements with Taiwanese foundries before capacity allocation tightens.
For New Entrants and Emerging Players: Enter via BIS-certified manufacturing partnerships in Maharashtra and Karnataka to capture underpenetrated Indian premium beauty device demand. Target acne treatment segments where younger demographics bypass dermatologist gatekeeping through social commerce channels. Launch electroporation-LED convergence platforms previously restricted to med-spa environments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor precision RF specialists with Japanese PMDA compliance infrastructure and stranded clinical study assets from MDR-triggered claim narrowing. Watch EU MDR periodic safety update report obligations as inflection indicator for mid-tier manufacturer distress. Long-term viability concentrates in platforms combining hardware miniaturization with software-guided protocol ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Supply | Captive gallium arsenide sourcing insulates margin from East Asian foundry volatility and geopolitical interruption. |
| EU MDR Clinical Evidence Pathway | CE marking under medical device regulation substantiates therapeutic claims that cosmetic-grade competitors cannot match. |
| Social Commerce Livestreaming Launch | Real-time demonstration formats on TikTok Shop and Instagram compress customer acquisition costs outside traditional retail structures. |
| Dermatologist Endorsement Network Construction | Peer-reviewed outcome publication elevates brand credibility among verification-driven United States beauty enthusiasts. |
| Electroporation-LED Convergence Platform | Combined transdermal delivery and photobiomodulation opens professional-grade serum infusion applications for home use. |
Study Parameters
FDA 510(k) filings, EU MDR technical documentation databases, and PMDA medical device registration records formed the secondary backbone, supplemented by customs trade data for gallium arsenide LED chip flows. Primary interviews with biomedical photonics engineers, dermatology clinic procurement managers, direct-to-consumer brand marketing directors, and GPO contracts administrators validated demand assumptions. Bottom-up and top-down triangulation reconciled device shipment estimates with channel inventory checks.
Bottom-up modeling aggregated segment-level volume across LED mask, ultrasonic cleanser, radiofrequency, and electroporation device types, with top-down cross-checks against aggregate beauty device spending patterns. CAGRs derived from fitted growth curves across the analysis window incorporated pricing trajectory assumptions for premium versus mass-market tiers. Forecast inputs included EU Green Deal repairability mandate compliance costs and FDA reclassification probability assessments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA Class II reclassification acceleration or gallium arsenide supply disruption scenarios. Forecasts reflect documented assumptions about regulatory interpretation stability and dermatologist endorsement network durability. A small set of named triggers—PMDA guidance revision, MDR clinical evidence deadline enforcement, and social commerce platform policy shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Global IVF Devices Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Self-Injections Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Global Gamma Probe Device Market
Medical Devices
Asia-Pacific Breast Biopsy Market
Medical Devices
Next Generation Nebulizers Market
Medical Devices
Spectacle Lens Market
Medical Devices
France Ultrasound Devices Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Australia Clear Aligner Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Antimicrobial Coated Medical Devices Market