
 Minimally Invasive Deformity Correction System Market | 2026-2036
Minimally Invasive Deformity Correction System Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Deformity Correction System Market Foresight
China is tilting toward domestic production of minimally invasive deformity correction systems, with state-backed medical device zones in Suzhou and Shenzhen expanding cleanroom capacity for precision implant manufacturing. Medtronic leverages its spine robotics platform to sustain leadership in navigated deformity procedures across Asian markets. Stryker anchors its position through integrated imaging-to-implant workflows that reduce operative time in complex spinal reconstructions.
A minimally invasive deformity correction system comprises percutaneous rod constructs, low-profile plates, or external fixators delivered through small incisions under fluoroscopic or navigational guidance, typically utilizing titanium or cobalt-chrome alloys with modular connection geometries to achieve mechanical stability while preserving soft tissue envelope. These systems enable gradual or acute correction of angular, rotational, or length deformities in the spine and long bones with reduced blood loss and faster mobilization compared to open approaches. Rod systems dominate current revenue owing to their established biomechanical track record in adolescent idiopathic scoliosis, while robotics and navigation technologies are capturing disproportionate R&D investment as hospitals seek to reduce radiation exposure and improve screw placement accuracy. Hybrid systems that combine internal fixation with external adjustability are emerging as a margin-rich niche for complex limb reconstruction cases requiring postoperative fine-tuning.
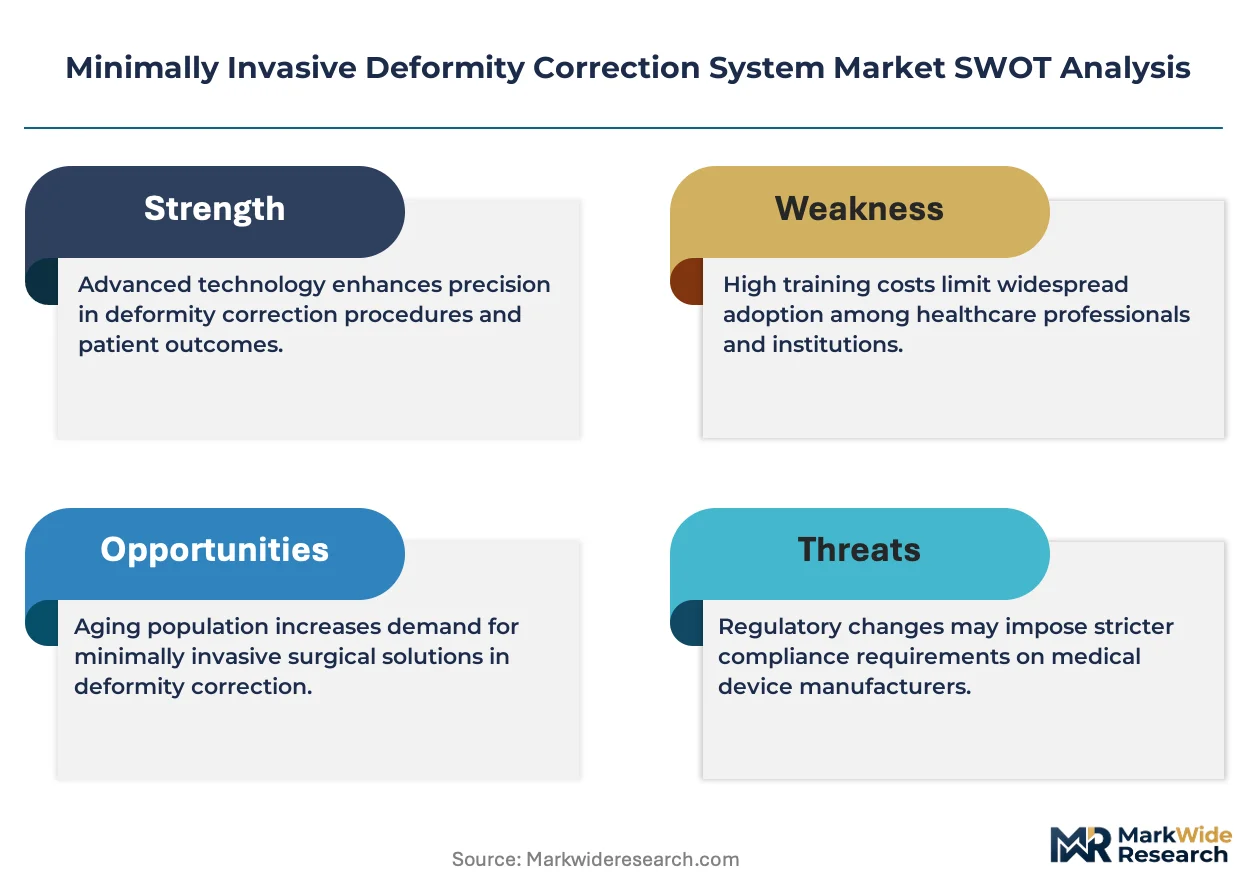
FDA 510(k) pathways and the EU Medical Device Regulation shape product development timelines, with the latter imposing stricter clinical evidence requirements for implantable devices that have redirected some manufacturers toward prioritized US launches. China's NMPA innovation approval channel offers accelerated review for domestically developed surgical robots, creating divergent market access strategies across regulatory jurisdictions. Stakeholders must monitor reimbursement decisions for computer-assisted surgery codes, as these will determine whether capital-intensive robotics investments translate into sustainable procedure economics for hospital buyers.
Market Dynamics
Robotics and navigation platforms are compressing operative workflows while elevating capital requirements, forcing hospital systems to consolidate purchasing power and restructure orthopedic service lines around high-throughput deformity correction centers.
Growth Catalysts
- FDA 510(k) Pathway Compression:Streamlined clearance timelines for computer-assisted surgical devices accelerate commercialization of next-generation navigation platforms. Device developers redirect engineering resources toward iterative software upgrades rather than lengthy premarket approval cycles.
- German Orthopedic Center Consolidation:Specialized hospitals in Bavaria and Baden-Württemberg integrate robotics into deformity correction workflows, creating reference sites that drive procurement standardization across Central European markets.
- Titanium Alloy Advances:Low-profile rod constructs with modular connection geometries enable percutaneous delivery while maintaining biomechanical stability. Surgeons report reduced blood loss and faster mobilization in adolescent idiopiopathic scoliosis cases.
Market Restraints
- EU Medical Device Regulation Friction:Stricter clinical evidence requirements for implantable devices extend development timelines and redirect some manufacturers toward prioritized US launches. Small-cap developers face disproportionate compliance burdens.
- Cobalt-Chrome Supply Concentration:Processing capacity for high-grade alloys concentrates in a limited number of metallurgical facilities. Input cost volatility ripples through implant manufacturing cost structures.
- Open Procedure Substitution:Conventional spinal fusion techniques retain preference in complex revision cases where tissue envelope preservation is secondary to structural rigidity. Hybrid external fixation systems face adoption headwinds in mature markets.
Strategic Opportunities
- China NMPA Innovation Channel:Accelerated review for domestically developed surgical robots creates divergent market access strategies. Suzhou and Shenzhen medical device zones expand cleanroom capacity for precision implant manufacturing.
- Hybrid System Convergence:Platforms combining internal fixation with external adjustability address complex limb reconstruction requiring postoperative fine-tuning. These configurations command premium positioning in pediatric and trauma applications.
- Computer-Assisted Surgery Reimbursement:Emerging procedural codes for navigated deformity correction in North American markets determine whether capital-intensive robotics investments translate into sustainable hospital economics. Payer decisions will shape procurement velocity.
Industry Challenges
- Fluoroscopy-to-Navigation Skill Migration:Surgeon training programs struggle to produce sufficient operators proficient in both percutaneous techniques and robotic platform management. Academic medical centers bear primary responsibility for fellowship pipeline development.
- Capital Equipment Integration Complexity:Hospitals deploying spine robotics must reconcile imaging-to-implant workflows with existing surgical suites. Facility retrofit costs and OR scheduling disruptions strain implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Deformity Correction System Market |
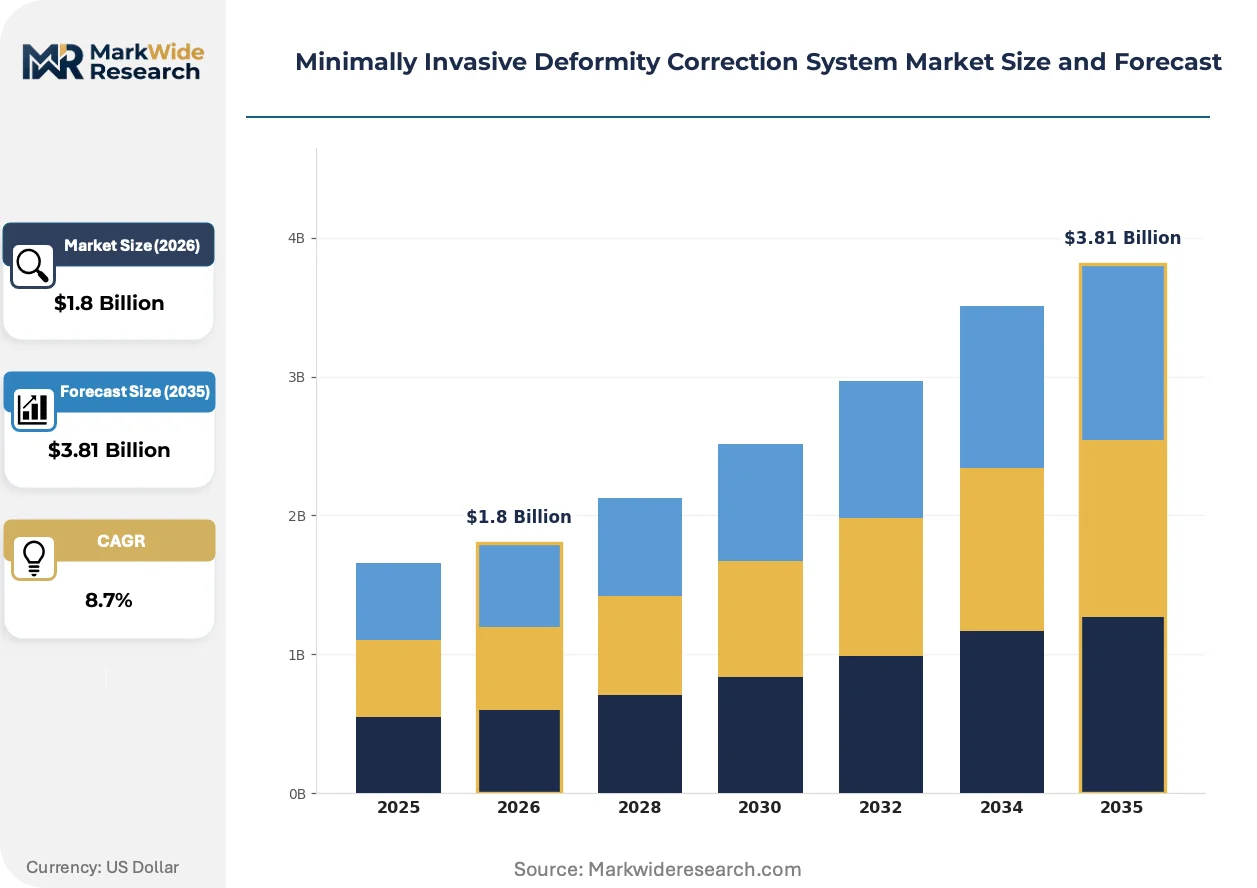
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod System, Plate System, Hybrid System, Fixator System Technology: Computer-Assisted Surgery, Robotics, Navigation, Imaging Procedure Type: Scoliosis Correction, Limb Lengthening, Angular Deformity Correction, Fusion End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Rehabilitation Facilities |
| Companies Covered | Medtronic, DePuy Synthes, Stryker, Globus Medical, Zimmer Biomet, SI-BONE, NuVasive, Boston Scientific, Aesculap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Deformity Correction System Market Shifts & Advancements
Navigation-assisted delivery systems are reconfiguring operative workflows while regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments product development roadmaps. Hospital procurement patterns increasingly favor integrated platform vendors over component suppliers.
Fluoroscopic guidance is migrating from standard-of-care status to adjunctive verification in deformity correction procedures. Academic medical centers in Germany and the United States lead adoption of optical tracking and intraoperative CT navigation. This technology is migrating from high-volume scoliosis centers toward community hospital systems seeking credential differentiation in competitive metropolitan markets.
EU Medical Device Regulation imposes post-market surveillance obligations that extend clinical evidence requirements for implantable spinal systems. Manufacturers must maintain updated technical documentation and periodic safety reporting across CE-marked portfolios. Small-to-mid tier developers face resource allocation pressures that favor partnership with larger platform holders over independent regulatory submissions.
Hospital procurement committees now bundle imaging capital, navigation software licenses, and implant supply agreements into multi-year contracts. Integrated vendors displace standalone component suppliers in competitive tenders. This concentration is most visible in North American health system consolidations where standardized protocols across regional networks override individual surgeon preferences.
Minimally Invasive Deformity Correction System Market Segmentation
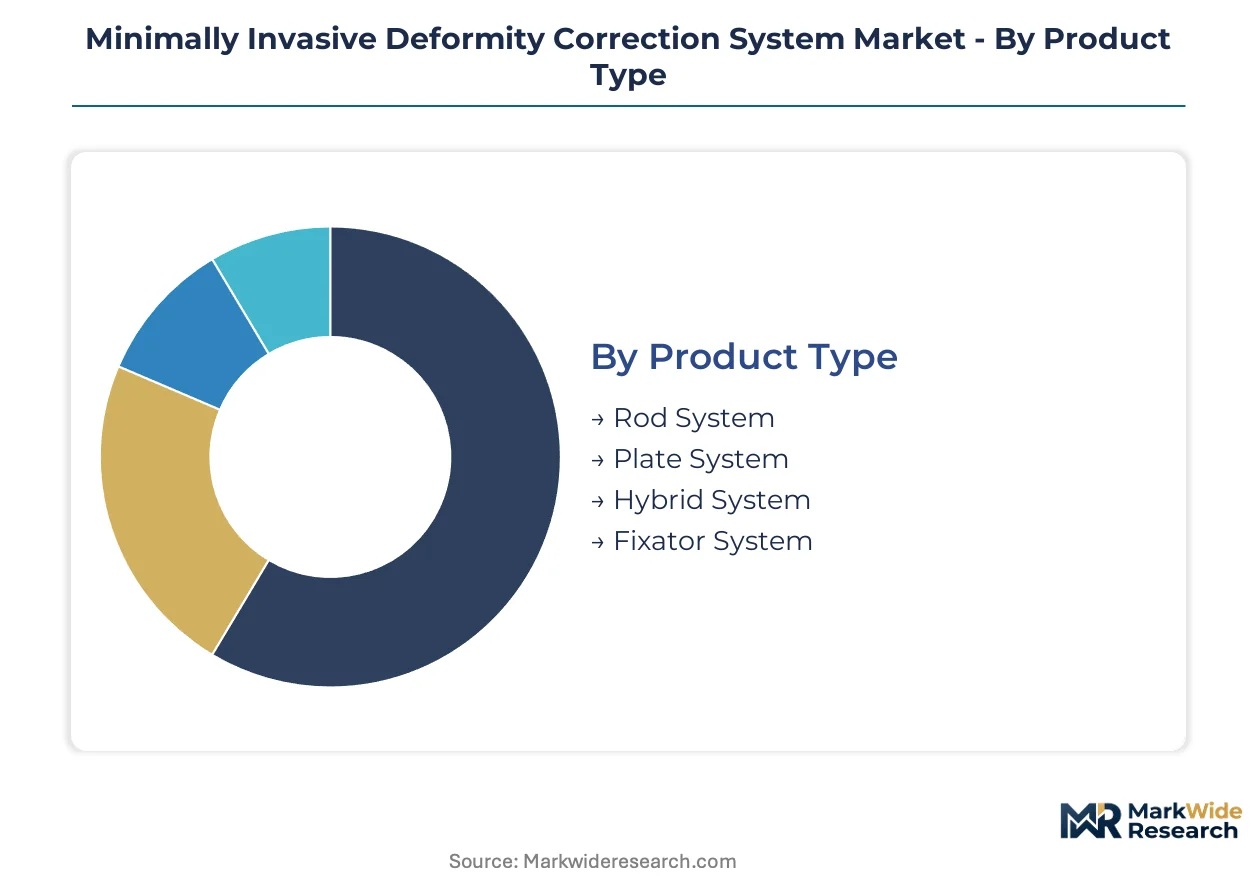
Segmentation in the minimally invasive deformity correction system market reveals distinct procurement patterns across hardware configurations, technological sophistication, and care delivery settings. Each dimension carries implications for capital intensity, reimbursement pathways, and surgeon training requirements.
Product Type:
Mature rod constructs anchor current revenue streams while hybrid configurations emerge as the margin-rich frontier for complex reconstruction cases.
- Rod System:Percutaneous titanium or cobalt-chrome rod constructs with modular connection geometries deliver biomechanical stability through small incisions. Demand concentrates in North American academic medical centers performing adolescent idiopathic scoliosis corrections, where established clinical protocols and surgeon familiarity sustain procurement velocity despite premium pricing.
- Hybrid System:Platforms combining internal fixation with external adjustability enable postoperative fine-tuning without revision surgery. German orthopedic centers in Bavaria and Baden-Württemberg drive adoption for pediatric limb reconstruction requiring gradual correction protocols.
- Plate System:Low-profile plates address angular deformities in long bones with reduced soft tissue disruption compared to conventional open plating.
- Fixator System:External fixators retain niche positioning for trauma cases requiring staged reconstruction or limb salvage procedures.
Rod systems handle the majority of throughput; hybrid systems are gaining share fastest as surgeons seek intraoperative flexibility.
Technology:
Cost tier stratification separates capital-intensive robotics from software-enabled navigation and conventional imaging modalities.
- Computer-Assisted Surgery:Software platforms integrating preoperative planning with intraoperative guidance reduce radiation exposure and improve screw placement accuracy. Hospital systems in the United States prioritize these systems for credential differentiation in competitive metropolitan markets.
- Robotics:Active and semi-active robotic platforms execute predetermined trajectories with submillimeter precision. China's NMPA innovation approval channel accelerates domestic development, with Suzhou and Shenzhen medical device zones expanding cleanroom capacity for precision manufacturing.
- Navigation:Optical tracking and electromagnetic navigation systems provide real-time instrument localization without robotic actuation.
- Imaging:Intraoperative fluoroscopy and cone-beam CT remain standard-of-care verification tools across community hospital settings.
Navigation technology commands the largest installed base; robotics is expanding most quickly as health systems consolidate purchasing power around integrated platforms.
Procedure Type:
Application complexity ranges from standardized scoliosis protocols to highly individualized limb reconstruction workflows.
- Scoliosis Correction:Posterior spinal fusion with percutaneous rod placement addresses adolescent idiopathic and adult degenerative curves. United States hospitals report reduced blood loss and faster mobilization compared to open approaches, supporting favorable reimbursement economics.
- Limb Lengthening:Gradual distraction osteogenesis via internal or external fixation systems corrects length discrepancies and deformities. Specialized centers in Germany integrate robotics to improve precision in complex femoral and tibial reconstructions.
- Angular Deformity Correction:Acute or gradual correction of varus, valgus, or rotational deformities in long bones.
- Fusion:Minimally invasive interbody and posterolateral fusion procedures for degenerative spinal conditions.
Scoliosis correction generates the highest procedure volume; limb lengthening shows the steepest expansion trajectory as techniques diffuse from academic centers to regional hospitals.
End User:
Customer type determines capital availability, case mix complexity, and procurement decision-making authority.
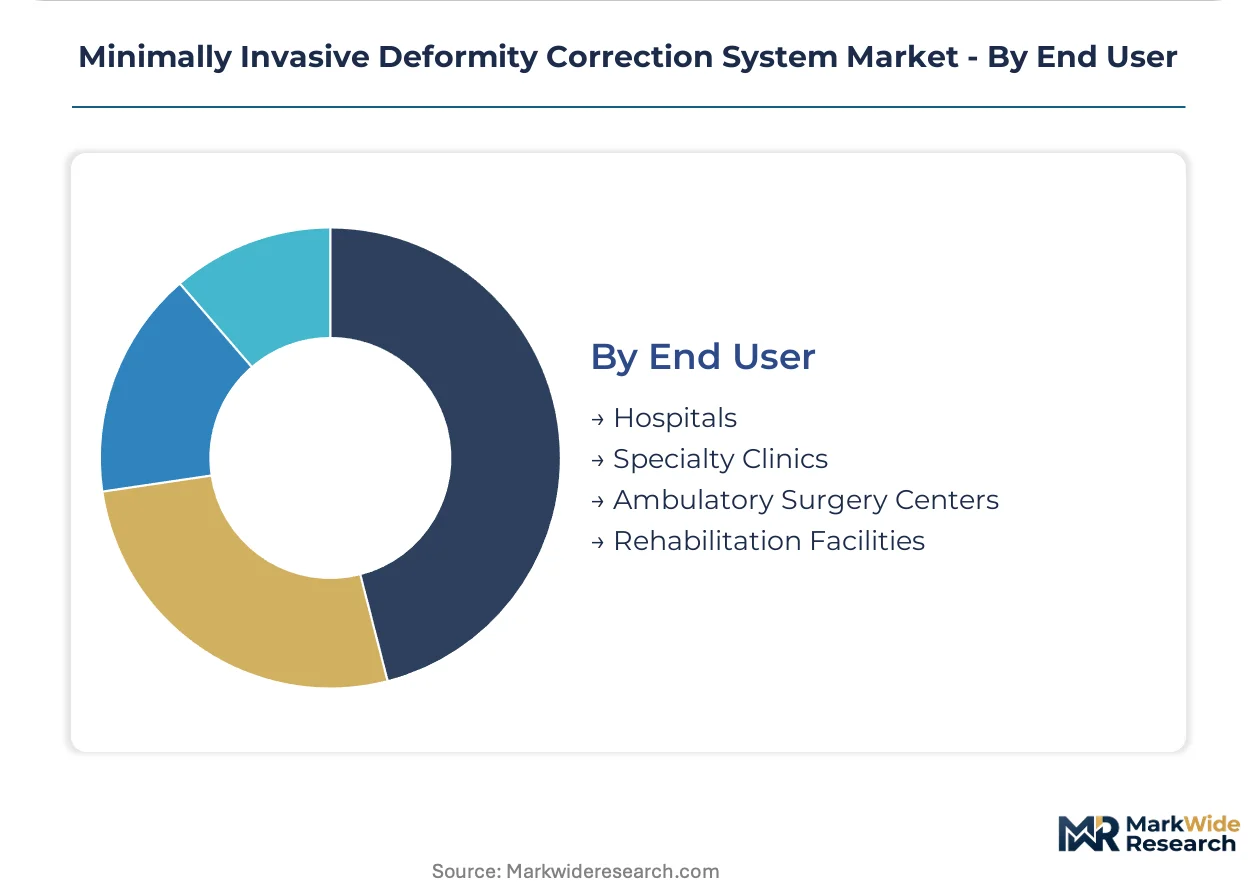
- Hospitals:Academic medical centers and large health systems deploy comprehensive deformity correction programs with robotics, navigation, and dedicated orthopedic service lines. North American hospital consolidations favor multi-year contracts bundling imaging capital, software licenses, and implant supply agreements.
- Ambulatory Surgery Centers:Freestanding surgical facilities perform select deformity corrections with lower acuity and reduced length-of-stay requirements. United States ASCs exploit favorable site-of-service reimbursement differentials for straightforward scoliosis cases.
- Specialty Clinics:Orthopedic and spine-focused clinics provide consultation, preoperative planning, and postoperative monitoring.
- Rehabilitation Facilities:Post-acute settings manage external fixation adjustments and gradual correction protocols.
Hospitals absorb the preponderance of capital equipment investment; ambulatory surgery centers are climbing fastest as case selection criteria broaden and payer policies evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-grade alloy processing for implant manufacturing concentrates in German metallurgical facilities and Chinese precision manufacturing zones. Hospital procurement committees in the United States and Germany bundle imaging capital with implant supply agreements into multi-year contracts. Regulatory divergence across FDA, EMA, and NMPA jurisdictions fragments product development roadmaps for device developers.
United States
Academic medical centers in Boston and New York Metro drive adoption of navigation-assisted deformity correction for adolescent idiopathic scoliosis. FDA 510(k) pathways compress clearance timelines for computer-assisted surgical devices, redirecting engineering resources toward iterative software upgrades. Hospital consolidations across the Midwest and Southeast favor standardized protocols with bundled imaging-to-implant contracts.
Germany
Specialized orthopedic centers in Bavaria and Baden-Württemberg integrate robotics into deformity correction workflows, creating reference sites for Central European procurement standardization. EU Medical Device Regulation imposes stricter clinical evidence requirements for implantable spinal systems. The Eindhoven-to-Munich medical technology corridor concentrates navigation platform development and surgeon training infrastructure.
China
State-backed medical device zones in Suzhou and Shenzhen expand cleanroom capacity for precision implant manufacturing and domestic surgical robot production. NMPA innovation approval channels accelerate review timelines for domestically developed navigation platforms. Yangtze River Delta hospitals pilot computer-assisted surgery reimbursement frameworks to validate capital-intensive robotics investments.
Japan
PMDA regulatory frameworks emphasize post-market surveillance for implantable spinal devices, extending clinical evidence maintenance obligations. METI industrial policy supports precision manufacturing clusters in the Nagoya and Osaka regions for titanium alloy component fabrication. Kanto-based academic medical centers lead adoption of optical tracking navigation for percutaneous rod placement procedures.
India
CDSCO medical device rules classify deformity correction implants under higher-risk categories, requiring enhanced quality management system documentation. Maharashtra and Karnataka host emerging distribution partnerships for navigation platform vendors seeking entry into private hospital chains. Delhi-NCR academic centers develop fellowship programs addressing fluoroscopy-to-navigation skill migration gaps.
Minimally Invasive Deformity Correction System Market Competitive Landscape
Integrated platform vendors and specialized component suppliers split the market between bundled system contracts and modular procurement arrangements. Hospital purchasing committees increasingly favor multi-year agreements combining imaging capital, software licenses, and implant supply over standalone component sourcing. Three strategic archetypes dominate: diversified medtech conglomerates with spine robotics portfolios, mid-tier navigation specialists seeking platform partnerships, and regional alloy processors controlling upstream material supply. Competitive moves center on M&A activity consolidating navigation software capabilities and strategic partnerships bridging regulatory submission gaps for small-cap developers.
Among diversified medtech conglomerates, Medtronic, Stryker, and Globus Medical occupy positions representing integrated platform strategies. Medtronic leverages its spine robotics presence across Asian markets through established distribution infrastructure. Stryker anchors its competitive position through imaging-to-implant workflow integration that reduces operative time in complex spinal reconstructions. Globus Medical exemplifies the navigation-specialist archetype seeking scale through platform consolidation. These three companies sit within the tier of vendors capable of bundling capital equipment, software, and implant supply into the multi-year contracts that hospital procurement committees now demand.
| Leading Market Players |
|---|
| Medtronic |
| DePuy Synthes |
| Stryker |
| Globus Medical |
| Zimmer Biomet |
| SI-BONE |
| NuVasive |
| Boston Scientific |
| Aesculap |
| Others |
Supply & Pricing Matrix
The Rotterdam-to-Frankfurt freight corridor carries titanium alloy rod components from German metallurgical facilities to Benelux distribution hubs, with container cost volatility feeding directly into premium-tier implant pricing and compressing margins for mid-tier navigation platform vendors unable to pass through logistics inflation.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure for deformity correction systems, separating premium robotics platforms with navigated workflows from standard fluoroscopy-guided rod constructs and economy-grade external fixation devices. Price differentiation hinges on CE marking grade under EU MDR and volume scale of hospital system contracts, with North American academic medical centers showing lowest price sensitivity due to bundled procurement authority while Indian private hospital chains exhibit acute cost consciousness. Pricing pressure intensifies in the standard tier as domestic Chinese manufacturers exploit NMPA innovation channel accelerations to undercut imported navigation platforms.
Supply Chain Analysis
High-grade cobalt-chrome feedstock concentrates in German metallurgical processing facilities, Chinese precision forging operations in Suzhou, and Japanese titanium alloy fabrication clusters in Nagoya. Finished implant manufacturing draws from optical tracking sensors sourced from Bavarian precision optics houses, electromagnetic navigation coils from South Korean component specialists, and surgical-grade polymers from Swiss extrusion facilities. Single-source vulnerability concentrates in German rod forging capacity, where any production disruption would cascade through European hospital procurement pipelines. Distribution runs through GPO-anchored contracts in the United States, direct-to-hospital agreements in Germany, and state-procurement frameworks in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital purchasing committee consolidation across North American health systems has shifted bargaining power decisively toward buyers capable of multi-year bundled contracts, fragmenting vendor pricing autonomy and forcing platform suppliers to absorb capital equipment financing costs.
For Market Incumbents: Build switching-cost moats through deep integration of navigation software with hospital EMR systems and captive surgeon training fellowship pipelines. Incumbents should anchor defensive positioning by acquiring optical tracking component suppliers to secure upstream sensor supply, while simultaneously lobbying CMS for favorable computer-assisted surgery reimbursement codes that protect robotics program economics against open-procedure substitution threats. For New Entrants and Emerging Players: Pursue white-space capture in India's emerging private hospital chains, where fluoroscopy-to-navigation skill gaps create procurement vulnerability for established Western vendors. New entrants should target hybrid external fixation systems for pediatric limb reconstruction in German orthopedic centers, leveraging NMPA innovation channel experience from Chinese regulatory consulting partners to accelerate CE marking timelines for European market entry. For Investors and Strategic Acquirers: Navigation-software specialists with FDA-cleared platforms but limited implant manufacturing capabilities represent the most defensible acquisition archetype for platform consolidation strategies. Long-term viability in this market rests on reimbursement code expansion rather than pure technology differentiation; investors should watch CMS physician fee schedule deliberations for computer-assisted surgery codes as the primary inflection signal determining whether capital-intensive robotics deployments achieve sustainable hospital economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year bundled contracts with GPOs lock in implant volume commitments across consolidated US health systems. |
| Reimbursement Strategy | CMS code advocacy for navigated deformity correction determines robotics program sustainability for hospital buyers. |
| CE Marking Pathway | EU MDR clinical evidence requirements favor manufacturers with established post-market surveillance infrastructure. |
| Software Companion Development | Preoperative planning modules integrated with hospital IT systems raise switching costs for competing platforms. |
| FDA Submission | 510(k) pathway compression for computer-assisted devices accelerates commercialization timelines versus PMA routes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement database records. Interviews with spine surgeons, biomedical engineers, GPO contracts managers, and orthopedic service line directors informed demand-side validation, while discussions with navigation platform engineers and titanium alloy metallurgists supplied supply-side perspective. Secondary sources include CMS Medicare reimbursement data, NMPA innovation approval registries, and German hospital procurement transparency reports. Bottom-up implant volume modeling triangulates against top-down health system capital expenditure tracking.
Forecast inputs span product type segmentation across rod, hybrid, plate, and fixator systems; technology tiers from conventional imaging through robotics; procedure type including scoliosis correction and limb lengthening; and end-user categories from academic medical centers to ambulatory surgery centers. CAGRs derive from installed base expansion rates for navigation platforms, procedure volume elasticity to reimbursement changes, and capital equipment replacement cycles. Industry-specific inputs incorporate EU MDR transition timelines for post-market surveillance obligations and NMPA innovation channel approval velocity for domestic Chinese surgical robots.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets, titanium alloy commodity pricing, or freight corridor cost structures would shift the trajectory. Forecasts embed assumptions regarding reimbursement code expansion and regulatory pathway stability that may require revision pending policy developments. Cross-checking against GPO contract announcement databases and hospital robotics installation tracking services is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Lacrimal Devices Market
Medical Devices
Endometrial Ablation Devices Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Global Bone Screw System Market
Medical Devices
MIS Sacroiliac Joint Fusion Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Pressure-Volume Loop Systems Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Organ Care Systems (OCS) Market