
 Trocars Market | 2026-2036
Trocars Market Size, Share, and Industry Trends Forecast 2026-2036
Trocars Market Intelligence
The EU Medical Device Regulation is shifting procurement criteria across European hospital systems toward higher-assurance instrument traceability. Medtronic leverages its integrated manufacturing footprint to meet these documentation requirements at scale. Ethicon competes through sustained R&D investment in polymer-based non-bladed designs. Stryker Corporation anchors its position via direct distribution networks into academic medical centers.
A trocar is a sharply pointed surgical instrument, typically constructed from stainless steel or medical-grade polycarbonate, designed to create a puncture wound and maintain a portal for the insertion of laparoscopic tools during minimally invasive procedures. Its primary purpose is to provide stable access to body cavities while minimizing tissue trauma and maintaining pneumoperitoneum. Bladed trocars retain dominance in high-volume general surgery settings, while optical trocars represent the fastest-growing category as surgeons prioritize direct visualization during entry. Stainless steel commands the material segment due to reusability economics in cost-sensitive health systems, though polycarbonate variants gain ground where single-use protocols dominate.
The FDA enforces Class II medical device controls over trocar safety and biocompatibility, while ISO 13485 certification shapes supplier qualification across OEM procurement channels. The EU MDR's Unique Device Identification requirements are forcing inventory system upgrades among distributors serving European surgical centers. Stakeholders must monitor how FDA guidance on reusable device reprocessing evolves against single-use cost pressures.
Market Dynamics
Single-use instrument protocols are compressing the reusable trocar installed base as hospitals reconfigure sterilization economics around infection control liability. The EU MDR's traceability mandates are forcing distributors to upgrade inventory systems ahead of compliance deadlines.
Growth Catalysts
- Outpatient procedural volume expansion:Ambulatory surgery centers in the United States are scaling laparoscopic capacity to capture migrating cases from inpatient settings, driving portal access instrument procurement.
- Optical entry technology:Direct visualization trocars are displacing blind entry techniques in general surgery departments, reducing vascular injury litigation exposure and accelerating category upgrade cycles.
- EU MDR compliance window:European hospital systems are pre-positioning certified single-use inventories ahead of Unique Device Identification enforcement, pulling forward replacement demand.
Market Restraints
- Medical-grade polycarbonate supply concentration:Specialty polymer feedstock for disposable trocar housings routes through a narrow supplier base in Germany and Belgium, exposing molders to allocation risk during petrochemical volatility.
- Stainless steel reusability economics:Cost-sensitive health systems in India and Brazil extend instrument lifecycles through third-party reprocessing, delaying single-use conversion and capping premium pricing power.
- FDA reprocessing guidance uncertainty:Evolving draft recommendations on reusable device validation create procurement paralysis among US hospital systems awaiting final rule clarity.
Strategic Opportunities
- Optical-haptic convergence:Force-feedback sensing layered onto visualization platforms enables entry force quantification, opening premium positioning in bariatric and pediatric surgery segments.
- Direct-to-ambulatory distribution:Bypassing traditional distributor markups through manufacturer-owned logistics to US surgery centers captures margin and accelerates same-day fulfillment.
- Japanese PMDA fast-track pathway:Streamlined approval for instruments with predicate equivalence allows earlier market entry versus standard 12-18 month review cycles.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity validation queues at contracted laboratories extend product launch timelines by 4-6 months.
- Legacy sterilization infrastructure stranded assets:Health systems with recent capital deployment into central sterile processing face write-down pressure when converting to single-use protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trocars Market |
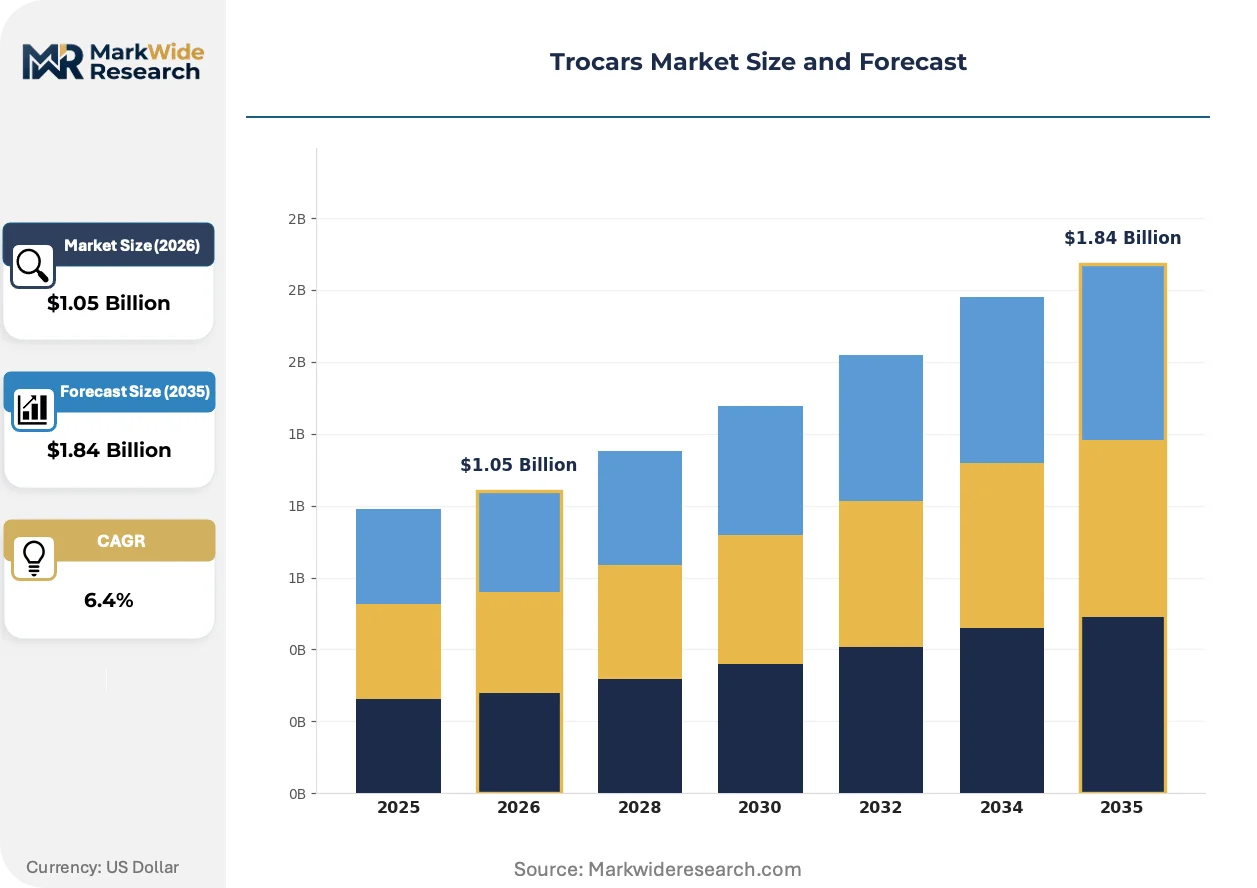
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bladed, Non-Bladed, Optical, Balloon, Dilating Application: Laparoscopy, Thoracoscopy, Arthroscopy, Gynecologic Surgery, Urologic Surgery End User: Surgical Centers, Specialty Clinics, Teaching Hospitals, Ambulatory Surgery Centers Material: Stainless Steel, Polycarbonate, Silicone, Titanium, ABS Plastic |
| Companies Covered | B. Braun, CONMED Corporation, Medtronic, Stryker Corporation, Genicon, Ethicon, Teleflex Incorporated, Purple Surgical, Applied Medical Resources Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trocars Market Strategic Shifts & Innovations
Material science and regulatory instrumentation are compressing product lifecycles while expanding the addressable procedure set. Surgeons and procurement officers now weight traceability and visualization parity against capital recovery timelines.
Polymer-based non-bladed trocar designs are electrifying entry safety profiles by eliminating sharp-tipped components that historically caused visceral and vascular lacerations. Academic medical centers in the United States and university hospitals in Germany are standardizing these platforms across general surgery residencies. The technology is electrifying competitive positioning by collapsing the safety-versus-cost tradeoff that previously segmented the installed base.
EU MDR Unique Device Identification requirements are forcing European distributors to deploy serialized inventory tracking from manufacturer through point-of-use. Hospital procurement departments must reconcile legacy ERP systems with EUDAMED database integration by compliance deadlines. Single-use trocar categories face the steepest implementation burden given high SKU velocity and expiration-date sensitivity.
Surgeon preference for direct visualization during abdominal entry is compressing switching cycles between instrument generations. General surgery departments that historically retained trocar sets for 7-10 years now accelerate replacement to capture optical platform improvements. The United States exhibits the shortest replacement intervals, driven by malpractice risk management and residency training standardization.
Trocars Market Segmentation
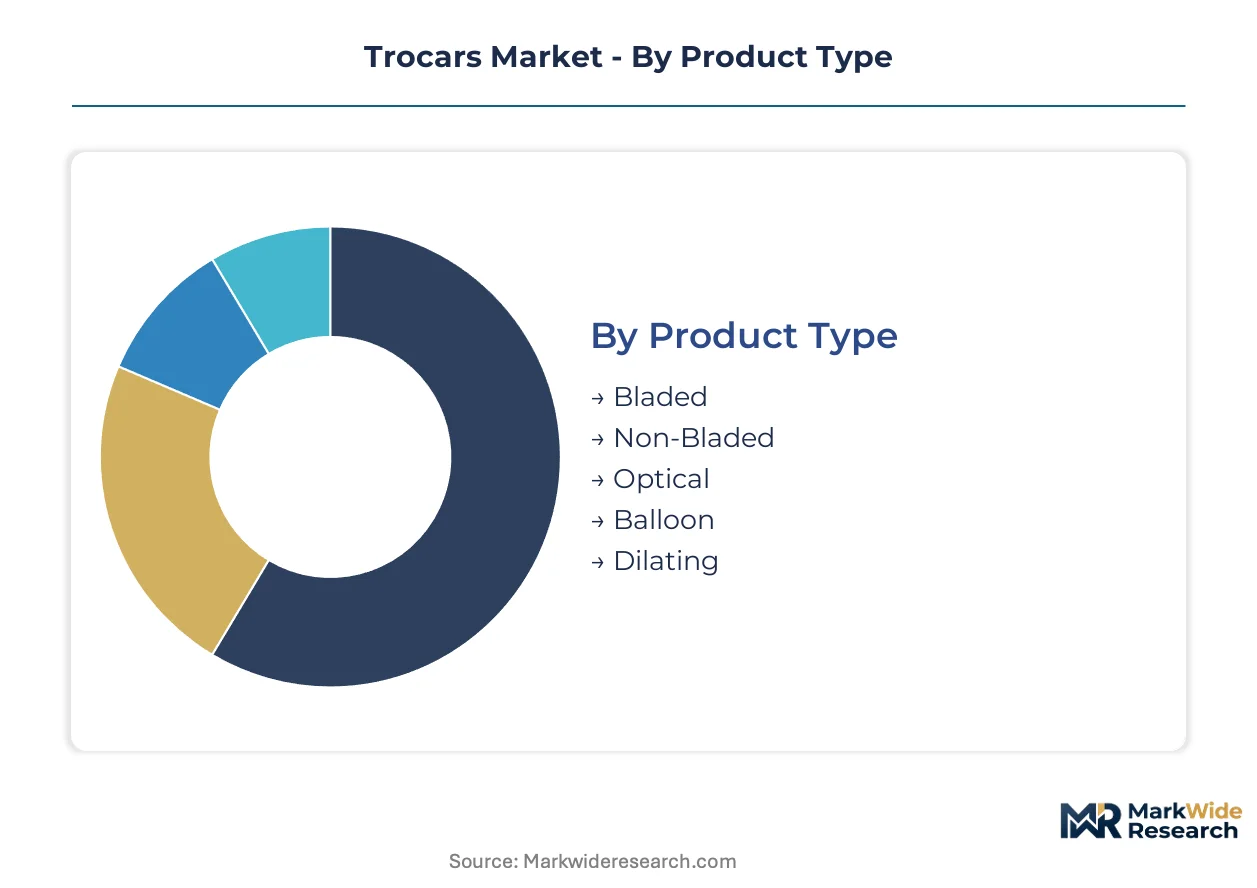
Trocar segmentation reflects divergent procurement priorities across surgical settings. Product type determines entry safety profiles and visualization capabilities. Material selection hinges on sterilization infrastructure and single-use conversion economics.
Product Type:
Standardization dominates high-volume general surgery, while optical platforms command customization premiums in academic settings.
- Bladed:Stainless steel or polymer housings with sharpened pyramidal or conical tips penetrate abdominal wall fascia under manual pressure. Demand concentrates in cost-sensitive health systems across India and Brazil where reusable protocols persist and capital replacement cycles extend.
- Optical:Transparent polymer cannulas integrate laparoscope channels for direct visualization during entry, eliminating blind insertion risks. United States academic medical centers prioritize these platforms to reduce vascular injury litigation and standardize residency training curricula.
- Non-Bladed:Blunt-tipped dilating designs separate tissue fibers rather than cutting, reducing visceral laceration incidence.
- Balloon:Inflatable distal anchors secure pneumoperitoneum in bariatric populations with thickened abdominal walls.
- Dilating:Sequential diameter expansion enables single-site entry with minimal fascial defect.
Most installed capacity flows through Bladed trocars. Expansion is steepest in Optical.
Application:
Procedure volume distribution across surgical specialties determines SKU velocity and inventory turnover requirements.
- Laparoscopy:Abdominal and pelvic cavity access for cholecystectomy, appendectomy, and hernia repair constitutes the foundational use case. Ambulatory surgery centers in the United States scale laparoscopic suites to capture migrating cases from inpatient settings, driving portal instrument procurement.
- Thoracoscopy:Pleural cavity visualization and lung resection access require specialized trocar lengths and angled configurations. German university hospitals standardize thoracoscopic platforms across cardiothoracic training programs, pulling optical entry technology into this segment.
- Arthroscopy:Joint space access for knee and shoulder procedures demands smaller diameter instruments with fluid management integration.
- Gynecologic Surgery:Hysteroscopic and laparoscopic fertility procedures utilize low-profile entry systems.
- Urologic Surgery:Retroperitoneal and transperitoneal renal access requires extended working lengths.
Procedure volume concentrates in Laparoscopy. Technology migration is most rapid in Thoracoscopy.
End User:
Capital intensity and sterilization infrastructure differentiate procurement patterns across facility types.
- Ambulatory Surgery Centers:Freestanding facilities optimized for same-day discharge prioritize single-use disposables to eliminate reprocessing overhead and liability exposure. United States outpatient procedural volume expansion drives trocar procurement in this channel.
- Teaching Hospitals:Academic medical centers balance training standardization against budget constraints, often maintaining hybrid reusable-single-use inventories. Residency program accreditation requirements in the United States and Germany mandate optical platform availability.
- Surgical Centers:Hospital-affiliated same-day surgery units leverage central sterile processing infrastructure.
- Specialty Clinics:Focused gynecologic or urologic practices require procedure-specific instrument configurations.
Procurement volume concentrates in Ambulatory Surgery Centers. Technology upgrade cycles are shortest in Teaching Hospitals.
Material:
Supply concentration and sterilization validation costs shape material selection across health system tiers.
- Stainless Steel:Surgical-grade 304 and 316L alloys deliver durability for 50-100 reprocessing cycles in autoclave systems. Cost-sensitive health systems in India and Brazil extend instrument lifecycles through third-party reprocessing, anchoring demand for metal platforms.
- Polycarbonate:Medical-grade aromatic thermoplastics provide optical clarity and impact resistance for single-use housings. EU MDR traceability mandates accelerate polycarbonate trocar adoption as European hospitals pre-position certified single-use inventories.
- Silicone:Elastomeric seals and valve components ensure pneumoperitoneum maintenance.
- Titanium:Lightweight corrosion-resistant alloys serve niche reusable applications.
- ABS Plastic:Cost-engineered housings target emerging market price points.
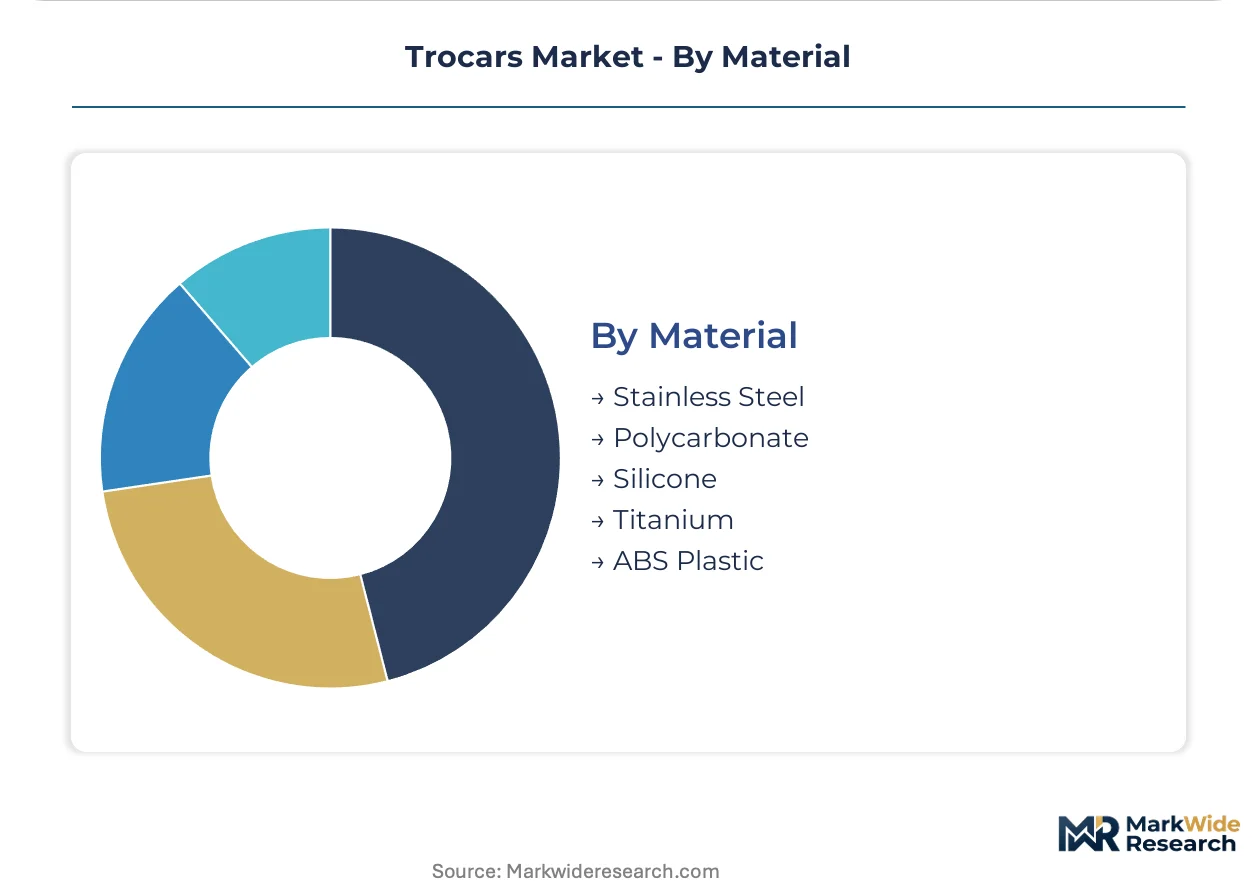
Installed base concentrates in Stainless Steel. Conversion momentum is strongest in Polycarbonate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The trocar industry traces its modern commercial origins to German surgical instrument engineering in the late twentieth century, where precision metalworking traditions enabled the first standardized laparoscopic access systems. From that foundation, production and demand have dispersed across five principal national markets.
United States
Ambulatory surgery centers in Texas and Florida are scaling laparoscopic capacity to capture migrating cholecystectomy and hernia repair cases from inpatient settings. FDA Class II device controls enforce biocompatibility validation and 510(k) clearance timelines for new optical entry platforms. The Minneapolis-St. Paul corridor anchors several major manufacturers' distribution infrastructure serving academic medical centers nationwide.
Germany
University hospitals in Baden-Württemberg and Bavaria standardize thoracoscopic and laparoscopic training curricula, pulling optical trocar technology into cardiothoracic and general surgery residencies. EU MDR Unique Device Identification mandates force distributors serving the Tübingen and Heidelberg surgical clusters to deploy serialized inventory tracking ahead of EUDAMED integration deadlines. Stuttgart-area polymer compounders supply medical-grade polycarbonate feedstock for single-use instrument housings.
Japan
Aging demographics and minimally invasive procedure preference in the Kanto and Kansai regions sustain demand for precision entry systems. PMDA fast-track pathways for predicate-equivalent instruments compress approval timelines versus standard review cycles, enabling earlier market entry for optical platform upgrades. Tokyo-based teaching hospitals anchor technology adoption curves that diffuse to regional medical centers.
India
Cost-sensitive health systems in Maharashtra and Tamil Nadu extend stainless steel trocar lifecycles through third-party reprocessing, delaying single-use conversion. CDSCO medical device rules impose registration requirements on imported instruments, shaping procurement patterns among Delhi-NCR and Bengaluru hospital chains. Ahmedabad-area metal fabricators supply reusable instrument components to domestic distributors.
Brazil
Private hospital networks in São Paulo and Rio de Janeiro balance infection control liability against capital constraints when evaluating single-use protocols. ANVISA medical device regulations require in-country registration and quality system certification for imported trocar lines. The Campinas medical device cluster hosts sterilization equipment manufacturers whose installed base influences reusable-single-use economics.
Trocars Market Key Industry Players
Premium-margin players sit above commodity-margin players across documentation capability and optical platform sophistication. The vendor base organizes into three tiers: integrated multinationals with full regulatory dossiers, mid-scale specialists with regional certification depth, and price-focused fabricators serving emerging market reprocessing protocols. Strategic moves concentrate on direct distribution bypass into ambulatory surgery centers and polymer-based non-bladed design portfolios that collapse the safety-cost tradeoff.
Among integrated multinationals, Medtronic, Ethicon, and Stryker Corporation exemplify the premium-tier archetype through manufacturing footprint scale and regulatory dossier breadth. Medtronic occupies a position anchored by integrated production systems capable of EU MDR documentation at volume. Ethicon sits within the polymer-based non-bladed design specialization. Stryker Corporation represents the direct distribution model into academic medical centers. Each anchors a distinct competitive vector without overlapping positioning.
| Leading Market Players |
|---|
| B. Braun |
| CONMED Corporation |
| Medtronic |
| Stryker Corporation |
| Genicon |
| Ethicon |
| Teleflex Incorporated |
| Purple Surgical |
| Applied Medical Resources Corporation |
| Others |
Cost & Logistics Intelligence
Captive polycarbonate compounding in Germany and Belgium anchors supply positioning and pricing power for single-use trocar manufacturers serving European hospital systems. This backward integration into medical-grade polymer feedstock insulates molders from petrochemical volatility while supporting premium positioning against reprocessed stainless steel alternatives in cost-sensitive markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates optical visualization platforms from bladed reusable sets from ABS plastic emerging market variants. Price differentiation hinges on FDA 510(k) clearance tier and optical entry certification against blind insertion liability. Cost compression in standard-tier bladed instruments is intensifying because Brazilian and Indian health systems extend third-party reprocessing cycles. Ambulatory surgery centers in the United States exhibit the least price sensitivity, prioritizing single-use disposables to eliminate sterilization overhead and malpractice exposure.
Supply Chain Analysis
Single-source vulnerability sits with Stuttgart-area polymer compounders supplying medical-grade polycarbonate for optical trocar housings. Manufacturing concentrates in Germany, the United States, and Japan for precision metalworking and polymer molding capabilities. Raw material dependencies include aromatic thermoplastics, surgical-grade 316L stainless steel, and silicone elastomeric seals. Tariff exposure on Chinese-sourced ABS plastic components threatens cost-engineered economy tier production. Distribution runs through manufacturer-direct logistics to ambulatory surgery centers and traditional medical-surgical distributors serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as outpatient procedural volume expansion in the United States pulls specification upgrades toward optical entry platforms with force-feedback integration.
For Market Incumbents: Deepen EU MDR documentation capabilities ahead of Unique Device Identification enforcement deadlines to capture replacement demand from distributors upgrading inventory systems. Anchor position through captive polycarbonate supply agreements with Stuttgart-area compounders, insulating against feedstock allocation risk from emerging entrant molders lacking backward integration.
For New Entrants and Emerging Players: Optical-haptic convergence technology offers a technology-first wedge into bariatric and pediatric surgery segments where entry force quantification commands premium positioning. Target ambulatory surgery centers in Texas and Florida through direct distribution partnerships, bypassing traditional distributor markups. Penetrate Japanese university hospitals via PMDA fast-track predicate equivalence pathways.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale optical platform specialists because EU MDR compliance costs are forcing fragmentation among distributors lacking serialized inventory tracking infrastructure. Five-to-ten year viability favors manufacturers with integrated polymer compounding and direct-to-ambulatory logistics. Watch FDA final rule clarity on reusable device reprocessing as the inflection signal for single-use conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Unique Device Identification compliance secures access to German and French hospital procurement channels. |
| Hospital System Partnership | Direct distribution agreements with Texas ambulatory surgery centers capture margin and accelerate fulfillment. |
| Optical Platform Integration | Force-feedback sensing layered onto visualization systems opens premium positioning in bariatric segments. |
| Backward Integration into Polycarbonate | Captive medical-grade polymer supply insulates against German compounder allocation risk during volatility. |
| Reimbursement Strategy | Outpatient procedural volume expansion in United States ASCs supports optical platform upgrade cycles. |
Research Approach
Direct dialogue with hospital purchasing committees, GPO contracts managers, biomedical engineers, and laparoscopic surgeons grounded qualitative assessment, cross-referenced against FDA 510(k) filings, EU MDR EUDAMED database records, hospital procurement databases, and CMS Medicare outpatient procedure data. Bottom-up and top-down triangulation validated volume estimates across product type, material, application, and end-user segments.
Bottom-up modeling aggregated procedure volume by surgical specialty and facility type, while top-down analysis calibrated against medical-surgical distributor revenue disclosures and polymer feedstock demand indicators across the projection horizon. Segmentation dimensions included product type (bladed, optical, non-bladed), material (stainless steel, polycarbonate, ABS plastic), application (laparoscopy, thoracoscopy, arthroscopy), and end-user (ambulatory surgery centers, teaching hospitals, surgical centers). CAGRs derived from weighted average of historical replacement cycle compression and single-use protocol conversion rates.
The model holds under stable FDA reprocessing guidance and EU MDR enforcement timelines; deviation in regulatory final rule clarity or petrochemical supply disruption would shift conversion trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Leadless Pacing Systems Market
Medical Devices
Microwave Ablation Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Global Liposuction Surgery Devices Market
Medical Devices
Russia Viscosupplementation Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Automated Insulin Delivery Device Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Lower Limb Prosthetics Market
Medical Devices
Battery-Operated Lactate Meter Market