
 Non-Rebreathing Oxygen Mask Market | 2026-2036
Non-Rebreathing Oxygen Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Rebreathing Oxygen Mask Market Analysis
The capital-intensity divergence between integrated manufacturers and assembly-only suppliers is redrawing competitive boundaries in oxygen delivery devices. Philips Respironics leverages captive resin compounding and in-house mask molding to sustain margin control across North American hospital contracts. Intersurgical Ltd anchors its position through automated PVC and silicone production lines in Europe, while Fisher & Paykel Healthcare differentiates via heated humidification integration with non-rebreathing circuits in Australasian markets.
A non-rebreathing oxygen mask is a high-concentration respiratory device incorporating a one-way valve system and reservoir bag to deliver oxygen fractions exceeding 80 percent while minimizing carbon dioxide retention, typically manufactured from medical-grade PVC or silicone with adjustable nose clips and elastic head straps for sealed facial fit. The adult mask segment dominates hospital procurement volumes due to standardized sizing and bulk purchasing agreements, while pediatric variants command premium positioning through specialized dimensional tolerances and safety certifications. Disposable PVC masks lead unit economics in emergency services where cross-contamination protocols mandate single-patient use, whereas silicone reusable alternatives concentrate margin pools in home care settings where durability and skin compatibility drive replacement cycles.
FDA 510(k) clearance requirements and ISO 10993 biocompatibility standards govern material selection and valve performance validation for US market entry, while the EU Medical Device Regulation mandates notified body certification and post-market surveillance for CE-marked products distributed in Europe. Stakeholders must monitor evolving polymer regulations and reimbursement coding shifts for high-flow oxygen therapy to align product portfolios with emerging clinical protocols and payer coverage criteria.
Market Dynamics
Hospital emergency departments are consolidating purchasing power around high-flow oxygen delivery systems, compressing margins for standalone mask suppliers while rewarding integrated respiratory device manufacturers with multi-year contract awards.
Growth Catalysts
- ISO 10993 biocompatibility mandates:Medical-grade silicone adoption is accelerating as FDA 510(k) pathways tighten material validation requirements for acute respiratory devices.
- Home care oxygen therapy expansion:Durable reusable mask demand is concentrating in post-acute settings where skin compatibility and extended wear cycles reduce replacement frequency.
- Japan's acute respiratory infrastructure:METI-backed hospital modernization programs are driving procurement of heated humidification-integrated circuits in tertiary care facilities.
Market Restraints
- Medical-grade PVC resin concentration:Supply bottlenecks in Asian petrochemical corridors are transmitting price volatility downstream to disposable mask converters.
- EU MDR notified body capacity:Extended CE-marking timelines for Class IIa respiratory devices are freezing product line extensions across European distribution networks.
- High-flow nasal cannula substitution:Heated and humidified nasal oxygen delivery is displacing traditional reservoir mask applications in intermediate care wards.
Strategic Opportunities
- India's tertiary care expansion:CDSCO streamlined medical device registration pathways are opening procurement channels for imported respiratory accessories in corporate hospital chains.
- Pediatric dimensional specialization:Underserved neonatal and infant mask sizing creates premium positioning for manufacturers with ISO 13485-certified cleanroom molding capabilities.
- Telemedicine-integrated home monitoring:Bluetooth-enabled oxygen saturation tracking is converging with reusable mask platforms to create subscription-based respiratory management services.
Industry Challenges
- Biocompatibility testing timelines:ISO 18562 cytotoxicity validation for new polymer formulations extends product development cycles by 12-18 months.
- Cleanroom molding capacity scarcity:Qualified medical device injection molding contractors are operating at utilization rates above 85% across North American and European manufacturing corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Rebreathing Oxygen Mask Market |
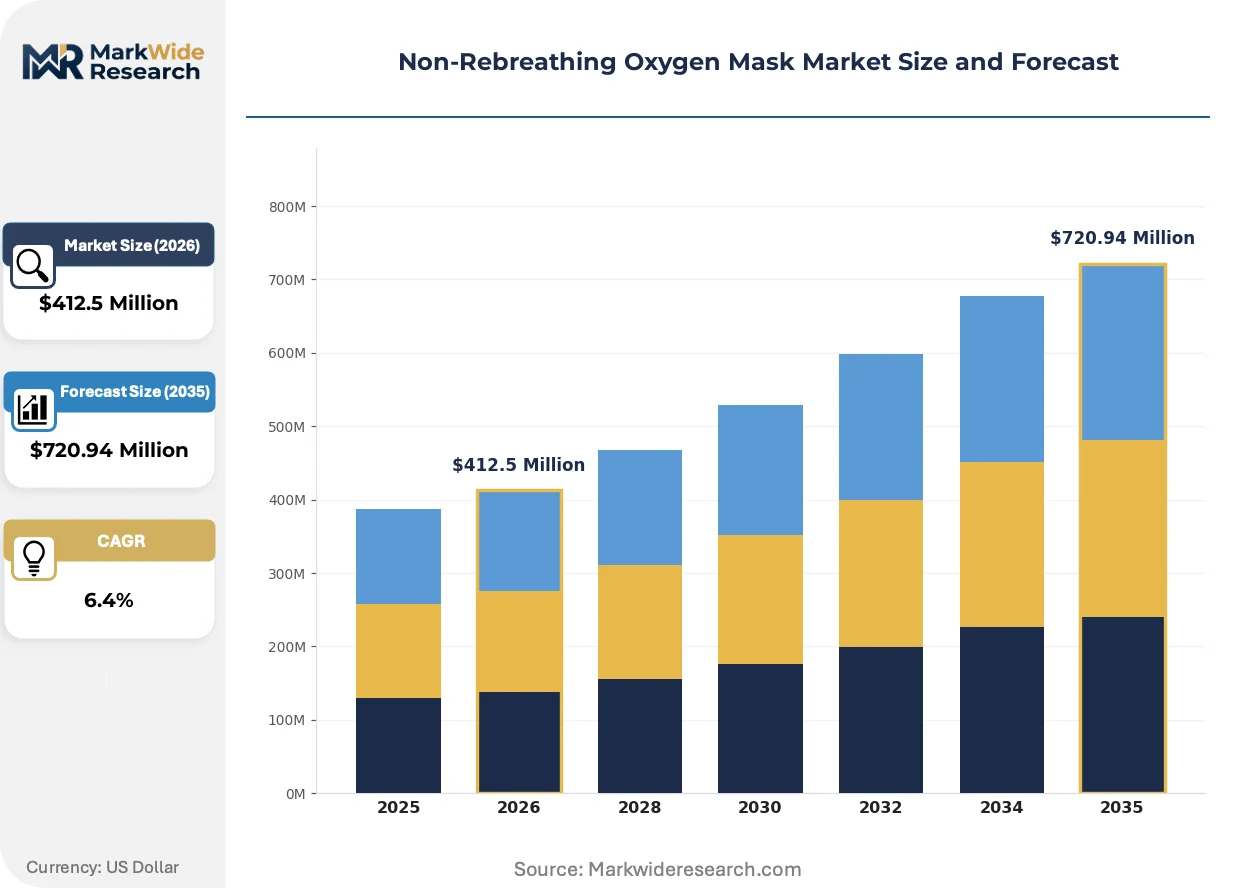
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Masks, Pediatric Masks, Disposable Masks, Reusable Masks End User: Hospitals, Emergency Services, Home Care, Clinics Material: Silicone, PVC, Latex, Rubber Connection Type: Standard Connector, Integral Connector, Adjustable Connector, Others |
| Companies Covered | Philips Respironics, Intersurgical Ltd, Smiths Medical, Fisher & Paykel Healthcare, Teleflex Incorporated, Becton Dickinson and Company, Medline Industries, Drägerwerk AG & Co. KGaA, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Rebreathing Oxygen Mask Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are reconfiguring how oxygen delivery devices achieve clinical validation and manufacturing scale.
Heated humidification integration with non-rebreathing circuits is decomposing the traditional separation between mask and conditioning hardware. Hospital systems in Australia and New Zealand are specifying bundled respiratory circuits that combine reservoir bags, heated wire tubing, and humidification chambers under single-source contracts. This convergence is compressing the addressable market for standalone mask suppliers while elevating engineering capabilities required for competitive participation.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC compound reformulation across European supply chains. Medical device manufacturers are accelerating migration to citrate-based plasticizers and alternative polymer substrates to maintain CE-marking compliance. German and French notified bodies are prioritizing technical file reviews for devices with documented substitution strategies, creating first-mover advantages for compounders with validated non-phthalate portfolios.
Group purchasing organizations are consolidating acute care procurement decisions for respiratory accessories across multi-hospital networks. Independent distributors are losing shelf space to direct manufacturer agreements as IDN procurement committees standardize on contracted SKUs. This concentration is most visible in United States metropolitan markets where three major GPOs control over 60% of oxygen delivery device spend.
Non-Rebreathing Oxygen Mask Market Segmentation
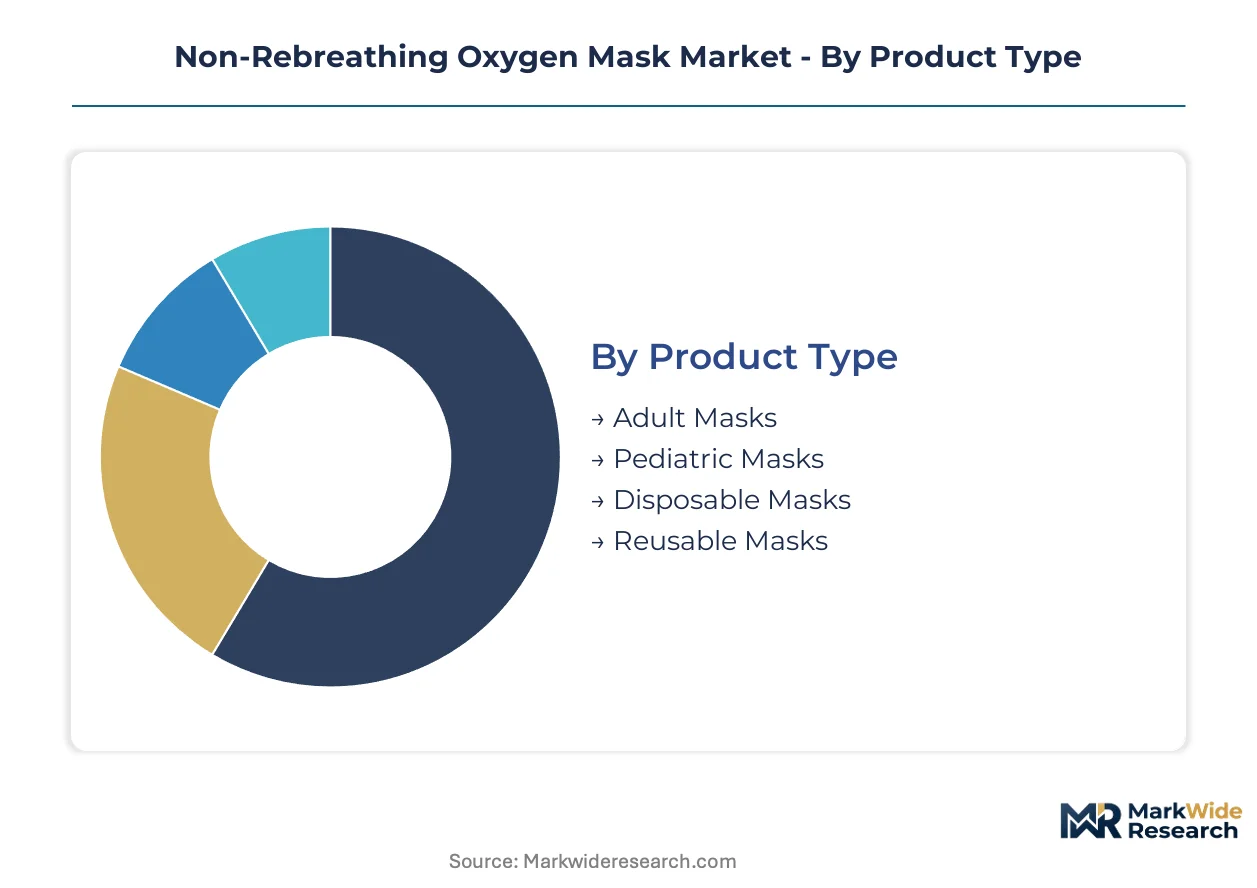
Segmentation in non-rebreathing oxygen masks determines regulatory pathways, procurement economics, and manufacturing scale requirements. FDA 510(k) and ISO 10993 requirements vary sharply across material and patient-age categories, creating divergent competitive moats.
Product Type:
ISO 10993 biocompatibility tiers and patient-age specifications split validation costs and margin structures across product categories.
- Adult Masks:Standardized 22mm ISO connectors and universal facial geometry enable high-volume molding with minimal SKU proliferation. Hospital emergency departments in the United States and Germany consolidate procurement around these specifications for bulk contract efficiency.
- Pediatric Masks:Dimensional tolerances for neonatal through adolescent sizing demand ISO 13485-certified cleanroom production with specialized cavity tooling. Japanese tertiary care facilities drive premium positioning through METI-backed safety certification requirements.
- Disposable Masks:Single-use PVC formulations dominate emergency services where cross-contamination protocols mandate patient-specific allocation.
- Reusable Masks:Medical-grade silicone withstands autoclave cycles for home care durability and skin compatibility.
Adult masks handle the majority of throughput; pediatric masks are expanding most quickly on share.
End User:
Procurement authority and reimbursement coding create distinct margin profiles across care settings.
- Hospitals:Group purchasing organization concentration in United States metropolitan markets compresses standalone mask margins while rewarding integrated respiratory device vendors with multi-year awards.
- Emergency Services:Disposable PVC unit economics align with ambulance and air-medical protocols where sterilization infrastructure is absent.
- Home Care:Reusable silicone platforms with extended replacement cycles concentrate in post-acute settings where patient self-administration drives durability preferences.
- Clinics:Intermediate volume procurement splits between disposable and reusable stock based on specialty respiratory service intensity.
Hospitals absorb the dominant procurement volume; home care registers the steepest expansion trajectory.
Material:
REACH Annex XVII phthalate restrictions and FDA polymer validation timelines are forcing compound reformulation across supply chains.
- Silicone:Platinum-cured medical grades deliver biocompatibility for reusable platforms with ISO 18562 cytotoxicity clearance. German notified bodies prioritize technical file reviews for silicone substitution strategies.
- PVC:Citrate-based plasticizer migration is accelerating as ECHA restrictions eliminate traditional phthalate formulations from European distribution.
- Latex:Declining share due to Type I hypersensitivity risk in acute care protocols.
- Rubber:Niche positioning in industrial oxygen delivery outside regulated medical channels.
PVC maintains the highest unit throughput; silicone is gaining share fastest on regulatory tailwinds.
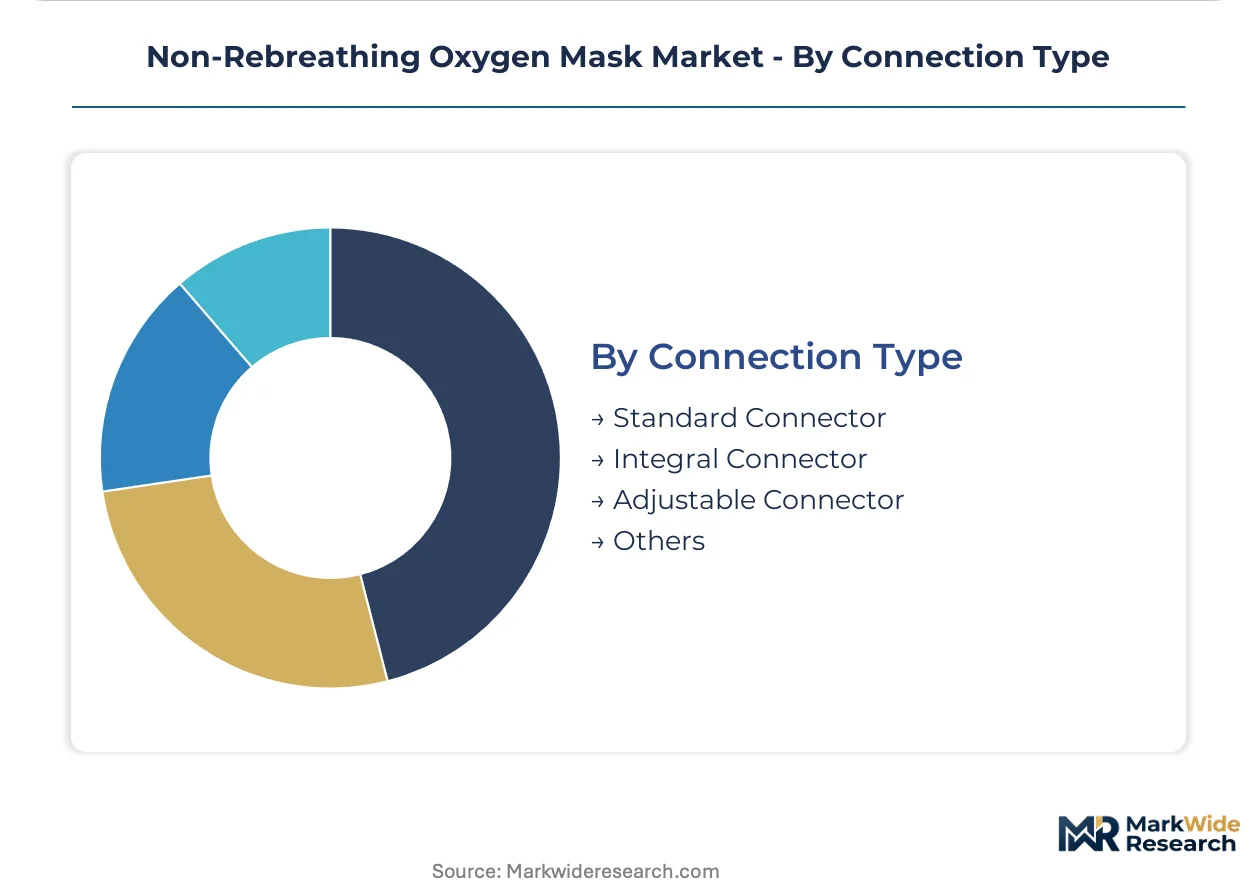
Connection Type:
Interoperability standards and heated humidification integration are reshaping connector specification requirements.
- Standard Connector:ISO 5356-1 compliant 22mm/15mm dimensions ensure interchangeability across ventilator and oxygen source platforms.
- Integral Connector:Molded single-piece construction reduces leak paths in high-flow circuits specified by Australian and New Zealand hospital systems.
- Adjustable Connector:Rotating or telescoping designs accommodate patient positioning in emergency transport.
- Others:Proprietary interfaces for bundled respiratory circuit contracts.
Standard connectors dominate procurement volumes; integral configurations are climbing the fastest on heated humidification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across acute care markets. Japanese hospital systems absorb premium pricing for heated-humidification integration, while Indian procurement remains volume-driven and price-sensitive.
United States
Group purchasing organizations consolidate oxygen delivery device spend across metropolitan hospital networks. FDA 510(k) clearance timelines and ISO 10993 biocompatibility mandates govern material selection for acute respiratory devices. The Boston-Cambridge medical device corridor hosts specialized polymer compounders serving Class IIa respiratory manufacturers.
Germany
Notified bodies prioritize technical file reviews for phthalate-free PVC substitution strategies under REACH Annex XVII. EU MDR certification requirements extend timelines for new respiratory device market entry. The Baden-Württemberg industrial belt concentrates medical-grade silicone molding capacity for reusable mask platforms.
Japan
METI-backed hospital modernization programs drive procurement of heated humidification-integrated circuits in tertiary care facilities. PMDA regulatory pathways align with international standards while maintaining domestic safety certification requirements. The Osaka-Kobe manufacturing zone anchors production of precision-molded respiratory components for Asia-Pacific distribution.
India
CDSCO streamlined medical device registration pathways open procurement channels for imported respiratory accessories in corporate hospital chains. Price sensitivity dominates tender processes for disposable PVC masks in government health programs. The Maharashtra-Gujarat pharmaceutical corridor attracts contract manufacturers targeting domestic and export markets.
Australia
TGA regulatory harmonization with international standards facilitates rapid market entry for ISO 13485-certified suppliers. Bundled respiratory circuit contracts specify heated wire tubing and humidification chambers under single-source agreements. The Melbourne-Sydney medical technology cluster concentrates distribution infrastructure for Oceania acute care networks.
Non-Rebreathing Oxygen Mask Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in oxygen delivery devices. Captive resin compounding and in-house mask molding distinguish the upper tier from assembly-dependent competitors. Three archetypes populate the landscape: diversified respiratory device conglomerates, specialized disposable consumables manufacturers, and integrated heated-humidification system vendors. Competitive moves concentrate on multi-year hospital contract awards and regulatory-first-mover positioning in phthalate-free material transitions.
Among diversified respiratory device conglomerates, Philips Respironics and GE Healthcare exemplify integrated manufacturing architectures spanning polymer compounding through finished device assembly. Fisher & Paykel Healthcare occupies a distinct position at the convergence of mask platforms and heated humidification systems, reflecting the Australian-New Zealand market preference for bundled respiratory circuits. These three anchors illustrate how geographic origin and corporate structure map onto divergent competitive vectors in acute oxygen delivery.
| Leading Market Players |
|---|
| Philips Respironics |
| Intersurgical Ltd |
| Smiths Medical |
| Fisher & Paykel Healthcare |
| Teleflex Incorporated |
| Becton Dickinson and Company |
| Medline Industries |
| Drägerwerk AG & Co. KGaA |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Citrate-based plasticizer substitution for traditional phthalate formulations is simultaneously shifting compounding capacity toward German and French chemical corridors and compressing margin structures for disposable mask converters unable to absorb reformulation costs. This material transition rewards compounders with validated non-phthalate portfolios while penalizing assembly-dependent suppliers locked into legacy PVC supply agreements.
Pricing Analysis
After-sales service contracts for heated humidification maintenance and mask replacement scheduling now drive lifetime value beyond initial hardware procurement. Three-tier pricing structure across premium silicone reusable platforms, standard disposable PVC contracts, and economy bulk tenders for emergency services governs hospital procurement. Cost compression in the disposable tier intensifies as group purchasing organizations consolidate oxygen delivery spend across metropolitan networks. Emergency services exhibit highest price sensitivity due to volume-driven government tenders, while Japanese tertiary care facilities show lowest sensitivity given METI-backed modernization budgets.
Supply Chain Analysis
Germany and China anchor medical-grade silicone compounding and PVC resin production respectively, with the Baden-Württemberg industrial belt hosting platinum-cured silicone molding for reusable platforms. The supply chain draws from Asian petrochemical corridors for PVC resin, European specialty chemical producers for citrate plasticizers, and North American cleanroom molding contractors for finished device assembly. Single-source vulnerability concentrates in medical-grade polymer validation capacity, where ISO 18562-certified testing laboratories operate at utilization rates above 85%. Distribution runs through group purchasing organization networks in the United States, direct hospital contracts in Germany, and specialized respiratory device distributors in Japan and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-rebreathing oxygen mask market functions as a service-attach opportunity where humidification maintenance contracts and remote patient monitoring subscriptions expand faster than standalone mask hardware sales. Recurring revenue layers around respiratory management platforms now justify premium valuations for integrated device vendors.
For Market Incumbents: Fortify positions through backward integration into medical-grade silicone compounding and captive cleanroom molding capacity to defend against high-flow nasal cannula substitution threats. Philips Respironics and Fisher & Paykel Healthcare exemplify this architecture through in-house resin formulation and heated humidification integration. Priority investment in ISO 13485-certified pediatric molding capabilities creates defensive moats given Japanese METI safety certification requirements. For New Entrants and Emerging Players: Pediatric dimensional specialization represents the most penetrable white-space where ISO 10993 biocompatibility mandates have frozen incumbent product line extensions. India's CDSCO streamlined registration pathways offer geographic entry with lower competitive density than saturated United States GPO markets. A telemedicine-integrated home monitoring go-to-market angle bypasses hospital procurement concentration entirely. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compounders with validated non-phthalate portfolios and cleanroom molding assets over assembly-only suppliers. Long-term viability hinges on regulatory-first-mover positioning in REACH Annex XVII compliance and heated humidification bundling capabilities. Watch FDA 510(k) clearance timelines for phthalate-free PVC formulations as the inflection signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Phthalate-Free PVC Reformulation | REACH Annex XVII compliance secures CE-marking continuity across European distribution networks. |
| Heated Humidification Integration | Australian hospital bundled contracts specify single-source respiratory circuit vendors with conditioning hardware. |
| Pediatric Cleanroom Molding Investment | ISO 13485-certified neonatal sizing captures premium positioning in Japanese tertiary care procurement. |
| Telemedicine Platform Partnership | Bluetooth-enabled saturation tracking enables subscription-based home respiratory management services. |
| India CDSCO Registration Pathway | Streamlined medical device approval opens corporate hospital chain procurement for imported accessories. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineering managers, group purchasing organization contract specialists, and respiratory therapy department heads and refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body certification records, hospital procurement contract filings, and polymer trade flow customs data. Bottom-up demand modeling from end-user segment procurement volumes triangulated against top-down supply-side capacity assessments across medical-grade silicone and PVC compounding corridors.
Variance decomposition across product type, patient age category, material substrate, and end-user care setting anchored the analytical framework throughout the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing tier concentration and regulatory pathway timelines. Forecast inputs incorporated ISO 10993 biocompatibility validation cycle lengths, REACH Annex XVII implementation phases, and METI hospital modernization program disbursement patterns.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR notified body operations, and Japan PMDA alignment with international standards; material policy shifts would require re-modeling. Specific risks include extended CE-marking timelines from notified body capacity constraints, Asian petrochemical corridor supply disruptions, and accelerated high-flow nasal cannula substitution in intermediate care wards. Recalibration cycles align with material shifts in polymer regulation enforcement, GPO contract award announcements, and heated humidification bundling adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Coating Market
Medical Devices
China Anesthesia Devices Market
Medical Devices
Global Bone Cement Delivery System Market
Medical Devices
Surgical Integration Systems Market
Medical Devices
Electric Handpiece Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Polyethersulfone Dialyzer Market
Medical Devices
Sinus Irrigation Systems Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Photopheresis Products Market
Medical Devices
Cervical Implants Market
Medical Devices
Global Radial Artery Compression Devices Market