
 ADA Substitute Market | 2026-2036
ADA Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
ADA Substitute Market Analytics
Multi-source procurement for enzymatic and botanical alternatives is recalibrating supply economics across the bakery sector. DowDuPont leverages its industrial biotechnology platform to secure fermentation-derived solutions at scale. Kerry Group anchors its position through integrated flavor-mask systems that offset off-notes in stevia formulations. DSM competes on vitamin-adjacent positioning, bundling nutritional fortification with ADA replacement claims.
ADA substitutes encompass non-azo bleaching and conditioning agents—principally ascorbic acid, L-cysteine, and enzyme blends such as glucose oxidase and lipoxygenase—that restore dough elasticity and crumb structure without nitrogen-bearing off-gassing residues. These replacements must match ADA's oxygen-scavenging functionality at 20-45 ppm equivalent dosing to maintain commercial bake consistency. Among product types, natural sweeteners and stevia extract the strongest price premiums as clean-label bakery demand outpaces supply of high-Reb-A cultivars. Powder formulations dominate industrial channels for dry-mix integration, while liquid concentrates gain traction in beverage applications where solubility and dosing precision matter most.
FDA's continued azodicarbonamide monitoring under food additive regulations, coupled with EFSA's re-evaluation of respiratory sensitization risks, compels reformulation investments across multinational portfolios. India's FSSAI has signaled alignment with Codex standards on bleaching agent limits, tightening market access for legacy ADA suppliers. Stakeholders must track evolving enzymatic cost curves against botanical extract volatility, as the margin-optimal substitution pathway hinges on crop yield stability and bioprocess yield improvements rather than regulatory deadlines alone.
Market Dynamics
Enzymatic processing platforms are compressing cost differentials between synthetic ADA and biological alternatives, forcing incumbent suppliers to defend margin positions through fermentation yield improvements rather than regulatory lobbying alone.
Growth Catalysts
- FDA azodicarbonamide residue scrutiny:Tighter monitoring under food additive regulations compels commercial bakeries to accelerate reformulation timelines for clean-label bread lines.
- Enzyme blend functionality:Glucose oxidase and lipoxygenase combinations now match ADA's oxygen-scavenging performance at industrial dosing scales, removing technical barriers to substitution.
- Retailer clean-label mandates:US grocery chains are conditioning shelf access on verified ADA-free formulations, transmitting consumer preference directly upstream to ingredient procurement.
Market Restraints
- Stevia cultivar supply concentration:High-Reb-A stevia varieties remain concentrated in specific growing regions, exposing price volatility to climatic yield fluctuations.
- EFSA respiratory sensitization protocols:Extended re-evaluation timelines for bleaching agent alternatives delay product registration and commercial deployment across European markets.
- Fermentation capacity bottlenecks:Industrial-scale bioprocess infrastructure for enzymatic substitutes remains concentrated among limited contract manufacturing networks.
Strategic Opportunities
- India FSSAI alignment with Codex:Emerging market regulatory harmonization creates first-mover advantage for ADA substitute suppliers establishing local formulation partnerships.
- Flavor-mask system bundling:Integrated off-note suppression technologies enable premium positioning for stevia-based sweeteners in sensory-sensitive applications.
- Liquid concentrate channel expansion:Solubility-optimized formats penetrate beverage manufacturing segments previously inaccessible to powder-based conditioning agents.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise remains concentrated in pharmaceutical and industrial biotechnology sectors, constraining bakery ingredient supplier hiring pipelines.
- Legacy equipment recalibration:Dry-mix integration protocols require reformulation of established dosing systems originally optimized for azodicarbonamide particle distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ADA Substitute Market |
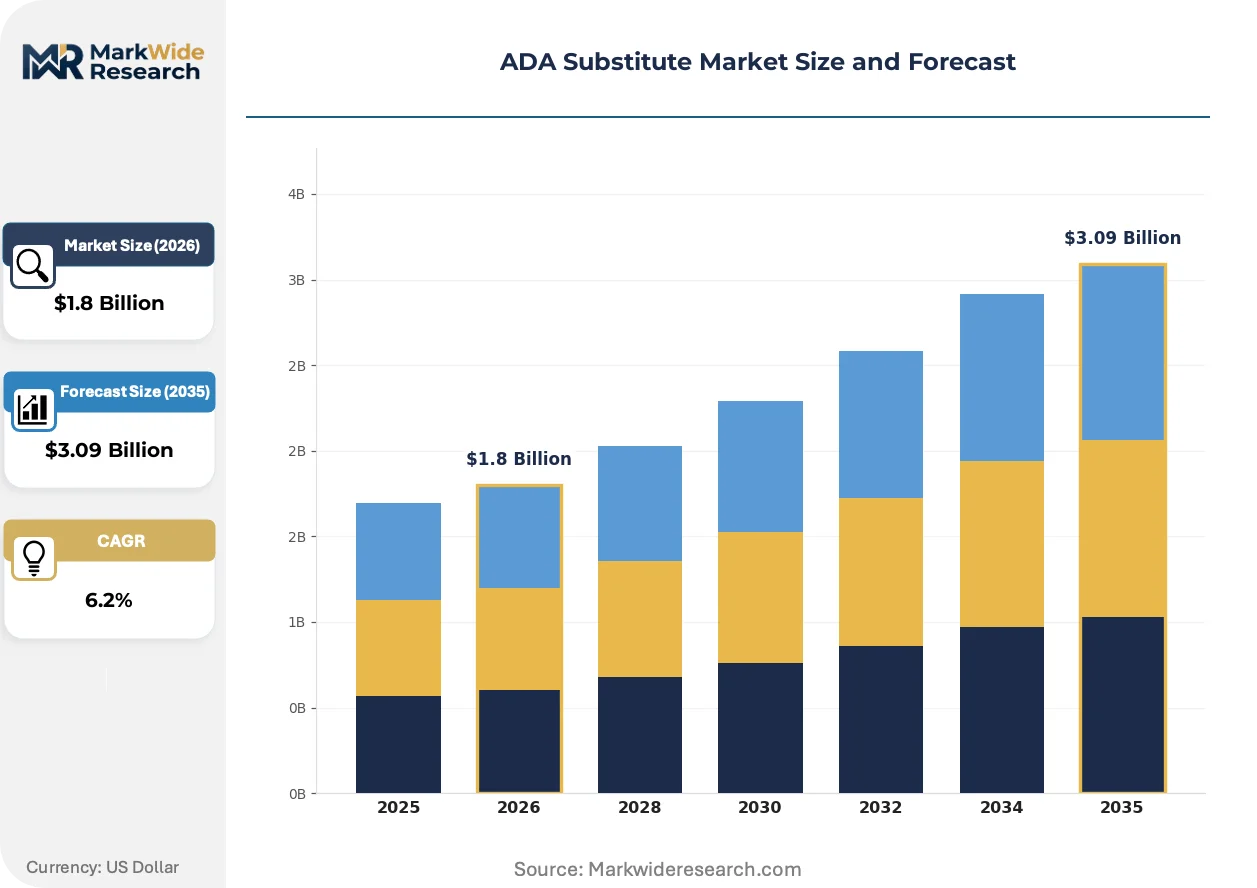
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.09 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugar Alcohols, Natural Sweeteners, Artificial Sweeteners, Stevia Application: Beverages, Bakery Products, Confectionery, Dairy Form: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants |
| Companies Covered | DowDuPont, ADM, DSM, Kerry Group, PAK Group, Calpro Specialities Pvt. Ltd., Gum Technology, Inc., Puratos Bakery Supply, Inc., JK Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADA Substitute Market Evolving Landscape
Biological processing methods are displacing chemical synthesis across dough conditioning applications, with enzymatic platforms capturing formulation share from legacy azo compounds through superior label transparency and equivalent functional performance.
Fermentation-derived ascorbic acid is decentralizing supply geography for commercial baking operations. Regional bioreactor installations in North America and Europe reduce dependency on concentrated chemical manufacturing hubs. Mid-cap bakery ingredient distributors are securing captive fermentation capacity through toll manufacturing agreements rather than asset-heavy vertical integration.
EFSA's re-evaluation of respiratory sensitization risks for nitrogen-bearing bleaching agents is compressing registration timelines for enzymatic alternatives. Commercial bakeries in Germany and France are pre-qualifying glucose oxidase formulations ahead of anticipated restriction schedules. The regulatory uncertainty is accelerating dual-track formulation development across multinational bread portfolios.
Clean-label procurement specifications are consolidating buyer power among US retail grocery chains. Category managers are unbundling ingredient certification from traditional supplier relationships, creating direct contracting channels with enzymatic ingredient specialists. This disintermediation is most pronounced in private-label bread programs where margin pressure amplifies reformulation urgency.
ADA Substitute Market Segmentation
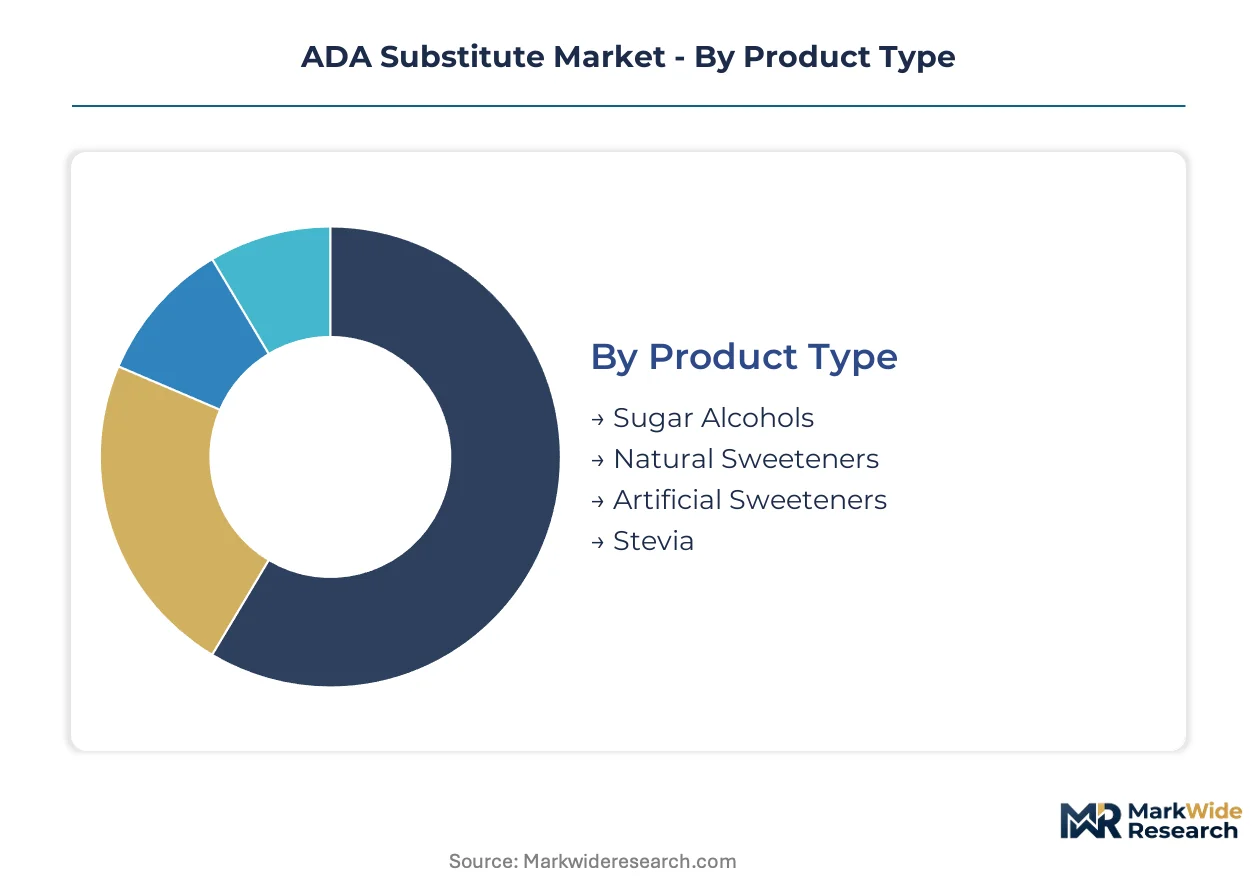
ADA substitute segmentation reveals divergent growth trajectories across functional categories. Sweetener chemistry and delivery format choices determine reformulation economics for commercial bakeries navigating clean-label mandates.
Product Type:
Volume concentrates in commodity sugar alcohols while premium pricing accrues to botanical extracts with superior sensory profiles.
- Stevia:High-Reb-A glycoside extracts command the strongest price premiums in clean-label bakery applications. Demand concentrates in US private-label bread programs where retailer mandates eliminate synthetic alternatives entirely.
- Natural Sweeteners:Monk fruit and thaumatin extracts serve sensory-sensitive formulations requiring minimal off-notes. European confectionery manufacturers prioritize these for premium chocolate lines facing EFSA scrutiny on artificial additive residues.
- Sugar Alcohols:Erythritol and xylitol provide bulk sweetness at intermediate cost positions for mass-market reformulations.
- Artificial Sweeteners:Sucralose and acesulfame potassium retain residual volume in cost-optimized beverage applications with less stringent clean-label requirements.
Today's leader: Sugar Alcohols. Tomorrow's challenger: Stevia.
Application:
Reformulation urgency varies sharply by processing temperature and moisture content requirements.
- Bakery Products:Bread and roll manufacturers face the most acute substitution pressure as FDA azodicarbonamide monitoring tightens. Glucose oxidase enzyme blends now match ADA's oxygen-scavenging performance at 20-45 ppm equivalent dosing.
- Beverages:Liquid concentrate formats penetrate carbonated and still drink manufacturing where solubility and dosing precision override cost considerations. High-Reb-A stevia extracts gain traction in reduced-sugar formulations.
- Confectionery:Hard candy and chewing gum applications favor heat-stable sugar alcohols over thermally degradable botanical extracts.
- Dairy:Yogurt and flavored milk processors balance clean-label positioning against fermentation compatibility constraints.
Bakery Products anchors current procurement volumes. Beverages represents the steepest expansion trajectory as liquid concentrate technology matures.
Form:
Industrial integration protocols favor dry formats while beverage manufacturing demands solubility-optimized solutions.
- Powder:Dry-mix integration dominates bakery ingredient channels where established dosing systems require minimal recalibration. Particle distribution engineering matches legacy azodicarbonamide handling equipment.
- Liquid:Concentrate formats penetrate beverage manufacturing segments previously inaccessible to powder-based conditioning agents. Solubility optimization enables precise dosing in high-speed bottling operations.
- Granular:Intermediate particle sizing serves tabletop and small-batch foodservice applications requiring visual sweetness cues.
- Tablet:Unit-dose formats address foodservice and institutional procurement with portion control requirements.
Powder retains manufacturing scale advantages. Liquid concentrates are gaining share fastest in beverage channel expansion.
End User:
Procurement authority is consolidating downstream as retailer clean-label specifications disintermediate traditional supplier relationships.
- Food Manufacturers:Commercial bakeries drive enzymatic alternative adoption through direct contracting with fermentation specialists. DowDuPont and Kerry Group secure formulation partnerships bypassing legacy ingredient distributors.
- Beverage Companies:Carbonated and functional drink processors prioritize solubility-optimized stevia extracts for reduced-sugar line extensions.
- Retailers:US grocery chains condition shelf access on verified ADA-free formulations, transmitting consumer preference directly upstream to ingredient procurement decisions.
- Restaurants:Foodservice operators lag in substitution adoption due to equipment recalibration costs and menu standardization constraints across franchise networks.
Food Manufacturers dominate current enzymatic procurement. Retailers are emerging as the decisive demand shaper through specification unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial bakeries in the United States drive enzymatic reformulation investment as FDA azodicarbonamide monitoring intensifies. Regional procurement patterns diverge sharply between mature clean-label markets and emerging regulatory harmonization zones.
United States
Private-label bread programs at Kroger and Albertsons mandate verified ADA-free formulations, transmitting retailer specifications directly to ingredient procurement teams. FDA residue scrutiny under food additive regulations compels commercial bakeries to accelerate enzyme blend adoption. Chicago and Minneapolis industrial baking clusters now standardize glucose oxidase dosing at 20-45 ppm equivalents.
Germany
EFSA respiratory sensitization re-evaluations compress registration timelines for nitrogen-bearing bleaching agents. Munich and Stuttgart industrial baking operations pre-qualify enzymatic alternatives ahead of anticipated restriction schedules. The country's federal food safety authority aligns with EU-wide clean-label procurement standards for multinational bread portfolios.
France
Premium chocolate and confectionery manufacturers prioritize monk fruit extracts for sensory-sensitive formulations facing EFSA artificial additive scrutiny. Paris-based ingredient distributors consolidate supply relationships with fermentation-derived ascorbic acid specialists. Lyon industrial zones witness accelerated dry-mix recalibration for legacy dosing equipment.
India
FSSAI signals alignment with Codex standards on bleaching agent limits, tightening market access for legacy ADA suppliers. Mumbai and Ahmedabad commercial bakeries pilot enzyme blend integration through toll manufacturing partnerships. The regulator's draft notifications create first-mover positioning for substitute suppliers establishing local formulation networks.
China
Domestic baking ingredient manufacturers expand fermentation capacity for ascorbic acid production targeting export certification. Shanghai and Guangzhou industrial clusters adopt dual-track formulation development to serve both domestic and EU-compliant product lines. SAMR food additive standards increasingly reference international clean-label benchmarks.
ADA Substitute Market Competitive Landscape
Global majors compete with regional champions across enzymatic technology platforms and fermentation capacity deployment. Market structure consolidates around three tiers: diversified biotechnology conglomerates with industrial-scale fermentation infrastructure, mid-cap ingredient specialists bundling flavor-mask systems, and regional distributors securing captive toll manufacturing agreements. Strategic archetypes include integrated bioprocess platforms, sensory-optimization specialists, and emerging market formulation partners. Dominant competitive moves encompass fermentation yield improvements and direct retailer contracting channels that bypass legacy distributor relationships.
Within the integrated biotechnology tier, DowDuPont and DSM exemplify industrial-scale fermentation platform operators. Kerry Group occupies a position among sensory-optimization specialists, anchoring competitive positioning through integrated flavor-mask capabilities. Among Asia-Pacific regional players, Calpro Specialities Pvt. Ltd. represents emerging market formulation partnership archetypes.
| Leading Market Players |
|---|
| DowDuPont |
| ADM |
| DSM |
| Kerry Group |
| PAK Group |
| Calpro Specialities Pvt. Ltd. |
| Gum Technology, Inc. |
| Puratos Bakery Supply, Inc. |
| JK Ingredients |
| Others |
Value Network & Pricing Analysis
US retail grocery chains now dominate procurement authority, compressing supplier margins through unbundled certification requirements and direct enzymatic ingredient contracting. This buyer concentration forces tiered pricing stratification across clean-label grade tiers, with high-Reb-A stevia extracts commanding substantial premiums over commodity sugar alcohols.
Pricing Analysis
Input-cost pass-through from high-Reb-A stevia cultivar scarcity anchors premium tier positioning, while fermentation-derived ascorbic acid and enzyme blends compete at intermediate price points. Price differentiation rests on Reb-A glycoside purity certification and organic cultivation status rather than functional performance alone. Pricing pressure intensifies in the sugar alcohol segment as Chinese fermentation capacity expansion erodes erythritol and xylitol margins. Mass-market bread manufacturers exhibit highest price sensitivity, whereas premium confectionery and private-label organic lines absorb botanical extract premiums with minimal volume elasticity.
Supply Chain Analysis
Certification and qualification gating through FDA food additive petitions and EFSA novel food approvals constrains supplier entry and concentrates viable sourcing among pre-qualified enzymatic specialists. Fermentation capacity concentrates in China, the United States, and India, with high-Reb-A stevia leaf supply anchored in Paraguay, China, and Kenya. Raw material dependencies include corn-derived glucose feedstocks, specialized yeast strains for ascorbic acid production, and stevia cultivar germplasm. Single-source vulnerability in high-Reb-A genetics exposes price volatility to climatic yield fluctuations. Distribution runs through integrated ingredient distributors and direct retailer contracting channels that disintermediate legacy bakery supply relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where clean-label specification tightening now separates viable suppliers from commodity players. Premium bakery and beverage procurement has shifted decisively toward verified ADA-free enzymatic and botanical alternatives with full supply chain transparency.
For Market Incumbents: Anticipate margin compression from Chinese fermentation capacity expansion by securing captive high-Reb-A stevia supply through backward integration into Paraguayan and Kenyan cultivation partnerships. Defend positioning through integrated flavor-mask system bundling that offsets off-notes in stevia formulations, creating switching costs for sensory-sensitive bakery applications. For New Entrants and Emerging Players: Enzymatic toll manufacturing partnerships with underutilized pharmaceutical fermentation infrastructure offer the most penetrable entry vector. Target Indian FSSAI pre-qualification status ahead of Codex-aligned bleaching agent restrictions, establishing local formulation networks before multinational incumbents complete regional capacity deployment. Lead with glucose oxidase-lipoxygenase blend functionality demonstrations at industrial bakeries facing immediate FDA reformulation deadlines. For Investors and Strategic Acquirers: Food and beverage conglomerates with stranded legacy ingredient portfolios are the most active acquirer in this space, seeking enzymatic capabilities to retrofit existing bakery supply relationships. Over a five-to-ten-year horizon, fermentation yield improvement trajectories and stevia cultivar breeding programs determine competitive viability more than regulatory deadlines alone. Monitor EFSA respiratory sensitization protocol finalization as the critical inflection signal for European market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Industrial-scale bioreactor deployment in North America reduces dependency on concentrated Chinese manufacturing hubs. |
| Flavor-Mask System Integration | Kerry Group's bundled off-note suppression creates switching costs for sensory-sensitive clean-label bakery applications. |
| High-Reb-A Cultivar Development | Proprietary stevia germplasm programs in Paraguay and Kenya secure premium raw material supply against climatic volatility. |
| Direct Retailer Contracting | Kroger and Albertsons private-label mandates disintermediate legacy ingredient distributors for enzymatic procurement. |
| Regulatory Pre-Qualification | EFSA novel food approval and FDA food additive petition status gates European and US market access for new entrants. |
Research Methodology
Multiple input streams — primary interviews with bakery procurement directors, fermentation technology specialists, and retail category managers; secondary validation through FDA food additive petitions, EFSA scientific opinions, and FSSAI draft notifications; trade data from customs records and industrial biotechnology capacity databases — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Cross-referencing historical enzyme adoption curves against panel input from commercial bakery R&D executives established the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application heat-stability requirements, form factor solubility specifications, and end-user procurement authority concentration. CAGRs were derived from enzymatic cost curve compression trajectories and stevia cultivar yield improvement assumptions, with sensitivity analysis around EFSA regulatory timeline uncertainty and Chinese fermentation capacity expansion rates.
The model holds under stable regulatory enforcement schedules and intact crop yield patterns; deviation in EFSA respiratory sensitization protocol stringency or prolonged drought in Paraguayan stevia cultivation zones would shift volume trajectories materially. A model refresh is warranted upon material change in FSSAI final rulemaking or major fermentation yield breakthrough announcements from industrial biotechnology platforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Urinary Sphincters Market
Medical Devices
Liposuction Devices Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Global Female Stress Urinary Incontinence Treatment Devices Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Bronchial Thermoplasty Catheter Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Bone-Cutting Technologies Market
Medical Devices
Light Therapy Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Intrapartum Monitors Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market