
 Retractable Needle Safety Syringes Market | 2026-2036
Retractable Needle Safety Syringes Market Size, Share, and Industry Trends Forecast 2026-2036
Retractable Needle Safety Syringes Market Outlook
Hospital procurement of retractable needle safety syringes is consolidating around integrated health systems with centralized purchasing power. Becton, Dickinson and Company leverages its scale across North American hospital networks to sustain contract dominance. Retractable Technologies, Inc. competes through specialized automatic retraction patents that differentiate its product from conventional safety mechanisms. Terumo Corporation anchors Asian supply chains with manufacturing depth across multiple polymer and metal component tiers.
Retractable needle safety syringes incorporate spring-loaded or manually activated mechanisms that withdraw needles into barrel housings after injection, typically using polycarbonate or polypropylene barrels with stainless steel cannulas to prevent post-use needlestick exposure. The primary commercial purpose centers on protecting healthcare workers from bloodborne pathogen transmission during injection procedures. Automatic retractable variants command premium positioning due to single-hand activation and reduced failure rates in high-stress clinical environments. Hospitals represent the dominant end-user segment with concentrated volume contracting, while home care applications show structural growth as self-injection therapies expand beyond traditional clinical settings.
FDA 510(k) clearance requirements and OSHA Bloodborne Pathogens Standard enforcement shape product validation timelines and design specifications for US market entry. The EU Medical Device Regulation and CE marking framework impose additional clinical evidence requirements that filter manufacturer participation across European markets. Stakeholders must monitor evolving sharps safety legislation in major procurement jurisdictions to align R&D investment with compliance-driven replacement cycles.
Market Dynamics
Hospital procurement consolidation and OSHA Bloodborne Pathogens Standard enforcement are compressing supplier margins while accelerating automatic retractable syringe adoption across integrated health systems.
Growth Catalysts
- OSHA Bloodborne Pathogens Standard:Mandatory needlestick prevention protocols in US healthcare facilities drive replacement of conventional syringes with safety-engineered alternatives.
- Polycarbonate barrel materials:Enhanced durability and clarity properties enable single-use retractable designs that withstand high-pressure injections without component failure.
- Integrated health system contracting:Centralized purchasing by multi-hospital networks creates volume aggregation that favors suppliers with scalable automatic retraction manufacturing.
Market Restraints
- Stainless steel cannula cost volatility:Medical-grade needle metal pricing fluctuations compress margins for manufacturers locked into fixed-price hospital contracts.
- German manufacturing concentration:European supply chains cluster around B. Braun Melsungen AG and Henke-Sass, Wolf GmbH production facilities, creating geographic single-source vulnerability.
- Manual retraction substitution:Lower-cost passive safety mechanisms compete for budget-constrained ambulatory care segments where automatic systems face price resistance.
Strategic Opportunities
- Home care self-injection expansion:Diabetes and biologic therapy patients outside clinical settings create demand for patient-activated retractable syringes with simplified activation.
- EU Medical Device Regulation clinical evidence pathways:MDR Article 61 requirements for post-market surveillance data create competitive moats for manufacturers with established clinical documentation.
- Spring-loaded mechanism miniaturization:Convergence of precision metal stamping and polymer micro-molding enables compact retractable designs for subcutaneous injection volumes below 0.5mL.
Industry Challenges
- FDA 510(k) clearance timelines:Predicate device identification and substantial equivalence documentation extend product launch schedules by 12-18 months for novel retraction mechanisms.
- Polymer supply chain reconfiguration:Medical-grade polypropylene resin qualification requirements limit rapid supplier switching when primary resin producers face allocation constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retractable Needle Safety Syringes Market |
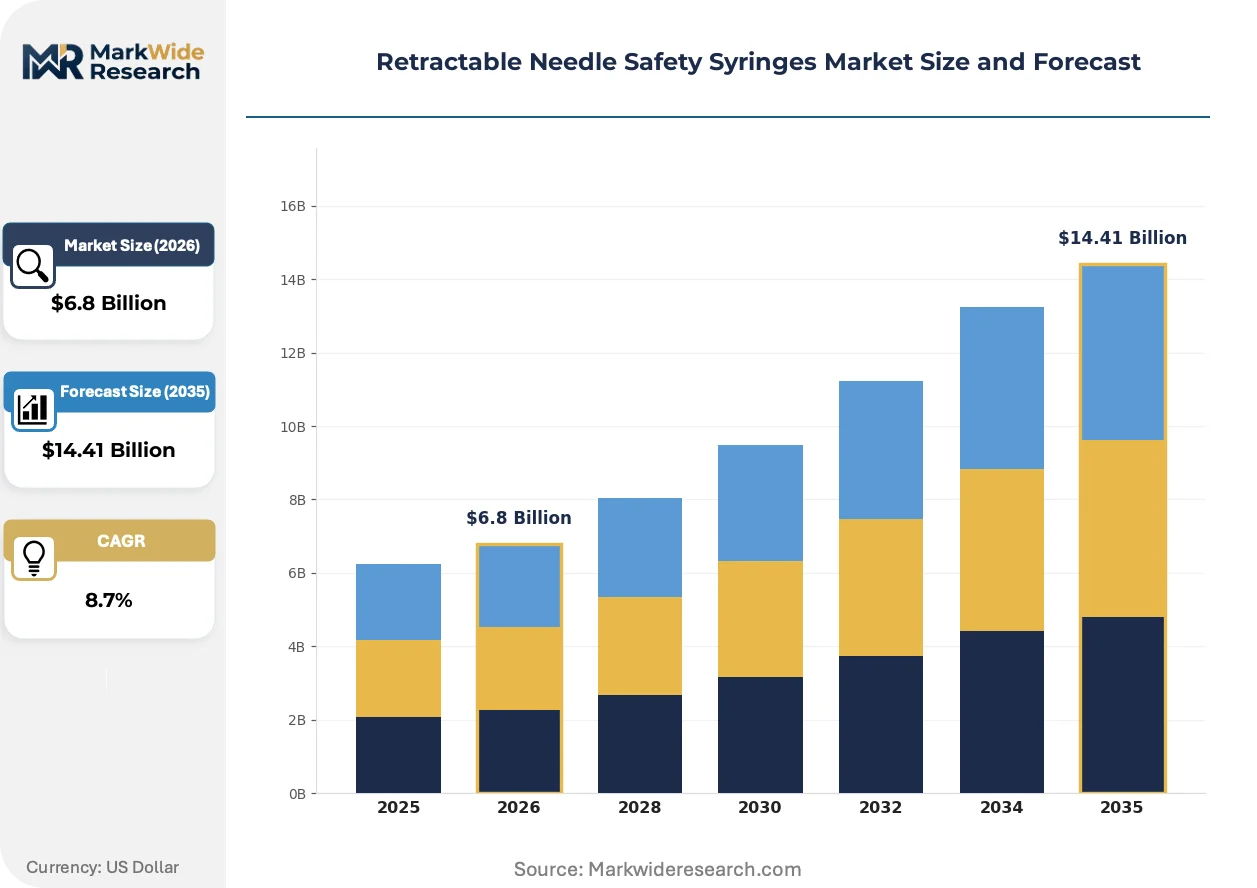
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Retractable, Automatic Retractable, Safety Mechanism, Needleless End User: Hospitals, Clinics, Home Care, Research Laboratories Delivery Mode: Subcutaneous Injection, Intravenous Injection, Intramuscular Injection, Vaccination Material: Plastic, Stainless Steel, Glass, Polycarbonate |
| Companies Covered | Becton, Dickinson and Company, Retractable Technologies, Inc., Terumo Corporation, Nipro Corporation, Medtronic plc, Smiths Medical, B. Braun Melsungen AG, Henke-Sass, Wolf GmbH, DMC Medical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retractable Needle Safety Syringes Market Strategic Shifts
Automatic retraction mechanisms are displacing passive safety designs as OSHA enforcement tightens and hospital risk management departments prioritize fail-safe needlestick prevention over unit cost minimization.
Dual-chamber prefilled retractable syringes are expanding into oncology and autoimmune therapeutic categories where biologic drugs require reconstitution immediately before injection. Major pharmaceutical packagers are adopting these systems for high-value monoclonal antibodies where contamination risk and dosing precision outweigh premium pricing. This format is expanding into chronic disease management protocols previously served by conventional vial-and-syringe workflows.
The EU Medical Device Regulation's enhanced clinical evidence requirements are filtering manufacturer participation across European markets. CE marking technical documentation now demands post-market clinical follow-up studies that smaller manufacturers cannot fund, consolidating notified body relationships among established suppliers. German hospital procurement networks are responding by tightening pre-qualification criteria to exclude manufacturers without MDR-certified quality management systems.
Centralized procurement by US integrated delivery networks is compressing distributor margins and forcing direct manufacturer contracting. Group purchasing organizations are losing influence as single-source agreements with automatic retractable specialists replace multi-vendor formularies. This concentration is most visible in California and Texas health systems where Kaiser Permanente and HCA Healthcare have consolidated injection device specifications across hundreds of facilities.
Retractable Needle Safety Syringes Market Segmentation
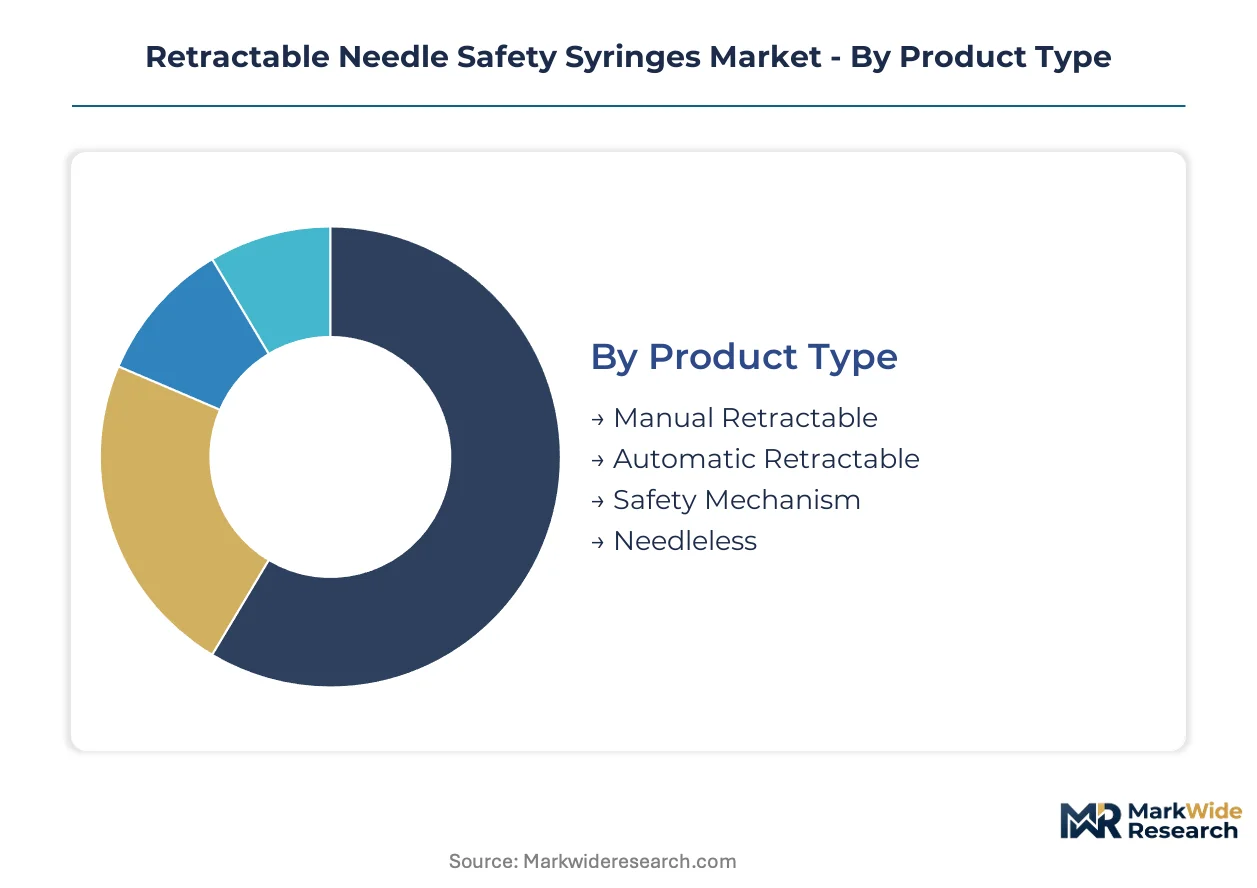
Segmentation reveals how procurement priorities diverge across clinical settings and material specifications. Each dimension captures distinct upgrade cycles driven by regulatory enforcement and risk management mandates.
Product Type:
Replacement cycles accelerate where OSHA compliance deadlines force obsolescence of legacy designs.
- Automatic Retractable:Spring-loaded mechanisms withdraw needles into barrel housings immediately post-injection without user activation. Hospital systems in California and Texas favor these for high-stress emergency departments where single-hand operation reduces failure rates. OSHA Bloodborne Pathogens Standard enforcement tightens specification requirements.
- Manual Retractable:Thumb-activated or plunger-triggered designs require deliberate user engagement to sheath needles. Budget-constrained ambulatory clinics in rural US markets select these for lower per-unit cost despite higher training burdens. Price resistance limits penetration in integrated health networks.
- Safety Mechanism:Passive shields and hinged caps that deploy without user action. These occupy transitional procurement tiers where automatic systems face cost barriers but conventional syringes no longer satisfy compliance.
- Needleless:Jet injection and microneedle array systems eliminate cannula exposure entirely. Vaccination campaigns and mass immunization programs pilot these for population-scale deployment.
Volume placements concentrate in Automatic Retractable; the faster expansion belongs to Needleless.
End User:
Customer concentration patterns reflect reimbursement structures and liability exposure thresholds.
- Hospitals:Multi-facility health systems wield centralized purchasing power to mandate automatic retractable specifications across emergency, surgical, and inpatient units. Kaiser Permanente and HCA Healthcare networks drive standardization through single-source agreements.
- Clinics:Federally qualified health centers and independent physician practices balance OSHA compliance against per-procedure economics. Manual retractable systems dominate where patient volumes fail to justify premium automatic pricing.
- Home Care:Diabetes and autoimmune therapy patients self-inject outside clinical supervision. Simplified activation mechanisms and patient training protocols reshape product design requirements for this expanding segment.
- Research Laboratories:Preclinical and clinical trial operations require documented needlestick prevention for occupational health compliance. Protocol standardization across multi-site studies favors retractable systems with activation verification.
Procurement authority concentrates in Hospitals; Home Care claims the steepest expansion trajectory as biologic therapies shift to patient-administered regimens.
Delivery Mode:
Injection depth and viscosity requirements dictate barrel pressure tolerances and retraction force specifications.
- Subcutaneous Injection:Shallow tissue penetration with low-resistance formulations. Retractable designs for insulin and GLP-1 agonists emphasize compact profiles and minimal dead space.
- Intravenous Injection:Direct vascular access demands secure connection integrity and controlled retraction timing. Oncology and critical care applications prioritize fail-safe mechanisms.
- Intramuscular Injection:Higher volume and viscosity loads require reinforced polycarbonate barrels. Vaccination and long-acting antipsychotic depot formulations stress-test automatic retraction reliability.
- Vaccination:Mass immunization campaigns drive demand for single-dose prefilled retractable formats. Public health procurement emphasizes cold chain compatibility and activation simplicity.
Specification intensity peaks with Intravenous Injection; Vaccination scales most rapidly through pandemic preparedness stockpiling.
Material:
Supply chain qualification constraints limit rapid formulation switching when primary resin producers face allocation pressures.
- Polycarbonate:High clarity and impact resistance enable thin-wall barrel designs that withstand autoclave sterilization. German manufacturers anchor European supply for premium hospital-grade specifications.
- Stainless Steel:Medical-grade cannula material with precise grind geometry for penetration performance. Metal pricing volatility compresses margins under fixed-price hospital contracts.
- Plastic:Polypropylene homopolymer and copolymer formulations balance cost and chemical resistance. Volume applications in disposable vaccination syringes favor this material tier.
- Glass:Prefilled syringe formats for sensitive biologics requiring inert contact surfaces. Oncology and monoclonal antibody therapies specify borosilicate barrels with integrated retractable plunger systems.
Procurement volume clusters in Plastic; Glass gains share fastest as pharmaceutical packagers adopt prefilled retractable formats for high-value biologics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement concentrates in the United States, Germany, and Japan where occupational safety regulations and integrated health system purchasing power reshape supplier relationships. Manufacturing clusters in these markets anchor regional supply chains while emerging Asian production centers capture volume growth.
United States
Integrated delivery networks Kaiser Permanente and HCA Healthcare mandate automatic retractable specifications across hundreds of facilities. OSHA Bloodborne Pathogens Standard enforcement tightens compliance deadlines for needlestick prevention protocols. California and Texas health systems drive standardization through single-source contracting with automatic retraction specialists.
Germany
B. Braun Melsungen AG and Henke-Sass, Wolf GmbH anchor substantial manufacturing capacity for European hospital networks. EU Medical Device Regulation clinical evidence requirements filter manufacturer participation through post-market surveillance mandates. The Melsungen and Tuttlingen industrial clusters concentrate precision metal stamping and polymer molding for premium hospital-grade specifications.
Japan
Terumo Corporation leverages manufacturing depth across multiple polymer and metal component tiers to serve Asian supply chains. PMDA regulatory frameworks align with international sharps safety standards for domestic and export markets. Tokyo-Osaka industrial corridors host integrated production facilities serving oncology and vaccination applications.
China
Domestic hospital procurement expands safety-engineered syringe adoption as NMPA harmonizes with international needlestick prevention standards. Medical device registration pathways accelerate for manufacturers with established predicate device documentation. Yangtze River Delta manufacturing bases scale polycarbonate barrel and stainless steel cannula production for regional and export demand.
India
Federally qualified health centers and government immunization programs drive volume procurement of cost-optimized retractable designs. CDSCO medical device rules impose quality management system requirements that consolidate supplier relationships. Gujarat and Maharashtra industrial zones expand injection molding capacity for disposable vaccination syringes.
Retractable Needle Safety Syringes Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue patient-activated home care formats and miniaturized subcutaneous delivery systems. The vendor base stratifies across three tiers: multinational health system contractors with integrated manufacturing, regional specialists with automatic retraction patents, and emerging Asian fabricators serving price-sensitive procurement channels. Dominant competitive moves include direct hospital contracting that bypasses traditional distribution and precision metal stamping investments that enable compact spring-loaded mechanism production.
Among US-based health system contractors, Becton, Dickinson and Company and Retractable Technologies, Inc. exemplify contrasting archetypes—scale-driven integrated manufacturing versus specialized patent-protected automatic retraction. German producers B. Braun Melsungen AG and Henke-Sass, Wolf GmbH occupy positions as European supply chain anchors with concentrated production in Melsungen and Tuttlingen. Terumo Corporation represents the Asian manufacturing depth archetype with multi-tier component integration.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Retractable Technologies, Inc. |
| Terumo Corporation |
| Nipro Corporation |
| Medtronic plc |
| Smiths Medical |
| B. Braun Melsungen AG |
| Henke-Sass, Wolf GmbH |
| DMC Medical Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU Medical Device Regulation Article 61 post-market surveillance mandates gate qualified supply access and premium-tier pricing for retractable needle safety syringes, filtering manufacturer participation to those with documented clinical evidence and certified quality management systems. Hospital procurement consolidation across integrated health systems amplifies this bifurcation, concentrating volume contracting among MDR-compliant suppliers while excluding smaller competitors from premium pricing tiers.
Pricing Analysis
High-volume automatic retractable contracts for integrated health systems trade margin for lock-in, while specialized patient-activated formats for home care command premium positioning. Price differentiation hinges on FDA 510(k) clearance tier and single-source GPO contract status. Pricing pressure stems from stainless steel cannula cost volatility under fixed-price hospital agreements. Federally qualified health centers exhibit acute price sensitivity, whereas Kaiser Permanente and HCA Healthcare networks prioritize fail-safe activation over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle integrated delivery network demand, bypassing traditional distribution tiers for automatic retractable specifications. Manufacturing concentrates in Germany, the United States, and Japan, with B. Braun Melsungen AG and Terumo Corporation anchoring regional capacity. Supply chains draw from medical-grade polycarbonate resin and precision-stamped spring components. Single-source vulnerability in German production clusters creates geographic concentration risk. Distribution runs through manufacturer-direct contracting with centralized hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade polypropylene resin qualification constraints limit rapid supplier switching, propping pricing power for qualified manufacturers with established polymer supply relationships and hospital contract lock-in.
For Market Incumbents: Anchor automatic retraction patent portfolios through precision metal stamping investments in compact spring-loaded mechanisms. Defend hospital contract positions by securing MDR-certified quality management systems ahead of European procurement pre-qualification tightening. Capacity addition in Yangtze River Delta manufacturing bases counters German supply concentration vulnerability. For New Entrants and Emerging Players: Launch via patient-activated formats targeting home care self-injection expansion, where simplified activation mechanisms face less entrenched incumbent presence. Diabetes and biologic therapy patients outside clinical settings represent the most penetrable segment. Direct-to-patient training protocols differentiate against hospital-focused automatic systems. For Investors and Strategic Acquirers: FDA 510(k) clearance timeline extensions for novel retraction mechanisms are the leading indicator that patent-protected automatic retraction specialists will command scarcity premiums. Five-to-ten year viability favors manufacturers with predicate device documentation and established clinical evidence pathways. Watch for CDSCO quality management system enforcement consolidating Indian supplier relationships as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Quality Management Certification | Post-market surveillance compliance unlocks German hospital network procurement access. |
| Precision Metal Stamping Investment | Spring-loaded miniaturization enables sub-0.5mL subcutaneous injection formats. |
| Direct Hospital System Partnership | Single-source agreements with Kaiser Permanente bypass distributor margin compression. |
| Patient-Activated Home Care Launch | Simplified self-injection designs capture biologic therapy patient-administered regimens. |
| Dual-Chamber Prefilled Development | Oncology monoclonal antibody packagers adopt reconstitution-ready retractable formats. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU MDR technical documentation requirements, and OSHA enforcement records, complemented by interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at automatic retraction specialists. Secondary sources included hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, delivery mode, and material segmentation dimensions.
Unit shipment and revenue outputs derived from analytical framework modeling across the projection horizon, with automatic retractable, manual retractable, safety mechanism, and needleless product types cross-referenced against hospital, clinic, home care, and research laboratory end users. CAGRs were computed from year-over-year growth trajectory analysis. Forecast inputs incorporated polycarbonate barrel pricing indices and stainless steel cannula cost volatility assumptions.
Regulatory timeline delays, polymer supply allocation constraints, and hospital procurement consolidation acceleration are the dominant revision risks for forecast outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
South Africa Hospital Supplies Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Bile Collection Bags Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Diagnostic Vials Market
Medical Supplies
Swabs Collection Kit Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Europe Insulin Syringe Market
Medical Supplies
Global Surgical Pledgets Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Global Absorbent Dressings Market
Medical Supplies
MENA Syringes and Cannula Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
Asia-Pacific Syringe Market