
 Wireless Handheld Ultrasound Devices Market | 2026-2036
Wireless Handheld Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Handheld Ultrasound Devices Market Insights
Semiconductor foundry capacity in South Korea is hardening as a bottleneck for CMUT and piezoelectric transducer supply. GE HealthCare leverages captive sensor partnerships to secure wafer allocations ahead of consumer electronics buyers. Butterfly Network competes through single-probe architecture that collapses manufacturing complexity into one MEMS-fabricated element. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors Asia-Pacific production with vertically integrated probe assembly lines in Guangdong province.
Wireless handheld ultrasound devices combine miniaturized transducer arrays, low-power beamforming ASICs, and Wi-Fi or Bluetooth data transmission to generate real-time B-mode, M-mode, and Doppler images without a tethered console. These instruments typically operate at 2-15 MHz with 128-element phased arrays, delivering diagnostic-grade imaging for bedside triage, interventional guidance, and remote consultation where cart-based systems prove impractical. Pocket-sized devices and handheld scanners dominate unit shipments, though margin pools concentrate in battery-powered units with extended wireless range and rapid-charge protocols. Emergency services and clinics represent the fastest-growing end-user channels, driven by reimbursement alignment for point-of-care cardiovascular assessment and musculoskeletal imaging protocols.
FDA 510(k) premarket notification requirements govern device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for wireless connectivity features classified as active therapeutic devices. Japan's PMDA enforces JIS T 0601-1 electrical safety standards that manufacturers must satisfy before METI grants market authorization. Stakeholders must monitor how AI-enabled diagnostic algorithms trigger new software validation requirements across these jurisdictions, as regulatory divergence in digital health oversight will determine which product architectures achieve multi-market scale without redundant certification cycles.
Market Dynamics
Semiconductor foundry allocation battles for CMUT wafers are compressing supply timelines and forcing device manufacturers into long-term offtake agreements with South Korean foundries.
Growth Catalysts
- Emergency medicine protocols:Point-of-care cardiovascular assessment reimbursement codes in the United States are expanding qualified use cases for bedside triage applications.
- Software-as-medical-device pathways:FDA 510(k) clearance streams for algorithm updates accelerate product iteration cycles without full hardware resubmission.
- MEMS fabrication advances:Single-chip transducer integration collapses probe assembly steps and yields cost structures accessible to primary care clinics.
Market Restraints
- Foundry concentration:CMUT wafer supply concentrates among two South Korean semiconductor fabricators, exposing buyers to allocation rationing during consumer electronics demand surges.
- EU MDR clinical evidence:Wireless connectivity features classified as active therapeutic devices face expanded clinical trial requirements before CE marking authorization.
- Piezoelectric ceramic volatility:Lead zirconate titanate raw material prices fluctuate with environmental mining restrictions in supplier jurisdictions.
Strategic Opportunities
- Rural health network penetration:Federally qualified health centers in the United States lack imaging infrastructure and represent unserved demand for portable diagnostic tools.
- AI diagnostic convergence:Real-time algorithmic interpretation of B-mode and Doppler streams enables technician-level operation without specialist presence.
- Subscription hardware models:Device-as-a-service arrangements reduce capital barriers for independent physician practices and align vendor revenue with utilization.
Industry Challenges
- Beamforming ASIC talent scarcity:Mixed-signal integrated circuit design expertise for low-power ultrasound processing commands premium compensation and extends hiring timelines.
- Multi-jurisdiction software validation:Divergent AI oversight requirements across FDA, EU MDR, and PMDA create redundant certification cycles for algorithm-enabled features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Handheld Ultrasound Devices Market |
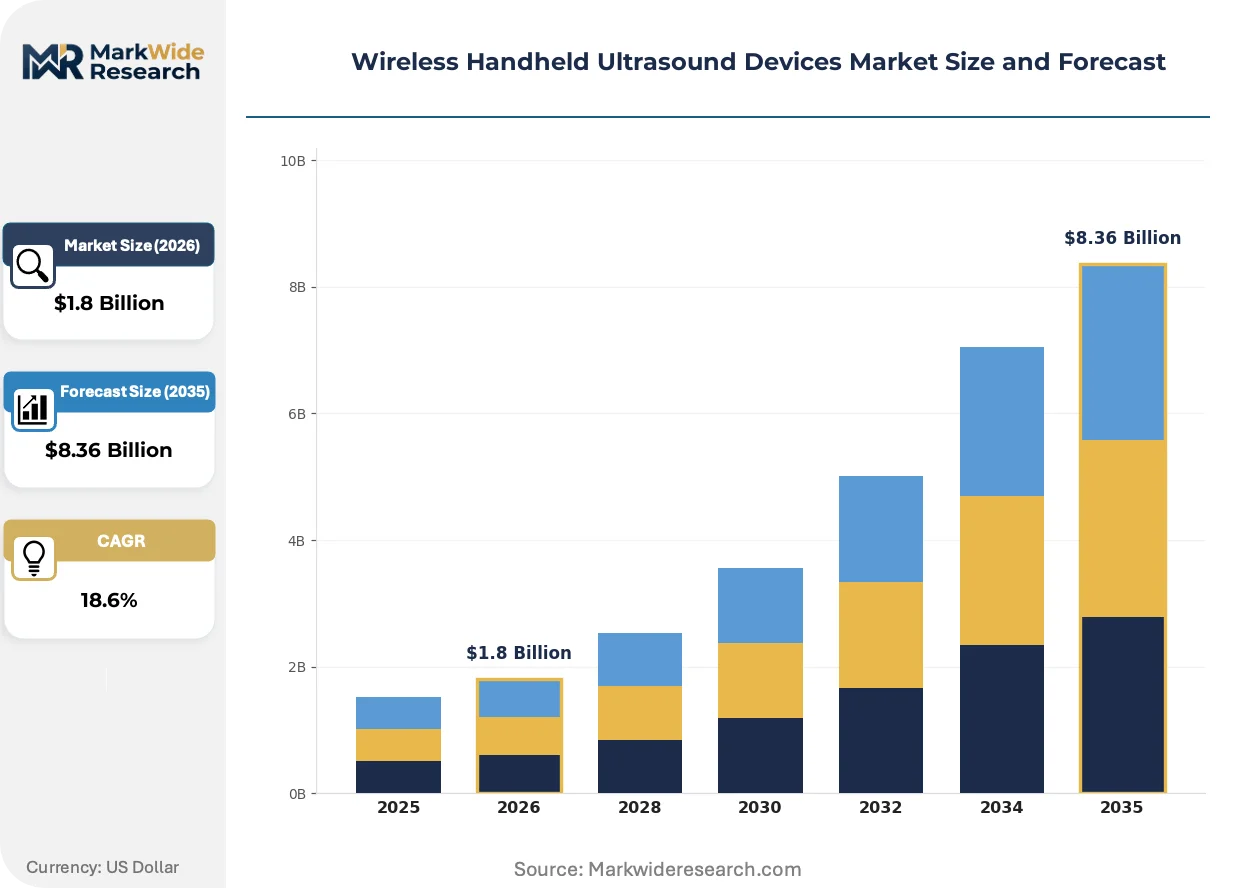
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Pocket-Sized Devices, Battery-Powered Units, Handheld Scanners End User: Clinics, Emergency Services, Home Care Providers, Veterinary Practices Technology: Digital Imaging, Wireless Connectivity, Battery Technology, Compact Design Application: Obstetrics, Cardiovascular Assessment, Musculoskeletal Imaging, Pediatric Examinations |
| Companies Covered | GE HealthCare, Koninklijke Philips N.V., Siemens Healthineers, Butterfly Network, Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Clarius Mobile Health Corp., Canon Medical Systems Corporation, FUJIFILM Sonosite, Inc., Viatom Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Handheld Ultrasound Devices Market Trends and Innovations
Portable imaging architectures are shedding tethered consoles through wireless data transmission and edge computing, collapsing the traditional cart-based equipment model into probe-centric systems.
Capacitive micromachined ultrasonic transducer technology is converging with standard CMOS fabrication processes to enable single-chip probe production. Emergency departments and interventional suites are adopting these devices for procedural guidance at replacement rates exceeding traditional departmental purchasing cycles. This convergence is compressing the manufacturing cost curve and displacing legacy piezoelectric stack assemblies in mid-tier product lines.
The EU Medical Device Regulation imposes stricter post-market surveillance obligations on wireless connectivity features than predecessor directives. Manufacturers must maintain clinical evidence repositories for software updates that modify diagnostic outputs. Cardiovascular imaging applications face the steepest compliance burden, prompting some vendors to segment product architectures by jurisdiction.
Hospital procurement departments are unbundling imaging hardware from long-term service contracts and evaluating devices on total cost-per-scan metrics. Group purchasing organizations are consolidating vendor panels and demanding interoperability with existing electronic health record systems. This behavioral shift is most pronounced in United States health systems undergoing decentralization, where individual service lines gain autonomous capital allocation authority.
Wireless Handheld Ultrasound Devices Market Segmentation
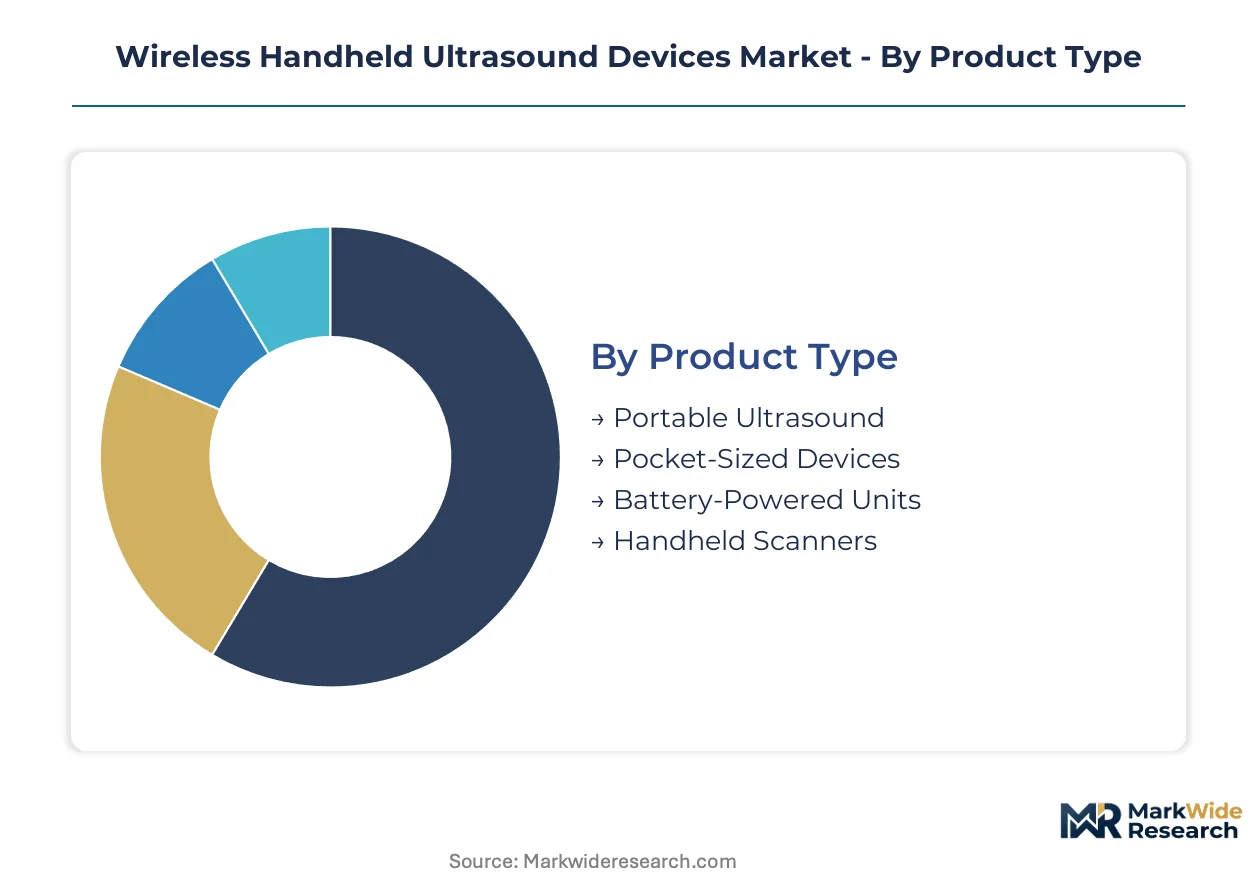
Probe architecture and power delivery specifications determine reimbursement eligibility and procurement channel access. Wireless handheld ultrasound devices segment across four orthogonal dimensions that shape pricing power and regulatory pathway complexity.
Product Type:
Form factor and power autonomy define the hardware cost structure and deployment flexibility across clinical environments.
- Portable Ultrasound:Larger handheld units with extended battery arrays and external tablet pairing dominate hospitalist workflows. Demand concentrates in United States emergency departments where reimbursement codes for point-of-care cardiovascular assessment reward rapid deployment capability.
- Pocket-Sized Devices:Minimalist single-probe systems with integrated beamforming ASICs collapse manufacturing into MEMS-fabricated elements. Clinics in rural health networks are expanding procurement fastest where capital constraints exclude cart-based systems.
- Battery-Powered Units:Rapid-charge protocols and extended wireless range command premium positioning in interventional suites.
- Handheld Scanners:Basic imaging capability at entry price points serves technician-level screening programs.
Mature deployment sits with portable ultrasound. Newer deployment is concentrated in pocket-sized devices.
End User:
Capital allocation authority and reimbursement alignment determine vendor access and contract structure across buyer categories.
- Emergency Services:Point-of-care triage protocols in United States ambulance services and flight medicine programs drive replacement cycles exceeding traditional departmental purchasing. FDA 510(k) clearance streams for algorithm updates accelerate product refresh without hardware resubmission.
- Clinics:Federally qualified health centers lacking imaging infrastructure represent unserved demand for subscription hardware models. Primary care practices in decentralized United States health systems gain autonomous procurement authority.
- Home Care Providers:Remote patient monitoring expansion creates demand for technician-operated devices with cloud connectivity.
- Veterinary Practices:Companion animal imaging applications bypass human medical regulatory burdens.
Established procurement patterns sit with clinics. Expanding most quickly is emergency services.
Technology:
Component integration depth separates premium architectures from cost-optimized alternatives in manufacturing cost curves.
- Wireless Connectivity:Wi-Fi and Bluetooth transmission protocols with edge computing capability displace tethered console architectures. EU MDR imposes stricter post-market surveillance obligations on connectivity features classified as active therapeutic devices.
- Digital Imaging:Real-time B-mode and Doppler processing with AI-enabled diagnostic algorithms enables technician-level operation without specialist presence.
- Battery Technology:Lithium-polymer cell density and thermal management determine continuous scan duration.
- Compact Design:Miniaturized transducer array packaging at 2-15 MHz operating frequency.
Deep integration sits with digital imaging. Steepest expansion trajectory is wireless connectivity.
Application:
Clinical evidence requirements and reimbursement density vary sharply across diagnostic use cases.
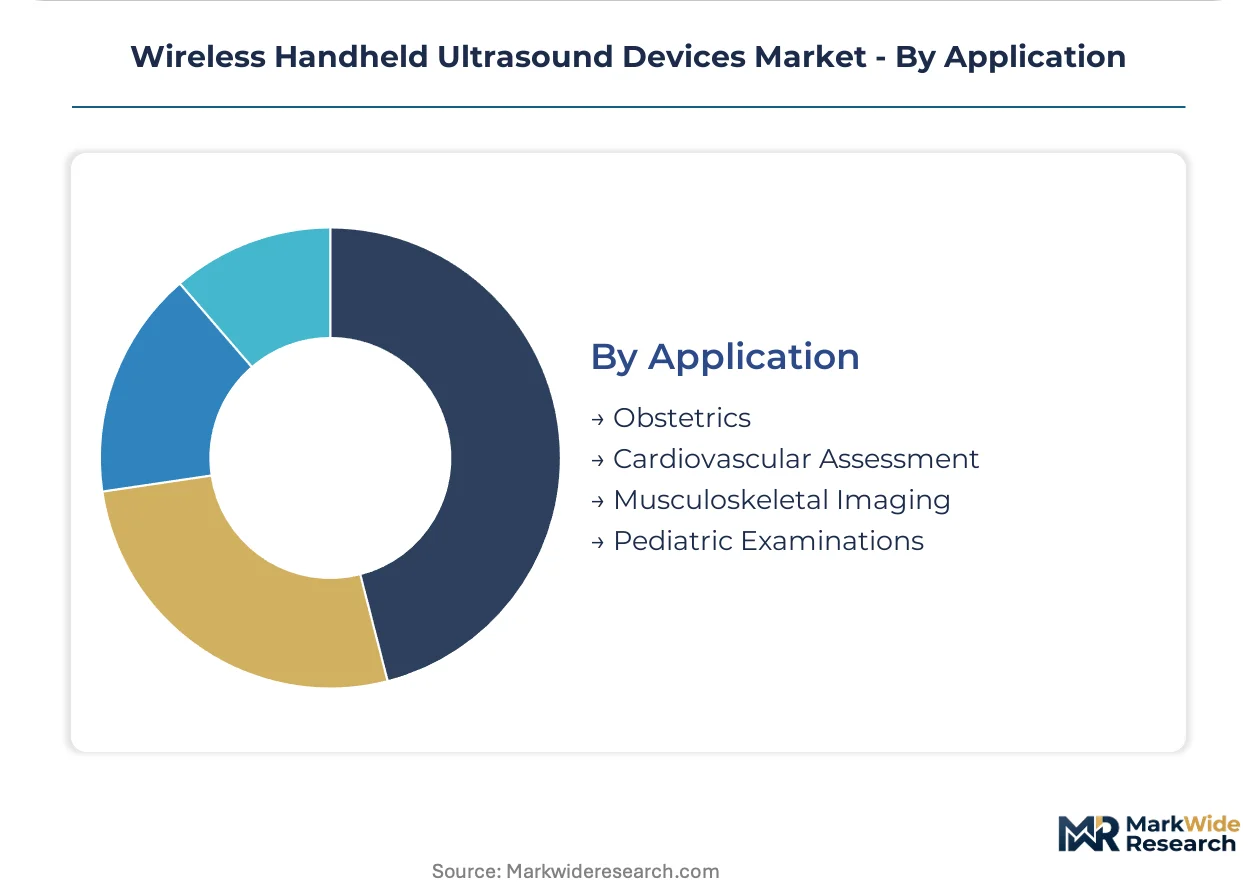
- Cardiovascular Assessment:Bedside triage for heart failure and pericardial effusion commands highest reimbursement alignment in United States emergency medicine protocols. PMDA enforces JIS T 0601-1 electrical safety standards before METI grants market authorization for cardiac output measurement features.
- Musculoskeletal Imaging:Procedural guidance for joint injections and fracture assessment expands in sports medicine clinics. Interventional suites adopt these devices at replacement rates exceeding traditional purchasing cycles.
- Obstetrics:Fetal biometry and placental assessment applications face stringent AI validation requirements.
- Pediatric Examinations:Neonatal cranial and hip dysplasia screening protocols.
Reimbursement maturity sits with cardiovascular assessment. Gaining share fastest is musculoskeletal imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lead zirconate titanate deposits in Jiangxi province and CMUT wafer fabrication in Gyeonggi-do anchor the upstream geography for transducer supply chains. Device assembly concentrates in Guangdong province and the Seoul Capital Area, while clinical demand pulls strongest from United States emergency medicine networks and European decentralized health systems.
United States
Emergency departments and federally qualified health centers drive procurement for point-of-care cardiovascular assessment. FDA 510(k) clearance pathways streamline software updates without hardware resubmission, accelerating product refresh cycles. Boston and Minneapolis medical device clusters host engineering talent for beamforming ASIC design.
China
Primary care clinics in rural health networks expand procurement of pocket-sized devices where capital constraints exclude cart-based systems. NMPA medical device registration requires clinical evidence for AI-enabled diagnostic algorithms. Shenzhen anchors vertically integrated probe assembly lines serving domestic and export markets.
Germany
Hospital procurement departments evaluate devices on total cost-per-scan metrics and demand interoperability with electronic health record systems. EU MDR imposes stricter post-market surveillance obligations on wireless connectivity features classified as active therapeutic devices. Munich and Berlin clusters concentrate regulatory affairs expertise for CE marking navigation.
South Korea
Semiconductor foundries in Gyeonggi-do and Pyeongtaek ration CMUT wafer allocations between medical device and consumer electronics buyers. MFDS enforces electrical safety standards for wireless medical devices before market authorization. Samsung and SK Hynix captive partnerships secure supply priority for domestic health technology manufacturers.
Japan
Interventional suites in Tokyo and Osaka adopt handheld devices for procedural guidance at replacement rates exceeding traditional purchasing cycles. PMDA enforces JIS T 0601-1 electrical safety standards before METI grants market authorization for cardiac output measurement features. Kanto region hospitals lead adoption of technician-operated screening protocols.
Wireless Handheld Ultrasound Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled diagnostic convergence and subscription hardware models. The vendor base spans diversified medical technology conglomerates, single-probe specialists, and regional assembly operations. Three archetypes dominate: captive sensor partnerships securing foundry allocation, MEMS-fabricated single-chip architectures collapsing manufacturing complexity, and vertically integrated probe assembly lines in cost-optimized manufacturing zones. Competitive moves concentrate on long-term offtake agreements with South Korean foundries and strategic partnerships for algorithm development.
Among diversified health technology conglomerates, GE HealthCare and Koninklijke Philips N.V. represent established archetypes with captive supply chain relationships. Butterfly Network, Inc. exemplifies the single-probe specialist model, while Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors the vertically integrated regional fabricator tier. These three occupy positions across the pricing and capability spectrum without overlapping strategic positioning.
| Leading Market Players |
|---|
| GE HealthCare |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Butterfly Network, Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Clarius Mobile Health Corp. |
| Canon Medical Systems Corporation |
| FUJIFILM Sonosite, Inc. |
| Viatom Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement departments and group purchasing organizations concentrate buying power in the United States, forcing vendors toward unbundled hardware pricing and total cost-per-scan evaluation models that separate device acquisition from long-term service contracts.
Pricing Analysis
Warranty and preventive maintenance bundling distinguishes premium-tier offerings from entry-level alternatives, with extended coverage periods and rapid replacement guarantees commanding substantial markups. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, AI-enabled diagnostic capability, and wireless range specifications. Cost compression in the pocket-sized device tier is intensifying because MEMS fabrication advances collapse manufacturing steps and enable Asian assembly operations. Federally qualified health centers exhibit highest price sensitivity, while interventional suites in academic medical centers prioritize performance metrics over acquisition cost.
Supply Chain Analysis
Dual-sourcing mandates from major device manufacturers require qualification of at least two CMUT wafer suppliers, though foundry concentration in South Korea limits genuine supply diversification. Probe assembly draws from vertically integrated operations in Guangdong province, South Korean semiconductor fabricators in Gyeonggi-do, and specialized lithium-polymer cell producers in Japan. Lead zirconate titanate ceramic supply rests on mining operations in Jiangxi province subject to environmental restriction volatility. Distribution runs through medical device distributors with GPO contracting relationships and direct hospital system partnerships for large-volume placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMUT foundry capacity constraints in South Korea prop pricing power for manufacturers with secured wafer allocations, creating a supply-constrained market structure that favors incumbents with long-term offtake agreements.
For Market Incumbents: Lock in multi-year CMUT wafer supply agreements with Samsung and SK Hynix before consumer electronics demand surges absorb remaining foundry capacity. Deepen backward integration into beamforming ASIC design to reduce dependence on scarce mixed-signal engineering talent pools in Boston and Minneapolis clusters. For New Entrants and Emerging Players: Federally qualified health centers in rural United States networks represent the most penetrable segment, with capital constraints excluding cart-based systems and reimbursement codes expanding for point-of-care cardiovascular assessment. Pursue subscription hardware models that reduce capital barriers and align vendor revenue with utilization metrics. For Investors and Strategic Acquirers: The window for entry favors single-probe specialists with MEMS-fabricated architectures and FDA 510(k) clearance streams already established. Watch for FDA software-as-medical-device pathway expansion as the inflection signal indicating accelerated algorithm-enabled product refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term CMUT Wafer Supply Agreement | Secures semiconductor foundry allocation ahead of consumer electronics buyers in South Korea. |
| Software-as-Medical-Device FDA Pathway | Accelerates algorithm update cycles without hardware resubmission under 510(k) streams. |
| Hospital System GPO Partnership | Unlocks procurement access to decentralized United States health systems with autonomous capital authority. |
| AI Diagnostic Algorithm Development | Enables technician-level operation without specialist presence in rural clinic deployments. |
| Subscription Hardware Service Model | Reduces capital barriers for independent physician practices and aligns revenue with utilization. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across biomedical engineers, hospital purchasing committees, GPO contracts managers, and emergency medicine clinicians. FDA 510(k) premarket notification databases, EU MDR technical documentation, and NMPA registration records provided regulatory pathway validation. Bottom-up unit shipment estimates triangulated against top-down healthcare expenditure analysis across the analysis window.
Data-stream reconciliation merged probe architecture segmentation with end-user channel dynamics and geographic reimbursement patterns. Modeled dimensions span product type, application, technology integration depth, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to historical adoption rates in point-of-care imaging and foundry capacity expansion timelines. Forecast inputs incorporated CMUT wafer allocation trends and FDA software validation pathway evolution.
Caveats apply where foundry capacity rationing or regulatory divergence in AI oversight could materially shift the outlook. Deviation in South Korean semiconductor export policy or EU MDR clinical evidence requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Face Mask Device Market
Medical Devices
Global Patient Warming Systems Market
Medical Devices
Eye Socket Implants Market
Medical Devices
Phoropters Market
Medical Devices
Gamma Knife Market
Medical Devices
Tubal Obstruction Devices Market
Medical Devices
Ventilation Devices Market
Medical Devices
Temporary Cardiac Pacing Wires and Leads Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Medical Germicidal Lamps Market