
 Global Carbon Dioxide Incubators Market | 2026-2036
Global Carbon Dioxide Incubators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Dioxide Incubators Market Foresight
Remote monitoring subscriptions and predictive maintenance contracts is realigning how carbon dioxide incubators are sold, shifting revenue from single-unit transactions to recurring service relationships. Thermo Fisher Scientific Inc. leverages its installed base to bundle cloud-connected diagnostics with hardware, while Eppendorf AG sustains loyalty through certified service networks across major research corridors. BINDER GmbH anchors its positioning in pharmaceutical validation workflows where audit-ready documentation commands premium positioning.
A carbon dioxide incubator is a sealed, thermally controlled chamber that maintains temperature typically near 37°C, humidity above 90%, and carbon dioxide concentration at 5% to simulate physiological conditions for living cell cultures. Water jacket technology retains thermal stability during door openings, making it preferred for long-term embryology and stem cell protocols where fluctuation kills sensitive lines. Bench-top units dominate academic labs where space constraints and budget cycles favor compact footprints, while floor-standing dual chamber systems capture margin pools in contract development and manufacturing organizations running parallel batch campaigns. Infrared CO2 sensor configurations are displacing older thermal conductivity methods in pharmaceutical testing environments where drift-free calibration satisfies regulatory filing requirements.
FDA enforces 21 CFR Part 11 electronic records standards that shape software architecture in units sold to U.S. biopharmaceutical end users, while EMA's Annex 1 revision on sterile manufacturing pushes European buyers toward HEPA-filtered chamber designs with continuous particle monitoring. China's NMPA alignment with PIC/S guidelines is forcing domestic manufacturers to adopt ISO 9001 traceability protocols or lose access to hospital-based IVF laboratories. Stakeholders must decide whether to build captive service organizations or partner with third-party validation specialists as compliance complexity outpaces internal technical capacity.
Market Dynamics
Carbon dioxide incubators are shifting from standalone capital equipment to integrated nodes within cloud-connected laboratory ecosystems, as biopharmaceutical manufacturers demand real-time environmental traceability for cell-based therapy submissions.
Growth Catalysts
- EMA Annex 1 Revision:The updated sterile manufacturing guidelines mandate continuous environmental monitoring in European cell therapy production facilities, forcing upgrades to HEPA-filtered incubators with validated sensor arrays.
- Monoclonal antibody manufacturing expansion:Contract development organizations in the United States and China are scaling parallel batch capacity, driving floor-standing dual-chamber system procurement for campaign flexibility.
- Water jacket thermal stability:Embryology laboratories prioritize this technology for IVF protocols where temperature fluctuation during door openings compromises sensitive cell line viability.
Market Restraints
- Stainless steel and copper alloy input volatility:Chamber construction materials face commodity price swings that compress manufacturer margins on mid-tier product lines.
- Sensor calibration infrastructure concentration:NIST-traceable calibration services cluster in Germany and the United States, creating logistics barriers for laboratories in emerging manufacturing regions.
- Thermal conductivity sensor obsolescence:Legacy measurement methods suffer drift that fails FDA 21 CFR Part 11 electronic records standards, stranding installed bases in regulated environments.
Strategic Opportunities
- India's hospital-based IVF laboratory expansion:Fertility clinic networks in Mumbai and Bangalore lack validated incubator capacity, opening premium positioning for audit-ready equipment suppliers.
- Remote predictive maintenance subscriptions:Cloud-connected diagnostics bundled with hardware create recurring revenue streams that decouple growth from unit sales cycles.
- ISO 9001 traceability protocol convergence:China's NMPA alignment with PIC/S guidelines forces domestic manufacturers to upgrade quality systems, creating partnership openings for validated foreign suppliers.
Industry Challenges
- Field service engineer scarcity:Qualified technicians for HEPA filtration validation and sensor calibration are concentrated in established biopharma corridors, limiting geographic expansion.
- Legacy building management system integration:New cloud-connected incubators face protocol incompatibility with older laboratory infrastructure, extending sales cycles and requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Dioxide Incubators Market |
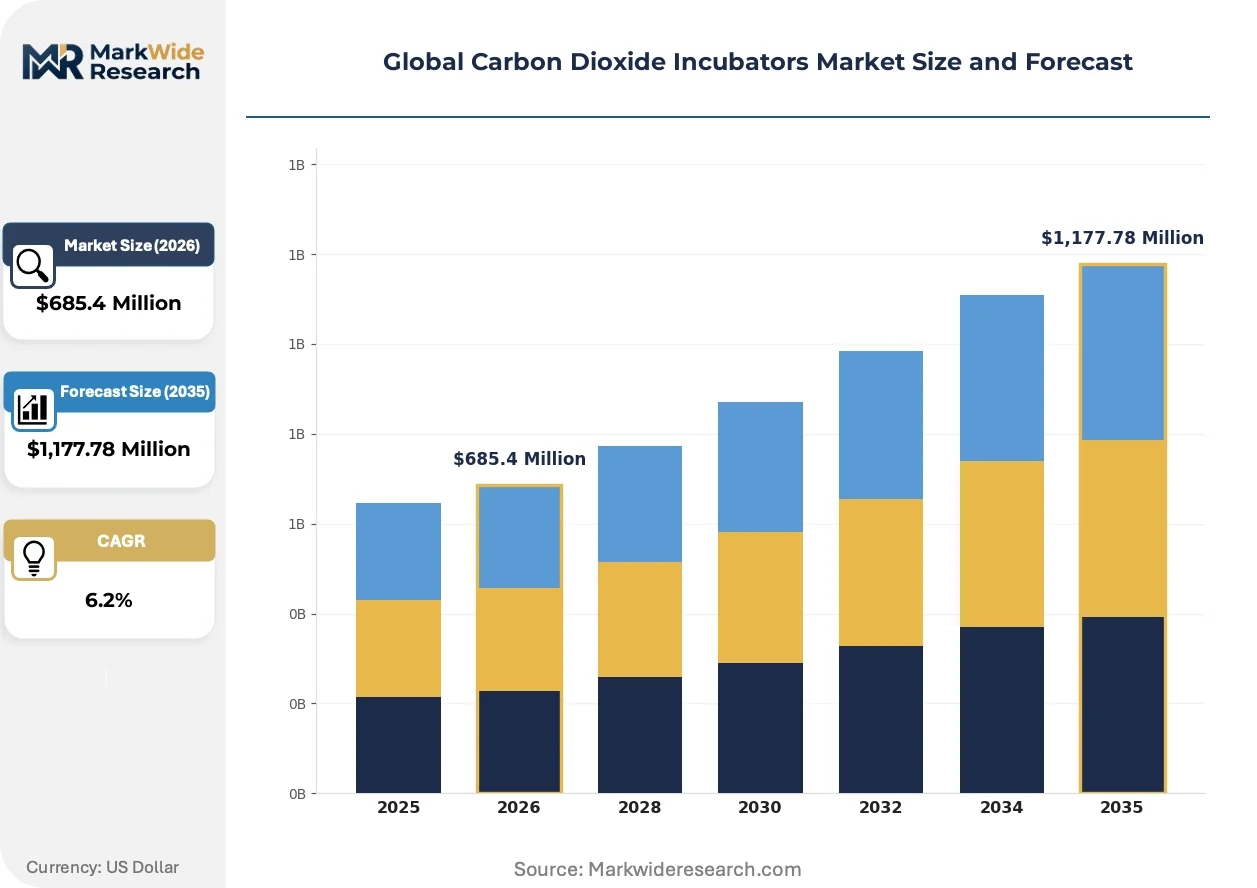
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-Top, Floor-Standing, Single Chamber, Dual Chamber, Microscope-Integrated Technology: Water Jacket, Air Jacket, Microprocessor Controlled, Infrared CO2 Sensor, PID Controller Application: Cell Culture, Microbial Growth, Tissue Engineering, IVF Procedures, Pharmaceutical Testing End User: Research Institutes, Biopharmaceutical Companies, Academic Labs, Clinical Laboratories, Biotech Startups |
| Companies Covered | Thermo Fisher Scientific Inc., Eppendorf AG, BINDER GmbH, PHC Holdings Corporation, Sheldon Manufacturing Inc., Bellco Glass Inc., NuAire Inc., LEEC Ltd., Memmert GmbH + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Dioxide Incubators Market Shifts & Advancements
Instrumentation architecture is fragmenting as laboratory managers demand modular systems that interoperate with diverse software platforms rather than locked ecosystems.
Infrared CO2 sensor technology with solid-state non-dispersive detection is decentralizing quality control workflows in pharmaceutical testing environments. Contract manufacturing organizations in Germany and the United States are adopting these configurations at replacement-cycle pace. The technology is decentralizing calibration authority from centralized metrology labs to point-of-use verification, compressing downtime and documentation overhead.
China's NMPA implementation of PIC/S-aligned traceability protocols is reshaping domestic manufacturing requirements. Domestic producers must adopt ISO 9001 documentation standards or forfeit hospital laboratory access. Floor-standing systems with continuous particle monitoring are capturing preference share in Shanghai and Beijing cell therapy facilities.
Academic laboratories are unbundling service contracts from hardware procurement, treating preventive maintenance as separately negotiable spend. Compact bench-top units in United States university settings now route through group purchasing organizations that pit third-party validation specialists against manufacturer service arms. This pattern is most visible in California and Massachusetts research corridors where budget autonomy has shifted to departmental principal investigators.
Global Carbon Dioxide Incubators Market Segmentation
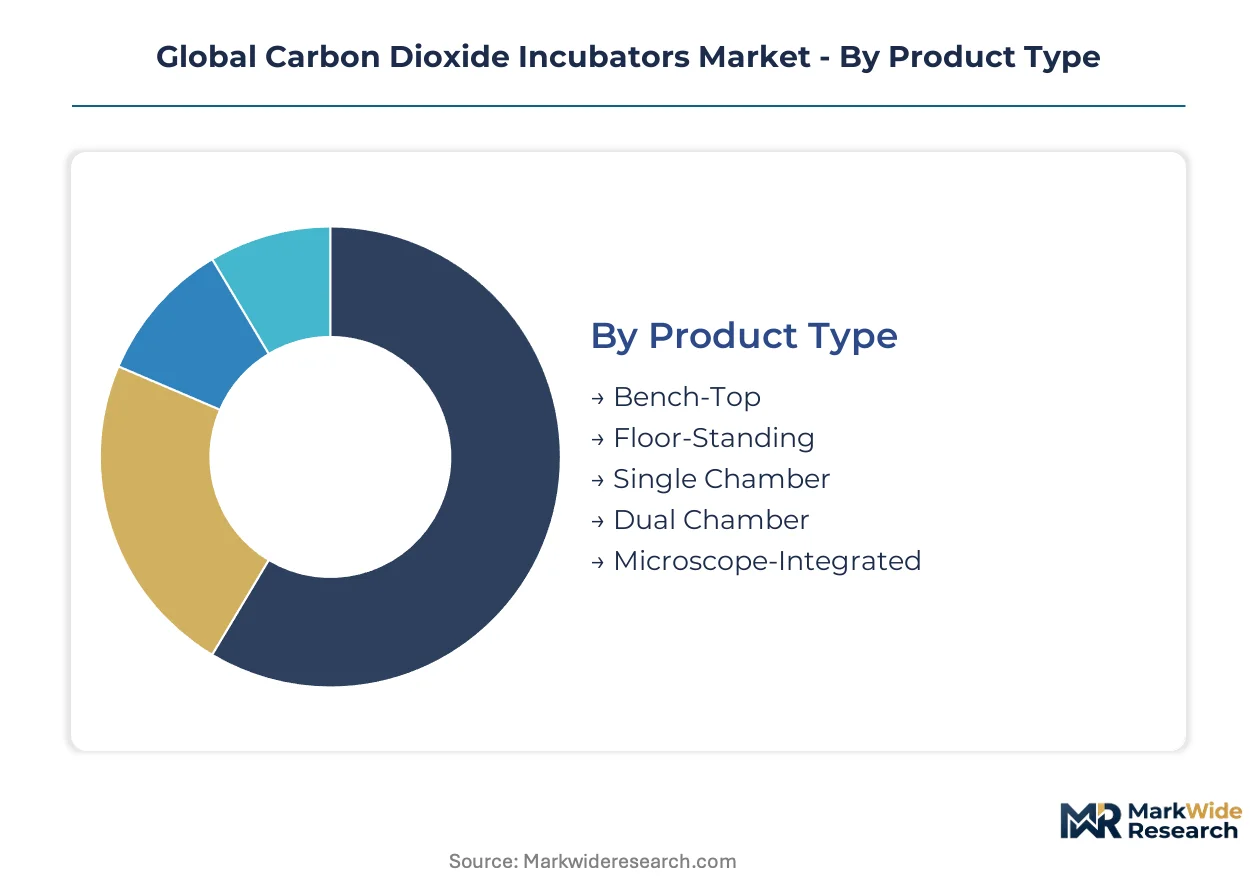
Carbon dioxide incubator purchasing patterns diverge sharply across laboratory types, with biopharmaceutical manufacturers prioritizing validated traceability systems while academic buyers optimize for capital efficiency and space constraints. Equipment specifications cascade from end-use regulatory exposure, creating distinct margin pools that reward modular architectures over locked ecosystems.
Product Type:
Facility footprint and batch scale differentiate buyers most acutely in this category, with space-constrained laboratories trading chamber capacity for bench access.
- Bench-Top:Compact units under 200-liter capacity dominate United States academic laboratories where departmental principal investigators control procurement budgets. California and Massachusetts research corridors route these through group purchasing organizations that unbundle service contracts from hardware.
- Floor-Standing:Dual-chamber configurations capture contract development organizations in China and Germany running parallel monoclonal antibody batch campaigns. These systems command premium positioning where campaign flexibility justifies higher capital outlay.
- Single Chamber:Standard configuration for mid-scale cell culture operations requiring validated environmental control without redundancy overhead.
- Dual Chamber:Isolated compartments enable simultaneous processing of distinct cell lines, critical for biopharmaceutical testing environments with cross-contamination protocols.
- Microscope-Integrated:Combined imaging and incubation systems reduce handling disruption for live-cell imaging workflows in embryology laboratories.
Bench-Top units lead volumes today; Floor-Standing configurations are climbing the fastest as biologics manufacturing scales.
Technology:
Sensor architecture and thermal management method determine regulatory compliance eligibility and long-term calibration burden.
- Water Jacket:Thermal mass surrounding the chamber maintains temperature stability during door openings. Embryology laboratories in Germany prioritize this technology for IVF protocols where fluctuation compromises sensitive cell line viability.
- Infrared CO2 Sensor:Solid-state non-dispersive detection eliminates drift that plagues legacy thermal conductivity methods. Contract manufacturing organizations in the United States adopt these at replacement-cycle pace to satisfy FDA 21 CFR Part 11 electronic records standards.
- Air Jacket:Rapid thermal recovery suits high-throughput screening environments with frequent access patterns.
- Microprocessor Controlled:Digital precision enables programmable cycle variations for specialized culture protocols.
- PID Controller:Proportional-integral-derivative algorithms minimize temperature oscillation in pharmaceutical validation workflows.
Water Jacket systems anchor current installed base; Infrared CO2 Sensor configurations show steepest expansion trajectory.
Application:
Regulatory filing requirements and cell sensitivity thresholds segment demand across therapeutic and research domains.
- Cell Culture:Mammalian cell propagation for biologics production demands continuous environmental monitoring. EMA Annex 1 revision mandates HEPA-filtered configurations for European cell therapy facilities.
- IVF Procedures:Human embryo culture requires sub-0.1°C temperature stability and rapid recovery post-access. China's NMPA alignment with PIC/S guidelines forces hospital laboratories toward validated, audit-ready equipment.
- Tissue Engineering:Three-dimensional scaffold cultivation drives demand for specialized gas and humidity profiles.
- Microbial Growth:Bacterial and fungal culture applications tolerate wider environmental tolerances than mammalian systems.
- Pharmaceutical Testing:Stability studies and cytotoxicity assays require documented traceability for regulatory submission packages.
Cell Culture commands the largest revenue pool; IVF Procedures are expanding most quickly as fertility clinic networks proliferate.
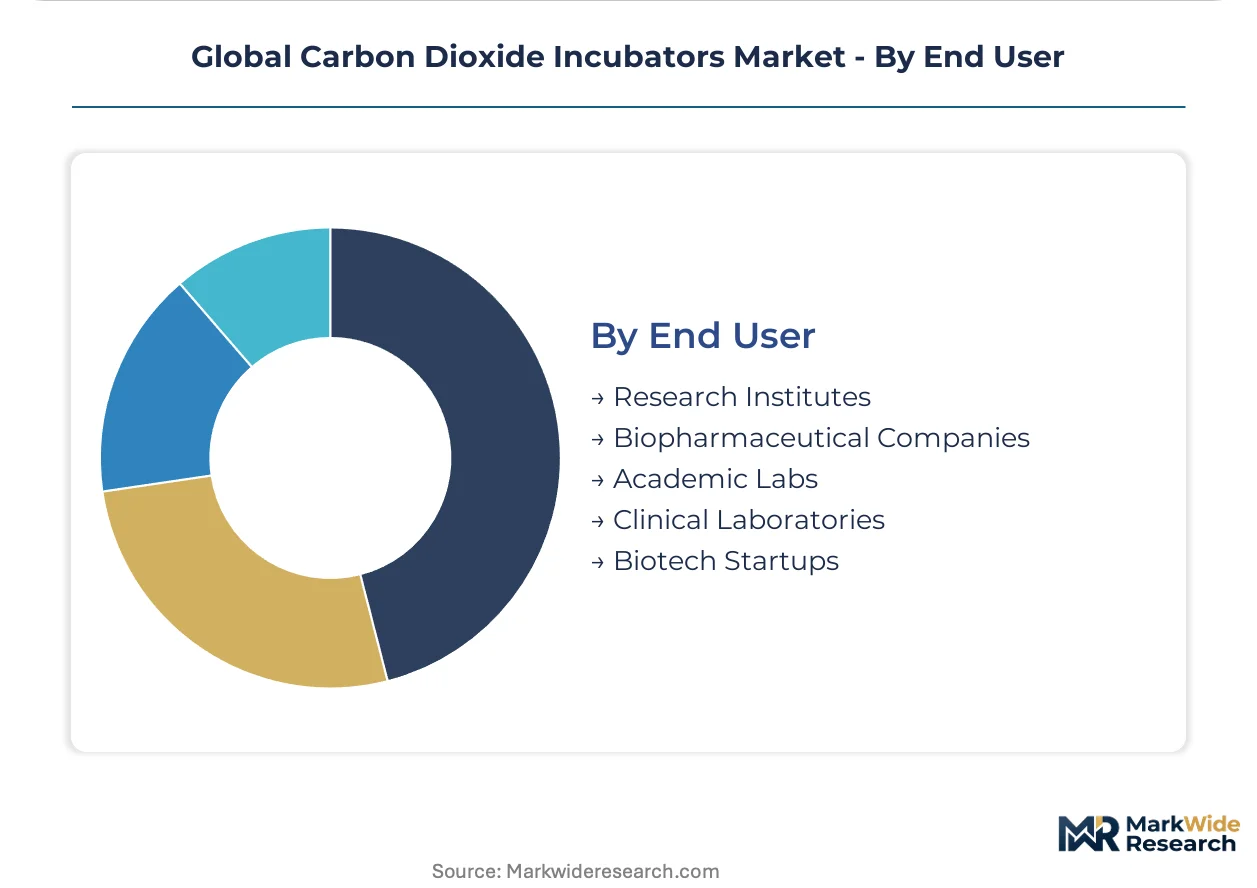
End User:
Procurement autonomy and compliance maturity separate institutional buyers, with centralized biopharmaceutical purchasing favoring bundled service relationships.
- Biopharmaceutical Companies:Scaled monoclonal antibody manufacturers in the United States and China demand cloud-connected diagnostics with predictive maintenance subscriptions. These buyers decouple equipment selection from capital budget cycles through recurring service contracts.
- Research Institutes:Federally funded laboratories balance equipment performance against grant-funded capital constraints. Bench-top units predominate where space allocation competes with competing instrumentation needs.
- Academic Labs:Departmental control over procurement enables third-party validation specialists to compete against manufacturer service arms.
- Clinical Laboratories:Hospital-based operations face joint commission accreditation requirements that elevate documentation standards.
- Biotech Startups:Venture-funded operations prioritize lease flexibility and rapid deployment over long-term ownership economics.
Biopharmaceutical Companies generate the highest per-unit margins; Biotech Startups are gaining share fastest as cell therapy venture formation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers are migrating production toward jurisdictions with mature validation infrastructure and harmonized regulatory frameworks, creating compliance-cost arbitrage that favors established manufacturing clusters over emerging markets lacking NIST-traceable calibration networks.
United States
Contract development organizations in Massachusetts and North Carolina are scaling dual-chamber floor-standing capacity for parallel monoclonal antibody campaigns. FDA enforcement of 21 CFR Part 11 electronic records standards forces sensor upgrades toward infrared CO2 configurations with drift-free calibration. The Greater Boston biologics corridor concentrates demand for cloud-connected diagnostics bundled with predictive maintenance subscriptions.
Germany
EMA's Annex 1 revision on sterile manufacturing mandates HEPA-filtered chamber designs with continuous particle monitoring for cell therapy production. Water jacket technology retains preference in Heidelberg and Munich embryology laboratories where sub-0.1°C stability protects sensitive IVF protocols. NIST-traceable calibration services cluster in Baden-Württemberg, creating logistics advantages for European manufacturers.
China
NMPA alignment with PIC/S guidelines forces domestic producers toward ISO 9001 documentation standards or forfeiture of hospital-based IVF laboratory access. Shanghai and Beijing cell therapy facilities are capturing floor-standing systems with validated sensor arrays. Yangtze River Delta biopharmaceutical parks are expanding monoclonal antibody manufacturing capacity, driving procurement of audit-ready equipment.
India
Fertility clinic networks in Mumbai and Bangalore lack validated incubator capacity, opening premium positioning for foreign suppliers with audit-ready documentation. The country's national pharmaceutical regulator has tightened traceability requirements for assisted reproductive technology equipment. Hospital-based IVF laboratories in Maharashtra are upgrading from unvalidated domestic units toward certified systems.
Japan
PMDA guidelines for cell-based therapy manufacturing emphasize environmental monitoring documentation that favors sensor-traceable incubator configurations. Osaka and Tokyo metropolitan research institutes balance grant-funded capital constraints against performance requirements for live-cell imaging workflows. Microscope-integrated systems are penetrating academic laboratories where handling disruption must be minimized.
Global Carbon Dioxide Incubators Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated presence among premium-tier suppliers serving regulated biopharmaceutical environments and fragmentation among regional fabricators targeting academic price points. The vendor base clusters around three strategic archetypes: full-service laboratory conglomerates bundling hardware with recurring diagnostics subscriptions, mid-cap specialists anchoring positioning in validation-intensive pharmaceutical workflows, and regional OEMs competing on capital efficiency for budget-constrained research institutes. Dominant competitive moves include cloud-connectivity integration to capture service revenue streams and third-party validation partnerships to extend geographic reach without captive field service organizations.
Among full-service laboratory conglomerates, Thermo Fisher Scientific Inc. and Eppendorf AG exemplify the integrated-service archetype, while BINDER GmbH occupies a position within the mid-cap specialist tier focused on pharmaceutical validation workflows. These three entities represent contrasting approaches to market coverage: the conglomerate model leveraging installed base for recurring revenue, versus the specialist model commanding premium positioning through audit-ready documentation capabilities. Each anchors a distinct competitive vector without direct overlap in customer procurement criteria.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Eppendorf AG |
| BINDER GmbH |
| PHC Holdings Corporation |
| Sheldon Manufacturing Inc. |
| Bellco Glass Inc. |
| NuAire Inc. |
| LEEC Ltd. |
| Memmert GmbH + Co. KG |
| Others |
Supply & Pricing Matrix
Stainless steel alloy price indices cascade through carbon dioxide incubator manufacturing into three-tier pricing stratification across premium, standard, and economy levels. Biopharmaceutical buyers absorb premium positioning for FDA-validated configurations while academic laboratories face capital constraints that compress mid-tier margins.
Pricing Analysis
Distributor margins of 15-25% separate manufacturer list pricing from end-user acquisition costs in most geographies. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 9001-traceable and FDA 21 CFR Part 11-compliant units commanding substantial premiums over unvalidated alternatives. Pricing pressure stems from commodity input volatility in copper and stainless steel alloys, compressing manufacturer margins on standard-tier product lines. Academic laboratories exhibit highest price sensitivity, routing procurement through group purchasing organizations that unbundle service contracts and pit third-party validation specialists against manufacturer service arms.
Supply Chain Analysis
Dual-sourcing requirements from biopharmaceutical manufacturers mandate multi-supplier qualification for critical sensor components, forcing incubators to carry redundant calibration certifications. Component manufacturing concentrates in Germany, the United States, and China, with NIST-traceable sensor arrays and HEPA filtration modules drawing from specialized fabricators in Baden-Württemberg and Massachusetts. Raw material dependencies center on stainless steel chamber construction, copper alloy heat exchangers, and solid-state infrared detector elements. Single-source vulnerability in NIST-traceable calibration services creates logistics barriers for emerging manufacturing regions. Distribution runs through laboratory equipment distributors and direct OEM relationships with large biopharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon dioxide incubator procurement patterns create geographic-arbitrage opportunities between European EMA Annex 1 compliance costs and Asian manufacturing scale advantages. Regulatory divergence between FDA 21 CFR Part 11 standards and China's NMPA PIC/S alignment forces equipment suppliers to maintain parallel validation workflows.
For Market Incumbents: Hedge against sensor technology obsolescence by deepening backward integration into solid-state infrared detector manufacturing or securing exclusive supply agreements with German calibration specialists. Incumbents must defend service revenue streams from third-party validation specialists by embedding predictive maintenance subscriptions into hardware contracts, particularly in United States academic corridors where group purchasing organizations unbundle traditional service relationships. For New Entrants and Emerging Players: Launch via third-party validation partnerships to extend geographic reach without captive field service organizations, targeting India's hospital-based IVF laboratory expansion in Mumbai and Bangalore where validated incubator capacity remains scarce. New entrants should prioritize audit-ready documentation capabilities over hardware innovation, as China's NMPA alignment with PIC/S guidelines forces domestic manufacturers toward ISO 9001 traceability protocols that foreign specialists can exploit. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing pharmaceutical validation workflows and audit-ready documentation capabilities rather than full-service conglomerates dependent on hardware sales cycles. Long-term viability over the projection horizon favors targets with recurring service revenue streams from cloud-connected diagnostics and predictive maintenance subscriptions. Watch NMPA enforcement timelines in China as the inflection indicator for premium equipment penetration in Asia-Pacific biopharmaceutical manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Diagnostics Integration | Thermo Fisher Scientific leverages installed base to bundle predictive maintenance subscriptions with hardware sales. |
| Third-Party Validation Partnerships | Eppendorf AG extends geographic reach without captive field service organizations through certified service networks. |
| Pharmaceutical Validation Workflow Positioning | BINDER GmbH commands premium positioning where audit-ready documentation satisfies EMA Annex 1 requirements. |
| HEPA-Filtered Chamber Design Certification | Continuous particle monitoring configurations capture preference share in European cell therapy facilities. |
| ISO 9001 Traceability Protocol Adoption | Foreign suppliers exploit China's NMPA alignment with PIC/S guidelines to displace unvalidated domestic manufacturers. |
Research Methodology
Multiple input streams — primary interviews with biopharmaceutical manufacturing executives, laboratory equipment procurement managers, and embryology laboratory directors; secondary validation through FDA 510(k) filings, EMA regulatory submissions, and NMPA registration databases; plus customs trade data and SEC 10-K equipment revenue disclosures — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement decision criteria across United States, German, and Chinese research corridors.
Historical shipment patterns were cross-referenced against expert panel inputs to construct segment-level projections across the analysis window. The analytical framework modeled technology type, product configuration, application domain, and end-user procurement autonomy as core segmentation dimensions. CAGRs were derived from equipment replacement cycle timing, biopharmaceutical manufacturing capacity expansion announcements, and regulatory compliance deadline clustering. Industry-specific forecast inputs included NIST-traceable calibration service capacity constraints and PIC/S guideline implementation timelines in China.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt stainless steel commodity price spikes or accelerated FDA enforcement of 21 CFR Part 11 electronic records standards. Deviation in EMA Annex 1 revision implementation timelines or NMPA PIC/S alignment enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Vacuum Mixing Devices Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Dialyzer Reprocessing Machines and Concentrates Market
Medical Equipment
Birthing Beds Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Sterilization Equipment Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Global Oxygen Flow Meters Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Global Microtome Market
Medical Equipment
US ECG Equipment Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Global Plasma Sterilizers Market
Medical Equipment
Medication Pouch Inspection Systems Market
Medical Equipment
Global Countertop Platelet Incubator Market