
 Global Medical Lifting Slings Market | 2026-2036
Global Medical Lifting Slings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Lifting Slings Market Foresight
ISO 10535 certification for patient lift slings is redrawing competitive boundaries in the Global Medical Lifting Slings Market. Arjo leverages its vertically integrated manufacturing footprint across Europe and North America to sustain premium positioning. V. Guldmann A/S anchors Nordic design standards while Etac AB specializes in bariatric and rehabilitation-specific configurations.
Medical lifting slings are load-bearing textile devices engineered with specified safe working loads, typically constructed from polyester, nylon, or mesh fabrics with reinforced stitching patterns, designed to transfer patients between surfaces while distributing pressure across body contact points. The product type dimension shows universal slings occupying the volume core while bariatric slings command margin premiums due to specialized engineering requirements. Material selection increasingly favors mesh fabric for infection control protocols in acute care, though cotton-polyester blends dominate home care channels for comfort perception.
The FDA's 510(k) clearance framework, the EU Medical Device Regulation (MDR), and Japan's PMDA quality management requirements collectively elevate compliance costs but simultaneously filter out subscale competitors. REACH chemical restrictions and the EU Green Deal's textile sustainability targets are pressuring manufacturers to reformulate fabric treatments and dye processes. Stakeholders must monitor how reimbursement code expansions for safe patient handling equipment in Medicare and analogous national health systems reshape procurement volume distribution between institutional and home-based care settings.
Market Dynamics
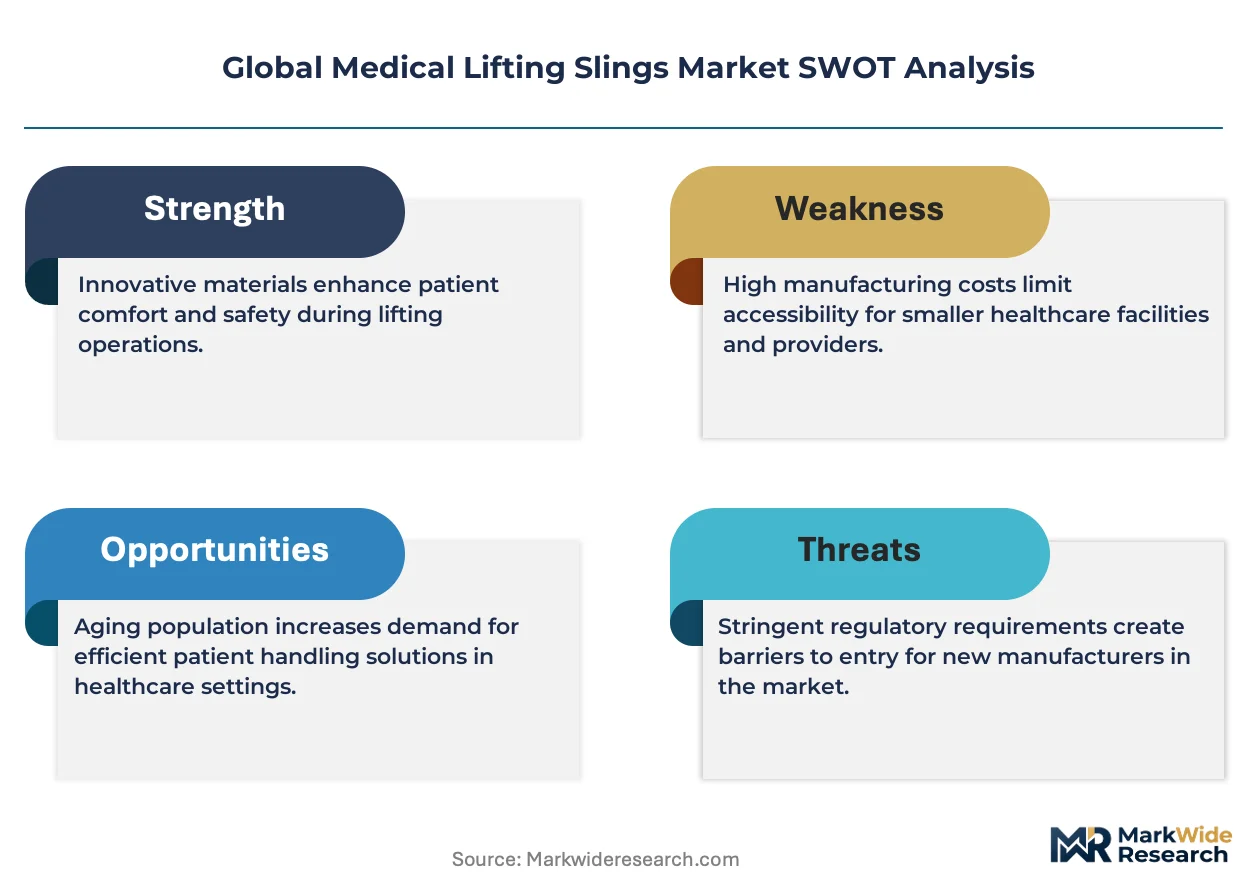
ISO 10535 certification requirements are compressing the vendor base in medical lifting slings by mandating third-party load testing and traceable manufacturing records that smaller textile converters cannot sustain.
Growth Catalysts
- Medicare reimbursement expansion:CMS additions to durable medical equipment codes for safe patient handling devices in home settings are pulling procurement volume toward residential channels in the United States.
- Mesh fabric protocols:Infection control departments in acute care facilities are specifying antimicrobial mesh constructions that withstand autoclave cycles, accelerating material substitution.
- Germany's Pflegeversicherung:Long-term care insurance coverage for bariatric slings is expanding eligible patient populations and normalizing higher-specification purchases.
Market Restraints
- Polyester staple fiber volatility:Medical-grade polyester feedstock prices fluctuate with crude oil benchmarks, compressing margin stability for sling manufacturers without captive textile operations.
- Single-source stitching equipment:Automated bar-tack machines for load-bearing seams concentrate with German and Japanese capital equipment suppliers, creating supply concentration risk.
- EU MDR compliance timelines:Extended notified body review periods for Class I medical devices are delaying product line refreshes and freezing SKU rationalization decisions.
Strategic Opportunities
- Japan's super-aging prefectures:Rural municipalities in Akita and Shimane are piloting sling pooling programs that create service-based revenue models beyond equipment sales.
- Pediatric rehabilitation:Custom-configured slings for cerebral palsy and muscular dystrophy patients represent an underserved specification tier with limited incumbent focus.
- CE-MDR mutual recognition:Streamlined conformity assessment pathways between EU and select ASEAN markets are reducing duplicate testing costs for exporters.
Industry Challenges
- Biomechanical assessment training:Safe sling selection requires certified occupational therapist evaluation, and workforce shortages in this function are extending sales cycles.
- Legacy lift compatibility:Proprietary attachment hook geometries from established patient lift manufacturers force sling vendors to maintain multiple connector variants per SKU.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Lifting Slings Market |
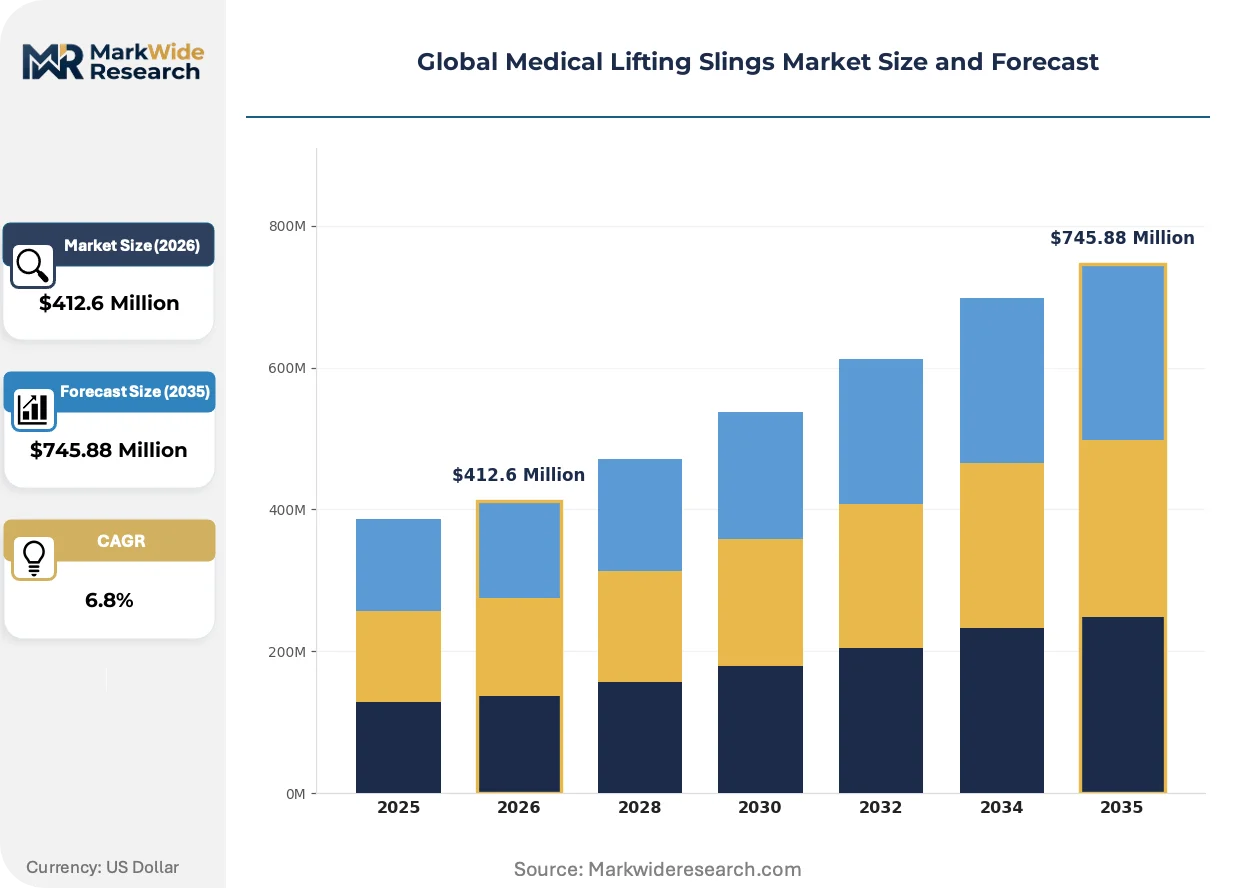
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Slings, Bariatric Slings, Hammock Slings, Toilet Slings, Stand Assist Slings Material: Cotton, Polyester, Nylon, Mesh Fabric, Blended Fabrics Application: Patient Transfer, Bathing Assistance, Rehabilitation Support, Seating Assistance, Mobility Aid End User: Hospitals, Nursing Homes, Rehabilitation Centers, Home Care Providers, Assisted Living Facilities |
| Companies Covered | Arjo, Invacare Corporation, Baxter (Hill-Rom), Joerns Healthcare, V. Guldmann A/S, Etac AB, Prism Medical, DJO Global, Drive DeVilbiss Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Lifting Slings Market Shifts & Advancements
Material science advances and regulatory harmonization efforts are restructuring how medical lifting slings are specified, procured, and maintained across acute and post-acute settings.
Antimicrobial silver-ion mesh fabrics are displacing conventional polyester constructions in hospital procurement specifications. Infection control committees in tertiary care centers are mandating launderable mesh with documented bacterial load reduction. This material shift is compressing order volumes for traditional padded sling inventories as facilities consolidate toward single-fabric protocols.
REACH chemical restrictions on per- and polyfluoroalkyl substances are forcing reformulation of water-repellent fabric treatments used in sling manufacturing. ECHA's 2023 restriction proposals are accelerating substitution toward silicone-based alternatives. European manufacturers are responding with redesigned coating lines, while importers face stranded inventory risks from legacy-treated stock.
Hospital group purchasing organizations are consolidating supplier panels and demanding real-time utilization data through RFID-tagged sling fleets. This behavioral shift is displacing spot purchasing through distributor channels with multi-year managed service agreements. The United Kingdom's NHS Supply Chain is most advanced in this transition, with acute trusts standardizing on single-source sling provision with embedded laundering logistics.
Global Medical Lifting Slings Market Segmentation
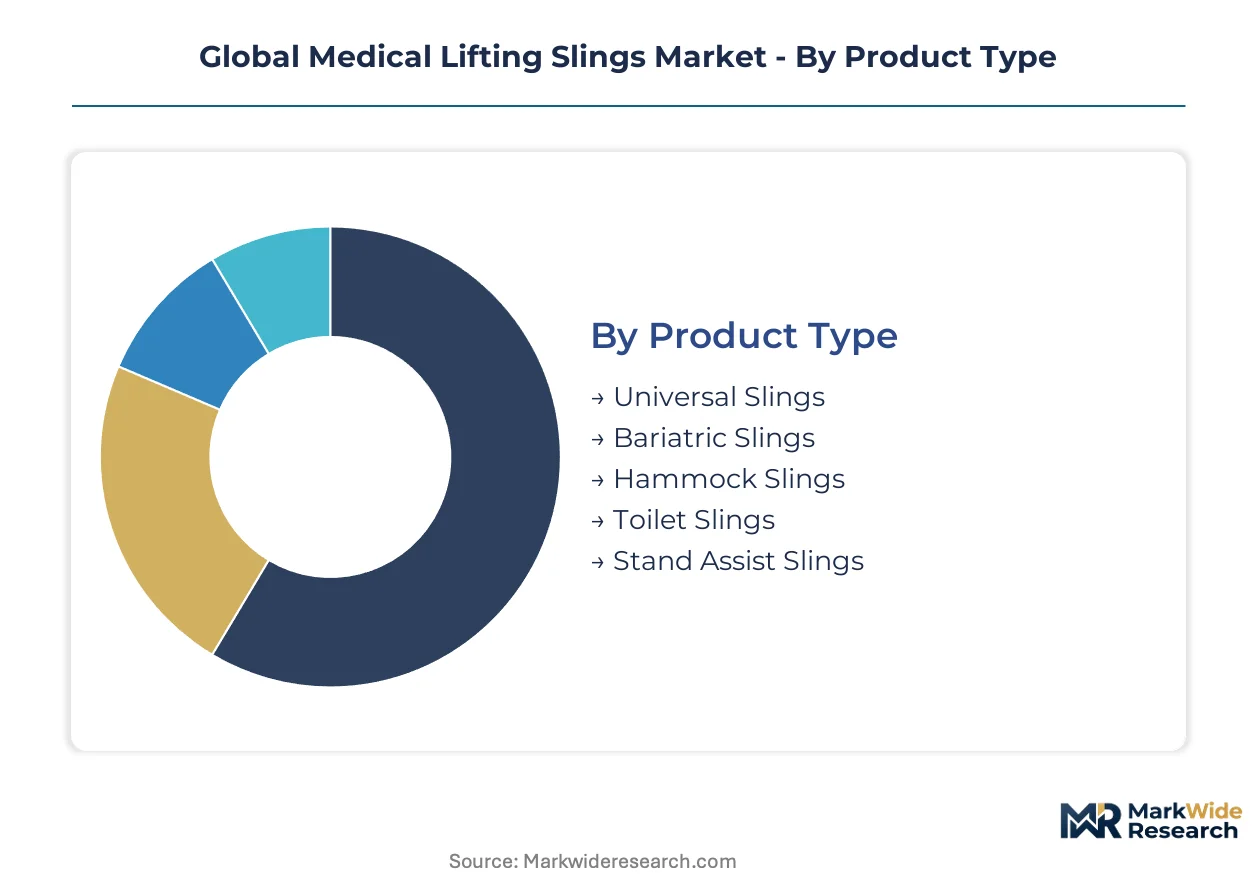
Product specification, material certification, and care setting requirements create distinct procurement channels for medical lifting slings. Understanding how segments map to reimbursement codes and infection control protocols reveals where margin pools concentrate.
Product Type:
Universal slings flow through distributor networks to institutional buyers, while bariatric and specialized configurations often route direct to hospital material management or home medical equipment dealers.
- Universal Slings:Constructed with four to six attachment points and standardized safe working loads, these accommodate 80-90% of patient transfer scenarios. Acute care hospitals in the United States and Germany specify these for general ward inventory due to Medicare and Pflegeversicherung reimbursement alignment.
- Bariatric Slings:Engineered with reinforced webbing and wider load distribution panels rated for patients exceeding 350 pounds. Long-term care facilities in Japan's super-aging prefectures are expanding procurement as obesity rates climb among elderly populations.
- Hammock Slings:Full-body support design with head and thigh containment for dependent patients. Rehabilitation centers favor these for post-surgical transfer protocols.
- Toilet Slings:Open-bottom construction enabling hygiene access without full removal. Home care providers in OECD markets specify these for aging-in-place installations.
- Stand Assist Slings:Torso and underarm support for partial-weight-bearing mobilization. Physical therapy departments prioritize these for early rehabilitation programs.
Universal slings dominate installed base. Bariatric configurations are where expansion concentrates.
Material:
Cost tiers separate commodity textiles from certified medical-grade constructions, with acute care buyers paying premiums for validated infection control properties.
- Mesh Fabric:Open-weave polyester or nylon construction permitting airflow and rapid drying, treated with antimicrobial silver-ion formulations. Tertiary care centers in the United Kingdom and Australia mandate these for autoclave-compatible fleet management.
- Polyester:Medical-grade staple fiber with controlled denier and tenacity specifications, offering durability at moderate cost points. German nursing homes source these through regional textile converters with ISO 10535 certification.
- Cotton:Natural fiber construction prioritized for skin sensitivity in pediatric and geriatric applications. Home care channels in France and Italy favor these for patient comfort perception.
- Nylon:High-tenacity filament yarn with superior abrasion resistance for high-frequency institutional use. Japanese hospital group purchasing organizations specify these for multi-year service contracts.
- Blended Fabrics:Cotton-polyester or cotton-nylon combinations balancing comfort and durability. Assisted living facilities in Canada procure these for moderate-use environments.
Mesh fabric claims the steepest expansion trajectory. Polyester retains volume leadership across reimbursement-constrained channels.
Application:
Customer type determines specification depth, with hospitals demanding full biomechanical documentation while home care buyers prioritize intuitive selection.
- Patient Transfer:Core function spanning bed-to-chair, chair-to-toilet, and lateral repositioning scenarios. All sling types serve this application, driving standardization efforts among GPOs.
- Rehabilitation Support:Early mobilization and gait training applications requiring specialized stand-assist and ambulation sling configurations. Rehabilitation centers in Germany and Switzerland invest here.
- Bathing Assistance:Water-compatible mesh constructions for tub and shower transfer. Long-term care facilities specify these for hygiene protocol compliance.
- Seating Assistance:Sling-to-wheelchair integration for pressure redistribution. Pressure injury prevention committees in Australian hospitals drive procurement.
- Mobility Aid:Ambulation support and fall recovery applications. Home care providers in Japan's rural municipalities pilot sling pooling for this use case.
Patient transfer commands the largest addressable base. Rehabilitation support is gaining share fastest among specialized providers.
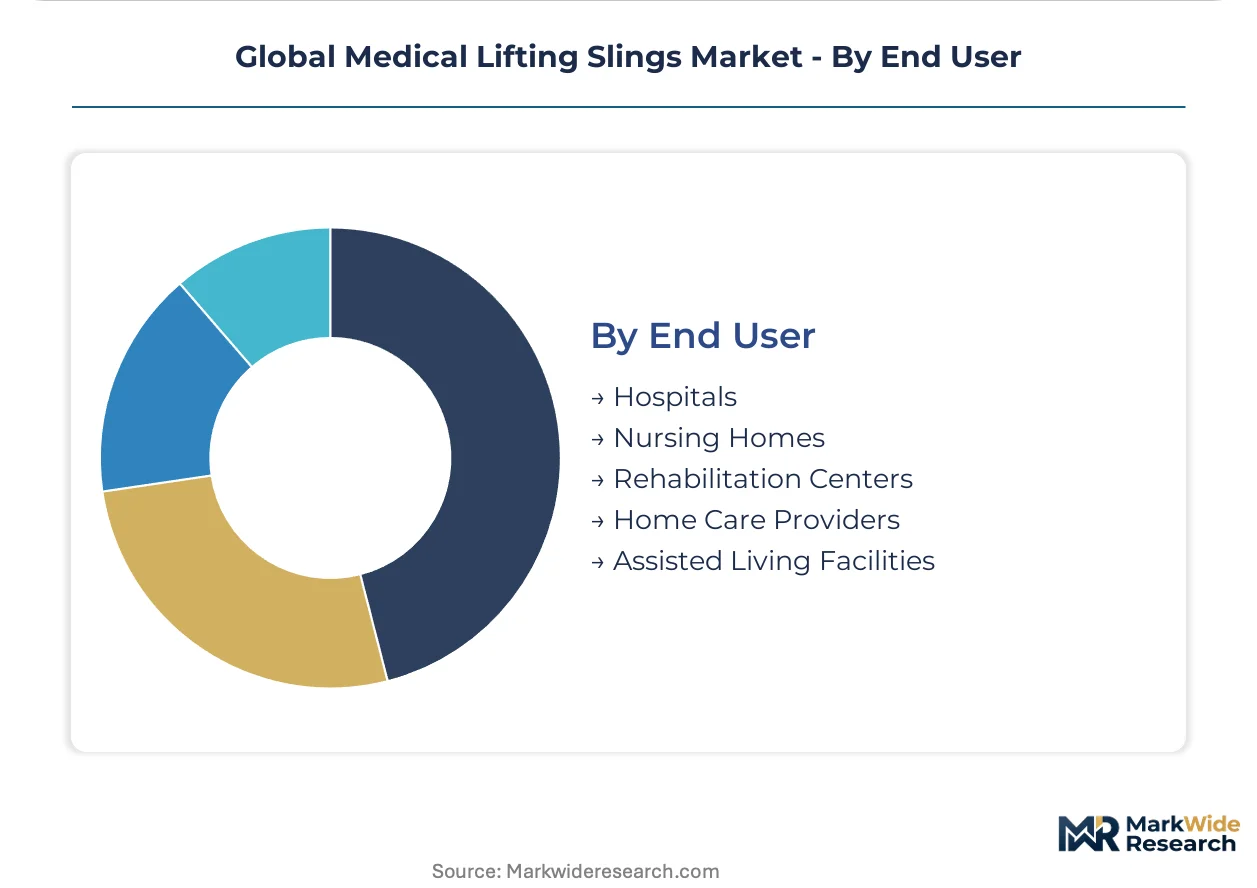
End User:
Volume concentration and margin structure diverge sharply between institutional procurement with embedded laundering services and retail-equivalent home care transactions.
- Hospitals:Acute care facilities with infection control committees, RFID fleet tracking, and multi-year managed service agreements. NHS Supply Chain in the United Kingdom and Vizient in the United States shape specifications.
- Home Care Providers:Durable medical equipment suppliers and visiting nurse organizations serving aging-in-place populations. Medicare reimbursement code expansions are accelerating channel growth.
- Nursing Homes:Long-term care facilities with high patient-to-staff ratios requiring efficient transfer protocols. Germany's Pflegeversicherung coverage directly enables procurement.
- Rehabilitation Centers:Post-acute facilities with physical therapy departments specifying custom configurations for neurological and orthopedic recovery.
- Assisted Living Facilities:Residential care settings with lighter medical acuity, prioritizing comfort and ease of use over clinical specifications.
Hospitals anchor procurement volume. Home care providers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics corridor underwrites European distribution efficiency for textile-based patient handling equipment. Container throughput at this hub connects Nordic manufacturers to German clinical supply chains.
United States
Medicare's durable medical equipment reimbursement expansion is pulling procurement volume toward home care channels. The FDA's 510(k) clearance pathway shapes product development timelines for domestic and imported slings alike. Hospital group purchasing organizations in the Midwest and Southeast are consolidating supplier panels with embedded RFID fleet tracking.
Germany
Pflegeversicherung coverage for bariatric slings is normalizing higher-specification purchases across long-term care facilities. The EU MDR compliance timeline is delaying product line refreshes for Class I medical devices. North Rhine-Westphalia's textile engineering cluster hosts ISO 10535-certified converters serving Benelux acute care networks.
Japan
Super-aging prefectures including Akita and Shimane are piloting sling pooling programs that create service-based revenue models. PMDA quality management requirements elevate compliance costs for market entry. The Kanto region's hospital group purchasing organizations specify high-tenacity nylon constructions for multi-year service contracts.
United Kingdom
NHS Supply Chain is standardizing acute trusts on single-source sling provision with embedded laundering logistics. REACH chemical restrictions on per- and polyfluoroalkyl substances are forcing fabric treatment reformulation. The Midlands manufacturing belt supplies antimicrobial mesh constructions to tertiary care centers nationwide.
Australia
Pressure injury prevention committees in New South Wales and Victoria hospitals are driving procurement for sling-to-wheelchair integration. The TGA's alignment with ISO 10535 certification streamlines conformity assessment for imported equipment. Melbourne's aged care infrastructure expansion is accelerating distributor channel consolidation.
Global Medical Lifting Slings Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and manufacturing scale. The vendor base compresses around ISO 10535 compliance capabilities that smaller textile converters cannot sustain. Three archetypes dominate: vertically integrated European manufacturers with captive textile operations, Nordic design-focused specialists emphasizing ergonomic configuration, and North American distributors leveraging group purchasing organization relationships. Consolidation concentrates through multi-year managed service agreements and RFID-enabled fleet management contracts.
Among Nordic specialists, V. Guldmann A/S and Etac AB exemplify the design-standard archetype with rehabilitation-specific positioning. Arjo represents the scale-integrated tier with manufacturing footprints spanning multiple continents. These anchors illustrate how premium positioning correlates with certification depth and captive supply chain control rather than spot-market textile sourcing.
| Leading Market Players |
|---|
| Arjo |
| Invacare Corporation |
| Baxter (Hill-Rom) |
| Joerns Healthcare |
| V. Guldmann A/S |
| Etac AB |
| Prism Medical |
| DJO Global |
| Drive DeVilbiss Healthcare |
| Others |
Supply & Pricing Matrix
Antimicrobial silver-ion mesh fabrics displacing conventional polyester constructions are redrawing supply geography toward Nordic and UK textile engineering clusters while compressing margin pools for commodity converters. This material transition simultaneously elevates certification costs and concentrates procurement power with hospital group purchasing organizations that specify validated infection control properties.
Pricing Analysis
Certification level creates the primary spread between ISO 10535-validated premium slings and uncertified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects safe working load ratings, antimicrobial treatment validation, and after-sales service bundling. Cost compression in the economy tier intensifies because REACH chemical restrictions force reformulation of water-repellent coatings. Home care providers exhibit highest price sensitivity due to reimbursement code constraints, while NHS Supply Chain and Vizient demonstrate lowest sensitivity when RFID fleet tracking and laundering logistics are embedded.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are elevating inbound logistics costs for polyester staple fiber shipments from Chinese and South Korean chemical fiber producers. Manufacturing concentrates in Germany, the United Kingdom, and Sweden where ISO 10535-certified textile converters maintain captive dyeing and finishing operations. Raw material dependencies draw from medical-grade polyester feedstock, high-tenacity nylon filament, and silver-ion antimicrobial treatments. Single-source vulnerability concentrates with German and Japanese automated bar-tack equipment suppliers. Distribution runs through hospital group purchasing organizations and durable medical equipment dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from reusable-to-disposable pivot demands and service-based pooling models that displace equipment ownership economics.
For Market Incumbents: Fortify certification depth by accelerating EU MDR technical documentation for Class I device reclassifications. Secure backward integration into antimicrobial mesh weaving to defend margin position against REACH-driven coating cost inflation. Counter Japanese sling pooling pilots by embedding RFID-enabled fleet management into multi-year service contracts. For New Entrants and Emerging Players: Differentiate on pediatric rehabilitation configurations where cerebral palsy and muscular dystrophy specifications remain underserved by incumbent portfolios. Target Germany's Pflegeversicherung reimbursement expansion for bariatric sling direct procurement. Pursue Nordic design partnerships to anchor ergonomic credibility before scaling manufacturing footprint. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive textile operations over distributor-dependent assemblers. Long-term viability hinges on compliance infrastructure amortization across multi-year managed service agreements. Acquisition target archetype: ISO 10535-certified regional converters with established GPO relationships. Monitor CE-MDR mutual recognition progress with ASEAN regulators as inflection indicator for export scalability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German Pflegeversicherung reimbursement channels. |
| Hospital System Partnership | NHS Supply Chain single-source agreements displace spot distributor purchasing. |
| Software Companion Development | RFID fleet tracking enables utilization-based service revenue models. |
| Reimbursement Strategy | Medicare DME code alignment pulls volume toward home care channels. |
| Backward Integration | Captive antimicrobial mesh production defends against REACH coating cost spikes. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases preceded structured interviews with biomedical engineers, GPO contracts managers, and long-term care facility purchasing directors. Secondary validation drew from CMS reimbursement code updates, NHS Supply Chain tender records, and Japanese Ministry of Health sling pooling pilot documentation. Bottom-up unit demand estimates triangulated against top-down reimbursement expenditure flows.
Analytical variance decomposes across product type, material certification tier, end-user channel, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from segmented unit volume projections applied to price trajectories indexed to polyester feedstock volatility and certification cost inflation. Modeled inputs include ISO 10535 adoption curves, REACH chemical restriction implementation timelines, and Medicare DME code expansion schedules.
Material uncertainties — EU MDR notified body capacity constraints, crude oil benchmark swings affecting polyester staple fiber, and super-aging prefecture pooling program scalability — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as REACH restriction enforcement intensity and ASEAN mutual recognition pathway finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Biomedical Refrigerators and Freezers Market
Medical Equipment
Autoclaves Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Ultrasound Equipment Market
Medical Equipment
Operating Table Market
Medical Equipment
Surgical Lighting System Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Cryochambers Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Home Medical Equipment Market
Medical Equipment
Cell Culture Incubator Market
Medical Equipment
Water Bath Market
Medical Equipment
Medical Equipment Calibration Services Market
Medical Equipment
New-Born Screening Equipment Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Refurbished MRI Systems Market