
 Global Laminar Airflow Cabinets Market | 2026-2036
Global Laminar Airflow Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laminar Airflow Cabinets Market Foresight
Multi-source procurement for HEPA filtration assemblies is pivoting toward captive in-house production among leading cabinet manufacturers. Thermo Fisher Scientific leverages its vertically integrated supply chain for critical airflow components. Esco Lifesciences Group anchors its competitive position through specialized biosafety and laminar product lines across Asia-Pacific and European installations. Labconco Corporation differentiates via stringent quality protocols and dedicated channel control in North American research markets.
Laminar airflow cabinets are enclosed workstations that deliver filtered air in a unidirectional stream to protect samples, operators, or both from particulate contamination, typically achieving ISO Class 5 cleanliness with face velocities between 0.3 and 0.5 meters per second. Vertical cabinet configurations dominate pharmaceutical and biotechnology installations due to superior operator protection and ergonomic access, while portable systems represent the fastest-expanding category driven by field diagnostics and decentralized manufacturing trends. HEPA filtration technology sustains the largest installed base, though ULPA systems are capturing margin pools in semiconductor and nanotechnology applications where sub-0.3-micron particle retention proves critical.
FDA cGMP guidelines, EMA Annex 1 sterile manufacturing requirements, and ISO 14644 cleanroom standards collectively mandate validated airflow performance and documented contamination control for cabinet installations in regulated industries. These frameworks compel end users to replace legacy units and adopt electronic monitoring systems that log real-time pressure differential and filter integrity data. Stakeholders must monitor evolving EU GMP Annex 1 revisions and semiconductor fab expansion cycles to align capacity planning with certification-intensive procurement timelines.
Market Dynamics
HEPA filtration supply concentration and semiconductor cleanroom expansion cycles are compressing procurement timelines while forcing end users toward validated electronic monitoring systems. Manufacturers must synchronize capacity with certification-intensive replacement waves.
Growth Catalysts
- EMA Annex 1 sterile manufacturing mandates:Pharmaceutical facilities across Europe are replacing legacy laminar airflow units to meet revised contamination control requirements. This drives demand for ISO 14644-compliant cabinets with documented filter integrity protocols.
- Semiconductor fabrication investments:South Korea, Germany, and the United States are expanding cleanroom infrastructure for advanced chip manufacturing. ULPA-grade laminar systems capture this demand for sub-0.3-micron particle retention.
- Field diagnostics proliferation:Portable laminar airflow configurations serve decentralized pharmaceutical manufacturing and point-of-care testing expansion. These systems address contamination control outside traditional fixed-facility environments.
Market Restraints
- Specialized HEPA media supply concentration:A limited supplier base controls high-efficiency filtration media production. Disruptions in glass microfiber supply chains compress manufacturer margins and extend lead times.
- Validation protocol costs:FDA cGMP and EMA Annex 1 compliance requires extensive documentation, on-site certification, and ongoing filter integrity monitoring. Small research laboratories defer replacement purchases due to qualification expense burdens.
- UV-C decontamination substitution:Some biotechnology applications adopt ultraviolet-based surface sterilization as an alternative to continuous laminar airflow protection. This displaces cabinet demand in non-sterile compounding workflows.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO regulatory alignment with international standards and PLI scheme incentives attract sterile formulation investments. Domestic laminar cabinet demand follows contract manufacturing organization growth.
- Real-time monitoring convergence:Integration of pressure differential sensors with facility management systems enables predictive filter replacement. This technology pairing creates service revenue streams beyond equipment sales.
- Modular cleanroom architectures:Prefabricated isolator systems incorporating laminar airflow modules reduce construction timelines for cell therapy manufacturing. These integrated solutions penetrate gene therapy facility buildouts.
Industry Challenges
- Certified technician scarcity:Qualified personnel for HEPA filter testing and cabinet requalification are concentrated in metropolitan manufacturing clusters. Remote facilities face extended service response times.
- Legacy system integration complexity:Electronic monitoring retrofits for installed base cabinets require analog-to-digital sensor adaptation. Pharmaceutical quality teams struggle with data integrity documentation across mixed-vendor environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laminar Airflow Cabinets Market |
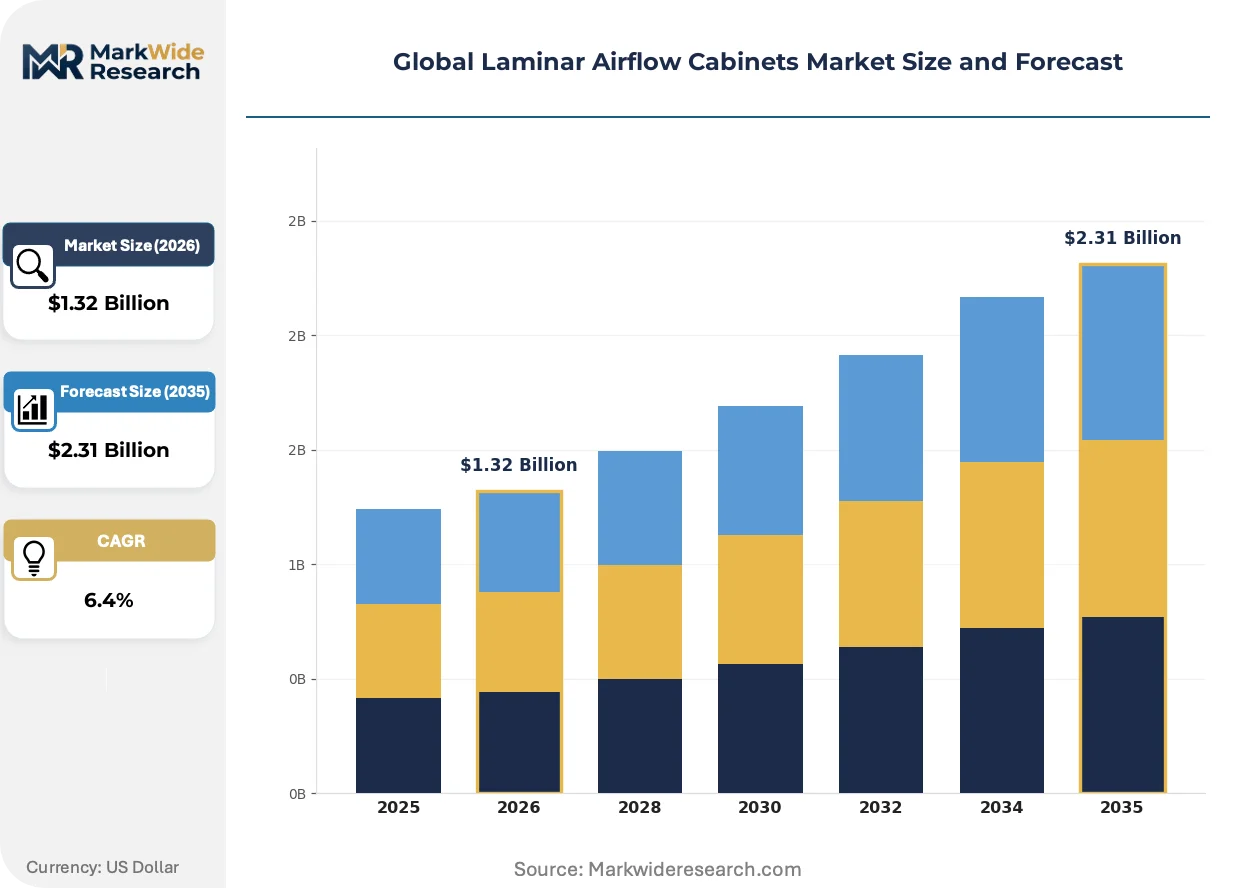
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Cabinets, Vertical Cabinets, Portable Cabinets, Customized Cabinets Technology: HEPA Filtration, ULPA Filtration, UV Sterilization, Electronic Monitoring Systems Application: Pharmaceutical Manufacturing, Biotechnology Research, Semiconductor Assembly, Food Processing End User: Research Facilities, Quality Control Labs, Cleanroom Operators, Production Units |
| Companies Covered | Thermo Fisher Scientific, Esco Lifesciences Group, Esco Micro Pte. Ltd, Telstar (Azbil Corporation), Biobase Group, Labconco Corporation, NuAire, Inc., Lamsystems, AirClean Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laminar Airflow Cabinets Market Shifts & Advancements
Connectivity architectures and filtration media advances are transforming laminar airflow cabinets from passive containment devices into integrated contamination control nodes. Equipment vendors compete on data interoperability and service attach rates rather than hardware specifications alone.
Smart sensor arrays embedded in cabinet plenums now stream real-time velocity, pressure differential, and filter loading data to building automation systems. Biopharmaceutical quality teams in Massachusetts and North Carolina facilities adopt these networked configurations to satisfy FDA data integrity expectations. This connectivity layer is decentralizing monitoring responsibility from centralized HVAC teams to production floor operators.
EU GMP Annex 1 revisions finalized in 2022 mandate continuous viable and non-viable particle monitoring in Grade A environments. German and Swiss pharmaceutical manufacturers accelerate cabinet replacement cycles to incorporate integrated environmental monitoring probes. The regulation compresses equipment lifecycles from fifteen to ten years in sterile fill-finish applications.
Leasing and managed service contracts displace capital purchase models among mid-sized contract research organizations. European academic medical centers and North American biotechnology startups favor operational expenditure structures that bundle preventive maintenance and filter replacement. This financing shift concentrates purchasing authority with distributor networks rather than end-user procurement departments.
Global Laminar Airflow Cabinets Market Segmentation
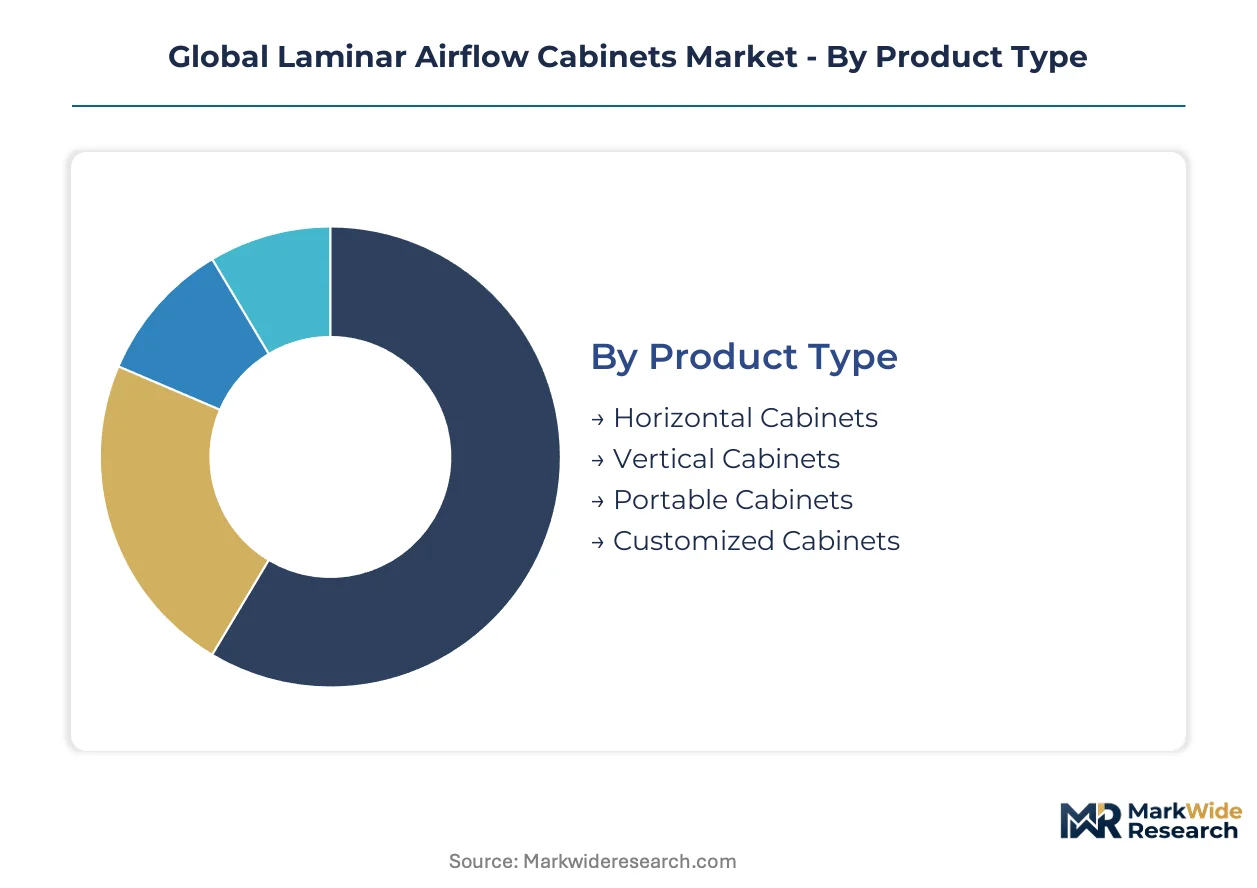
Product configuration and filtration technology determine compliance pathways and capital allocation for laminar airflow cabinet procurement. End-user operational scale and regulatory exposure further stratify demand across fixed-installation and field-deployable systems.
Product Type:
Facility layout constraints and operator protection requirements drive divergent specification patterns across pharmaceutical and research installations.
- Horizontal Cabinets:These systems direct filtered air horizontally across the work surface toward the operator, suited for cleanroom environments where product protection outweighs personnel safety needs. Demand concentrates in semiconductor cleanrooms across South Korea and Germany where ISO Class 5 particle control supports wafer handling protocols. FDA cGMP documentation requirements for sterile manufacturing sustain replacement cycles in United States pharmaceutical facilities.
- Vertical Cabinets:Downward airflow creates a protective barrier between operators and sensitive materials, dominating biotechnology and pharmaceutical applications. Installations across Massachusetts and North Carolina biopharmaceutical clusters prioritize vertical configurations for ergonomic access during extended compounding operations. EMA Annex 1 Grade A environment mandates accelerate cabinet refresh timelines in Swiss and German sterile fill-finish facilities.
- Portable Cabinets:Mobile units with castor-mounted frames serve decentralized manufacturing and point-of-care diagnostics outside traditional fixed facilities.
- Customized Cabinets:Purpose-built dimensions and integrated isolator configurations address cell therapy manufacturing and gene therapy facility buildouts.
Volume sits with Vertical Cabinets; growth tilts toward Portable Cabinets.
Technology:
Filtration performance thresholds and data integrity capabilities separate premium installations from standard configurations.
- HEPA Filtration:High-efficiency particulate air systems retain 99.97% of particles at 0.3 microns, forming the installed base across pharmaceutical quality control laboratories. Replacement filter procurement and validation protocols create recurring revenue attachment for manufacturers serving United States and European research markets. Glass microfiber supply concentration constrains margin expansion for cabinet producers dependent on external media sourcing.
- ULPA Filtration:Ultra-low penetration air technology achieves 99.999% retention at 0.12 microns, capturing demand in semiconductor nanofabrication and advanced materials research. South Korean and German chip manufacturing investments prioritize ULPA-grade laminar systems for sub-0.3-micron contamination control. ISO 14644-1 Class 3 and Class 4 cleanroom specifications mandate this filtration tier for critical process zones.
- UV Sterilization:Ultraviolet-C lamp integration provides secondary surface decontamination in non-sterile compounding workflows.
- Electronic Monitoring Systems:Real-time pressure differential and velocity sensors enable predictive maintenance and FDA data integrity compliance.
HEPA Filtration dominates installed value; ULPA Filtration is climbing the fastest.
Application:
Regulatory stringency and contamination consequence severity shape technology selection and replacement frequency.
- Pharmaceutical Manufacturing:Sterile processing operations under FDA cGMP and EMA Annex 1 mandate validated airflow performance with documented filter integrity. Fill-finish lines across India and Ireland contract manufacturing organizations drive cabinet demand aligned with CDSCO and EMA regulatory convergence. Continuous viable particle monitoring requirements compress equipment lifecycles in Grade A environments.
- Biotechnology Research:Cell culture and gene therapy development require unidirectional airflow protection for sensitive biological materials. Academic medical centers and startup laboratories across California and Massachusetts favor operational expenditure models bundling maintenance and filter replacement.
- Semiconductor Assembly:Wafer handling and packaging operations demand sub-micron particle control in ISO Class 5 and cleaner environments.
- Food Processing:Aseptic packaging and quality testing applications adopt laminar airflow systems for microbial contamination prevention.
Pharmaceutical Manufacturing commands the largest capital allocation; Biotechnology Research exhibits the steepest expansion trajectory.
End User:
Procurement authority and compliance burden intensity vary systematically across organizational types.
- Research Facilities:Universities and government laboratories balance specification requirements against capital constraints. European academic medical centers increasingly favor leasing structures over direct purchase. Validation protocol costs defer replacement decisions at smaller research institutions.
- Quality Control Labs:Analytical testing and release laboratories require documented contamination control for regulatory submission support.
- Cleanroom Operators:Dedicated facility management organizations standardize cabinet specifications across multiple manufacturing suites.
- Production Units:Manufacturing floor installations prioritize ergonomic integration and minimal downtime during filter replacement.
Quality Control Labs anchor replacement demand; Research Facilities are gaining share fastest through service-contract conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass microfiber supply concentration in Germany and advanced semiconductor substrate production in South Korea anchor regional demand patterns for certified laminar airflow systems across pharmaceutical and electronics manufacturing clusters.
United States
Biopharmaceutical manufacturing expansion across Massachusetts and North Carolina drives vertical cabinet installations for sterile compounding workflows. FDA cGMP documentation requirements and data integrity mandates accelerate replacement cycles for legacy units without electronic monitoring capabilities. The Greater Boston cluster concentrates gene therapy facility buildouts requiring ISO 14644-compliant containment systems.
Germany
Semiconductor wafer handling and pharmaceutical fill-finish operations sustain dual demand streams for ULPA and HEPA filtration configurations. EU GMP Annex 1 revisions finalized in 2022 compress equipment lifecycles from fifteen to ten years in Grade A environments. The Baden-Württemberg region anchors precision manufacturing supply chains for filtration media and cabinet components.
South Korea
Advanced chip fabrication investments by Samsung Electronics and SK Hynix prioritize sub-0.3-micron particle control in ISO Class 3 and Class 4 cleanroom zones. MFDS alignment with international pharmaceutical manufacturing standards supports parallel demand from domestic biologics producers. The Yongin-Suwon corridor concentrates new fab construction requiring ULPA-grade laminar systems.
India
Contract manufacturing organization growth under CDSCO regulatory convergence attracts sterile formulation investments from global pharmaceutical sponsors. PLI scheme incentives for active pharmaceutical ingredients expand cleanroom capacity across Maharashtra and Gujarat. The Hyderabad-Visakhapatnam corridor anchors bulk drug production requiring validated airflow protection.
Switzerland
Specialized biologics manufacturing and precision pharmaceutical packaging sustain premium-tier cabinet demand with integrated environmental monitoring. Swissmedic enforcement of EU GMP Annex 1 equivalent standards mandates continuous viable particle detection in Grade A operations. The Basel region concentrates Novartis and Roche sterile processing facilities driving replacement procurement.
Global Laminar Airflow Cabinets Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers synchronize production lines with semiconductor fab construction cycles and pharmaceutical facility buildouts. The vendor base stratifies across three tiers: diversified laboratory equipment conglomerates with captive filtration supply chains, specialized cleanroom containment fabricators with regional installation expertise, and modular isolator integrators targeting cell therapy manufacturing. Strategic differentiation concentrates on electronic monitoring system interoperability and service contract attach rates rather than hardware specifications alone. M&A activity and backward integration into HEPA media production represent the dominant competitive moves reshaping supplier economics.
Among diversified equipment conglomerates, Thermo Fisher Scientific occupies a position exemplifying vertical control over critical airflow components through in-house production capabilities. Esco Lifesciences Group and Esco Micro Pte. Ltd. represent the specialized fabricator archetype with concentrated presence across Asia-Pacific and European installations. Labconco Corporation anchors the quality-focused tier with dedicated channel control in North American research markets. These named entities illustrate how competitive positioning stratifies around supply chain configuration, geographic focus, and regulatory compliance depth rather than product differentiation alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Esco Lifesciences Group |
| Esco Micro Pte. Ltd |
| Telstar (Azbil Corporation) |
| Biobase Group |
| Labconco Corporation |
| NuAire, Inc. |
| Lamsystems |
| AirClean Systems |
| Others |
Supply & Pricing Matrix
Contract manufacturing organizations in India and Ireland concentrate procurement authority for certified laminar airflow cabinets, compressing vendor margins through consolidated volume tenders while elevating total-cost-of-ownership evaluation over unit price alone. This buyer archetype concentration forces manufacturers toward service-bundled pricing models that capture lifetime filter replacement and validation protocol revenue.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier suppliers from transaction-focused competitors in laminar airflow cabinet procurement. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by ISO 14644 certification grade and electronic monitoring integration. Cost compression in the economy tier intensifies because glass microfiber supply constraints limit margin flexibility for HEPA-dependent producers. Small research laboratories exhibit highest price sensitivity due to validation expense burdens, while semiconductor fabs demonstrate lowest sensitivity given contamination consequence severity.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and South Korea's semiconductor self-sufficiency initiatives are reshaping sourcing patterns for critical filtration assemblies. Glass microfiber media production concentrates in Germany, China, and the United States, while cabinet fabrication draws from Malaysia, Singapore, and regional European hubs. Single-source vulnerability in specialized HEPA media supply chains threatens manufacturer margins when disruptions occur. Distribution runs through authorized distributor networks with certified installation capabilities rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminar airflow cabinet market is a vertical-integration race where captive control over HEPA filtration media production determines margin sustainability and supply security.
For Market Incumbents: Anticipate semiconductor fab construction cycles in South Korea and Germany by pre-positioning ULPA-certified inventory and certified technician networks. Backward integration into glass microfiber media production defends margin position against supply concentration risks. Electronic monitoring system interoperability investment locks in biopharmaceutical replacement demand under FDA data integrity mandates. For New Entrants and Emerging Players: Enter via modular isolator integration partnerships for cell therapy manufacturing buildouts in Massachusetts and North Carolina. Field-deployable portable cabinets for decentralized pharmaceutical manufacturing represent the most penetrable white-space segment. Go-to-market execution should emphasize operational expenditure leasing structures that bundle preventive maintenance and filter replacement for mid-sized contract research organizations. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized cleanroom containment fabricators with regional installation expertise in Asia-Pacific expansion corridors. Long-term viability hinges on service contract attach rates and recurring filter revenue rather than hardware shipment volume. Watch for EU GMP Annex 1 enforcement intensity in German and Swiss pharmaceutical clusters as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filtration Media | Captive HEPA glass microfiber production secures margin control against German supply concentration. |
| Electronic Monitoring System Integration | Real-time pressure differential sensors satisfy FDA data integrity expectations in Massachusetts biopharmaceutical facilities. |
| Leasing and Managed Service Contracts | Operational expenditure structures attract European academic medical centers and North American biotechnology startups. |
| Modular Isolator Partnerships | Prefabricated cell therapy containment solutions penetrate gene therapy facility buildouts across Greater Boston. |
| Certified Technician Network Expansion | Qualified HEPA filter testing personnel concentration reduces service response times for remote pharmaceutical installations. |
Research Methodology
Multi-period observation of semiconductor fab construction permits, pharmaceutical facility buildout announcements, and HEPA filter import volumes anchored the trend analysis, supplemented by interviews with cleanroom engineering directors, pharmaceutical quality assurance managers, biomedical equipment procurement officers, and certified HEPA filter testing technicians. Secondary validation drew from FDA cGMP inspection observations, EMA Annex 1 revision documentation, ISO 14644 certification records, and customs trade data for filtration media imports. Bottom-up equipment shipment tracking and top-down cleanroom capital expenditure analysis provided triangulation.
Segment-weighting across product configuration, filtration technology, application vertical, and end-user organizational type informed the analytical framework across the analysis window. CAGRs derived from facility expansion pipeline analysis and replacement cycle modeling for legacy cabinet installations. Forecast inputs incorporated EU GMP Annex 1 compliance timeline assumptions and semiconductor cleanroom ISO Class 3/4 specification adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended HEPA media supply disruptions or accelerated UV-C sterilization substitution in non-sterile workflows. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Portable Steam Autoclave Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Patient Lifting Equipment Market
Medical Equipment
Diathermy Equipment Market
Medical Equipment
China Radiotherapy Market
Medical Equipment
Brazil Massage Equipment Market
Medical Equipment
Global Hospital Equipment and Supplies Market
Medical Equipment
Fluoroscopy Equipment Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Global Platelet Agitator Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Global Optometry Equipment Market
Medical Equipment
North America Nuclear Medicine Equipment Market
Medical Equipment
Global Mobile Operating Tables Market