
 Cryochambers Market | 2026-2036
Cryochambers Market Size, Share, and Industry Trends Forecast 2026-2036
Cryochambers Market Analysis
Buyer concentration is fragmenting across wellness spas and boutique recovery studios is repositioning procurement dynamics toward smaller, mobile units. Cryomed leverages its electric-cooling technology leadership to serve high-volume fitness chains. MECOTEC GmbH anchors German-speaking European markets through localized service networks. Zimmer MedizinSysteme GmbH competes on clinical-grade certification breadth across hospital procurement channels.
Cryochambers are enclosed thermal treatment systems that expose the body to controlled temperatures between minus 110 degrees Celsius and minus 160 degrees Celsius using nitrogen vapor or electric refrigeration cycles, primarily to reduce inflammation, accelerate muscle recovery, and manage chronic pain conditions. Whole-body installations command the largest installed base but mobile units represent the fastest expansion trajectory as rental and pop-up models penetrate secondary cities. Electric technology segments attract capital due to lower operational hazards and reduced nitrogen supply dependency, while nitrogen-based systems dominate existing clinical infrastructure where cryogen logistics are established.
The FDA classifies whole-body cryotherapy devices under evolving medical device guidance, compelling manufacturers to substantiate safety claims through clinical evidence. Germany's KBA-equivalent medical device regulator and the EU MDR framework impose conformity assessment requirements that filter non-compliant suppliers from European tenders. Stakeholders must monitor regulatory divergence between US clinical-evidence standards and European conformity routes when allocating product development resources.
Market Dynamics
The electric-cooling technology transition is fragmenting buyer concentration away from hospital procurement departments toward independent wellness operators and mobile rental fleets. This shift compresses average deal sizes while multiplying addressable touchpoints across secondary urban markets.
Growth Catalysts
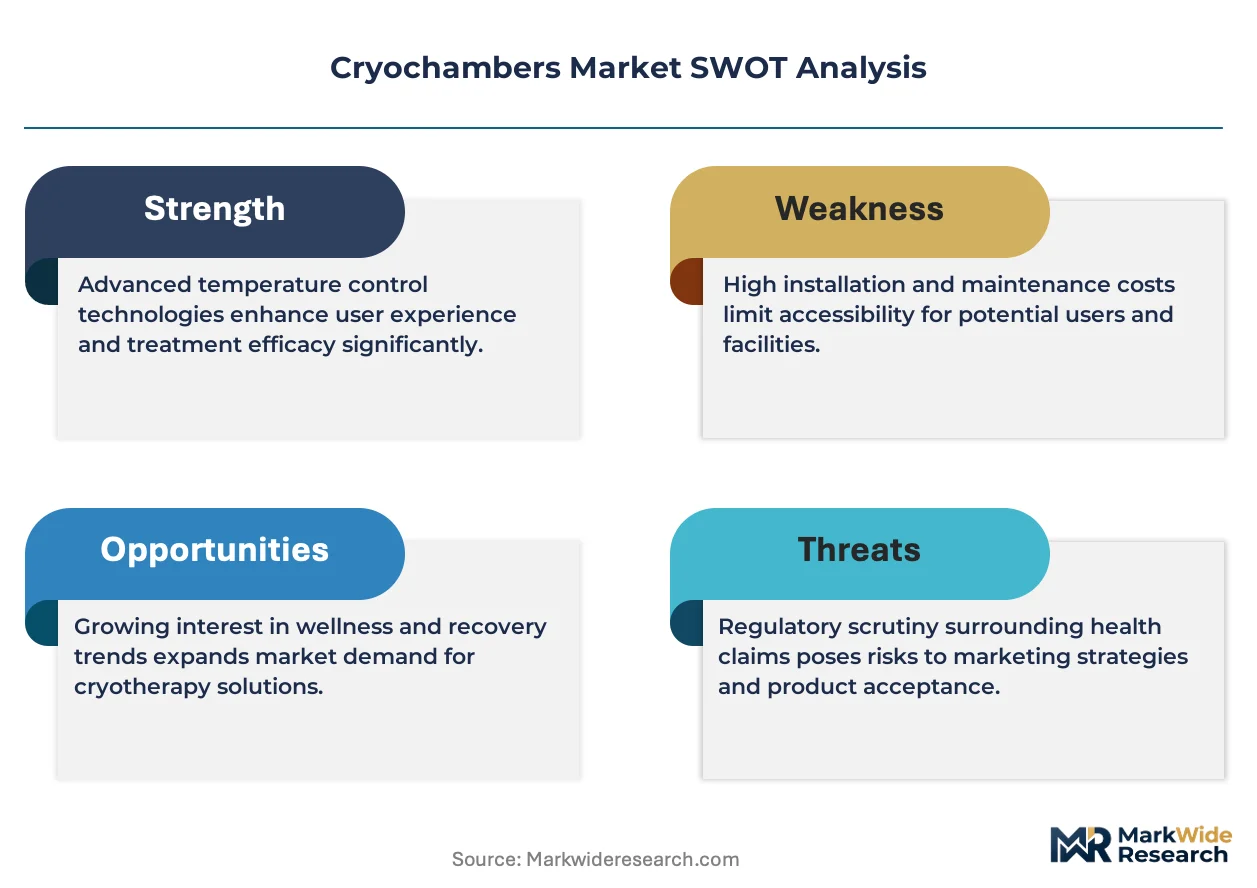
- EU MDR conformity pathways:The Medical Device Regulation's streamlined certification for Class IIa devices accelerates electric cryochamber approvals across German physiotherapy networks.
- Athletic recovery protocols:Professional sports franchises in North America are mandating cryotherapy installations as standard equipment, creating institutional demand pull.
- Nitrogen logistics infrastructure:Established cryogen supply chains in Central Europe enable rapid deployment of vapor-based systems without capital-intensive cooling hardware.
Market Restraints
- Liquid nitrogen price volatility:Industrial gas supply constraints and energy input costs create operational margin pressure for vapor-cooled installations.
- Clinical evidence requirements:FDA medical device classification demands substantiated safety claims that extend product development timelines and regulatory spend.
- Substitute modalities:Cold water immersion systems and localized compression therapy devices compete for the same recovery and pain management budgets.
Strategic Opportunities
- Underpenetrated secondary cities:Mobile and rental models can access markets below the population threshold for permanent installations in the United States.
- Convergence with biometric monitoring:Integration of heart rate variability and thermal response sensors creates differentiated product tiers for performance optimization segments.
- Reimbursement pathway development:Germany's standardized rehabilitation program frameworks present avenues for procedure code establishment and insurance coverage expansion.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in ultra-low temperature system design concentrates among a limited pool of suppliers and research institutions.
- Legacy facility retrofit complexity:Existing clinical infrastructure often lacks adequate ventilation and electrical capacity for electric-cooling unit installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryochambers Market |
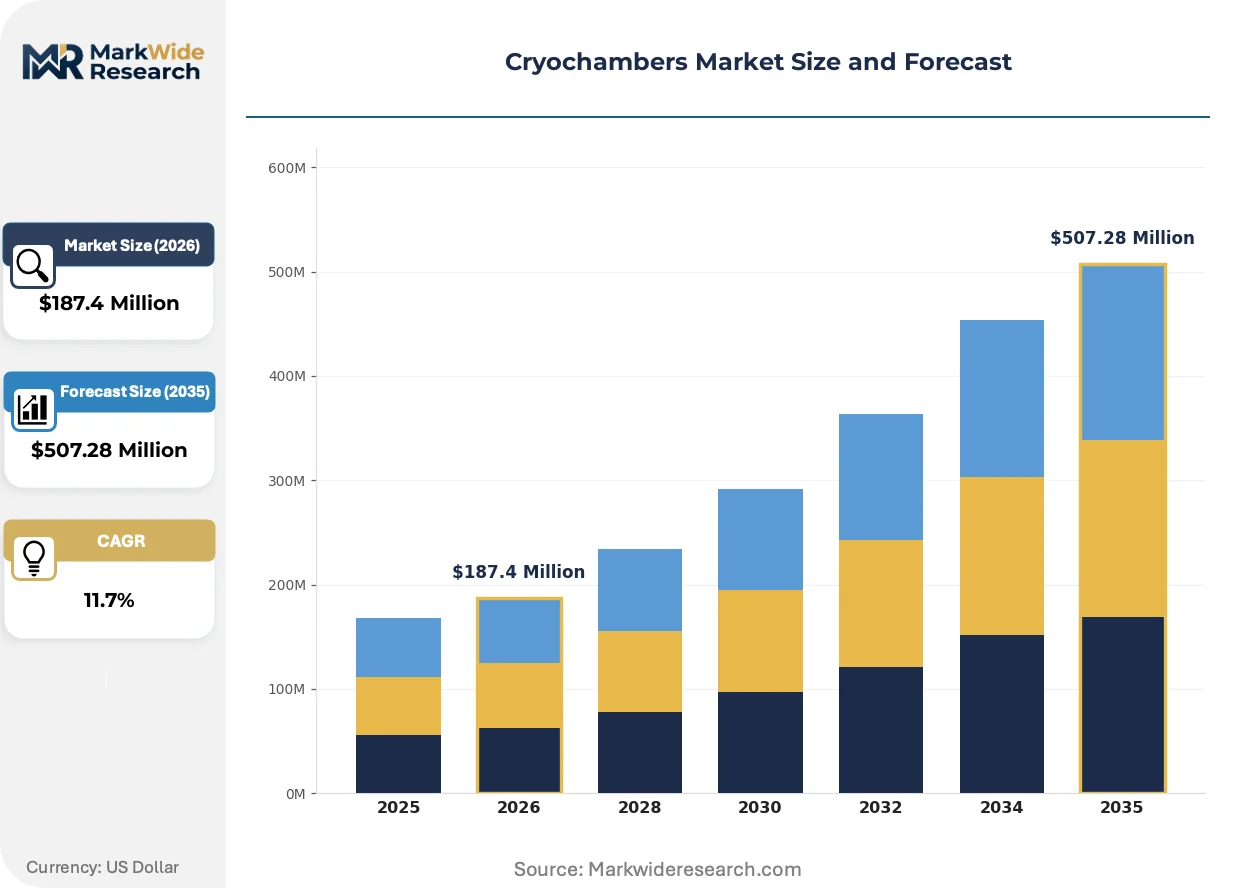
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Body,Localized,Mobile,Custom Technology: Electric, Nitrogen, Liquid Helium, Hybrid Application: Athletic Recovery,Physical Therapy,Wellness,Rehabilitation End User: Fitness Centers,Clinics,Hospitals,Wellness Spas |
| Companies Covered | Cryomed, Impact Cryotherapy, MECOTEC GmbH, Zimmer MedizinSysteme GmbH, KrioSystem, Metrum CryoFlex, CryoAction Limited, CRYO Holding, CryoBuilt, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryochambers Market Emerging Trajectories
Technology substitution and regulatory recalibration are compressing product lifecycles while opening new deployment formats. Three distinct vectors are restructuring competitive positioning and capital allocation priorities.
Electric refrigeration systems are decentralizing the installed base away from fixed clinical sites. These units eliminate nitrogen supply dependencies and ventilation requirements, enabling placement in standard fitness facilities. Boutique recovery studios and hotel wellness centers are adopting them at accelerating rates. This technology is decentralizing market access by removing the geographic constraint of cryogen logistics infrastructure.
REACH and F-Gas Regulation compliance requirements in Europe are elevating environmental performance standards for cooling system refrigerants. Manufacturers must phase down high-global-warming-potential gases and document lifecycle carbon footprints. Electric-cooling segments face the steepest adaptation costs, while nitrogen-based systems gain temporary competitive relief from chemical substitution mandates.
Service unbundling is fragmenting traditional capital-equipment sales into rental, lease-to-own, and per-session revenue models. Wellness chains and pop-up recovery concepts are displacing permanent procurement with flexible fleet arrangements. This behavioral shift is most visible in United States metropolitan markets where real estate costs and demand seasonality favor asset-light strategies.
Cryochambers Market Segmentation
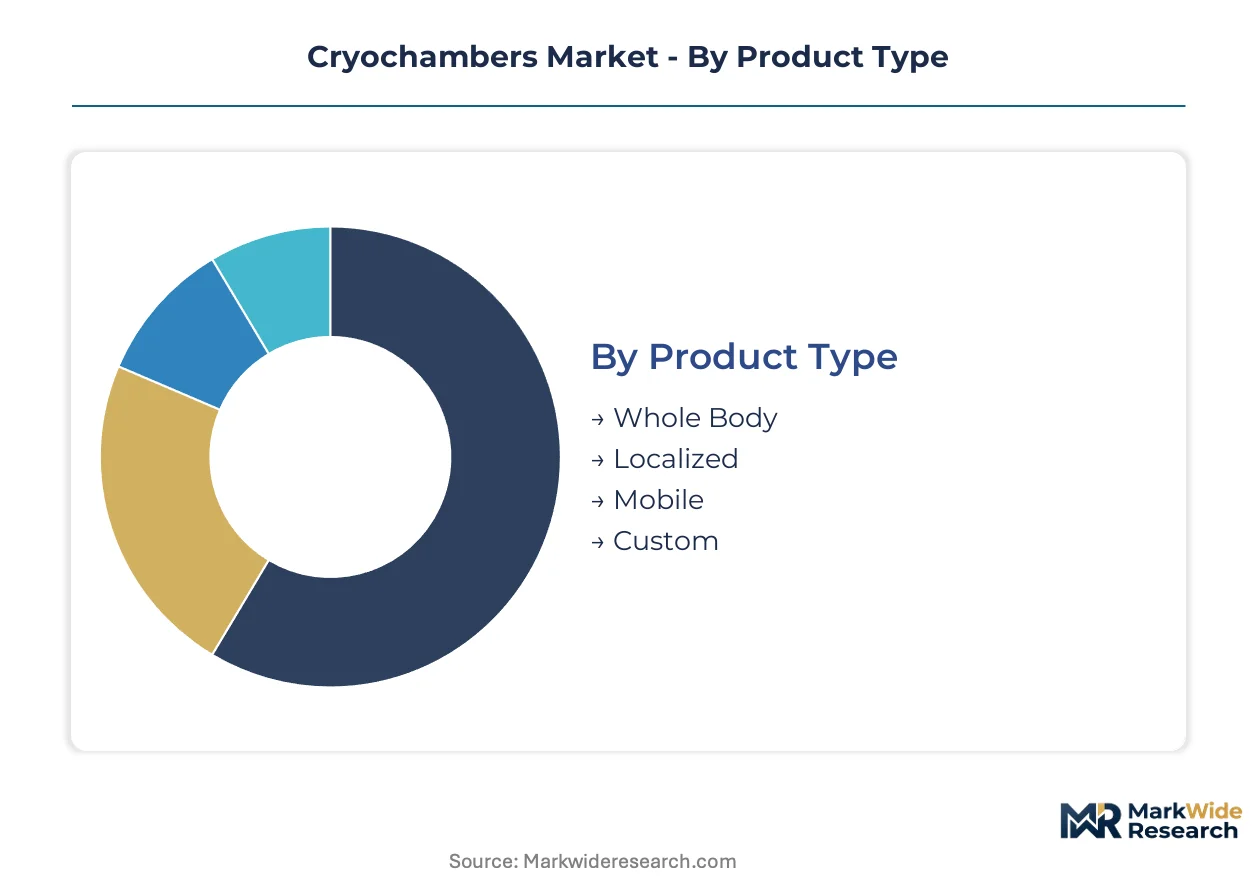
Cryochamber procurement diverges sharply between institutional buyers seeking permanent installations and mobile operators pursuing flexible deployment models. Understanding where each segment sits on this integration spectrum clarifies capital allocation priorities and service bundling strategies.
Product Type:
Standalone whole-body units dominate fixed-site deployments, while embedded mobile formats integrate into rental fleets and pop-up recovery concepts.
- Whole Body:Enclosed cabin systems expose patients to controlled ultra-low temperatures across the full body surface. Hospital procurement departments in Germany and the United States specify these for standardized rehabilitation programs, driven by insurance reimbursement frameworks and clinical protocol formalization.
- Localized:Targeted cooling devices treat specific anatomical regions through cryogen spray or contact plates. Demand concentrates in physiotherapy practices where space constraints and procedure specificity favor modular equipment over full-body infrastructure.
- Mobile:Trailer-mounted or compact electric units enable temporary deployment at sporting events and corporate wellness programs.
- Custom:Bespoke installations accommodate unusual facility footprints or specialized clinical workflows.
Volume placements concentrate in Whole Body installations; the faster expansion belongs to Mobile units.
Technology:
Cost tiers separate capital-intensive electric systems from nitrogen-based alternatives with lower upfront hardware requirements but ongoing cryogen dependencies.
- Electric:Refrigeration-cycle systems achieve ultra-low temperatures through compressor arrays and heat exchangers without cryogen consumption. Fitness chains in the United States favor these for reduced ventilation requirements and elimination of nitrogen supply contracts, though energy input costs and electrical infrastructure upgrades compress margins.
- Nitrogen:Vapor-phase cooling injects liquid nitrogen into insulated chambers for rapid temperature descent. Established clinical infrastructure in Central Europe leverages existing cryogen logistics networks, making this the default specification for hospital tenders where supply relationships are entrenched.
- Liquid Helium:Specialized research-grade systems achieve temperatures below nitrogen capabilities for experimental applications.
- Hybrid:Dual-mode units switch between electric pre-cooling and nitrogen boost phases.
Installed base tilts toward Nitrogen systems; electric configurations are climbing the fastest as wellness chains prioritize operational simplicity.
Application:
Application segments map to distinct customer maturity levels, from institutional athletic programs with standardized protocols to discretionary wellness consumers.
- Athletic Recovery:Post-exercise cold exposure protocols reduce inflammation markers and accelerate return-to-play timelines. Professional sports franchises in North America mandate cryotherapy as standard equipment, creating institutional demand pull through equipment specifications written into facility design standards.
- Physical Therapy:Clinically supervised treatment addresses acute injury management and post-surgical rehabilitation. German physiotherapy practices integrate cryochambers into standardized care pathways, supported by procedure code frameworks that enable insurance billing.
- Wellness:Consumer-facing cold exposure for stress reduction and metabolic enhancement.
- Rehabilitation:Long-term recovery programs for chronic pain and mobility restoration.
Revenue concentration sits with Athletic Recovery; Wellness applications are gaining share fastest as boutique studios proliferate.
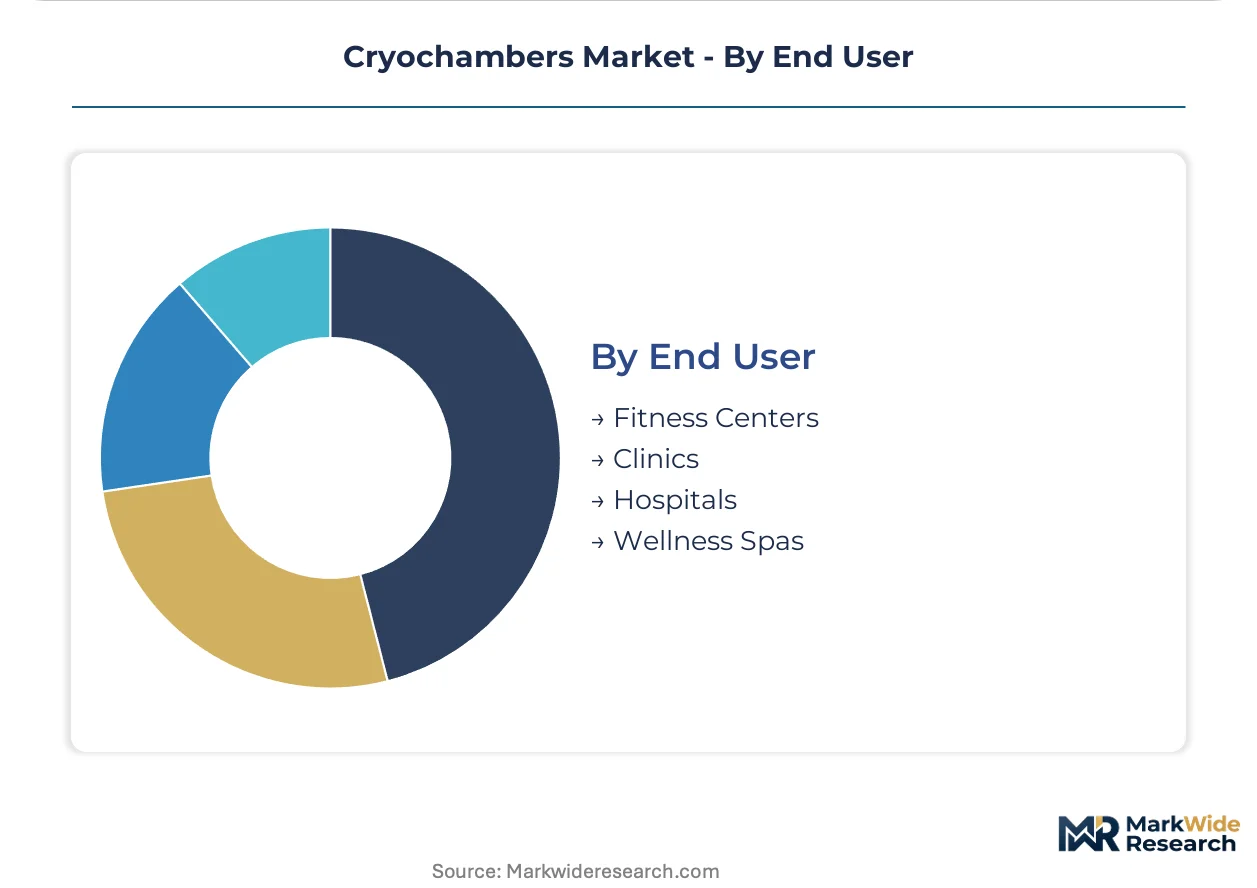
End User:
Customer type determines procurement scale and contract structure, from high-volume fitness chains to fragmented spa operators.
- Fitness Centers:Large-format gyms and boutique recovery studios deploy cryochambers as membership differentiators. Electric-cooling units penetrate this segment most aggressively due to simplified installation and reduced regulatory compliance burdens compared to nitrogen-based alternatives.
- Clinics:Outpatient physiotherapy and sports medicine practices require clinical-grade certification breadth. EU MDR conformity pathways accelerate electric cryochamber approvals across German-speaking networks, filtering non-compliant suppliers from tender processes.
- Hospitals:Acute care and rehabilitation facilities with established capital equipment procurement.
- Wellness Spas:Hospitality-integrated and standalone relaxation venues.
Procurement volume clusters in Clinics; Fitness Centers show the steepest expansion trajectory as recovery protocols professionalize beyond elite athletics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German physiotherapy networks concentrate installed base volume, while United States fitness chains drive electric-cooling adoption velocity.
Germany
Standardized rehabilitation programs embed cryochambers into insurance-reimbursed care pathways. The EU MDR framework accelerates Class IIa device approvals for physiotherapy tenders. Bavarian medical device clusters around Munich supply precision-engineered cooling systems to hospital procurement channels.
United States
Professional sports franchises mandate cryotherapy as standard athletic recovery equipment. FDA medical device classification oversight compels clinical evidence substantiation for safety claims. Boutique recovery studios in Los Angeles and New York deploy mobile rental fleets to penetrate secondary urban markets.
United Kingdom
Premier League training facilities drive institutional demand for whole-body installations. The Medicines and Healthcare products Regulatory Agency enforces conformity assessment for clinical-grade equipment. London wellness operators pioneer service unbundling through per-session revenue models.
France
ANSM oversight shapes medical device market access for hospital tenders. Olympic training centers in Île-de-France establish cryotherapy protocols for elite athlete preparation. Lyon-based rehabilitation clinics integrate localized cooling devices into post-surgical care pathways.
Japan
METI industrial standards govern ultra-low temperature equipment safety certification. Corporate wellness programs in Tokyo deploy compact electric units for employee stress reduction. Osaka physiotherapy chains adopt nitrogen-based systems leveraging established industrial gas supply networks.
Cryochambers Market Vendor Landscape
German producers anchor the clinical-grade tier; United States specialists hold the wellness and mobile segments. Market structure tilts toward consolidated regional champions with deep service networks rather than fragmented global competition. Three archetypes dominate: electric-cooling technology leaders, nitrogen-based system incumbents with cryogen logistics integration, and mobile rental fleet operators. Competitive moves center on M&A for regional service network expansion and technology licensing partnerships to bridge electric-nitrogen hybrid configurations.
Within the clinical-grade tier, MECOTEC GmbH and Zimmer MedizinSysteme GmbH exemplify German-engineered precision with established conformity assessment track records under EU MDR pathways. Cryomed occupies a position representing electric-cooling technology leadership, anchoring the segment shift away from nitrogen dependency toward simplified installation protocols for fitness chain deployment.
| Leading Market Players |
|---|
| Cryomed |
| Impact Cryotherapy |
| MECOTEC GmbH |
| Zimmer MedizinSysteme GmbH |
| KrioSystem |
| Metrum CryoFlex |
| CryoAction Limited |
| CRYO Holding |
| CryoBuilt, Inc. |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen procurement costs cascade through three distinct pricing tiers for cryochamber systems, compressing margins for vapor-cooled installations while electric refrigeration units capture premium positioning through simplified operational requirements. Energy input costs for compressor arrays and cryogen logistics contracts for nitrogen supply chains diverge sharply across German hospital tenders and United States fitness chain deployments.
Pricing Analysis
High-volume hospital procurement concentrates in the standard tier, while boutique wellness studios and mobile rental operators populate the economy segment where per-session revenue models dominate. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade certified units from fitness-optimized configurations and rental fleet equipment. Pricing pressure stems from substitute modalities including cold water immersion systems competing for recovery budgets. Fitness centers exhibit the highest price sensitivity due to capital constraints and seasonality exposure, whereas German physiotherapy networks demonstrate lower sensitivity given insurance reimbursement frameworks.
Supply Chain Analysis
Regional distribution centers in Bavaria, Texas, and Osaka coordinate hub-and-spoke patterns for cooling system components and cryogen logistics infrastructure. Manufacturing concentration centers on Germany for precision-engineered clinical units, the United States for electric-cooling fitness equipment, and Japan for compact corporate wellness configurations. Critical component dependencies include compressor arrays, ultra-low temperature insulation materials, and liquid nitrogen storage vessels. Single-source vulnerability for specialized cryogenic engineering talent concentrates design expertise among Munich and Stuttgart research clusters. Distribution runs through hospital procurement channels, GPO contracts, and direct-to-fitness-chain arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric refrigeration technology is displacing nitrogen-based cooling systems across wellness and fitness segments, compressing legacy infrastructure valuations while opening new deployment formats for asset-light operators.
For Market Incumbents: Lock in cryogen logistics relationships with industrial gas suppliers to defend hospital procurement positions against electric-cooling substitution. Deepen backward integration into compressor array manufacturing to capture margin from fitness chain growth. Prioritize EU MDR certification maintenance to filter non-compliant competitors from German physiotherapy tenders.
For New Entrants and Emerging Players: Launch via mobile rental fleet models to penetrate secondary United States cities below permanent installation thresholds. Target underpenetrated corporate wellness programs in Tokyo and Osaka with compact electric units. Exploit service unbundling trends through per-session revenue arrangements rather than capital equipment sales.
For Investors and Strategic Acquirers: FDA medical device classification guidance expansion is the leading indicator that clinical evidence requirements will intensify, favoring incumbents with substantiated safety portfolios. Acquisition focus should center on electric-cooling technology specialists with established fitness chain relationships. Watch for nitrogen price volatility spikes as signals for accelerated technology substitution timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Accelerates market access for Class IIa devices across German physiotherapy networks. |
| Electric-Cooling Technology Licensing | Enables nitrogen-dependent incumbents to bridge hybrid system configurations. |
| Mobile Fleet Expansion | Captures secondary urban demand through rental and pop-up recovery concepts. |
| Biometric Sensor Integration | Creates differentiated tiers for performance optimization segments. |
| Reimbursement Strategy Development | Secures procedure code establishment within German insurance frameworks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with cryochamber manufacturers, hospital procurement managers, fitness chain operations directors, and physiotherapy practice owners. FDA 510(k) databases, EU MDR notified body records, and German hospital procurement databases provided validation layers. Bottom-up unit economics triangulated against top-down market sizing across technology, application, and end-user dimensions.
Granularity-level modeling deployed product type, cooling technology, and end-user vertical as primary segmentation axes, with regional regulatory cluster and procurement channel as secondary cross-cuts. CAGRs derived from installed base growth trajectories and replacement cycle analysis across the projection horizon. Forecast inputs incorporated nitrogen price indices, fitness chain expansion pipelines, and reimbursement policy developments.
Regulatory reclassification, cryogen supply disruption, and substitute modality penetration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding technology substitution velocity and reimbursement pathway evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Clinical Microscopes Market
Medical Equipment
Medical Filter Market
Medical Equipment
Global Kidney Dialysis Equipment and Supplies Market
Medical Equipment
Proctologic Table Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Sanitary Napkin Equipment Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Medical Thawing Systems Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Bone Densitometer Systems Market
Medical Equipment
Radiotherapy Motion Management Market
Medical Equipment
Operating Table Parts Market