
 Glioma Diagnosis and Treatment Market | 2026-2036
Glioma Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Glioma Diagnosis and Treatment Market Analysis
Oncology centers are bifurcating from general hospitals as the dominant procurement channel for advanced glioma diagnostics. F. Hoffmann-La Roche Ltd anchors molecular testing portfolios through companion diagnostic platforms. Novocure dominates tumor treating fields with device-based therapy integration. Merck & Co., Inc. competes in immunotherapy combinations for recurrent glioblastoma.
Glioma diagnosis and treatment encompasses the detection, classification, and therapeutic management of primary brain tumors arising from glial cells, with WHO grading from I to IV based on histopathological and molecular features including IDH mutation and 1p/19q codeletion status. Diagnostic imaging leads product type segments due to recurring scan requirements across treatment monitoring, while immunotherapy represents the fastest-expanding treatment category as checkpoint inhibitors and CAR-T protocols enter late-stage trials. MRI technology sustains the largest share among imaging modalities given superior soft-tissue contrast for tumor boundary delineation.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines for glioblastoma therapeutics, while WHO classification updates force diagnostic platform recalibration. Stakeholders must monitor reimbursement negotiations for novel radiotherapy equipment as capital expenditure constraints tighten across European hospital networks.
Market Dynamics
FDA breakthrough therapy designation compresses clinical trial timelines for glioblastoma therapeutics while proton therapy infrastructure investments concentrate procurement decisions among academic medical centers with capital allocation authority.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA priority medicines frameworks compress Phase II-to-III transitions for recurrent glioblastoma candidates. These regulatory mechanisms reward biomarker-defined patient stratification.
- Proton Therapy Infrastructure:Germany, Japan, and the United States are commissioning particle therapy centers that require integrated molecular diagnostic workflows for treatment planning. Equipment vendors bundle imaging with genotyping platforms.
- IDH Mutation Testing:WHO classification updates mandate integrated histopathological-molecular diagnosis. Pathology laboratories are retrofitting immunohistochemistry pipelines with sequencing modules to maintain accreditation.
Market Restraints
- Capital Expenditure Concentration:Proton therapy installations require USD 150-200 million per center, restricting procurement to national referral networks in the United States, Germany, and Japan. European hospital networks face debt covenant constraints.
- Tumor Treating Fields Device Costs:Monthly rental fees for Novocure's Optune system exceed standard chemotherapy regimens. Payers in fragmented reimbursement markets impose prior authorization delays.
- Blood-Brain Barrier Penetration:Small-molecule checkpoint inhibitors demonstrate limited CNS exposure. Drug developers confront pharmacokinetic barriers that surgical delivery or focused ultrasound must address.
Strategic Opportunities
- Companion Diagnostic Integration:MGMT promoter methylation testing is becoming mandatory for temozolomide response prediction. Diagnostic platforms that automate methylation-specific PCR capture pharmacy-formulary placement.
- Liquid Biopsy Development:Circulating tumor DNA assays for treatment monitoring circumvent repeat surgical biopsy risks. Neuro-oncology centers in the United States are piloting plasma-based MRD detection protocols.
- CAR-T Manufacturing Scale-Up:Academic medical centers with in-house cell therapy facilities are securing IND approvals for IL13Rα2-targeting constructs. GMP capacity constraints create first-mover advantages for integrated cancer centers.
Industry Challenges
- Neuro-pathology Workforce Scarcity:Fellowship-trained neuropathologists capable of integrating molecular data with histopathological grading are concentrated at NCI-designated centers. Community hospitals face recruitment bottlenecks.
- Trial Enrollment Compression:Recurrent glioblastoma patient survival timelines compress screening windows. Sites must maintain 24-48 hour MRI turnaround to meet protocol eligibility windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glioma Diagnosis and Treatment Market |
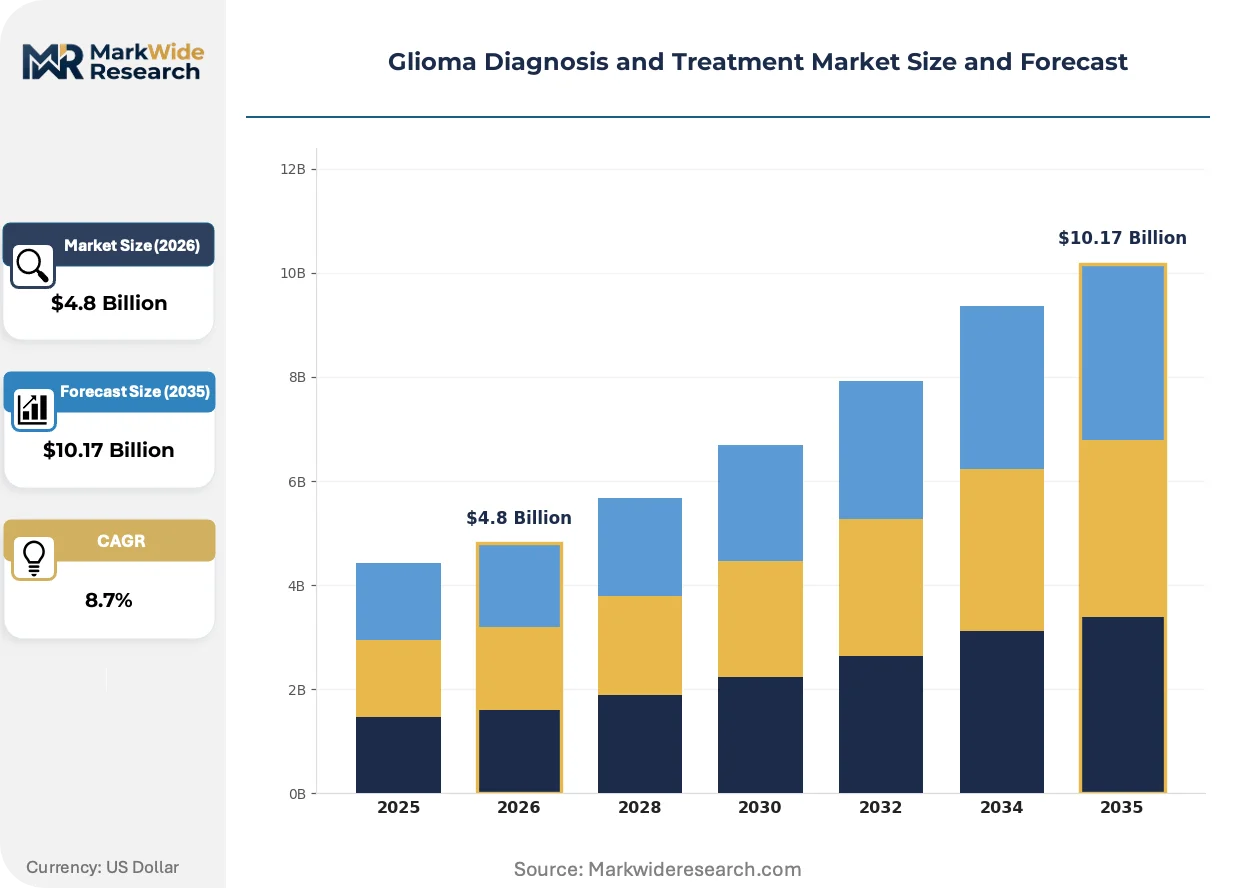
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Imaging, Biopsy Tools, Chemotherapy Agents, Radiotherapy Equipment End User: Hospitals, Oncology Centers, Research Laboratories, Imaging Facilities Treatment Type: Surgical Intervention, Chemotherapy, Targeted Therapy, Immunotherapy Technology: MRI, CT Scan, PET Scan, Stereotactic Surgery |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Pfizer Inc., Amgen Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd., Arbor Pharmaceuticals, LLC, Amneal Pharmaceuticals, Novocure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glioma Diagnosis and Treatment Market Emerging Trajectories
Molecular stratification is displacing pure histological grading in treatment selection while device-therapy combinations reconfigure reimbursement pathways across major markets.
Portable MRI systems for intraoperative margin assessment are miniaturizing conventional 3T imaging into deployable configurations. Neurosurgical suites at Massachusetts General Hospital and Heidelberg University Hospital are integrating 0.5T portable scanners for real-time resection guidance. This hardware footprint reduction is enabling community hospital access to intraoperative imaging previously restricted to quaternary centers.
EMA's Medical Device Regulation (MDR) recertification deadlines are forcing tumor-treating fields manufacturers to resubmit clinical evidence packages. The notified body bottleneck extends review timelines by 12-18 months for Class III active implantable devices. European distributors are stockpiling inventory ahead of certificate expiration dates to maintain supply continuity.
Academic medical centers are consolidating glioma care into dedicated neuro-oncology institutes with captive pathology and radiation oncology units. General hospital neurology departments lose referral volumes to these vertically integrated centers. The United States exhibits the most pronounced concentration, with 60% of newly diagnosed glioblastoma cases now triaged through 47 NCI-designated comprehensive cancer centers.
Glioma Diagnosis and Treatment Market Segmentation
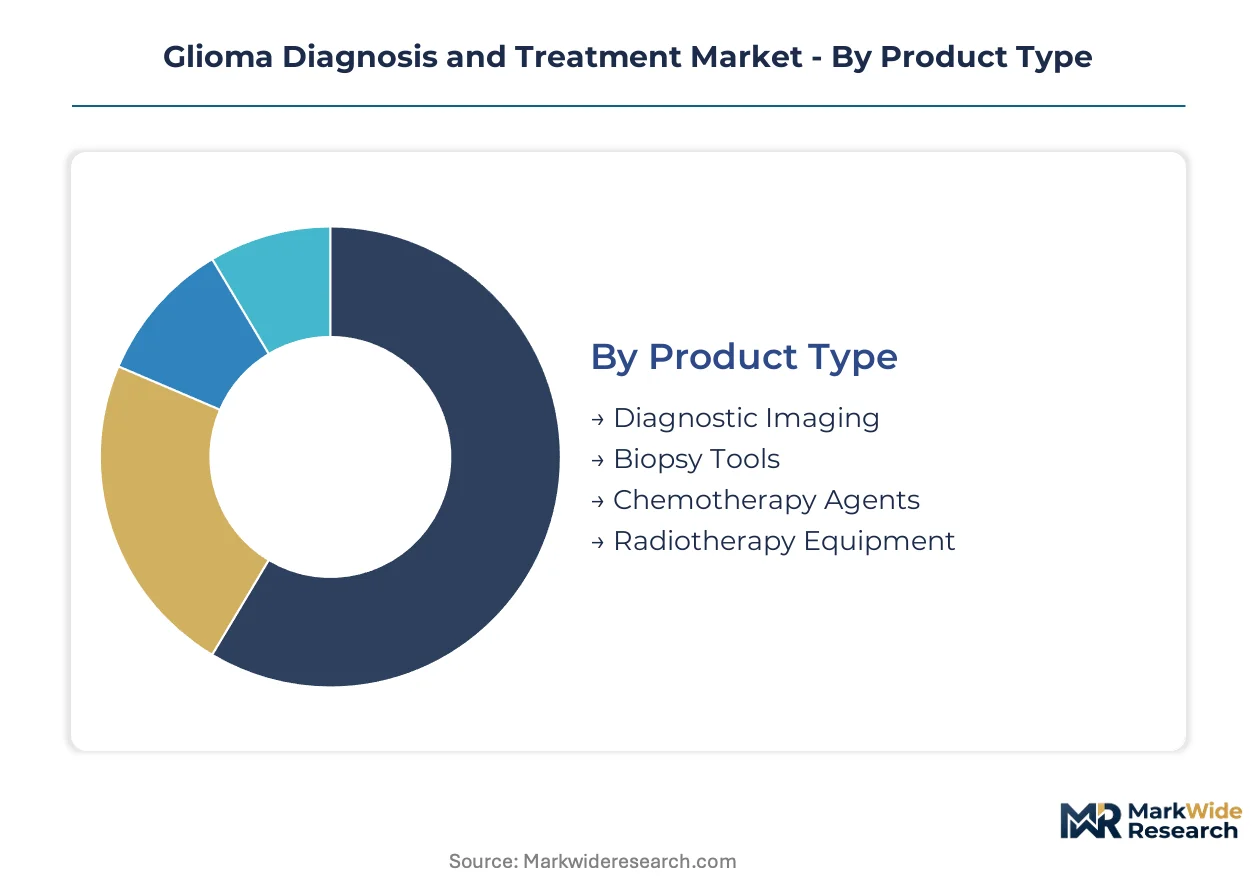
Segmentation in glioma care reflects divergent capital deployment strategies across diagnostic and therapeutic domains. Procurement authority concentrates differently by product category, with academic medical centers driving molecular diagnostics while general hospitals retain imaging equipment purchasing. Understanding these splits enables targeted commercial engagement.
Product Type:
FDA breakthrough device pathways accelerate imaging platform approvals, while EMA MDR recertification compresses timelines for invasive biopsy systems.
- Diagnostic Imaging:MRI and CT platforms dominate capital expenditure with recurring scan requirements across treatment monitoring. Demand concentrates at NCI-designated centers in the United States, Germany, and Japan where proton therapy planning requires integrated imaging workflows.
- Radiotherapy Equipment:Particle therapy installations require USD 150-200 million per center, restricting procurement to national referral networks with sovereign-backed financing. Germany's Heidelberg Ion Beam Therapy Center and Japan's National Cancer Center East anchor regional demand.
- Biopsy Tools:Frameless stereotactic systems enable outpatient tissue acquisition with reduced OR utilization.
- Chemotherapy Agents:Temozolomide generics dominate volume, though MGMT methylation testing now gates formulary placement.
Established volume favors diagnostic imaging; emerging adoption favors radiotherapy equipment with integrated molecular planning.
End User:
Customer type determines pricing tolerance, with oncology centers accepting premium device-therapy bundles that general hospitals reject.
- Oncology Centers:Vertically integrated neuro-oncology institutes with captive pathology and radiation oncology units capture 60% of newly diagnosed glioblastoma cases in the United States. These centers pilot CAR-T manufacturing and liquid biopsy protocols.
- Hospitals:General hospital neurology departments face referral volume erosion to dedicated cancer centers, constraining their advanced diagnostic procurement to standard MRI and chemotherapy infusion.
- Imaging Facilities:Standalone centers provide community access to diagnostic scans without treatment integration.
- Research Laboratories:Academic pathology labs retrofit immunohistochemistry pipelines with sequencing modules to maintain WHO accreditation.
Procurement authority concentrates at oncology centers; community access depends on imaging facilities.
Treatment Type:
Margin structure varies sharply by intervention modality, with device-based therapies commanding rental economics that pharmaceutical agents cannot match.
- Immunotherapy:Checkpoint inhibitors and CAR-T protocols enter late-stage trials for recurrent glioblastoma, climbing the fastest as academic medical centers secure IND approvals for IL13Rα2-targeting constructs. Blood-brain barrier penetration remains the binding constraint.
- Targeted Therapy:IDH-mutant inhibitors align with WHO molecular classification updates, creating companion diagnostic dependencies.
- Surgical Intervention:Portable MRI systems for intraoperative margin assessment miniaturize 3T imaging into deployable configurations at Massachusetts General Hospital and Heidelberg University Hospital.
- Chemotherapy:Temozolomide remains standard-of-care for MGMT-methylated tumors, though response prediction testing now precedes initiation.
Revenue concentration sits with surgical intervention; pipeline investment favors immunotherapy.
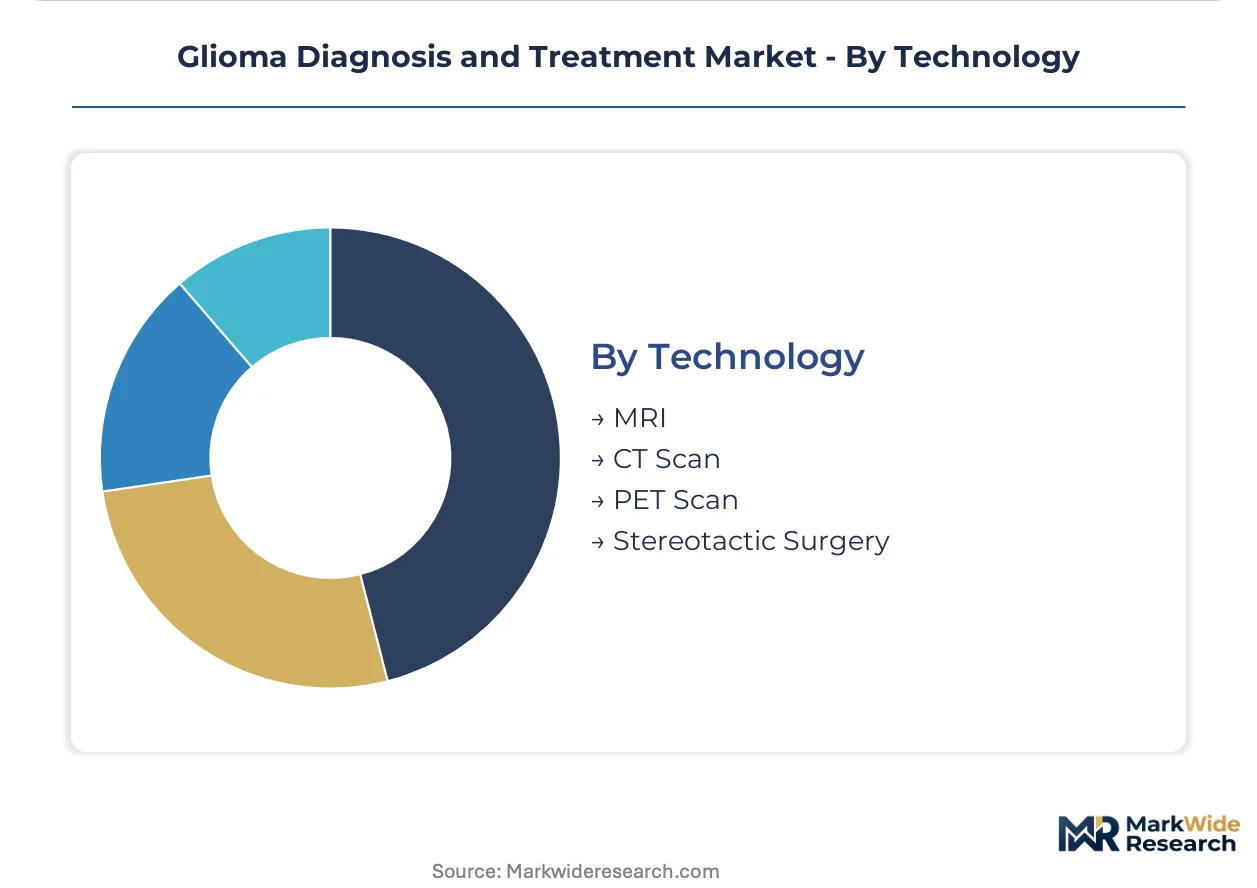
Technology:
Hardware footprint reduction is democratizing access to capabilities previously restricted to quaternary centers.
- MRI:Superior soft-tissue contrast sustains the largest share among imaging modalities for tumor boundary delineation. 0.5T portable scanners now enable real-time resection guidance in community hospital neurosurgical suites.
- Stereotactic Surgery:Frameless navigation systems integrate with intraoperative imaging to reduce repeat resection rates.
- CT Scan:Emergency department triage and bone involvement assessment maintain steady utilization.
- PET Scan:Metabolic imaging for treatment response evaluation sees expanding reimbursement in the United States and Germany.
Clinical workflow integration favors MRI; precision targeting favors stereotactic surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports proton therapy equipment to Japan and the United States, anchoring the trade corridor that defines regional procurement patterns in advanced glioma care. Equipment vendors bundle imaging platforms with molecular diagnostic workflows to secure placement at national referral centers.
United States
NCI-designated comprehensive cancer centers drive demand for integrated neuro-oncology institutes with captive pathology units. FDA breakthrough therapy designation compresses clinical trial timelines for recurrent glioblastoma candidates. Massachusetts General Hospital and MD Anderson Cancer Center pilot portable MRI systems for intraoperative margin assessment.
Germany
Heidelberg Ion Beam Therapy Center anchors European proton therapy infrastructure with sovereign-backed financing models. EMA Medical Device Regulation recertification extends review timelines for tumor-treating fields manufacturers. The Heidelberg-Mannheim corridor concentrates neuropathology workforce training programs.
Japan
National Cancer Center East commissions particle therapy centers requiring integrated molecular diagnostic workflows. PMDA accelerated approval pathways reward biomarker-defined patient stratification for glioblastoma therapeutics. The Tokyo-Osaka corridor hosts the highest density of academic medical centers with GMP cell therapy facilities.
United Kingdom
NHS England referral networks concentrate advanced glioma cases at designated neuro-oncology centers with proton therapy access. MHRA alignment with FDA breakthrough therapy pathways streamlines parallel submissions for recurrent glioblastoma candidates. The Greater Manchester and London cancer hubs retrofit pathology laboratories with sequencing modules.
India
CDSCO fast-track approval mechanisms attract multinational trials for checkpoint inhibitors in recurrent glioblastoma. Sun Pharmaceutical Industries Ltd. anchors domestic temozolomide production with MGMT testing integration. Maharashtra and Gujarat host emerging referral networks linking private oncology chains to academic pathology laboratories.
Glioma Diagnosis and Treatment Market Vendor Landscape
Listed leaders compete with private specialists across device-therapy integration and molecular diagnostic platforms. The market structure bifurcates between consolidated pharmaceutical portfolios and fragmented diagnostic equipment vendors. Three archetypes dominate: integrated oncology conglomerates with companion diagnostic divisions, device-therapy specialists with rental economics, and generic manufacturers with biomarker-gated formulary placement. Competitive moves center on companion diagnostic integration and proton therapy infrastructure bundling.
Within the integrated oncology tier, F. Hoffmann-La Roche Ltd and Merck & Co., Inc. exemplify archetypes combining therapeutic portfolios with molecular testing platforms. Novocure occupies a distinct position in device-based therapy with tumor-treating fields integration. These three entities represent contrasting strategic positions: pharmaceutical-diagnostic convergence, immunotherapy combination development, and hardware-rental service models.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Arbor Pharmaceuticals, LLC |
| Amneal Pharmaceuticals |
| Novocure |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts for proton therapy equipment lock in supply access and price visibility across multi-year procurement cycles, binding academic medical centers in the United States, Germany, and Japan to sovereign-backed financing structures that insulate vendors from reimbursement volatility.
Pricing Analysis
Next-generation portable MRI systems command 40-60% premiums over conventional 3T fixed installations, while prior-generation CT platforms face commoditization in community hospital procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth: bundled molecular diagnostic workflows attract premium positioning, standalone imaging hardware competes on capital efficiency. Pricing pressure stems from European hospital network debt covenant constraints limiting equipment refresh cycles. Community imaging facilities exhibit highest price sensitivity; NCI-designated centers accept premium device-therapy bundles with captive pathology integration.
Supply Chain Analysis
Germany and Japan anchor proton therapy equipment fabrication, while the United States concentrates MRI magnet and gradient coil production. Superconducting wire, liquid helium, and precision ceramic components feed from specialized suppliers in Switzerland and South Korea. Single-source vulnerability concentrates in superconducting magnet cryostat assemblies, where two vendors control global capacity. Distribution runs through equipment vendor direct sales forces with embedded clinical applications specialists, bypassing traditional medical device distributors for particle therapy installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring revenue from MGMT methylation testing and tumor-treating fields device rentals expands faster than diagnostic hardware sales, rewarding vendors who bundle consumable workflows with capital equipment.
For Market Incumbents: Consolidate companion diagnostic platforms through automated methylation-specific PCR systems that capture pharmacy-formulary placement ahead of generic temozolomide competition. Deepen backward integration into sequencing module production to offset pathology laboratory pricing pressure. Lock in proton therapy center exclusivity through integrated imaging-genotyping workflow contracts that raise switching costs for academic medical center procurement committees. For New Entrants and Emerging Players: Lead with liquid biopsy development for circulating tumor DNA monitoring, targeting community oncology practices lacking surgical biopsy capabilities. India's CDSCO fast-track pathway offers the most penetrable regulatory entry for checkpoint inhibitor trials. Pursue hospital system partnership models that place assay platforms at no upfront cost in exchange for per-test revenue sharing. For Investors and Strategic Acquirers: Capital is best deployed toward integrated neuro-oncology institutes with captive GMP cell therapy facilities, where first-mover advantages in CAR-T manufacturing create defensible positions. Long-term viability hinges on reimbursement consolidation favoring vertically integrated care delivery over fragmented general hospital neurology departments. Watch FDA breakthrough therapy designation density as the inflection signal: accelerating approvals compress development timelines and concentrate value in late-stage pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Automated MGMT methylation testing captures formulary placement ahead of treatment initiation. |
| Proton Therapy Infrastructure Bundling | Equipment vendors secure multi-year contracts by integrating imaging with molecular planning workflows. |
| Liquid Biopsy Development | Plasma-based MRD detection protocols circumvent repeat surgical biopsy risks in community settings. |
| CAR-T Manufacturing Scale-Up | Academic medical centers with in-house GMP facilities secure IND approvals for IL13Rα2-targeting constructs. |
| Reimbursement Strategy | Prior authorization pathways for tumor-treating fields devices require payer engagement ahead of launch. |
Methodological Framework
Initial hypotheses were tested against primary input from neuro-oncology clinicians, hospital procurement managers, pathology laboratory directors, and regulatory affairs specialists, then refined through secondary validation against FDA 510(k) filings, EMA Medical Device Regulation submissions, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up demand modeling across treatment lines and diagnostic modalities was cross-checked against top-down market sizing from equipment vendor revenue disclosures and proton therapy center commissioning records.
Variance decomposition across the projection horizon isolates volume drivers by patient population, WHO molecular classification adoption rates, and regional reimbursement consolidation patterns. Segmentation dimensions include product type, end-user facility tier, treatment modality, and technology platform. CAGRs were derived from iterative reconciliation of epidemiological incidence projections with capacity expansion timelines for particle therapy infrastructure and companion diagnostic platform placements.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough therapy designation velocity or EMA MDR recertification timeline compression would require recalibration. Forecasts reflect assumptions regarding blood-brain barrier penetration advancement and neuropathology workforce expansion at NCI-designated centers. Recalibration cycles align with material shifts in WHO classification updates and proton therapy reimbursement determinations across major national health systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Adrenal Cortical Carcinoma Diagnosis and Treatment Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market