
 Urine Sediment Testing Market | 2026-2036
Urine Sediment Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Urine Sediment Testing Market Analysis
EU MDR recertification timelines is decoupling European hospital procurement from legacy analyzer platforms. Siemens Healthineers leverages its installed base of automated urine sediment systems to sustain service contract renewals across German university hospitals. Sysmex Corporation anchors its competitive position in Japan through dedicated flow cytometry channels for particle recognition in urine specimens.
Urine sediment testing examines particulate matter—casts, crystals, cells, and bacteria—suspended in urine following centrifugation, typically analyzed at 400x magnification under bright-field microscopy or through automated imaging cytometry for standardized particle classification. The procedure serves as a frontline diagnostic screen for renal function assessment, urinary tract infection confirmation, and metabolic disorder monitoring in clinical laboratories. Automated analyzers command the dominant share of product type revenue as laboratories prioritize throughput and operator standardization over manual microscopy methods. Diagnostic laboratories represent the fastest-growing end user segment, outpacing hospital in-house labs as reference networks centralize specialized urinalysis capacity to capture economies of scale.
FDA clinical laboratory improvement amendment standards shape instrument validation requirements for commercial urine sediment analyzers marketed in the United States, while EU MDR technical documentation demands elevate compliance costs for reagent and consumable manufacturers serving European diagnostic laboratories. The country's national pharmaceutical regulator in India enforces import licensing for automated urinalysis instruments, creating differentiated market access conditions for multinational suppliers versus domestic kit producers. Stakeholders must monitor evolving reimbursement codes for automated microscopy versus flow cytometry methodologies as payers recalibrate coverage policies for laboratory-based renal diagnostics.
Market Dynamics
Laboratory consolidation and the FDA's clinical laboratory improvement amendment enforcement are compressing manual microscopy workflows into automated, traceable platforms that demand capital investment but reduce operator variability.
Growth Catalysts
- CLIA-mandated standardization:The FDA's clinical laboratory improvement amendment requirements push diagnostic facilities toward automated analyzers with built-in quality control traceability.
- Integrated delivery networks:Hospital systems in the United States consolidate procurement for high-throughput urinalysis operations, favoring platforms with fleet management capabilities.
- Flow cytometry channels:Particle recognition technology using dedicated flow cytometry channels enables faster, more reproducible cast and crystal classification than bright-field microscopy.
Market Restraints
- Capital intensity:Automated urine sediment analyzers require substantial upfront investment that constrains independent diagnostic laboratories with limited equipment budgets.
- EU MDR recertification:European medical device regulation timelines decouple hospital procurement from legacy analyzer platforms, freezing replacement cycles.
- Reimbursement compression:Payer recalibration of coverage codes for automated microscopy versus flow cytometry methodologies creates revenue uncertainty for laboratory operators.
Strategic Opportunities
- Diagnostic laboratory centralization:Reference networks in the United States capture economies of scale by consolidating specialized urinalysis capacity away from hospital in-house labs.
- Digital pathology integration:Automated imaging cytometry systems that feed directly into laboratory information systems enable remote review and telepathology applications.
- Indian import licensing differentiation:The country's national pharmaceutical regulator enforces instrument import licensing that favors domestic kit producers partnering with multinational platform suppliers.
Industry Challenges
- Microscopist skill attrition:The declining population of trained manual microscopy operators creates bottlenecks during automated system downtime or algorithm flag review.
- Legacy LIS integration:Middleware compatibility with existing laboratory information systems requires costly customization for multi-vendor instrument environments.
- Validation timeline compression:FDA instrument validation requirements for commercial analyzers extend deployment schedules, delaying revenue recognition for capital equipment sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urine Sediment Testing Market |
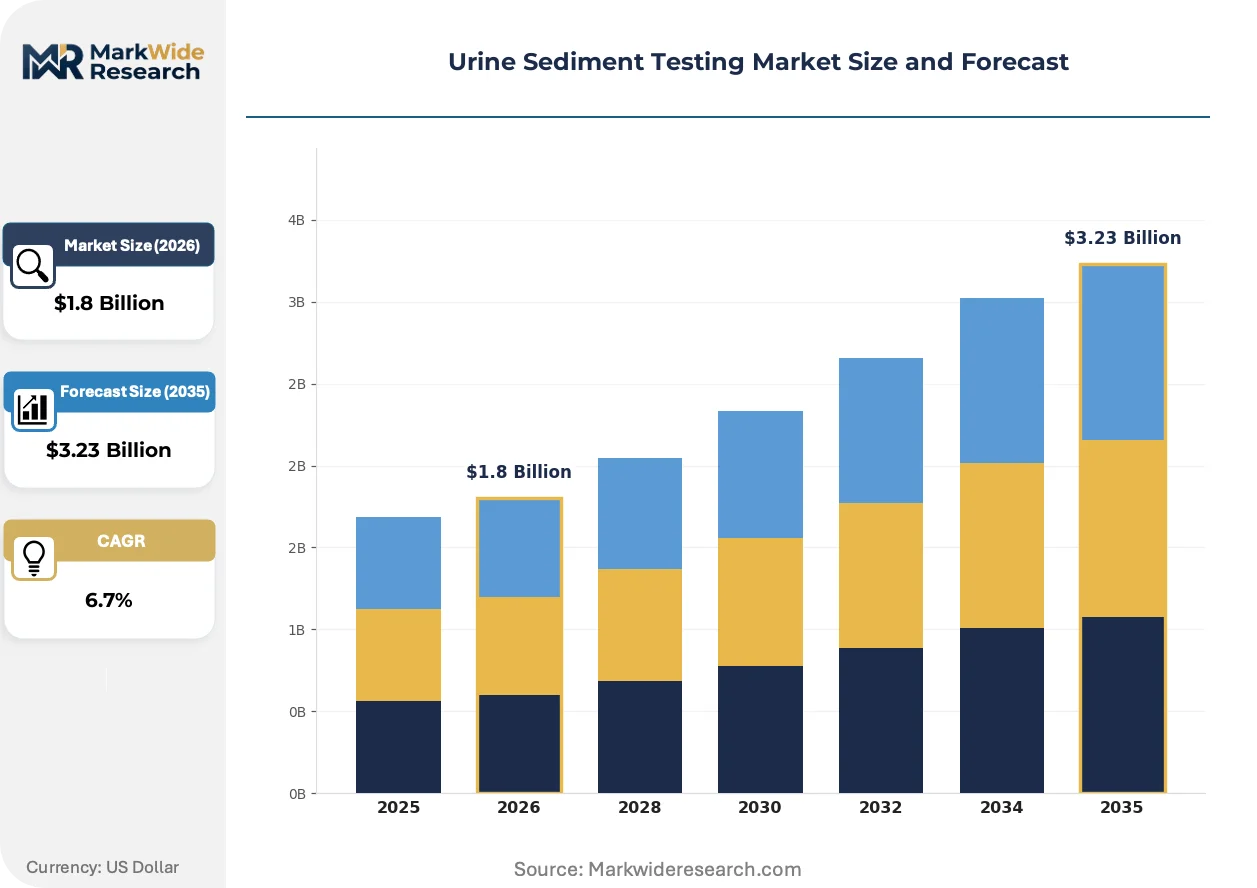
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Test Kits, Consumables End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutes Application: Renal Disorders, Urinary Tract Infections, Diabetes Monitoring, Pregnancy Tests Technology: Microscopy, Flow Cytometry, Dipstick Testing, Automated Analyzers |
| Companies Covered | Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Abbott, Sysmex Corporation, Thermo Fisher Scientific Inc., Danaher Corporation, BD (Becton, Dickinson and Company), Bio-Rad Laboratories Inc., ARKRAY Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urine Sediment Testing Market Emerging Trajectories
Digital imaging and artificial intelligence classification algorithms are transforming particle identification from subjective operator interpretation into standardized, auditable outputs that integrate with enterprise laboratory networks.
Deep-learning convolutional neural networks trained on annotated urine sediment image libraries are rewriting the accuracy benchmarks for cast classification and crystal identification. Academic medical centers and large reference laboratories deploy these systems to reduce inter-operator variability in particle reporting. The technology is compressing the diagnostic validation timeline from hours to minutes while generating datasets for longitudinal renal function monitoring.
EU MDR technical documentation demands for in vitro diagnostic devices elevate compliance costs for reagent and consumable manufacturers serving European diagnostic laboratories. The regulation mandates clinical performance evidence and post-market surveillance systems that smaller suppliers struggle to resource. German university hospitals and French public hospital groups delay procurement decisions until manufacturer recertification status clarifies, extending sales cycles.
After-sales service unbundling is fragmenting the traditional analyzer-vendor relationship as laboratory procurement teams negotiate separate contracts for hardware, reagents, and maintenance. Integrated delivery networks in the United States favor multi-year service agreements with penalty clauses for uptime guarantees over bundled capital purchases. This behavior is most visible in high-throughput hospital laboratories where instrument downtime directly impacts emergency department throughput metrics.
Urine Sediment Testing Market Segmentation
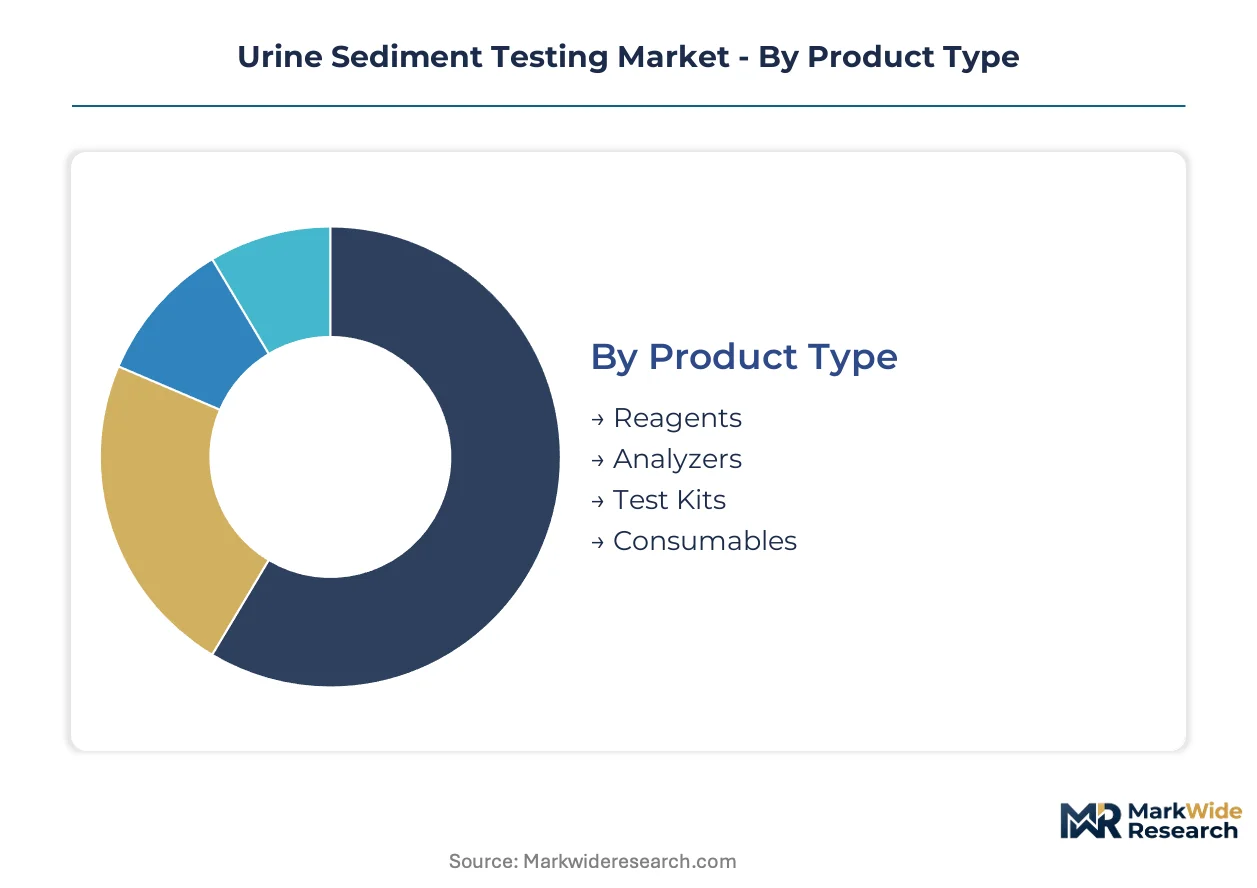
Segmentation in urine sediment testing reveals divergent upgrade cycles across hardware and consumable categories. Product type and end-user dimensions capture the tension between capital-intensive analyzer replacement and recurring reagent demand. Technology splits expose microscopy's defensive position against automated platforms.
Product Type:
Replacement cycles for capital equipment and recurring consumable demand operate on fundamentally different procurement calendars within laboratory budgets.
- Analyzers:Automated urine sediment analyzers integrate digital imaging cytometry and flow cytometry channels for standardized particle classification. Hospital laboratories in the United States prioritize these platforms as FDA clinical laboratory improvement amendment enforcement compresses manual microscopy workflows. Integrated delivery networks consolidate fleet procurement to capture volume discounts and unified service agreements.
- Reagents:Staining solutions, diluents, and calibration materials sustain daily testing operations with recurring purchase obligations. Diagnostic laboratories in Germany negotiate multi-year reagent supply contracts tied to analyzer service agreements as EU MDR recertification timelines delay hardware replacement decisions.
- Test Kits:Disposable unit-dose systems enable point-of-care urinalysis without capital infrastructure.
- Consumables:Cuvettes, pipette tips, and sample tubes represent high-frequency procurement with limited supplier switching costs.
Volume placements concentrate in Analyzers; the faster expansion belongs to Reagents.
End User:
Customer type determines pricing power, with consolidated hospital systems extracting steeper discounts than fragmented clinic networks.
- Diagnostic Laboratories:Reference networks centralize high-throughput urinalysis capacity away from hospital in-house operations to capture economies of scale. These facilities in the United States deploy automated analyzers with direct laboratory information system integration for streamlined reporting. The segment's expansion accelerates as payers recalibrate reimbursement toward centralized testing hubs.
- Hospitals:Emergency departments and inpatient units demand rapid turnaround for renal function assessment and urinary tract infection confirmation. Academic medical centers in Japan anchor demand for advanced flow cytometry systems with artificial intelligence classification algorithms.
- Clinics:Limited capital budgets constrain automated platform adoption in favor of manual microscopy or dipstick methods.
- Research Institutes:Longitudinal renal function studies generate specialized demand for standardized sediment imaging datasets.
Revenue concentration tilts toward Diagnostic Laboratories; Clinics are climbing the fastest as point-of-care testing expands.
Application:
Disease-specific testing volumes track chronic condition prevalence and acute infection incidence across patient populations.
- Urinary Tract Infections:Frontline screening for bacteriuria and pyuria drives the highest sample throughput in clinical laboratories. Automated analyzers with bacterial detection algorithms reduce time-to-result for emergency department patients. The application benefits from standardized reimbursement codes that favor automated microscopy over manual methods.
- Renal Disorders:Cast classification and crystal identification require precise morphological assessment for glomerular and tubular disease monitoring. Academic medical centers deploy deep-learning convolutional neural networks trained on annotated image libraries to reduce inter-operator variability.
- Diabetes Monitoring:Glucose and ketone screening through dipstick methods limits sediment microscopy demand.
- Pregnancy Tests:Hormone detection operates outside sediment analysis workflows entirely.
Sample volume concentrates in Urinary Tract Infections; Renal Disorders command the steepest expansion trajectory as chronic kidney disease surveillance intensifies.
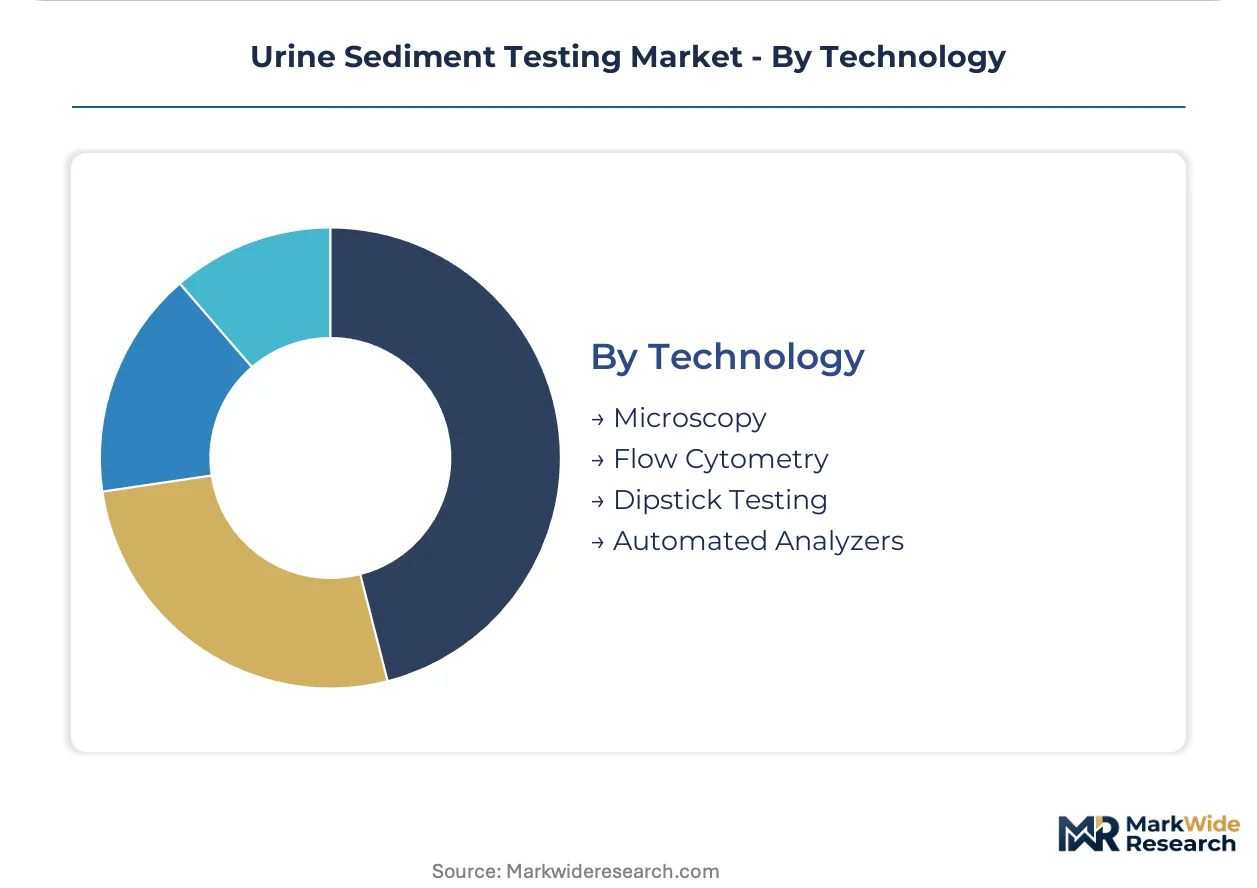
Technology:
Platform selection determines labor intensity, standardization, and integration depth with enterprise laboratory networks.
- Automated Analyzers:Imaging cytometry systems with artificial intelligence classification compress diagnostic validation from hours to minutes while generating auditable particle datasets. Sysmex Corporation anchors its competitive position in Japan through dedicated flow cytometry channels for particle recognition. Siemens Healthineers leverages installed base relationships to sustain service contract renewals across German university hospitals.
- Microscopy:Bright-field manual examination at 400x magnification remains the reference standard for cast morphology assessment. The declining population of trained microscopists creates operational bottlenecks during automated system downtime.
- Flow Cytometry:Dedicated channels enable faster cast and crystal classification than imaging-based methods.
- Dipstick Testing:Chemical analysis strips bypass sediment examination for rapid screening applications.
Installed base concentrates in Automated Analyzers; Flow Cytometry is gaining share fastest as particle recognition accuracy improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American demand for automated urine sediment analyzers, with Massachusetts General Hospital and Brigham and Women's Hospital operating high-throughput reference laboratories that standardize urinalysis workflows across New England integrated delivery networks.
United States
Hospital laboratories in the United States expand automated analyzer fleets to replace manual microscopy under FDA clinical laboratory improvement amendment enforcement. The FDA mandates quality control traceability for commercial analyzers marketed domestically. Academic medical centers in Boston and Baltimore deploy deep-learning classification algorithms for cast identification.
Germany
German university hospitals delay analyzer procurement decisions until EU MDR recertification status clarifies for legacy platform manufacturers. The EU MDR elevates compliance costs for reagent and consumable suppliers through clinical performance evidence requirements. Siemens Healthineers sustains service contract renewals across Munich and Heidelberg hospital clusters.
Japan
Japanese clinical laboratories prioritize flow cytometry channels for particle recognition in urine specimens. The PMDA regulates in vitro diagnostic device approvals with post-market surveillance mandates. Sysmex Corporation anchors its competitive position through dedicated channels deployed in Tokyo and Osaka metropolitan hospital networks.
India
Diagnostic laboratories in India confront import licensing barriers for automated urinalysis instruments enforced by the CDSCO. The country's national pharmaceutical regulator creates differentiated access conditions favoring domestic kit producers partnering with multinational platform suppliers. Reference networks in Mumbai and Bengaluru centralize specialized urinalysis capacity.
United Kingdom
NHS trusts in England consolidate procurement for high-throughput urinalysis operations through regional pathology networks. The MHRA enforces UKCA marking requirements for IVD devices post-Brexit. London teaching hospitals and Manchester reference laboratories drive adoption of automated imaging cytometry with laboratory information system integration.
Urine Sediment Testing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and service bundling dimensions. The vendor base organizes into three tiers: diversified diagnostics conglomerates with installed base leverage, specialized flow cytometry instrument manufacturers, and regional reagent suppliers competing on consumable pricing. Three strategic archetypes dominate: fleet management specialists capturing multi-year service agreements, algorithm developers licensing AI classification software, and unbundled service providers penetrating procurement teams with separate hardware and maintenance contracts. Competitive intensity centers on M&A activity consolidating reagent portfolios and strategic partnerships embedding analyzers into reference laboratory networks.
Within the diversified diagnostics conglomerate tier, Siemens Healthineers AG and Danaher Corporation represent archetypes of installed base leverage and acquisition-driven portfolio expansion respectively. Sysmex Corporation exemplifies the specialized flow cytometry instrument manufacturer archetype with dedicated channel technology. Abbott and BD (Becton, Dickinson and Company) occupy positions spanning both instrument and consumable supply across hospital and diagnostic laboratory end users.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| F. Hoffmann-La Roche Ltd |
| Abbott |
| Sysmex Corporation |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| BD (Becton, Dickinson and Company) |
| Bio-Rad Laboratories Inc. |
| ARKRAY Inc. |
| Others |
Supply Flow & Price Mechanics
Trained microscopist concentration in Germany and Japan sustains labor-cost premiums that widen pricing spreads between automated analyzer tiers and manual microscopy service levels. EU MDR compliance investments and FDA validation timelines further stratify procurement budgets across integrated delivery networks and independent diagnostic laboratories.
Pricing Analysis
Uptime-guarantee service contracts anchor value-based pricing for automated urine sediment analyzers, with penalty clauses for downtime replacing traditional capital purchase models. Three-tier pricing structure across premium, standard, and economy levels reflects analyzer throughput capacity, AI classification algorithm sophistication, and bundled reagent supply terms. Cost compression in the economy tier intensifies as domestic kit producers in India undercut multinational instrument pricing through CDSCO import licensing partnerships. Independent diagnostic laboratories exhibit highest price sensitivity due to capital budget constraints, while academic medical centers prioritize algorithm accuracy over unit economics.
Supply Chain Analysis
Direct-to-hospital-system channels handle high-throughput analyzer demand from United States integrated delivery networks, with separate reagent distribution through regional laboratory supply distributors. Manufacturing concentration rests on Germany for precision optical components, Japan for flow cytometry channel assemblies, and the United States for AI classification software modules. Key dependencies include CMOS imaging sensors, specialized staining reagents, and calibration particulate standards. Single-source vulnerability in EU MDR-certified reagent suppliers creates procurement bottlenecks as recertification timelines extend. Distribution runs through manufacturer-direct sales for capital equipment and third-party logistics networks for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around automated platform vendors with installed base leverage, as EU MDR recertification costs and FDA validation timelines force smaller reagent suppliers toward acquisition or exit.
For Market Incumbents: Deepen service contract penetration through multi-year uptime guarantees with penalty structures that lock hospital laboratories into captive reagent supply. Expand backward integration into AI classification algorithm development to defend against software-licensing entrants. Prioritize EU MDR technical documentation completion to capture delayed replacement cycles in German and French hospital systems. For New Entrants and Emerging Players: Capture white-space in Indian diagnostic laboratories by partnering with domestic kit producers to navigate CDSCO import licensing barriers. Target point-of-care clinic segments underserved by capital-intensive automated platforms through disposable test kit innovations. Lead with telepathology integration capabilities that enable remote microscopist review for health systems facing trained operator shortages. For Investors and Strategic Acquirers: Re-rating potential sits with specialized flow cytometry instrument manufacturers given accelerating displacement of bright-field microscopy by particle recognition channels. Long-term viability favors vendors with hybrid hardware-software revenue models and recurring reagent streams over pure equipment plays. Monitor FDA reimbursement code recalibration for automated microscopy versus flow cytometry methodologies as the inflection signal for platform technology winners.| Strategic Initiative | Industry Significance |
|---|---|
| AI Classification Algorithm Licensing | Software revenue streams reduce capital equipment cyclicality for analyzer vendors. |
| EU MDR Recertification Acceleration | Early compliance unlocks frozen procurement cycles in German university hospitals. |
| Integrated Delivery Network Fleet Consolidation | Volume discounts and unified service agreements strengthen incumbent pricing power. |
| Domestic Kit Producer Partnership | CDSCO licensing navigation enables multinational platform access to Indian reference networks. |
| Telepathology Platform Integration | Remote review capabilities address microscopist skill attrition in United States health systems. |
Methodological Framework
Independent corroboration across laboratory operations directors, biomedical equipment procurement managers, and clinical pathology consultants underwrites the qualitative findings. Primary fieldwork captured instrument utilization patterns, reagent contract structures, and validation timeline experiences across hospital and diagnostic laboratory settings. Secondary validation drew from FDA 510(k) filings for automated urine sediment analyzers, EU MDR technical documentation databases, CMS Medicare reimbursement code schedules, and hospital procurement records from integrated delivery networks. Bottom-up sizing of analyzer placements and reagent consumption triangulated against top-down diagnostic testing volume estimates.
Rate-of-change decomposition across the projection horizon separates volume growth in testing procedures from value capture in automation substitution and premium algorithm adoption. Segmentation modeling incorporated product type, end user, application, and technology platform dimensions alongside regional regulatory cluster variations. CAGRs were derived from instrument replacement cycle analysis and recurring consumable attach rates. Industry-specific forecast inputs included CLIA-mandated standardization timelines and EU MDR recertification completion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to reimbursement code recalibration, microscopist training pipeline recovery, and AI classification accuracy validation. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and laboratory consolidation momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Rapid Test Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
STD Testing Devices Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Adiponectin Testing Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Pneumococcal Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Europe IVD Regulatory Affairs Outsourcing Market
Testing Services
Home DNA Testing Market