
 Asia Pacific Multi-Cancer Early Detection Market | 2026-2036
Asia Pacific Multi-Cancer Early Detection Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Multi-Cancer Early Detection Market Insights
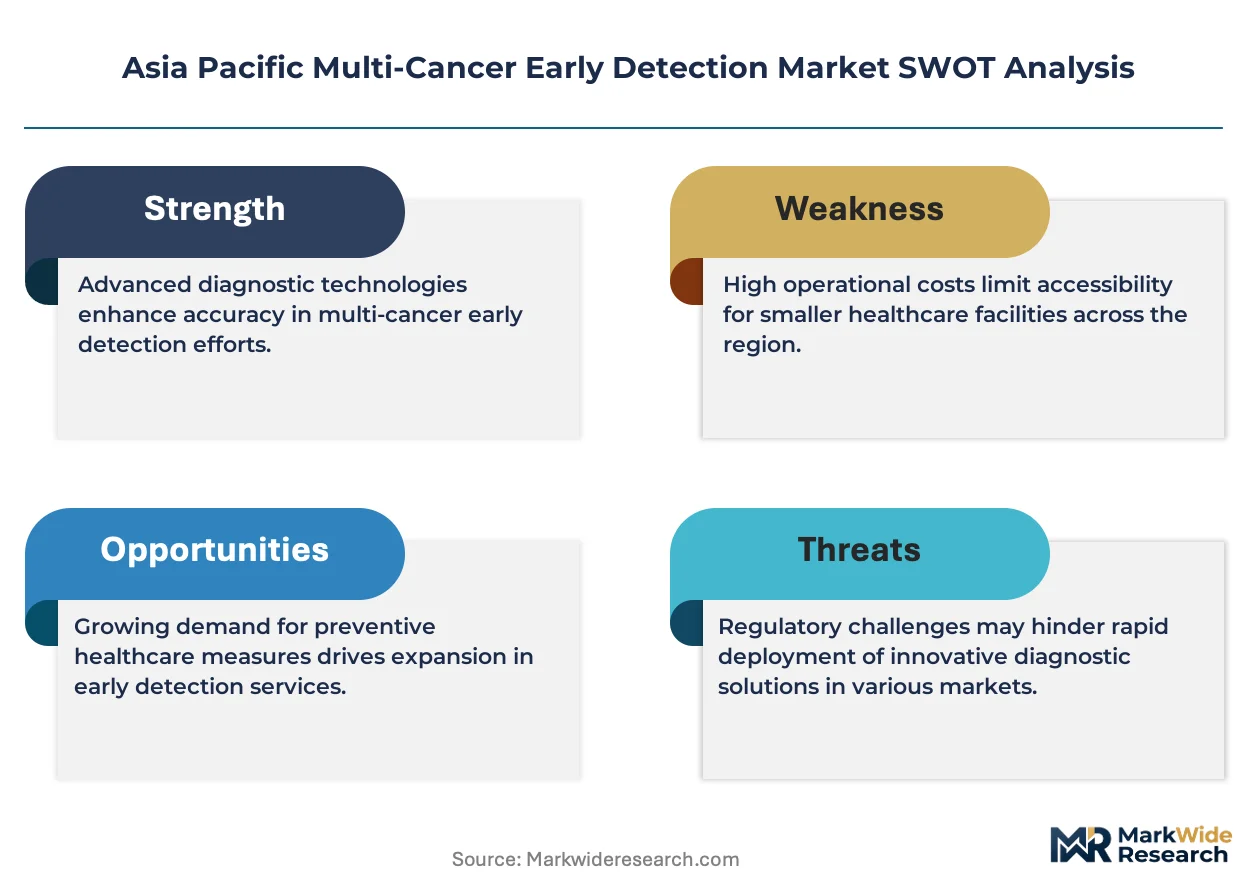
Project finance for large-scale sequencing infrastructure is tilting competitive advantage toward asset-light diagnostic platforms that minimize capital deployment. Burning Rock Biotech Limited leverages its vertically integrated NGS pipeline to control reagent costs across Greater China. GENECAST anchors its position through deep specialization in methylation-based early detection assays for liver and gastrointestinal malignancies. Illumina, Inc. dominates instrument placement across Asia Pacific reference laboratories, creating captive demand for its consumables ecosystem.
Multi-cancer early detection encompasses blood-based screening panels that simultaneously interrogate circulating tumor DNA, methylation patterns, and protein biomarkers to identify malignant signals prior to symptomatic presentation; these assays typically require 10-20 mL whole blood and employ targeted or whole-genome sequencing with analytical specificity exceeding 99% to minimize false-positive referral burden. Liquid biopsy platforms command the largest revenue share given their compatibility with existing phlebotomy infrastructure and scalable automation, while next-generation sequencing underpins the technology architecture with the steepest throughput improvement curves. Diagnostic centers represent the fastest-growing end-user channel as decentralized collection networks reduce patient travel friction and accelerate sample-to-result intervals.
Japan's PMDA, China's NMPA, and South Korea's MFDS each maintain distinct evidentiary thresholds for multi-cancer test approval, fragmenting registration strategy and prolonging market access timelines for pan-Asian product launches. China's GB standards for in-vitro diagnostics and South Korea's reimbursement pricing guidelines for novel screening technologies further shape commercialization economics and patient access. Stakeholders must monitor harmonization initiatives across these regulatory regimes to anticipate where centralized manufacturing and unified clinical trial designs could unlock margin expansion.
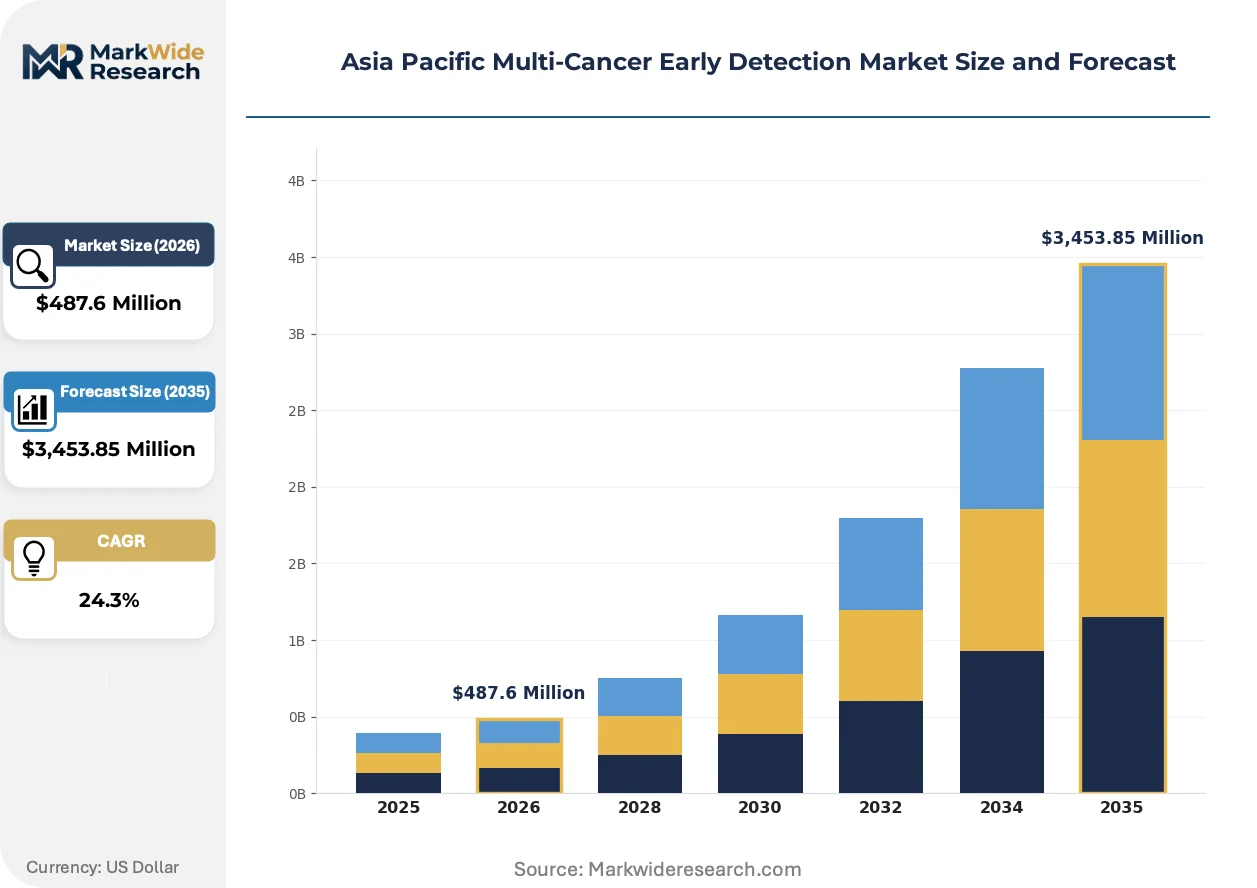
Market Dynamics
Capital deployment for sequencing infrastructure is tilting competitive advantage toward asset-light diagnostic platforms that minimize fixed-cost exposure across China, Japan, and South Korea.
Growth Catalysts
- PMDA Accelerated Approval:Japan's pharmaceutical and medical device agency compresses commercialization timelines for companion diagnostics, incentivizing early-stage test development.
- National Screening Networks:South Korea's MFDS-backed expansion of population-scale screening programs creates institutional demand for multi-cancer panels.
- Phlebotomy Infrastructure:Existing blood collection networks across tier-one Chinese oncology centers enable rapid liquid biopsy deployment without capital-intensive site buildouts.
Market Restraints
- Reagent Cost Volatility:Proprietary NGS chemistries and methylation assay kits concentrate pricing power with dominant consumables suppliers.
- Regulatory Fragmentation:Divergent evidentiary thresholds across China's NMPA, Japan's PMDA, and South Korea's MFDS prolong pan-Asian registration timelines.
- False-Positive Burden:Analytical specificity requirements exceeding 99% demand extensive validation cohorts, elevating development costs for novel biomarker combinations.
Strategic Opportunities
- Tier-Two Hospital Penetration:China's provincial oncology centers remain underserved by centralized reference laboratory networks.
- Methylation-Protein Convergence:Integration of circulating tumor DNA methylation patterns with protein biomarker quantification enables higher-sensitivity early detection.
- Diagnostic Center Channel:Decentralized collection networks reduce patient travel friction and compress sample-to-result intervals in Japan's urban corridors.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists capable of integrating multi-omic data streams constrains assay development velocity.
- Interoperability Complexity:Integration of multi-cancer test results with hospital electronic health record systems requires customized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Multi-Cancer Early Detection Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $3,453.85 Million |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Biopsy, Imaging Techniques, Biomarker Tests, Genetic Testing Technology: Next-Generation Sequencing, PCR, Mass Spectrometry, Microarray End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Application: Prostate Cancer, Breast Cancer, Colorectal Cancer, Lung Cancer |
| Companies Covered | AnchorDx, Burning Rock Biotech Limited, Grail, LLC, Singlera Genomics Inc., GENECAST, Illumina, Inc., Guardant Health, Laboratory for Advanced Medicine, Inc., Exact Sciences Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Multi-Cancer Early Detection Market Trends and Innovations
Technology convergence and regulatory pathway innovation are compressing development-to-deployment cycles for blood-based screening platforms across the region.
Targeted methylation sequencing is hybridizing with protein biomarker detection to create composite scoring algorithms that improve sensitivity for stage I malignancies. Reference laboratories in Shanghai and Tokyo are adopting these hybrid panels at accelerating pace. The technology is hybridizing previously distinct assay workflows, enabling single-sample multi-omic analysis that reduces per-test operational cost.
China's NMPA has established dedicated review channels for breakthrough in-vitro diagnostics, compressing registration timelines for novel screening technologies. This regulatory innovation reduces capital lockup during pre-market phases. Liver and gastrointestinal cancer panels receive priority designation, reflecting disease burden priorities in the national cancer control program.
Hospital procurement departments are consolidating vendor relationships around integrated platform providers capable of delivering instruments, reagents, and interpretive software under unified contracting frameworks. Independent diagnostic centers in South Korea's national screening network are displacing fragmented supplier arrangements with single-source partnerships. This concentration is most visible in Seoul's metropolitan laboratory cluster, where three reference networks now account for the majority of liquid biopsy volume.
Asia Pacific Multi-Cancer Early Detection Market Segmentation
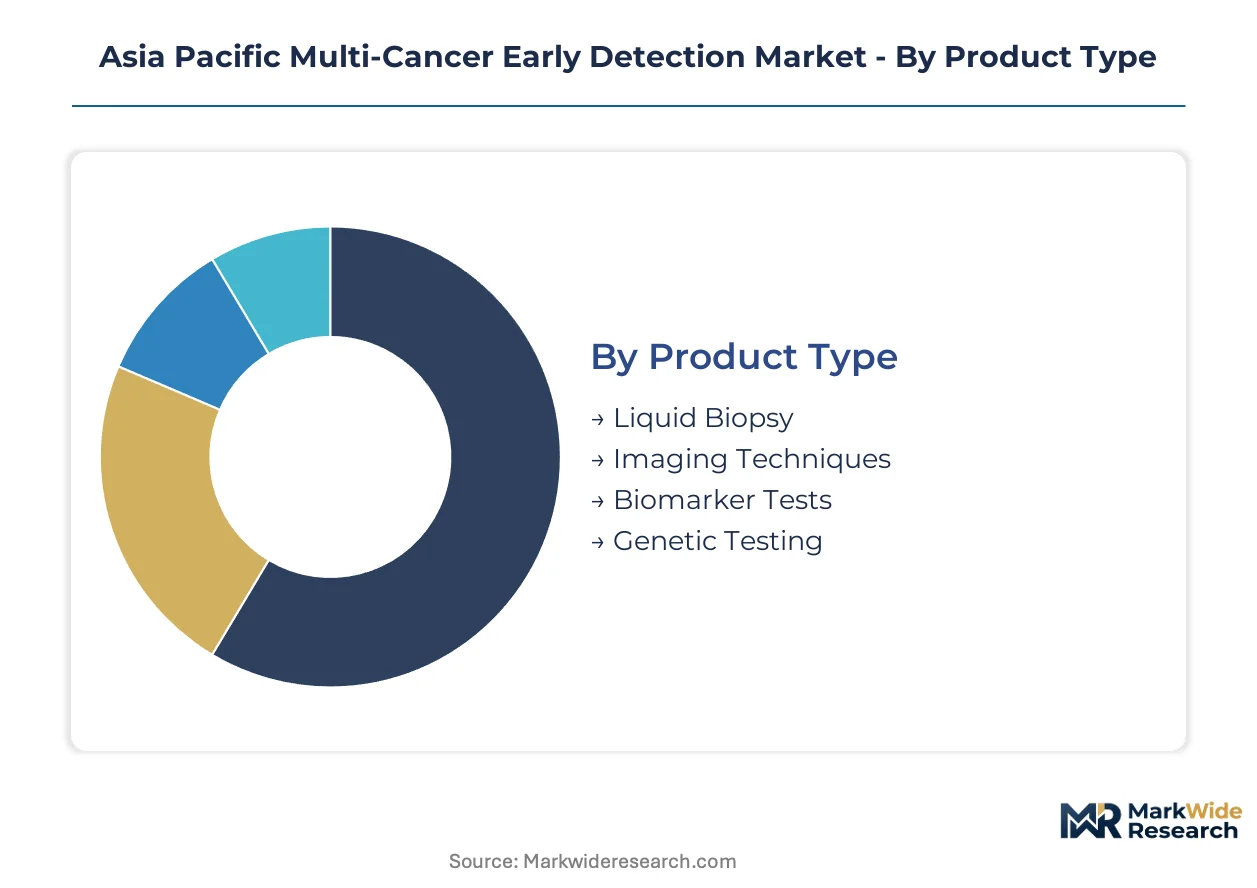
Segmentation in the Asia Pacific multi-cancer early detection market reveals divergent capital intensity and reimbursement pathways across technology platforms. Product architecture choices directly determine regulatory complexity and commercial scalability across China's NMPA, Japan's PMDA, and South Korea's MFDS jurisdictions.
Product Type:
Cycle times vary dramatically: consumable-based assays turn inventory weekly while capital equipment amortizes over years. Liquid biopsy panels and biomarker tests rotate fastest through diagnostic workflows.
- Liquid Biopsy:Blood-based assays interrogate circulating tumor DNA and methylation patterns using 10-20 mL whole blood samples. Demand concentrates in China's tier-one oncology centers and South Korea's national screening networks, driven by compatibility with existing phlebotomy infrastructure and scalable automation.
- Biomarker Tests:Protein and metabolite quantification platforms deliver rapid turnaround without sequencing infrastructure. Japanese reference laboratories in Tokyo and Osaka are expanding adoption of multiplex protein panels, constrained by PMDA validation requirements for novel biomarker combinations.
- Imaging Techniques:Radiomics and AI-enhanced imaging for early lesion detection.
- Genetic Testing:Germline and somatic variant analysis for hereditary cancer risk stratification.
Liquid biopsy dominates installed base. Biomarker tests are where expansion concentrates.
Technology:
Cost tiers separate high-throughput sequencing infrastructure from benchtop alternatives. NGS platforms command premium positioning while PCR maintains economy-tier accessibility.
- Next-Generation Sequencing:Targeted and whole-genome sequencing architectures underpin multi-cancer panels with analytical specificity exceeding 99%. Illumina instrument placements across Shanghai, Beijing, and Tokyo reference laboratories create captive demand for consumables ecosystems.
- PCR:Digital and quantitative PCR delivers rapid, cost-effective amplification for known mutation hotspots. Diagnostic centers in South Korea's national screening network favor PCR for hepatitis B viral load monitoring as a liver cancer precursor assay.
- Mass Spectrometry:Proteomic and metabolomic detection for protein biomarker quantification.
- Microarray:Methylation pattern interrogation and copy number variation analysis.
NGS commands premium pricing tier. PCR delivers volume penetration at economy positioning.
End User:
Customer type determines procurement pathway and service intensity requirements. Diagnostic centers and hospitals operate on fundamentally different capital deployment models.
- Diagnostic Centers:Decentralized collection networks reduce patient travel friction and compress sample-to-result intervals. Seoul's metropolitan laboratory cluster and Shanghai's independent diagnostic facilities are expanding liquid biopsy volume fastest.
- Hospitals:China's provincial oncology centers and Japan's cancer centers integrate multi-cancer testing with treatment planning workflows. Procurement departments consolidate vendor relationships around integrated platform providers.
- Laboratories:Centralized reference networks processing high-complexity assays.
- Research Institutions:Academic medical centers conducting biomarker discovery and clinical validation studies.
Hospitals anchor current revenue. Diagnostic centers are climbing the fastest.
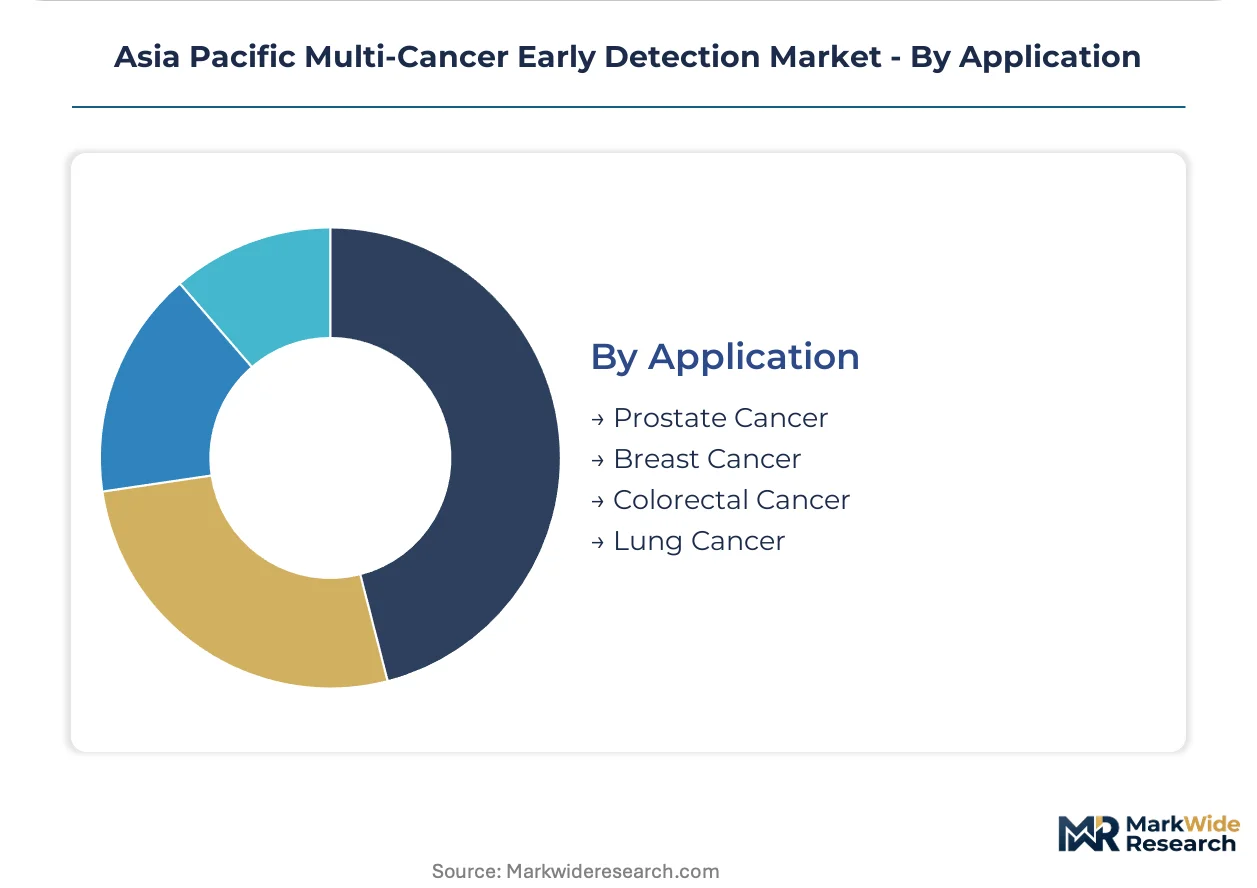
Application:
Disease burden and screening infrastructure maturity shape geographic prioritization. Liver and gastrointestinal malignancies receive regulatory priority in China's national cancer control program.
- Lung Cancer:Highest mortality burden across China and Japan drives screening program investment. Low-dose CT adjunct blood tests are penetrating urban screening networks in Beijing and Tokyo where smoking prevalence remains elevated.
- Colorectal Cancer:Fecal immunochemical test follow-up protocols create entry point for blood-based alternatives. South Korea's national screening program expansion targets colorectal malignancies alongside gastric cancer given dietary risk factors.
- Breast Cancer:Mammography adjunct and risk stratification applications.
- Prostate Cancer:PSA controversy creates demand for specificity-enhancing multi-omic approaches.
Lung cancer commands development priority. Colorectal cancer is gaining share fastest in reimbursement negotiations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National cancer control programs across Asia Pacific are directing public reimbursement toward blood-based screening modalities. Governments in China, Japan, and South Korea have established dedicated regulatory channels for multi-cancer test approval. This policy alignment is compressing market access timelines while fragmenting technical standards.
China
Provincial oncology centers in Guangdong and Jiangsu are expanding liquid biopsy procurement beyond tier-one hospitals. NMPA breakthrough designation for in-vitro diagnostics reduces pre-market capital lockup. Shanghai's Zhangjiang Hi-Tech Park hosts concentrated assay development activity for liver and gastrointestinal panels.
Japan
Tokyo and Osaka cancer centers are integrating multi-cancer testing with treatment planning workflows. PMDA accelerated approval pathways compress commercialization timelines for companion diagnostics. The Kanto region's reference laboratory cluster dominates instrument placement and consumables demand.
South Korea
MFDS-backed expansion of population-scale screening programs creates institutional demand for multi-cancer panels. Seoul's metropolitan laboratory cluster is consolidating vendor relationships around integrated platform providers. Busan-Ulsan's diagnostic facilities are adopting decentralized collection networks to reduce patient travel friction.
Australia
TGA regulatory frameworks for novel screening technologies shape reimbursement negotiations for blood-based assays. Sydney and Melbourne reference laboratories are evaluating methylation-protein hybrid panels for lung cancer adjunct applications. The Southeast corridor's phlebotomy infrastructure supports rapid deployment without capital-intensive site buildouts.
Singapore
Biomedical research agencies are funding biomarker discovery programs for early detection of Asian-prevalent malignancies. The national precision medicine initiative creates demand for multi-omic analysis capabilities. One-North and Biopolis research clusters host concentrated assay validation activity.
Asia Pacific Multi-Cancer Early Detection Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated platform providers and specialized assay developers. Tier-one sequencing instrument manufacturers command captive consumables demand through installed base expansion. Three archetypes dominate: NGS infrastructure owners, methylation assay specialists, and liquid biopsy platform operators. Competitive moves center on hospital procurement consolidation and diagnostic center channel partnerships.
Within the vertically integrated tier, Burning Rock Biotech Limited and GENECAST exemplify contrasting specialization strategies. Burning Rock anchors Greater China positioning through NGS pipeline control. GENECAST occupies a position centered on methylation-based detection for liver and gastrointestinal applications. Illumina, Inc. sits within the infrastructure layer, with instrument placements across Shanghai, Beijing, and Tokyo reference laboratories creating downstream reagent demand.
| Leading Market Players |
|---|
| AnchorDx |
| Burning Rock Biotech Limited |
| Grail, LLC |
| Singlera Genomics Inc. |
| GENECAST |
| Illumina, Inc. |
| Guardant Health |
| Laboratory for Advanced Medicine, Inc. |
| Exact Sciences Corporation |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in high-complexity sequencing reagent manufacturing across Greater China is compressing margins for independent assay developers while amplifying pricing power for vertically integrated platform owners. This utilization asymmetry forces mid-tier diagnostic companies toward contract manufacturing partnerships or captive production investments.
Pricing Analysis
Certification level creates the primary spread between NMPA-approved, PMDA-cleared, and research-use-only assay tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium NGS panels commanding substantial markups for regulatory-grade validation data. Cost compression in economy-tier PCR consumables is intensifying because of raw material pass-through from polymerase suppliers. Hospital procurement committees exhibit lowest price sensitivity for companion diagnostic applications, while independent diagnostic centers negotiate aggressively on reagent volume commitments.
Supply Chain Analysis
Contract manufacturing for methylation assay kits concentrates in Suzhou and Singapore bioproduction parks, with Thermo Fisher and local CMOs holding dominant capacity positions. Sequencing instrument supply draws from California, Singapore, and Japan, while critical reagent chemistries rest on single-source suppliers in Massachusetts and Basel. Single-source vulnerability for proprietary NGS flow cells creates bottleneck risk. Distribution runs through hospital GPO networks in China, direct instrument placement in Japan, and national tender channels in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific multi-cancer early detection market represents a high-growth disruption driven by PMDA breakthrough designation pathways compressing development-to-deployment cycles from years to months.
For Market Incumbents: Harden defensive positions by securing exclusive reagent supply contracts with Shanghai and Tokyo reference laboratories before NMPA regulatory harmonization accelerates. Prioritize backward integration into methylation oligonucleotide synthesis to offset polymerase cost volatility. Lock in diagnostic center channel partnerships across Seoul's metropolitan laboratory cluster to preempt entrant access.
For New Entrants and Emerging Players: Tier-two provincial oncology centers in Jiangsu and Guangdong represent the most penetrable entry point, given underserved phlebotomy infrastructure and fragmented supplier relationships. Liver cancer screening panels for China's national cancer control program offer fastest regulatory pathway traction. Pursue white-label partnerships with existing NMPA-licensed reference laboratories to bypass capital-intensive instrument placement requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light liquid biopsy platforms utilizing third-party sequencing infrastructure. Five-to-ten-year viability favors assay developers with differentiated methylation-protein hybrid intellectual property over pure infrastructure plays. Monitor MFDS reimbursement decisions for colorectal cancer adjunct applications as inflection signal for South Korean market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Breakthrough Designation Pursuit | Compresses pre-market capital lockup for liver and gastrointestinal panels in Shanghai development clusters. |
| Diagnostic Center Channel Partnership | Secures decentralized collection volume in Seoul and Busan-Ulsan corridors ahead of competitor consolidation. |
| Methylation-Protein Hybrid Assay Development | Enables stage I sensitivity improvement for lung cancer applications in Tokyo cancer center networks. |
| Reference Laboratory Instrument Placement | Creates captive consumables demand across Beijing and Osaka high-throughput sequencing facilities. |
| PMDA Companion Diagnostic Alignment | Accelerates commercialization timelines for pharmaceutical co-development partnerships in Kanto region. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NMPA registration databases, PMDA approval records, and hospital procurement disclosures. Primary interviews engaged regulatory affairs directors at assay developers, procurement managers at tier-one oncology centers, and biomedical engineers at reference laboratories across Shanghai, Tokyo, and Seoul. Secondary validation drew from ClinicalTrials.gov entries, MFDS reimbursement bulletins, and GPO contract award notices. Bottom-up assay volume estimates triangulate against top-down national screening program budget allocations.
Forecast inputs span technology platform adoption curves, regulatory pathway velocity differentials, and reimbursement negotiation timelines across the analysis window. Segmentation dimensions include product type, technology architecture, end-user channel, and cancer application. CAGRs derive from logistic diffusion modeling of liquid biopsy penetration rates against population screening eligibility expansion. Industry-specific inputs incorporate NMPA breakthrough designation approval rates and PMDA accelerated pathway utilization patterns.
Macroeconomic conditions sit as an overlay; deviation in public health expenditure growth or biotech venture capital availability would shift the trajectory. Forecasts reflect assumptions about regulatory harmonization progress and reagent cost stabilization. Quarterly review of NMPA registration queue depths and MFDS reimbursement schedule updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market