
 Non-Hodgkin Lymphoma Diagnostics Market | 2026-2036
Non-Hodgkin Lymphoma Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Hodgkin Lymphoma Diagnostics Market Intelligence
The shift towards specialized diagnostic laboratories as primary testing sites is rewriting traditional hospital-centric distribution channels. Roche leverages its extensive portfolio in both diagnostics and therapeutics, creating integrated solutions for these labs. Separately, Novartis competes through its focus on innovative cell and gene therapies that depend on precise companion diagnostics. Pfizer sustains its market position through strategic partnerships with diagnostic technology firms to broaden its testing capabilities.
Non-Hodgkin Lymphoma diagnostics encompass a range of laboratory and imaging techniques used to detect and classify malignancies of the lymphoid system. These tests often analyze specific cell surface antigens, such as CD20, to differentiate between the over 60 subtypes of the disease. While biopsy remains the gold standard for initial diagnosis, molecular tests using technologies like Next-Generation Sequencing represent the fastest-growing product segment. Flow cytometry continues to be essential for rapid immunophenotyping in hospitals and large diagnostic laboratories.
Approvals from regulatory bodies like the US FDA, the European Medicines Agency (EMA), and China's NMPA govern market access. These agencies mandate stringent clinical validation for new assays, particularly for companion diagnostics linked to targeted therapies, influencing development timelines. Stakeholders must navigate evolving reimbursement policies for advanced molecular tests to ensure broad patient access and commercial viability.
Market Dynamics
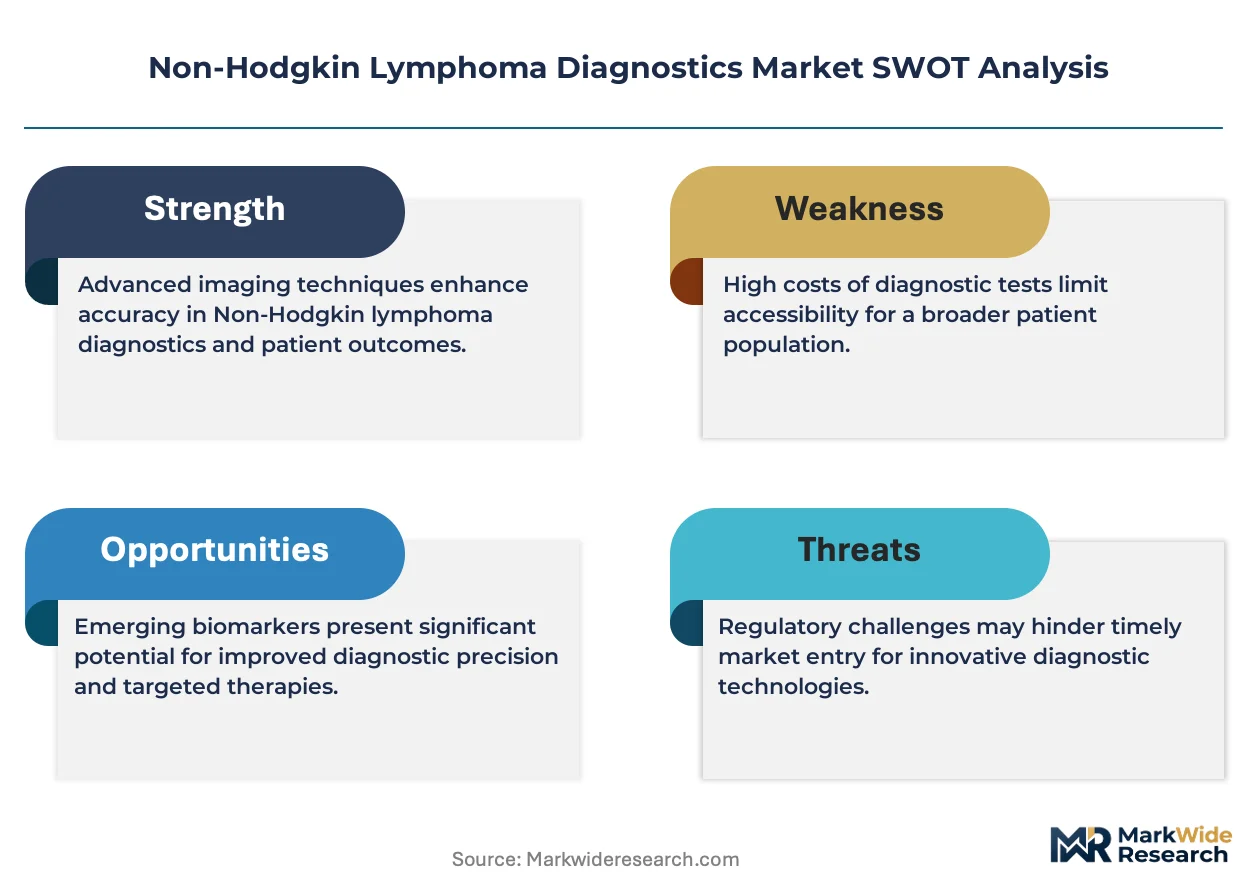
The central force shaping the market is the clinical shift toward precision oncology. This movement is driven by the integration of advanced molecular technologies like Next-Generation Sequencing, which enables highly specific subtyping essential for guiding targeted therapies.
Growth Catalysts
- Companion Diagnostic Development:The expanding pipeline of targeted therapies for specific NHL subtypes creates a direct pull for co-developed companion diagnostics, mandated by regulators like the US FDA to ensure patient stratification and treatment efficacy.
- Rising Disease Incidence:An increasing incidence of Non-Hodgkin Lymphoma, particularly in aging populations across North America and Western Europe, directly expands the patient pool requiring initial diagnosis and subsequent monitoring, increasing overall test volumes.
- Technological Advancement in Molecular Testing:Continuous improvements in the sensitivity and speed of technologies such as digital PCR and NGS allow for earlier detection and more accurate characterization of lymphoid malignancies, encouraging their adoption in clinical practice.
Market Restraints
- High Cost of Advanced Assays:The significant cost associated with Next-Generation Sequencing and other multiplex molecular tests can limit their accessibility, particularly in healthcare systems with constrained budgets or unfavorable reimbursement landscapes.
- Complexity of Data Interpretation:The vast amount of data generated by genomic tests requires specialized bioinformatics expertise for analysis and clinical interpretation, creating a bottleneck due to a shortage of qualified personnel.
- Stringent Regulatory Hurdles:New diagnostic assays, especially those intended as companion diagnostics, face lengthy and rigorous validation processes mandated by agencies like the European Medicines Agency, delaying market entry.
Strategic Opportunities
- Expansion in Emerging Markets:There is a significant opportunity to establish diagnostic infrastructure and services in markets like Brazil and India, where healthcare spending is increasing and awareness of advanced cancer diagnostics is growing.
- Development of Liquid Biopsies:Creating and commercializing non-invasive liquid biopsy tests for monitoring treatment response and detecting minimal residual disease represents a major area for innovation, offering a less invasive alternative to tissue biopsies.
- AI-Powered Diagnostic Platforms:Integrating artificial intelligence algorithms with pathology and molecular data can enhance diagnostic accuracy, automate subtype classification, and predict patient outcomes, offering significant value to laboratories and clinicians.
Industry Challenges
- Data Standardization and Interoperability:A lack of standardized protocols for molecular testing and data reporting across different laboratories hinders the comparability of results and the creation of large, cohesive datasets for research and clinical validation.
- Reimbursement Policy Uncertainty:Evolving and often inconsistent reimbursement policies for advanced molecular diagnostics create commercial uncertainty for manufacturers and can limit patient access to innovative tests in key markets.
- Skilled Workforce Shortage:The field faces a persistent shortage of pathologists and laboratory technicians with dual expertise in traditional histology and complex molecular genetics, which is necessary to fully leverage advanced diagnostic tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Hodgkin Lymphoma Diagnostics Market |
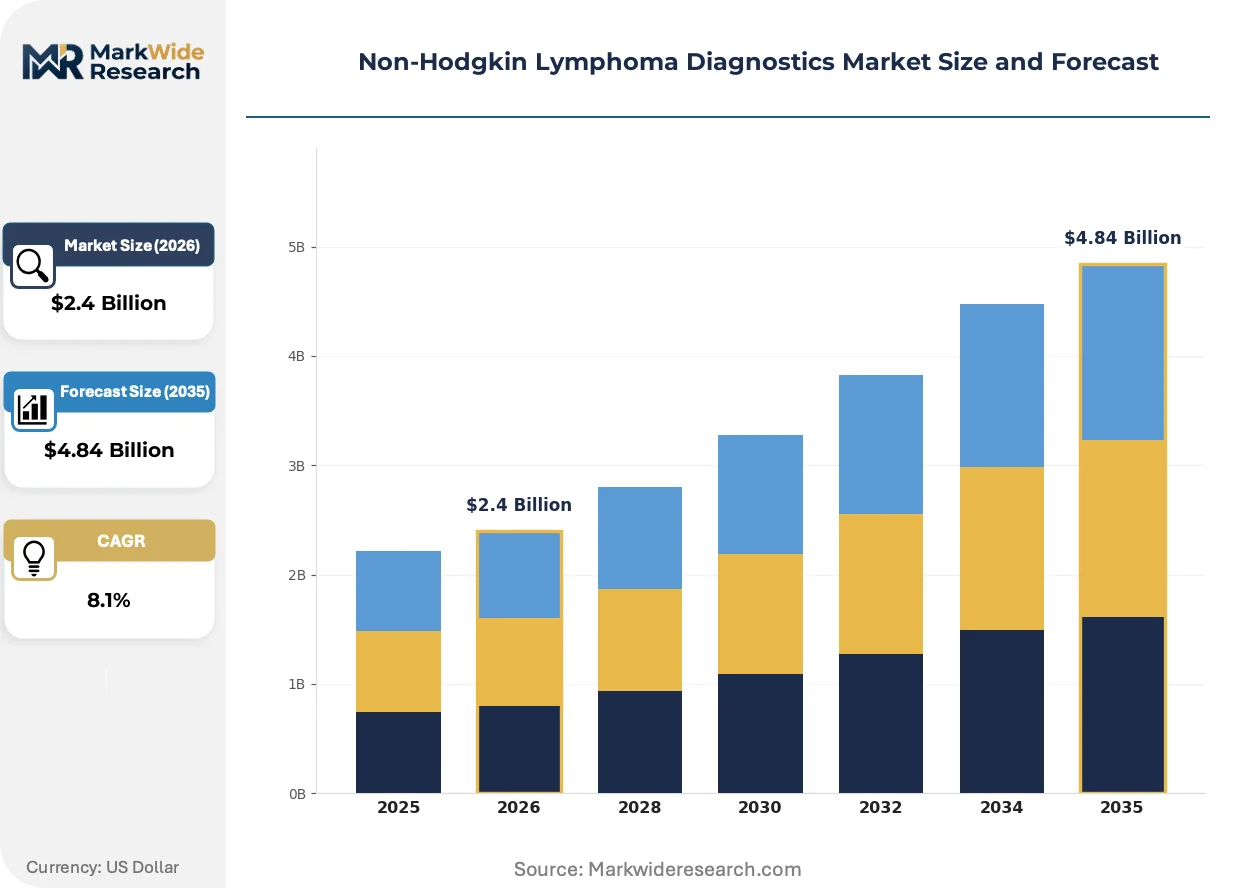
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Blood Tests, Molecular Tests Technology: Immunohistochemistry, Flow Cytometry, PCR, NGS End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Distribution Channel: Direct Sales, Online Stores, Distributors, Retail Pharmacies |
| Companies Covered | Novartis, Merck & Co., Roche, Pfizer, Amgen, AbbVie, Gilead Sciences, Janssen Biotech, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Hodgkin Lymphoma Diagnostics Market Strategic Shifts & Innovations
Technological convergence is redefining diagnostic capabilities in Non-Hodgkin Lymphoma. The fusion of high-throughput sequencing with advanced imaging and artificial intelligence is creating more integrated, predictive, and personalized approaches to disease management, moving beyond simple detection and classification.
Liquid biopsy technology is emerging as a powerful tool for non-invasive disease monitoring. Oncology clinics and specialized laboratories are adopting these tests to analyze circulating tumor DNA (ctDNA) for tracking treatment efficacy and detecting early signs of relapse. The high sensitivity of these assays for identifying molecular changes is rendering obsolete some traditional, invasive follow-up methods like serial tissue biopsies for disease surveillance.
The European Union's In Vitro Diagnostic Regulation (IVDR) is a prominent policy shift impacting the market. This regulation enforces more stringent requirements for clinical evidence, risk management, and post-market surveillance for all diagnostic tests. Manufacturers of NHL diagnostics, particularly companion diagnostics, are most affected, as they must now provide more extensive performance and clinical utility data to gain or maintain CE marking.
A notable behavioral change is the move by large healthcare providers from purchasing individual assays to acquiring integrated diagnostic platforms. This disrupts the conventional fee-for-service model, favoring bundled solutions that combine immunophenotyping, molecular profiling, and data interpretation software into a single workflow. This procurement trend is most apparent in academic medical centers and large commercial laboratories in the United States and Germany.
Non-Hodgkin Lymphoma Diagnostics Market Segmentation
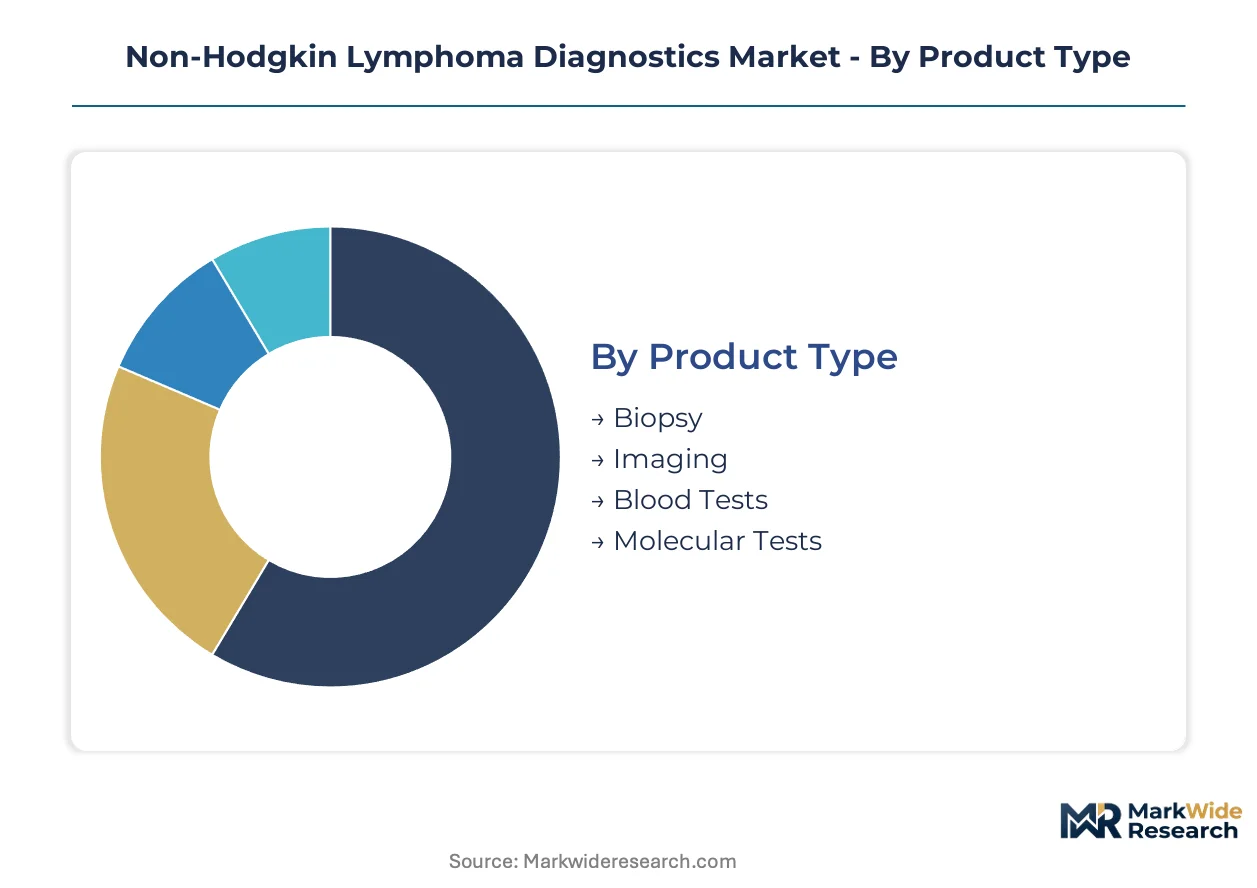
Understanding market segmentation provides critical insights into the varied demands and operational characteristics within the Non-Hodgkin Lymphoma diagnostics landscape. This granular view helps stakeholders identify specific growth pockets and tailor strategies for product development and market penetration. It highlights where innovation is most impactful.
Product Type:
The product type segmentation reveals distinct cycle times, with some diagnostic methods requiring extensive processing while others offer rapid turnaround.
- Molecular Tests:These diagnostics leverage technologies like Next-Generation Sequencing for comprehensive genetic profiling and precise subtype identification. Demand concentrates significantly in specialized diagnostic laboratories across the United States and Western Europe, driven by the increasing integration of precision oncology. These tests are critical for guiding targeted therapies.
- Biopsy:As the gold standard, biopsy involves tissue extraction for definitive pathological examination and initial diagnosis. Global demand remains foundational across all healthcare settings, primarily driven by the necessity for accurate morphological assessment and immunophenotyping before treatment initiation.
- Imaging:Techniques such as CT, PET, and MRI are crucial for disease staging, evaluating tumor burden, and monitoring treatment response.
- Blood Tests:These include routine complete blood counts and lactate dehydrogenase levels, primarily utilized for initial screening and general disease monitoring.
Biopsy dominates the installed base for initial diagnosis. Molecular Tests are where expansion concentrates, particularly for advanced characterization.
Technology:
Technology segmentation differentiates diagnostic approaches based on their functional application and analytical depth, from rapid screening to comprehensive genomic analysis.
- NGS:Next-Generation Sequencing offers high-throughput analysis of genetic mutations and rearrangements, enabling precise subtyping of NHL. Academic medical centers and large commercial laboratories in Germany and the US drive its adoption, leveraging its power for personalized treatment stratification.
- Flow Cytometry:This technique rapidly analyzes cell surface antigens for immunophenotyping, crucial for differentiating lymphoma subtypes. Large diagnostic laboratories and hospital pathology departments globally rely on it for quick and accurate classification of lymphoid malignancies.
- Immunohistochemistry:Utilizing antibody-based staining, this method aids in morphological assessment and specific protein expression analysis in tissue samples.
- PCR:Polymerase Chain Reaction is essential for detecting specific genetic rearrangements and monitoring minimal residual disease with high sensitivity.
Flow Cytometry holds a significant share in rapid immunophenotyping. NGS is gaining share fastest for comprehensive molecular profiling.
End User:
End user segmentation highlights varying operational scales and patient volumes, influencing the type and complexity of diagnostic services required.
- Diagnostic Laboratories:These specialized facilities handle high volumes of complex molecular and immunophenotyping tests, often serving multiple healthcare providers. Their demand for advanced platforms is particularly strong in the United States and Germany, reflecting a shift towards centralized, specialized testing.
- Hospitals:As primary points of patient care, hospitals require a broad range of diagnostic capabilities for initial diagnosis and urgent cases. Demand for integrated solutions and rapid turnaround times is high across Western Europe, supporting immediate clinical decision-making.
- Research Institutions:These entities focus on biomarker discovery, assay development, and clinical trials, driving demand for innovative and experimental diagnostic tools.
- Clinics:Primarily involved in patient screening and sample collection, clinics often rely on external laboratories for advanced diagnostic processing.
Procurement patterns in hospitals prioritize integrated solutions. Diagnostic laboratories are increasingly consolidating their testing platforms.
Distribution Channel:
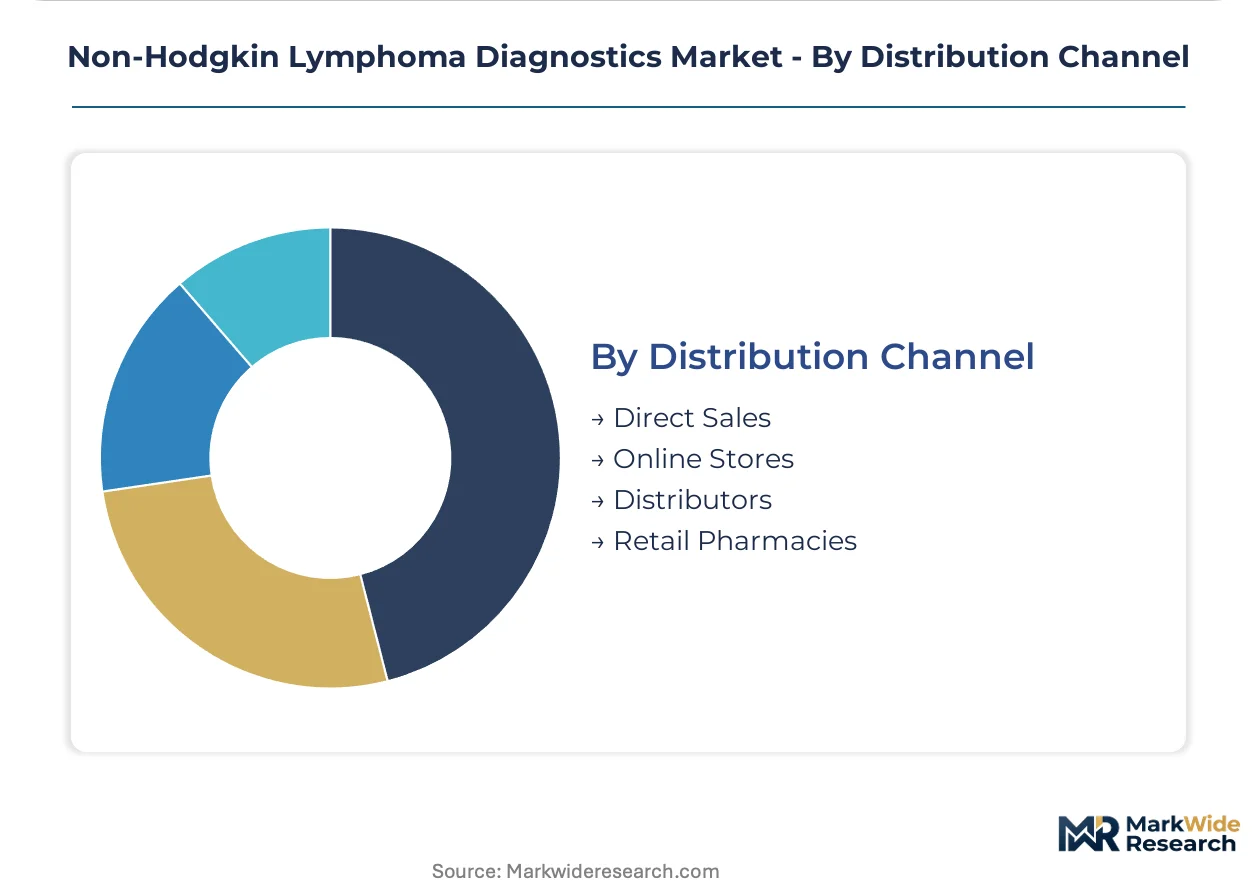
Distribution channel analysis reveals distinct approaches to market access and value capture, ranging from direct manufacturer engagement to broad third-party networks.
- Direct Sales:Manufacturers engage directly with large hospitals and diagnostic networks, offering tailored solutions and technical support. This channel ensures greater control over product messaging and service quality, particularly for complex, high-value diagnostic platforms in the US.
- Distributors:Third-party distributors provide extensive market reach, particularly beneficial for accessing smaller laboratories and healthcare providers in diverse geographies. They manage logistics and local sales, enabling broader penetration in emerging markets like Brazil and India.
- Online Stores:These platforms facilitate the sale of consumables, reagents, and less complex diagnostic kits, offering convenience and competitive pricing for specific items.
- Retail Pharmacies:While not primary diagnostic providers, these outlets can serve as collection points for samples or distribute basic, non-invasive screening tests.
The channel landscape is evolving with a greater emphasis on direct manufacturer engagement. Digital platforms are transforming how niche products reach end-users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry is evident between developed markets like the United States and emerging economies such as Brazil, influencing diagnostic test accessibility. Advanced healthcare infrastructures in Western Europe enable higher cost recovery for complex molecular assays compared to regions with nascent diagnostic capabilities. This disparity shapes investment priorities for diagnostic manufacturers.
United States
High disease incidence and a strong emphasis on precision oncology drive demand for advanced diagnostic solutions. The US FDA mandates stringent clinical validation for new companion diagnostics, directly impacting market entry. Major biotech hubs like Boston and San Francisco are centers for molecular diagnostic innovation and development.
Germany
Germany leads in the adoption of Next-Generation Sequencing for comprehensive molecular profiling in large diagnostic laboratories. The European Medicines Agency (EMA) and IVDR impose rigorous requirements for market access and post-market surveillance. The Munich region houses advanced medical technology firms and specialized diagnostic service providers.
Brazil
Growing healthcare expenditure and increasing awareness of advanced cancer diagnostics are expanding the patient pool for NHL testing. ANVISA, Brazil's national health surveillance agency, regulates the approval and commercialization of diagnostic assays. São Paulo's prominent medical centers are actively developing robust diagnostic infrastructure.
India
India's rising cancer incidence and investments in healthcare infrastructure are creating opportunities for advanced diagnostic services. The Central Drugs Standard Control Organization (CDSCO) governs the approval process for new diagnostic kits and technologies. Bangalore is emerging as a significant hub for medical technology and diagnostic research development.
United Kingdom
The United Kingdom's advanced healthcare system and focus on personalized medicine initiatives sustain demand for sophisticated NHL diagnostics. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees the approval and safety of diagnostic devices. London's academic medical centers are central to clinical trials and diagnostic innovation.
Non-Hodgkin Lymphoma Diagnostics Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing reagents and consumables. The market structure is tiered, with large multinational corporations offering integrated solutions alongside specialized firms focusing on specific molecular assays. Dominant competitive moves include strategic partnerships between diagnostic firms and pharmaceutical companies, alongside continuous portfolio diversification into advanced molecular testing.
Within the integrated solutions segment, Roche exemplifies a company leveraging its extensive portfolio across diagnostics and therapeutics. Novartis represents firms specializing in innovative cell and gene therapies that depend on precise companion diagnostics for patient stratification. Furthermore, Pfizer sustains its market position through strategic partnerships with diagnostic technology firms, broadening its testing capabilities across various disease areas.
| Leading Market Players |
|---|
| Novartis |
| Merck & Co. |
| Roche |
| Pfizer |
| Amgen |
| AbbVie |
| Gilead Sciences |
| Janssen Biotech |
| Bristol-Myers Squibb |
| Others |
Cost & Logistics Intelligence
The specialized cold chain logistics network, particularly for molecular reagents in Western Europe, drives up delivery costs, which in turn influences the pricing of advanced assays and impacts market access.
Pricing Analysis
Configured-to-order diagnostic panels for specific NHL subtypes command a premium over standard, off-the-shelf tests. Value-based pricing models are gaining traction, especially for companion diagnostics linked to targeted therapies. Certification levels, particularly US FDA approval, and brand premium from established diagnostic firms drive price differentiation. Pricing pressure stems from increasing competition among molecular testing providers and evolving reimbursement policies. Diagnostic laboratories are less price-sensitive for high-throughput NGS platforms, while smaller clinics exhibit higher price sensitivity for routine blood tests.
Supply Chain Analysis
Contract manufacturing organizations in China and India increasingly hold capacity for reagents and consumables used in NHL diagnostics. The supply chain draws from specialized enzymes, synthetic oligonucleotides, and advanced plastics as key inputs. Single-source vulnerability for rare antibodies represents a structural risk. Distribution runs through a hybrid model, combining direct sales for high-value platforms with third-party distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Non-Hodgkin Lymphoma diagnostics market represents a significant service-attach opportunity, with recurring revenue streams from bioinformatics support and data interpretation services expanding faster than initial hardware sales.
For Market Incumbents:Harden proprietary molecular assay portfolios against emerging open-source platforms to mitigate intellectual property erosion. Consolidate market share through strategic acquisitions of smaller, specialized diagnostic technology firms. Invest in US FDA and EMA certification for advanced companion diagnostics to maintain regulatory advantage. Expand channel control by direct engagement with large diagnostic laboratories, countering distributor reliance.
For New Entrants and Emerging Players:Underpenetration in Brazil and India offers significant white-space for establishing advanced molecular testing services. Target the liquid biopsy segment for monitoring minimal residual disease, a less saturated application area. A go-to-market angle involves partnering with local healthcare providers to establish specialized diagnostic hubs.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized molecular diagnostics firms with robust intellectual property in Next-Generation Sequencing. Long-term viability across the next decade hinges on platforms capable of integrating multi-omic data for predictive analytics. The signal to watch is the increasing rate of reimbursement approvals for novel AI-powered diagnostic algorithms.
| Strategic Initiative | Industry Significance |
|---|---|
| Development of AI-Powered Diagnostic Platforms | Integrating artificial intelligence with pathology data enhances diagnostic accuracy and automates subtype classification for laboratories. |
| Integration of NGS with Liquid Biopsy Technologies | Combining Next-Generation Sequencing with liquid biopsy offers non-invasive monitoring for treatment response and minimal residual disease. |
| Strategic Partnerships with Pharmaceutical Companies | Collaborations with drug developers accelerate co-development of companion diagnostics, essential for targeted therapies. |
| Pursuing Stringent Regulatory Approvals | Securing US FDA and EMA approvals for new assays ensures broad market access and clinical acceptance for advanced tests. |
| Geographic Expansion into Emerging Markets | Establishing diagnostic infrastructure in Brazil and India taps into growing patient populations and increasing healthcare spending. |
Research Approach
Operator-level perspectives from pathologists, clinical laboratory directors, and pharmaceutical R&D leads anchored the qualitative base for this analysis, triangulated with extensive secondary validation. Publicly available data from US FDA filings, EMA submissions, and national health agency reports provided key insights. A combination of bottom-up market sizing and top-down validation ensured robust data integrity.
Scenario-bracketing established plausible upper and lower bounds for market growth across the analysis window. The analytical framework segmented the market by product type, technology, end user, and regional regulatory cluster. Compound annual growth rates were derived from historical data trends and projected adoption rates. Key forecast inputs included Non-Hodgkin Lymphoma incidence rates and reimbursement policy evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized diagnostic technology firms would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and precision oncology investment. Quarterly review of new US FDA approvals and reimbursement policy changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
US Cancer Biopsy Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Screening Software Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Cancer Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Europe Kidney Cancer Therapeutics and Diagnostics Market