
 Europe Non-Small Cell Lung Cancer Diagnostics Market | 2026-2036
Europe Non-Small Cell Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Non-Small Cell Lung Cancer Diagnostics Market Foresight
Academic medical centers and large hospital networks is redrawing procurement patterns across Europe. F. Hoffmann-La Roche Ltd anchors its position through integrated workflow automation spanning tissue to molecular analysis. Thermo Fisher Scientific Inc. leverages its pan-European distribution infrastructure to sustain reagent supply security for high-throughput laboratories. Qiagen differentiates through sample preparation technologies that occupy critical steps in NGS and PCR pipelines.
Europe Non-Small Cell Lung Cancer Diagnostics encompasses tissue-based, imaging, and molecular methods for identifying adenocarcinoma, squamous cell carcinoma, and large cell carcinoma subtypes, employing immunohistochemistry staining protocols, polymerase chain reaction amplification, next-generation sequencing panels, and radiological assessment to guide targeted therapy selection. Liquid biopsy biomarker analysis is displacing repeat tissue biopsies in progression monitoring, concentrating margin pools in specialized reference laboratories. Point-of-care testing delivery mode remains nascent in Europe due to reimbursement complexity, while in-lab testing dominates revenue generation through centralized pathology networks.
EMA's In Vitro Diagnostic Regulation and EU Medical Device Regulation are forcing manufacturers to rebuild technical documentation and clinical evidence portfolios for market access continuity. CE marking requirements under the new framework extend conformity assessment timelines, reshaping competitive entry dynamics for novel biomarker assays. Stakeholders must monitor notified body capacity constraints and national reimbursement deliberations as the primary determinants of commercial velocity across European markets.
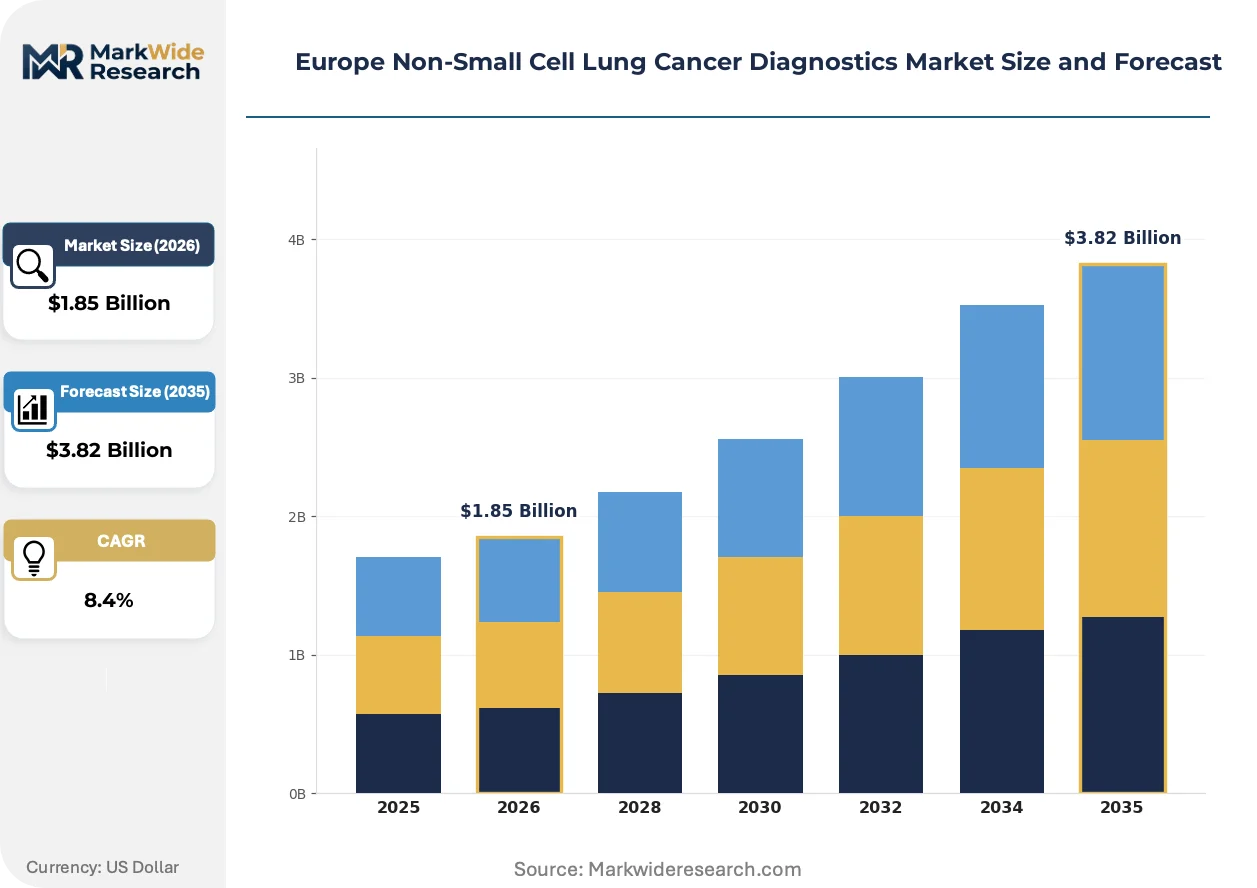
Market Dynamics
EMA's In Vitro Diagnostic Regulation is forcing manufacturers to rebuild clinical evidence portfolios and technical documentation, compressing commercial timelines while hospital networks consolidate testing volumes into fewer reference laboratories.
Growth Catalysts
- Liquid biopsy biomarker analysis:Specialized reference laboratories are capturing margin pools as this method displaces repeat tissue biopsies for progression monitoring in advanced NSCLC cases.
- CE marking under MDR framework:Accelerated compliance investments are filtering out marginal competitors and strengthening positions of firms with robust notified body relationships.
- Germany's reference laboratory networks:Consolidation of testing volumes is creating economies of scale that favor high-throughput molecular profiling platforms.
Market Restraints
- Notified body capacity constraints:Limited certification infrastructure under the new MDR framework is extending conformity assessment timelines to 18-24 months for novel assays.
- Reagent supply concentration:Pan-European distribution dependencies create vulnerability when single-source suppliers face manufacturing disruptions.
- Tissue acquisition limitations:Inadequate sample quality from core needle biopsies restricts comprehensive genomic profiling in 15-20% of cases.
Strategic Opportunities
- Eastern European expansion:Poland and Romania present underpenetrated markets where centralized pathology infrastructure is now receiving EU cohesion fund investments.
- AI-assisted image analysis:Convergence of digital pathology platforms with machine learning algorithms is opening automated PD-L1 scoring workflows.
- Companion diagnostic mandates:EMA's increasing requirement for validated tests alongside targeted therapy approvals is creating captive demand for approved assay platforms.
Industry Challenges
- Molecular pathologist shortage:Interpretation of complex NGS reports requires specialized expertise that academic training programs are not producing at sufficient rates.
- Legacy LIMS integration:Hospital pathology departments face friction connecting new molecular platforms to established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Non-Small Cell Lung Cancer Diagnostics Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging, Biomarkers, Liquid Biopsy End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Technology: Immunohistochemistry, PCR, NGS, Radiology Delivery Mode: In-Lab Testing, Home Testing, Point-of-Care Testing, Telehealth Services |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Abbott, Quest Diagnostics Incorporated, Bio-Rad Laboratories, Inc., Qiagen, Agilent Technologies, Illumina Inc, Biodesix, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Non-Small Cell Lung Cancer Diagnostics Market Shifts & Advancements
Diagnostic workflows are fragmenting across tissue-based, liquid, and computational methods, with each pathway demanding distinct capital deployment and personnel competencies from service providers.
Next-generation sequencing panels for comprehensive genomic profiling are bifurcating the market between high-complexity academic centers and streamlined community hospital laboratories. Academic medical centers in France and the Netherlands are adopting full exome approaches with 500+ gene coverage, while regional networks in Spain and Italy select targeted 50-gene panels to manage turnaround times and reimbursement constraints. This divergence is creating parallel supply chains with different pricing structures and service level agreements.
EMA's Medical Device Regulation is extending clinical evidence requirements for companion diagnostic assays, forcing manufacturers to generate prospective patient data rather than relying on analytical validation alone. IVD-MDR combination product submissions now require coordinated review timelines that synchronize with pharmaceutical marketing authorization applications. German and French notified bodies are developing specialized competencies for oncology diagnostics, creating geographic concentration in certification capacity.
Hospital procurement committees are consolidating vendor relationships to reduce contract management overhead, favoring integrated platform providers over point solution specialists. Large hospital networks in the UK and Scandinavia are negotiating enterprise-wide agreements spanning immunohistochemistry, fluorescence in situ hybridization, and sequencing workflows. This concentration is most visible in Germany's university hospital consortia, where standardization across 8-12 member institutions creates substantial volume commitments.
Europe Non-Small Cell Lung Cancer Diagnostics Market Segmentation
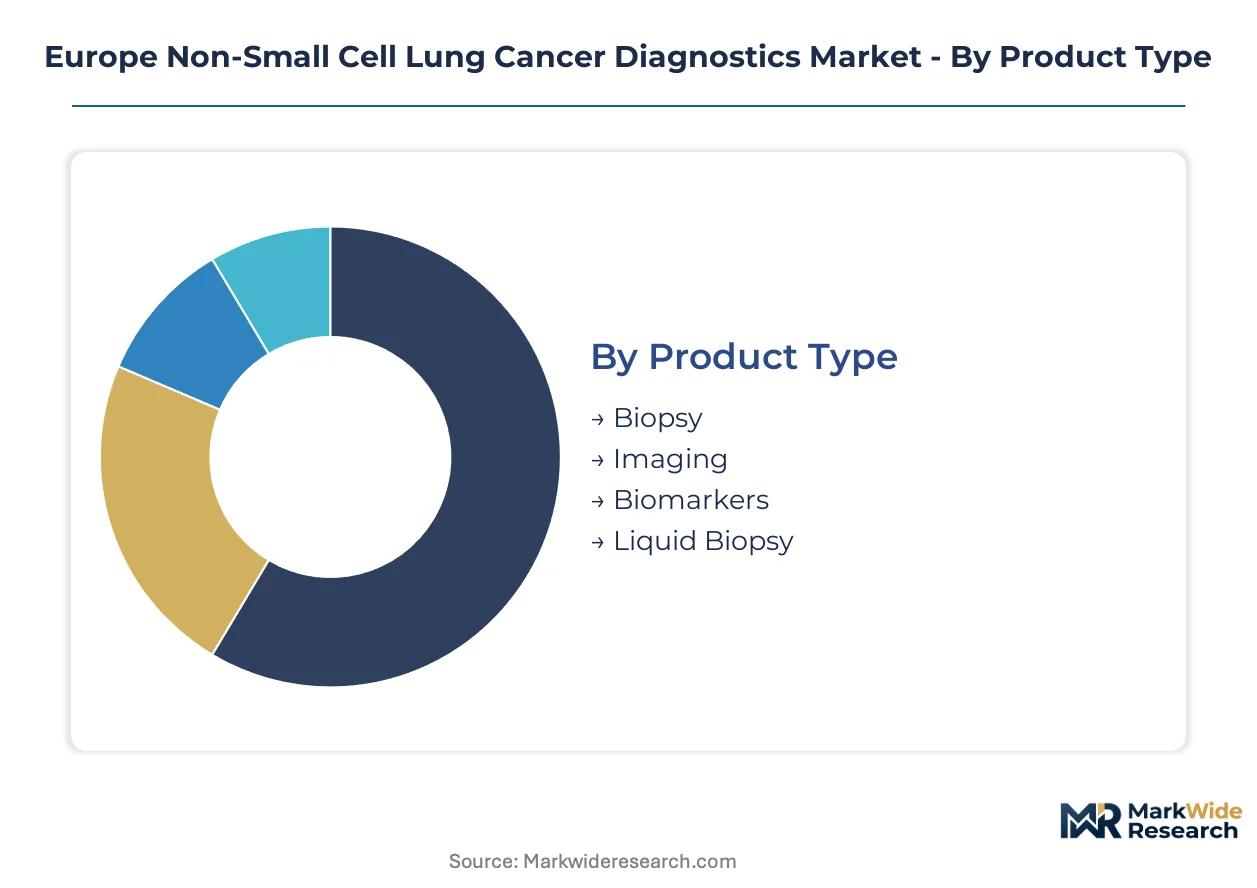
Segmentation in European NSCLC diagnostics reflects divergent reimbursement pathways and regulatory complexity. Each category maps to distinct procurement patterns across hospital networks and reference laboratories.
Product Type:
EMA's In Vitro Diagnostic Regulation applies differential conformity assessment burdens across invasive and non-invasive modalities, reshaping manufacturer investment priorities.
- Biopsy:Tissue acquisition through core needle or surgical excision remains the diagnostic gold standard for initial histological classification. Demand concentrates in Germany's university hospital consortia, where standardized protocols across member institutions create substantial volume commitments for integrated pathology platforms.
- Liquid Biopsy:Circulating tumor DNA analysis enables serial monitoring without repeat invasive procedures. Specialized reference laboratories in France and the Netherlands are capturing margin pools as EMA companion diagnostic mandates create captive demand for validated ctDNA platforms.
- Imaging:CT-guided localization and PET-CT staging protocols support treatment planning across European cancer centers.
- Biomarkers:Protein expression and genetic alteration detection guides targeted therapy selection through centralized laboratory networks.
Established volume favors Biopsy; emerging adoption favors Liquid Biopsy.
End User:
Procurement authority is consolidating toward entities with molecular pathology expertise and capital infrastructure for high-throughput sequencing.
- Hospitals:Academic medical centers and large hospital networks are redrawing vendor relationships through enterprise-wide agreements spanning IHC, FISH, and NGS workflows. UK and Scandinavian health systems favor integrated platform providers over point solution specialists.
- Laboratories:Reference laboratory networks in Germany are consolidating testing volumes from peripheral hospitals, creating economies of scale that favor automated molecular profiling platforms.
- Diagnostic Centers:Independent facilities face margin pressure from reimbursement complexity under national health service frameworks.
- Research Institutions:Academic centers in France and the Netherlands adopt full exome approaches with 500+ gene coverage for translational studies.
Procurement concentration favors Hospitals; specialized capability favors Laboratories.
Technology:
Capital deployment requirements and personnel competencies fragment the competitive landscape across workflow automation levels.
- NGS:Next-generation sequencing panels for comprehensive genomic profiling bifurcate between high-complexity academic centers and streamlined community laboratories. Regional networks in Spain and Italy select targeted 50-gene panels to manage turnaround times and reimbursement constraints.
- Immunohistochemistry:Automated staining platforms for PD-L1 and ALK detection anchor routine diagnostic workflows in high-volume pathology departments.
- PCR:Polymerase chain reaction amplification supports rapid turnaround for single-gene alterations in time-sensitive treatment decisions.
- Radiology:CT and PET-CT imaging protocols provide anatomical staging complementary to molecular characterization.
Workflow integration favors Immunohistochemistry; capability expansion favors NGS.
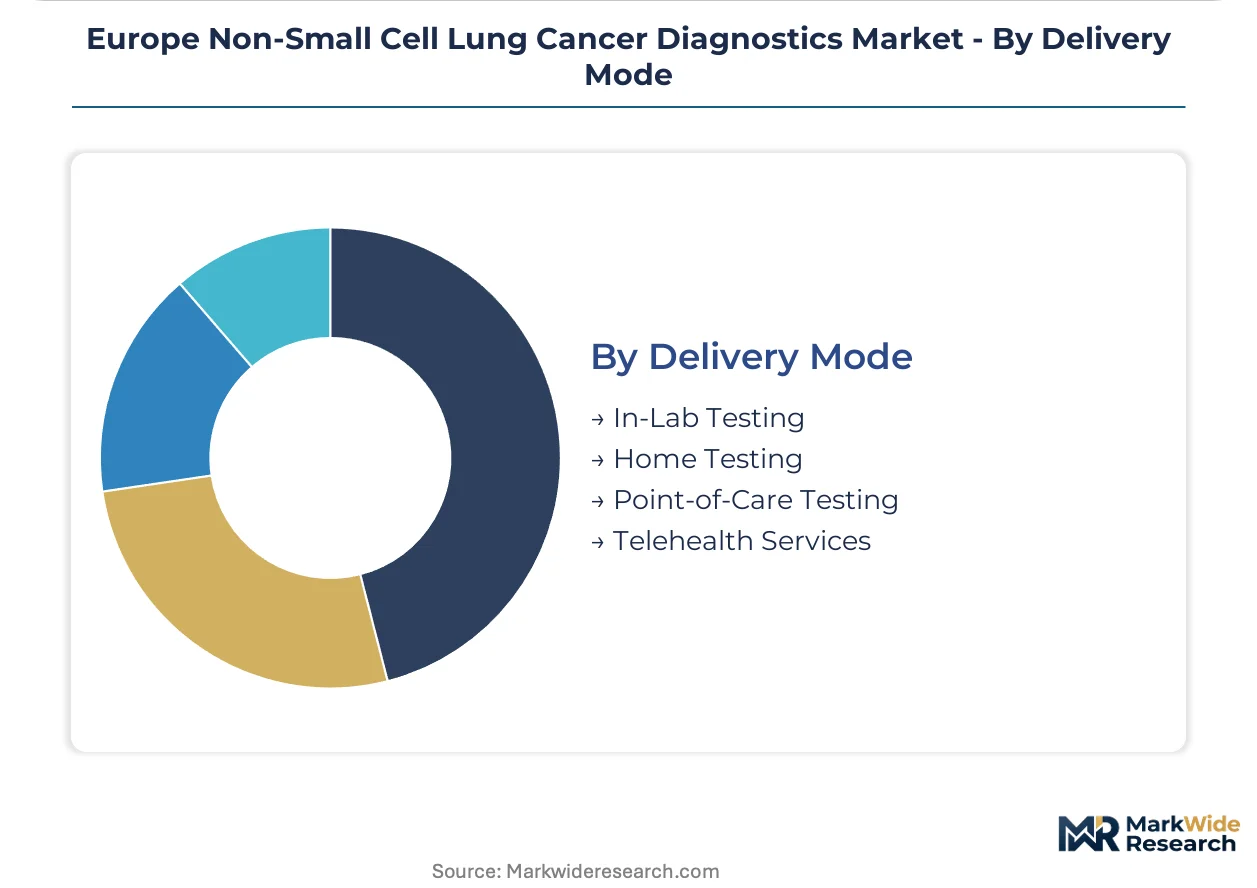
Delivery Mode:
Reimbursement frameworks and sample chain-of-custody requirements determine viable service configurations across European markets.
- In-Lab Testing:Centralized pathology networks dominate revenue generation through standardized quality control and EMA compliance documentation. Hospital-based departments deepen adoption of molecular profiling platforms with integrated workflow automation.
- Point-of-Care Testing:Near-patient molecular analysis remains nascent due to complex national reimbursement deliberations and technical validation requirements.
- Home Testing:Self-collection kits for liquid biopsy specimens face regulatory uncertainty under IVDR sample stability requirements.
- Telehealth Services:Remote consultation for molecular report interpretation addresses pathologist shortage constraints in peripheral regions.
Revenue concentration favors In-Lab Testing; access expansion favors Telehealth Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main corridor's logistics infrastructure underwrites Germany's central role in European diagnostic distribution, while the Channel Tunnel and North Sea shipping lanes connect UK and Benelux laboratory networks to continental supply chains.
Germany
University hospital consortia in Bavaria and North Rhine-Westphalia drive demand for automated molecular profiling platforms. EMA's IVDR implementation accelerates compliance investments by domestic manufacturers. Frankfurt's reference laboratory hub consolidates testing volumes from peripheral hospitals across Hesse and Baden-Württemberg.
United Kingdom
NHS England's genomic medicine service creates structured procurement for comprehensive cancer panels. The UK Medicines and Healthcare products Regulatory Agency enforces MDR transition timelines for IVD manufacturers. London's academic medical centers anchor molecular pathology networks extending into Manchester and Birmingham.
France
Assistance Publique-Hôpitaux de Paris operates Europe's largest hospital network for oncology diagnostics. ANSM coordinates with EMA on companion diagnostic validation requirements. The Lyon-Grenoble corridor hosts specialized reference laboratories serving the Auvergne-Rhône-Alpes biotech cluster.
Netherlands
Health-RI infrastructure connects seven university medical centers for federated genomic data analysis. The Dutch CBG enforces IVDR notified body standards for market access. Rotterdam's Erasmus MC anchors a diagnostic network spanning Randstad metropolitan laboratories.
Spain
Regional health service fragmentation in Catalonia and Andalusia creates procurement complexity for standardized testing protocols. The Spanish Agency for Medicines and Health Products manages MDR certification timelines. Barcelona's Hospital Clínic network drives adoption of targeted gene panels for community hospital outreach.
Europe Non-Small Cell Lung Cancer Diagnostics Market Competitive Landscape
Listed leaders compete with private specialists across platform integration depth, with publicly traded instrument manufacturers facing privately held reagent specialists for hospital procurement contracts. The market structure concentrates around integrated workflow providers capable of spanning tissue preparation through molecular reporting. Three archetypes dominate: pan-European distribution platforms, sample preparation technology specialists, and sequencing instrument manufacturers. Competitive moves center on enterprise-wide contract consolidation and notified body relationship building for IVDR compliance acceleration.
Among Swiss-diagnostics conglomerates, F. Hoffmann-La Roche Ltd exemplifies the integrated platform archetype spanning automated staining to sequencing workflows. Thermo Fisher Scientific Inc. occupies a position as the scale-driven distribution anchor for high-throughput laboratory supply security. Qiagen represents the sample preparation specialization tier with technologies embedded in NGS and PCR pipelines upstream of analytical instruments.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| Abbott |
| Quest Diagnostics Incorporated |
| Bio-Rad Laboratories, Inc. |
| Qiagen |
| Agilent Technologies |
| Illumina Inc |
| Biodesix |
| Others |
Supply & Pricing Matrix
EMA's In Vitro Diagnostic Regulation gates both supply qualification and price differentiation simultaneously, as CE marking under the MDR framework forces manufacturers to rebuild clinical evidence portfolios while hospital networks consolidate procurement toward compliant integrated platform providers.
Pricing Analysis
Volume-discount tiering structures dominate enterprise-wide agreements spanning immunohistochemistry, fluorescence in situ hybridization, and sequencing workflows. Three-tier pricing structure across premium, standard, and economy levels separates fully automated molecular profiling platforms from modular benchtop systems and manual assay kits. Cost compression in the economy tier is intensifying because peripheral hospitals face reimbursement constraints under national health service frameworks. Community hospital laboratories exhibit highest price sensitivity, while academic medical centers prioritize workflow integration over unit economics.
Supply Chain Analysis
Rotterdam port congestion and Rhine river water level volatility periodically disrupt reagent shipments to Central European laboratories. Germany, the Netherlands, and Switzerland anchor manufacturing concentration for sequencing instruments, sample preparation technologies, and diagnostic reagents. Supply chains draw from fluorophore chemistries sourced from specialized German chemical producers, oligonucleotide synthesis from Dutch biotech suppliers, and rare earth elements for imaging components. Single-source vulnerability concentrates in pan-European distribution dependencies when notified body capacity constraints delay alternative supplier qualification. Distribution runs through reference laboratory hubs that consolidate testing volumes from peripheral networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital networks and reference laboratory consortia, as Germany's university hospital consortia standardize procurement across member institutions and France's AP-HP centralizes oncology diagnostic purchasing.
For Market Incumbents: Secure notified body relationships with German and French certification bodies to accelerate IVDR compliance timelines ahead of marginal competitors. Deepen backward integration into sample preparation technologies to capture margin pools currently held by reagent specialists. Threat from emerging AI-assisted image analysis platforms demands preemptive workflow automation investments. For New Entrants and Emerging Players: CE marking fast-tracks through coordinated IVD-MDR combination product submissions alongside pharmaceutical marketing authorization applications open market access pathways. White-space targets concentrate in Poland and Romania, where EU cohesion fund investments are building centralized pathology infrastructure. Community hospital networks in Spain's regional health services present penetrable entry points through targeted 50-gene panel offerings with streamlined turnaround times. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to monetize non-core diagnostic divisions with established notified body relationships. Long-term viability hinges on positioning within consolidated vendor rosters of large hospital networks. Signal to watch: German reference laboratory network expansion velocity as indicator of platform standardization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Relationship Building | EMA's IVDR extends conformity assessment timelines to 18-24 months for novel assays without established certification partnerships. |
| Workflow Automation Investment | Hospital procurement committees favor integrated platform providers spanning tissue preparation through molecular reporting over point solutions. |
| Liquid Biopsy Platform Development | Specialized reference laboratories capture margin pools as ctDNA analysis displaces repeat tissue biopsies for progression monitoring. |
| Eastern European Geographic Expansion | Poland and Romania present underpenetrated markets receiving EU cohesion fund investments in centralized pathology infrastructure. |
| AI-Assisted Image Analysis Integration | Convergence of digital pathology with machine learning algorithms opens automated PD-L1 scoring workflows for high-volume laboratories. |
Research Methodology
The analysis maps tissue-based diagnostics, liquid biopsy platforms, imaging modalities, and biomarker assays, each validated through molecular pathologists, hospital procurement managers, reference laboratory directors, and regulatory affairs specialists. Primary interviews with industry stakeholders combined secondary validation through EMA submission databases, notified body certification records, hospital procurement databases, and GPO contracts. Bottom-up and top-down triangulation cross-checked segment-level estimates against consolidated revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology platform, and delivery mode, with regional regulatory clusters as an additional industry-specific dimension. CAGRs derived from fitted growth curves incorporating adoption rate trajectories for NGS panels and liquid biopsy platforms. Forecast inputs incorporated EMA IVDR implementation timelines and national reimbursement deliberation patterns.
Underlying assumptions cover notified body capacity expansion, sample acquisition quality rates, and companion diagnostic mandate enforcement, with deviation risk concentrated in regulatory timeline delays and molecular pathologist training pipeline constraints. Practitioners should keep alternative scenarios live as EMA IVDR transition deadlines and EU cohesion fund deployment schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
Europe Liver Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
US Colorectal Cancer Screening Market
Oncology Diagnostics
Asia-Pacific Liver Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Market
Oncology Diagnostics
Oncology Based Molecular Diagnostics Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Ovarian Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market