
 Remicade Biosimilar Market | 2026-2036
Remicade Biosimilar Market Size, Share, and Industry Trends Forecast 2026-2036
Remicade Biosimilar Market Outlook
Manufacturing platform convergence between mammalian cell culture and single-use bioreactor systems is narrowing cost differentials between originator and biosimilar production. Celltrion leverages large-scale stainless steel facilities in Incheon to sustain cost leadership across European tenders. Samsung Bioepis anchors its position through Samsung Group captive biologics capacity. Pfizer competes via integrated distribution networks that control hospital and specialty pharmacy channels.
A Remicade biosimilar is a recombinant monoclonal antibody targeting tumor necrosis factor-alpha, produced in mammalian CHO cell lines with glycosylation patterns matching the reference infliximab product, indicated for autoimmune conditions including rheumatoid arthritis, Crohn's disease, and psoriatic arthritis. The infliximab product type dominates hospital procurement due to established immunogenicity profiles and interchangeability designations in multiple jurisdictions, while subcutaneous delivery modes represent the fastest-expanding segment as patient administration shifts from infusion centers to home settings. Lyophilized powder formulations retain margin pools in emerging markets where cold chain infrastructure remains limited.
FDA interchangeability standards and EMA biosimilar comparability protocols shape product development timelines and market access conditions for manufacturers seeking multi-jurisdictional approval. The WHO prequalification pathway accelerates uptake in lower-income health systems where national regulators reference established agency determinations. Stakeholders must monitor evolving CMS reimbursement parity rules and state-level pharmacy substitution laws that determine whether interchangeability translates into automatic substitution at the dispensing level.
Market Dynamics
FDA interchangeability designations and EMA biosimilar comparability protocols are compressing prescriber hesitation windows, accelerating automatic substitution at pharmacy level across multiple jurisdictions.
Growth Catalysts
- Interchangeability Pathways:FDA's interchangeable biosimilar standards reduce prescriber switching friction, enabling automatic pharmacy-level substitution without physician consultation in US rheumatology clinics.
- Infusion-to-Subcutaneous Migration:Patient administration preferences are shifting from hospital infusion centers toward home-based subcutaneous delivery modes, expanding addressable patient populations.
- Hospital Procurement Consolidation:Tender processes across German hospital networks favor established immunogenicity profiles, concentrating volume toward approved infliximab biosimilars with multi-year safety data.
Market Restraints
- Mammalian Cell Culture Cost Concentration:CHO cell line production requires stainless steel bioreactor infrastructure with high fixed costs, creating capital barriers for new entrants.
- Cold Chain Infrastructure Gaps:Lyophilized powder formulations retain margin pools in emerging markets where temperature-controlled distribution remains underdeveloped.
- Reference Product Defense:Originator manufacturers leverage rebate contracting with pharmacy benefit managers to maintain formulary exclusivity in US commercial insurance segments.
Strategic Opportunities
- Home Administration Expansion:Subcutaneous biosimilar development targets patient populations seeking to avoid infusion center visits, creating new reimbursement coding opportunities.
- WHO Prequalification Acceleration:Lower-income health systems reference WHO determinations for national regulatory approval, streamlining market entry in African and Southeast Asian markets.
- Integrated Distribution Control:Captive specialty pharmacy and hospital channel networks enable margin capture currently lost to wholesale intermediaries.
Industry Challenges
- Glycosylation Matching Complexity:CHO cell line glycosylation pattern consistency requires analytical method validation timelines that extend development programs.
- State-Level Substitution Law Fragmentation:US pharmacy automatic substitution authority varies by state, forcing multi-jurisdictional compliance strategies for national product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remicade Biosimilar Market |
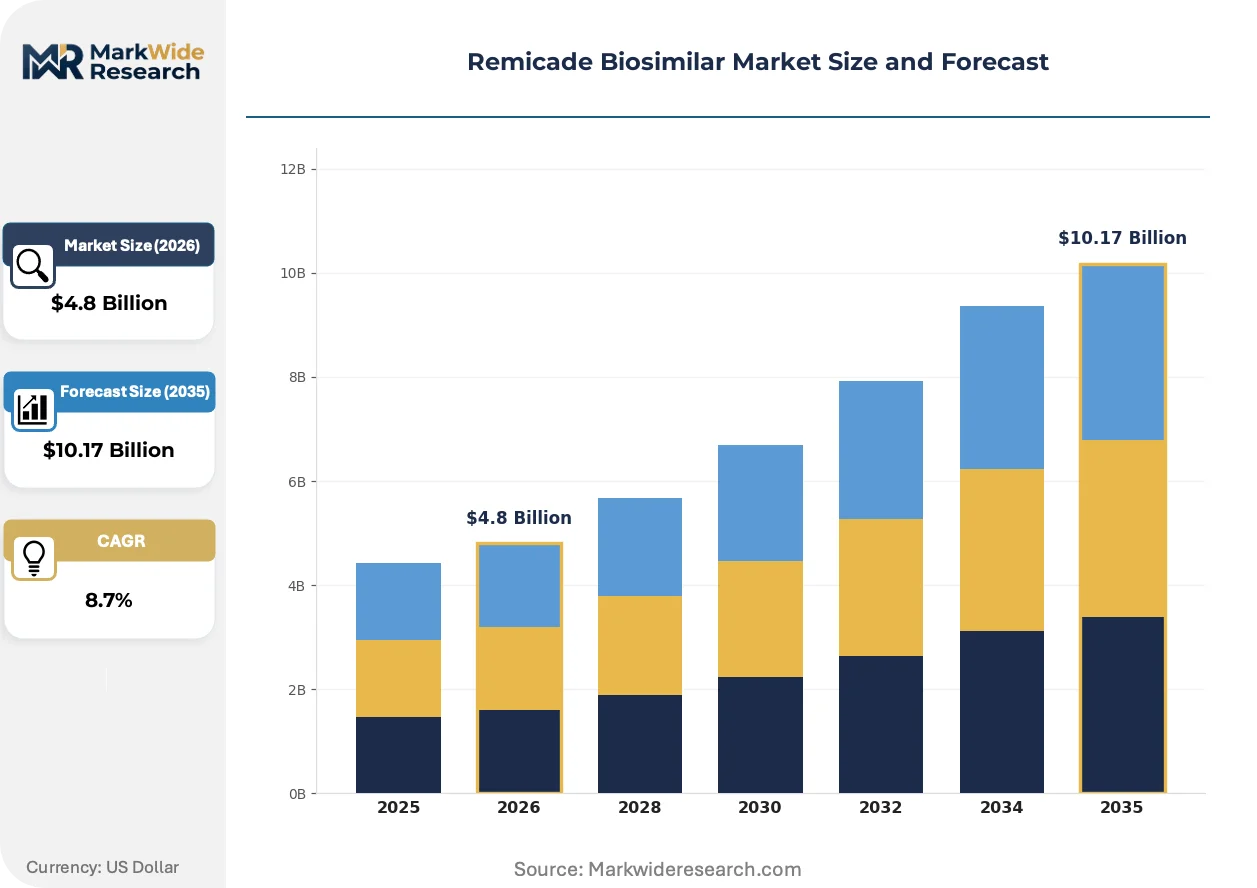
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adalimumab, Infliximab, Rituximab, Trastuzumab Delivery Mode: Injectable, Infusion, Subcutaneous, Intravenous End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Formulation: Lyophilized Powder, Solution for Injection, Pre-filled Syringe, Vial |
| Companies Covered | Merck & Co., Sandoz, Celltrion, Amgen, Biocon, Pfizer, Janssen Biotech, Dr. Reddy’s Laboratories, Samsung Bioepis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remicade Biosimilar Market Strategic Shifts
Digital health infrastructure and patient-administered delivery formats are compressing the traditional infusion center model, redistributing care settings and reimbursement flows across autoimmune therapy markets.
Continuous manufacturing platforms for monoclonal antibody production are virtualizing batch-based stainless steel operations. Contract development organizations in South Korea and Singapore are adopting single-use bioreactor trains to reduce cross-contamination risk and facility changeover downtime. This technology is virtualizing the capital intensity requirements that previously anchored production in dedicated multi-product facilities.
EMA's revised biosimilar comparability guidelines now accept analytical similarity data as primary evidence, reducing mandatory clinical trial patient numbers for well-characterized molecules. The industrial consequence accelerates development timelines for second-generation infliximab biosimilars seeking European market entry. Rheumatology indications with established immunogenicity profiles are responding fastest, with sponsors prioritizing Crohn's disease and psoriatic arthritis extensions.
Patient-administered subcutaneous formats are displacing intravenous infusion as the preferred first-line option in newly diagnosed autoimmune populations. Rheumatology practices in the United States are unbundling infusion services from drug reimbursement, shifting revenue toward injection training and remote monitoring. This pattern is most visible in Medicare Advantage plans where capitated payments incentivize site-of-care migration.
Remicade Biosimilar Market Segmentation
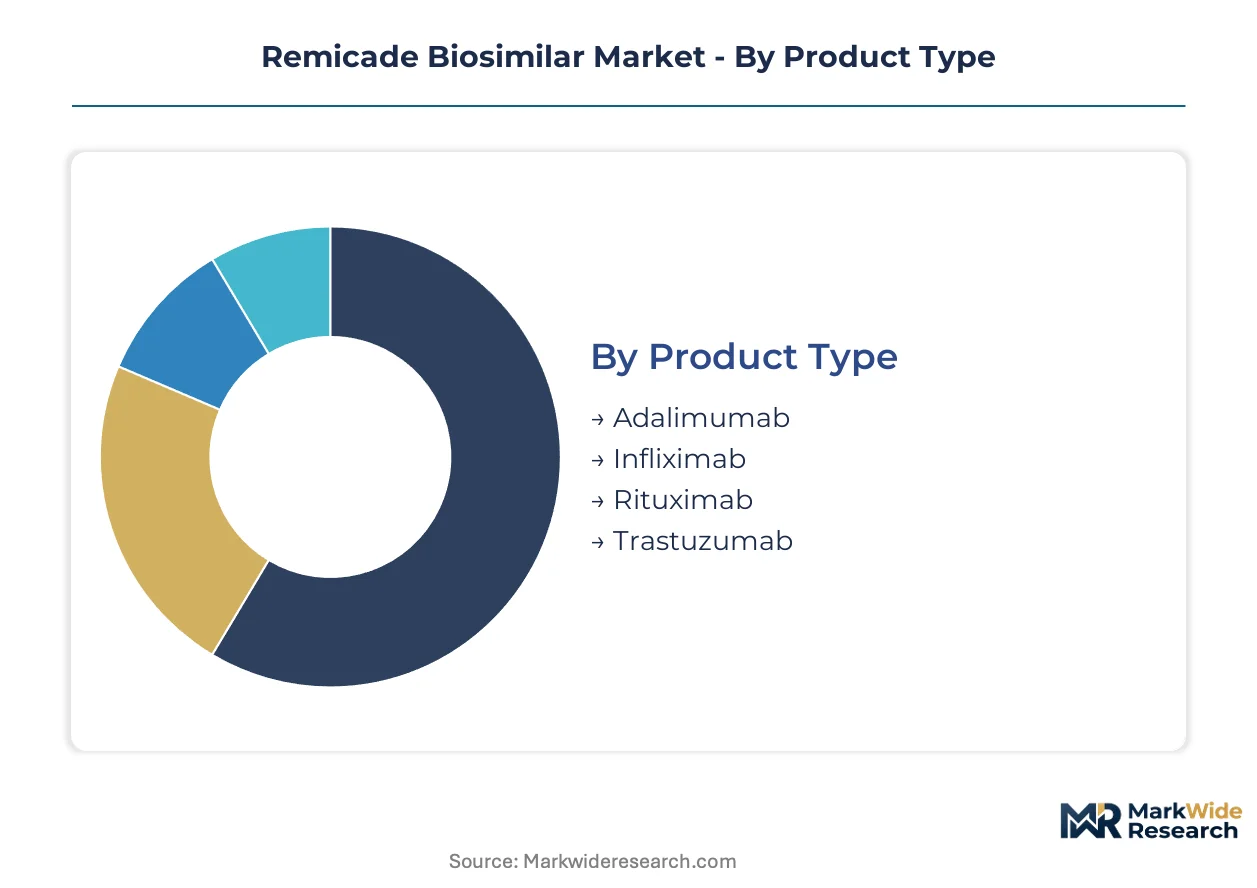
Remicade biosimilar manufacturers target distinct patient populations through differentiated product configurations. Delivery mode and formulation choices directly determine reimbursement coding, cold chain requirements, and site-of-care economics across rheumatology and gastroenterology practices.
Product Type:
The use-case spectrum spans TNF-alpha inhibitors and oncology monoclonals with overlapping manufacturing infrastructure but divergent prescriber networks.
- Infliximab:Recombinant chimeric monoclonal antibody matching reference Remicade glycosylation patterns. Hospital procurement in Germany concentrates volume here due to established immunogenicity profiles and EMA biosimilar comparability recognition.
- Adalimumab:Fully human TNF-alpha inhibitor with distinct intellectual property expiry timelines. Rheumatology clinics in the United States are expanding formulary access as FDA interchangeability pathways reduce prescriber switching friction.
- Rituximab:CD20-targeted monoclonal for oncology and autoimmune applications.
- Trastuzumab:HER2-directed biosimilar with separate prescriber networks and infusion center requirements.
Established volume favors infliximab; emerging adoption favors adalimumab as patent cliffs accelerate.
Delivery Mode:
Cost tier differentiation separates capital-intensive infusion infrastructure from patient-administered alternatives with lower fixed overhead.
- Subcutaneous:Patient-administered delivery bypassing infusion center overhead. Medicare Advantage plans in the United States are unbundling drug reimbursement from site-of-service fees, redirecting volume toward home administration with capitated payment incentives.
- Intravenous:Hospital and infusion center administration with established reimbursement codes. German hospital networks favor this mode for infliximab biosimilars through centralized tender processes requiring documented immunogenicity profiles.
- Injectable:General parenteral administration category spanning multiple clinical settings.
- Infusion:Extended-duration intravenous delivery requiring specialized nursing supervision.
Patient preference is shifting fastest toward subcutaneous; institutional procurement maintains intravenous dominance in acute settings.
End User:
Customer type determines margin capture through channel control versus wholesale intermediation.
- Hospitals:Centralized procurement through group purchasing organizations and national tenders. German hospital networks concentrate infliximab biosimilar volume through multi-year contracts favoring established safety data.
- Specialty Pharmacies:Dispensing sites with integrated patient support services. United States rheumatology clinics route automatic substitution through these channels where FDA interchangeability designations enable pharmacy-level switching.
- Clinics:Outpatient settings with mixed infusion and injection capabilities.
- Homecare:Direct-to-patient delivery with nursing support for subcutaneous administration.
Channel margin pools concentrate in specialty pharmacies; volume concentration remains with hospital procurement.
Formulation:
Supply concentration in mammalian cell culture infrastructure constrains formulation flexibility across all product types.
- Lyophilized Powder:Freeze-dried formulation reducing cold chain dependency. Emerging markets in Southeast Asia retain this configuration where temperature-controlled distribution infrastructure remains underdeveloped.
- Pre-filled Syringe:Ready-to-use delivery system for subcutaneous administration. Patient training requirements in United States rheumatology practices are standardizing around this format for home-based care migration.
- Solution for Injection:Liquid formulation requiring refrigerated storage and handling.
- Vial:Multi-dose container for institutional settings with pharmacy compounding requirements.
Pre-filled syringes are climbing the fastest in developed markets; lyophilized powder retains share where cold chain gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in Remicade biosimilars tilt toward net-importing developed markets with centralized procurement systems, while manufacturing export capacity concentrates in South Korea and India where contract development organizations leverage cost-optimized mammalian cell culture infrastructure.
United States
Rheumatology clinics in Texas and Florida are accelerating automatic substitution as FDA interchangeability designations reduce prescriber consultation requirements. Medicare Advantage plans unbundle infusion services from drug reimbursement, redirecting volume toward home-based subcutaneous administration. The Southeast hospital procurement corridor concentrates formulary negotiations through regional group purchasing organizations.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia award multi-year tenders favoring established infliximab biosimilar safety profiles. EMA biosimilar comparability protocols compress regulatory review timelines for second-generation entrants. The Munich-Stuttgart pharmaceutical cluster anchors European distribution for Korean-manufactured reference products.
South Korea
Incheon-based stainless steel bioreactor facilities supply European and Asian hospital tenders through cost leadership in large-scale CHO cell production. MFDS accelerated approval pathways for well-characterized molecules reduce development-to-market timelines. The Songdo biocluster houses captive biologics capacity serving Samsung Group affiliates.
India
Hyderabad and Bangalore development organizations pursue WHO prequalification for African and Southeast Asian market entry. CDSCO streamlined biosimilar guidelines reference EMA and FDA determinations to reduce redundant clinical trials. Western Maharashtra specialty pharmacy networks are piloting direct-to-patient distribution models.
United Kingdom
NHS England national procurement frameworks consolidate infliximab biosimilar volume through centralized tender processes. MHRA post-Brexit recognition agreements with FDA and EMA sustain parallel approval pathways. The Cambridge-Oxford-London life sciences corridor hosts analytical method validation services for glycosylation matching studies.
Remicade Biosimilar Market Competitive Environment
On the supply side, the industry is consolidating around three strategic archetypes: Korean conglomerate-affiliated biologics manufacturers with captive capacity, Indian contract development specialists leveraging cost-optimized platforms, and integrated pharmaceutical majors controlling distribution channels. Competitive positioning hardens through M&A activity targeting analytical capabilities and strategic partnerships securing hospital formulary access.
Among Korean manufacturers, Celltrion and Samsung Bioepis exemplify the conglomerate-affiliated archetype with stainless steel bioreactor infrastructure. Pfizer occupies a position within the integrated pharmaceutical tier, leveraging specialty pharmacy channel control. These three anchors represent distinct supply-side strategies: manufacturing scale leadership, captive biologics capacity, and distribution network dominance.
| Leading Market Players |
|---|
| Merck & Co. |
| Sandoz |
| Celltrion |
| Amgen |
| Biocon |
| Pfizer |
| Janssen Biotech |
| Dr. Reddy's Laboratories |
| Samsung Bioepis |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure between South Korean manufacturing hubs and European hospital procurement networks compresses margin pools for infliximab biosimilars while simultaneously reinforcing three-tier pricing stratification across premium interchangeability-certified, standard EMA-recognized, and economy lyophilized powder tiers. This structural tension forces manufacturers to anchor supply chain investments in tariff-advantaged jurisdictions or absorb cost differentials through captive biologics capacity.
Pricing Analysis
The pricing gap between first-generation intravenous infliximab biosimilars and next-generation subcutaneous formats spans roughly 15-25% at the hospital procurement level, with premium-mid-economy pricing differentiation driven by FDA interchangeability certification and volume scale commitments in German tender processes. Cost compression in standard-tier products is intensifying because Samsung Bioepis and Celltrion are expanding stainless steel bioreactor capacity, while Medicare Advantage plans exhibit the highest price sensitivity due to capitated reimbursement structures. Originator manufacturers maintain formulary exclusivity in US commercial segments through rebate contracting, insulating them from direct price competition.
Supply Chain Analysis
Tariff exposure between South Korea and the European Union dominates supply chain risk calculations for infliximab biosimilar manufacturers, with production gravity centering on Incheon stainless steel facilities and Songdo biocluster captive capacity. CHO cell line production draws from Chinese-sourced media components and German-engineered bioreactor systems, creating single-source vulnerability in analytical equipment calibration. Distribution runs through regional hospital procurement consortia in Germany and specialty pharmacy networks in the United States, with cold chain infrastructure gaps in Southeast Asian markets forcing lyophilized powder retention.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Remicade biosimilar market rewards analytical method validation capabilities and glycosylation matching expertise that remain concentrated among Korean conglomerate-affiliated manufacturers and select Indian contract development specialists. Firms lacking stainless steel bioreactor infrastructure or EMA comparability protocol experience face prohibitive entry barriers.
For Market Incumbents: Pre-empt automatic substitution erosion by securing FDA interchangeability designations ahead of adalimumab patent cliff competition, while anchoring European tender participation through multi-year German hospital network contracts that reference established immunogenicity profiles. Backward integration into CHO cell line development reduces dependency on external media suppliers and compresses cost differentials against originator rebate strategies. For New Entrants and Emerging Players: Build out subcutaneous formulation capabilities targeting Medicare Advantage home administration migration, where reimbursement coding unbundling creates penetrable white space absent from infusion-center-dominated hospital procurement. WHO prequalification acceleration for African and Southeast Asian markets offers the most accessible entry vector, with lyophilized powder configurations bypassing cold chain infrastructure gaps that constrain multinational incumbents. For Investors and Strategic Acquirers: The market sits at a manufacturing scale consolidation phase that favors analytical services specialists and regional distribution platform owners over pure-play biosimilar developers. Long-term viability over the next decade hinges on subcutaneous delivery transition capture and integrated specialty pharmacy channel control. Watch FDA interchangeability designation velocity as the primary inflection signal—accelerated approvals compress prescriber hesitation windows and trigger hospital formulary renegotiation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Pathway Advancement | Automatic pharmacy substitution in US rheumatology clinics accelerates volume capture without prescriber consultation requirements. |
| Subcutaneous Formulation Development | Home administration migration unbundles infusion service revenue from drug reimbursement in Medicare Advantage plans. |
| EMA Biosimilar Comparability Investment | Analytical similarity data acceptance reduces mandatory clinical trial patient numbers for European market entry. |
| Captive Biologics Capacity Expansion | Samsung Group and Celltrion stainless steel facilities sustain cost leadership across German hospital tender processes. |
| WHO Prequalification Acceleration | Lower-income health systems in Africa and Southeast Asia reference WHO determinations for streamlined national regulatory approval. |
Study Parameters
Desk research of FDA interchangeability designation databases, EMA biosimilar comparability assessment reports, and German hospital procurement tender records preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary fieldwork captured manufacturing platform economics and site-of-care migration patterns, validated against secondary sources including ClinicalTrials.gov entries, CMS Medicare reimbursement coding updates, and SEC 10-K biologics segment disclosures. Bottom-up patient population modeling and top-down pharmaceutical expenditure tracking were cross-referenced for triangulation.
Assumptions regarding FDA interchangeability designation timelines, EMA comparability protocol evolution, and CMS reimbursement parity rules were held fixed across baseline scenarios, while subcutaneous adoption velocity and hospital procurement consolidation intensity were varied in sensitivity testing. The analytical framework segmented volume and value across delivery mode, formulation type, end-user channel, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from patient population epidemiology, patent expiry sequencing, and tender participation win rates, with glycosylation matching success rates and cold chain infrastructure development serving as key biopharmaceutical-specific forecast inputs.
Practitioners should monitor FDA interchangeability designation denial rates, EMA biosimilar guideline revisions, and state-level pharmacy substitution law amendments for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Global Sirolimus Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Global Biosimilars Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Etanercept Market