
 Tumor Necrosis Factor Inhibitor Market | 2026-2036
Tumor Necrosis Factor Inhibitor Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Necrosis Factor Inhibitor Market Analysis
Biologics manufacturing capacity in Ireland is expanding to support European supply of monoclonal antibodies for autoimmune therapy. AbbVie Inc leverages its vertically integrated production network to sustain adalimumab supply continuity across multiple continents. Pfizer Inc competes through biosimilar development programs that anchor its position in post-patent TNF inhibitor markets.
Tumor necrosis factor inhibitors are recombinant protein biologics, typically immunoglobulin G1 antibodies or fusion proteins, manufactured through mammalian cell culture in bioreactors exceeding 10,000-liter scale; they function by binding soluble TNF-alpha or its cell-surface receptors to interrupt inflammatory cytokine signaling in autoimmune pathologies. Adalimumab and etanercept dominate prescription volumes among product types, while infliximab retains concentrated use in hospital-based infusion centers for severe Crohn's disease. Subcutaneous administration routes are displacing intravenous delivery in rheumatoid arthritis as home care settings expand their capacity for patient self-injection training and monitoring.
FDA, EMA, and WHO frameworks govern TNF inhibitor approval, with FDA's biosimilar interchangeability standards and EMA's biosimilar extrapolation rules directly shaping competitive entry timelines and prescriber confidence in switching. The IRA's Medicare price negotiation provisions in the United States will restructure revenue expectations for originator molecules selected in forthcoming rounds. Stakeholders must monitor pipeline positioning in ulcerative colitis and psoriasis, where clinical differentiation increasingly determines formulary placement against emerging JAK and IL-23 alternatives.
Market Dynamics
FDA biosimilar interchangeability standards and EMA extrapolation rules are compressing originator exclusivity windows while expanding prescriber choice architectures across autoimmune therapy markets.
Growth Catalysts
- Subcutaneous delivery platforms:Rheumatology clinics in Germany are scaling patient self-injection training programs to reduce infusion center congestion. Home administration protocols expand prescriber capacity for biologic initiation.
- IRA Medicare price negotiation:Selected originator molecules face scheduled price resets that redirect formulary placement toward biosimilar alternatives in United States commercial plans.
- Ulcerative colitis pipeline positioning:Clinical differentiation against JAK inhibitors and IL-23 antagonists secures hospital pharmacy committee access for TNF inhibitors in inflammatory bowel disease.
Market Restraints
- Manufacturing concentration risk:Mammalian cell culture capacity in Ireland supplies European monoclonal antibody demand, creating single-geography vulnerability for adalimumab and infliximab active pharmaceutical ingredient.
- Immunogenicity surveillance burden:Anti-drug antibody testing requirements extend treatment monitoring costs and complicate switching protocols between originator and biosimilar products.
- Storage and cold chain complexity:Temperature-controlled distribution from 2-8°C limits pharmacy dispensing flexibility and raises logistics costs for community-based rheumatology practices.
Strategic Opportunities
- Latin America biosimilar penetration:ANVISA accelerated approval pathways in Brazil create first-mover positioning for etanercept and adalimumab biosimilars ahead of originator patent cliff timing.
- Psoriasis combination protocols:Topical corticosteroid integration with subcutaneous TNF inhibition offers dermatology clinics pathway to step-up therapy adherence in moderate-to-severe plaque psoriasis.
- Digital therapeutic adjuvants:Mobile-enabled injection reminders and flare-tracking applications are pairing with biologic prescriptions to differentiate pharmacy benefit manager formulary placement.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization for high-titer monoclonal antibody production requires specialized bioprocess engineers concentrated in Boston and Basel talent pools.
- Switching study design complexity:EMA extrapolation rules demand indication-specific immunogenicity data that extends biosimilar development timelines and raises clinical trial costs for multiple autoimmune indications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Necrosis Factor Inhibitor Market |
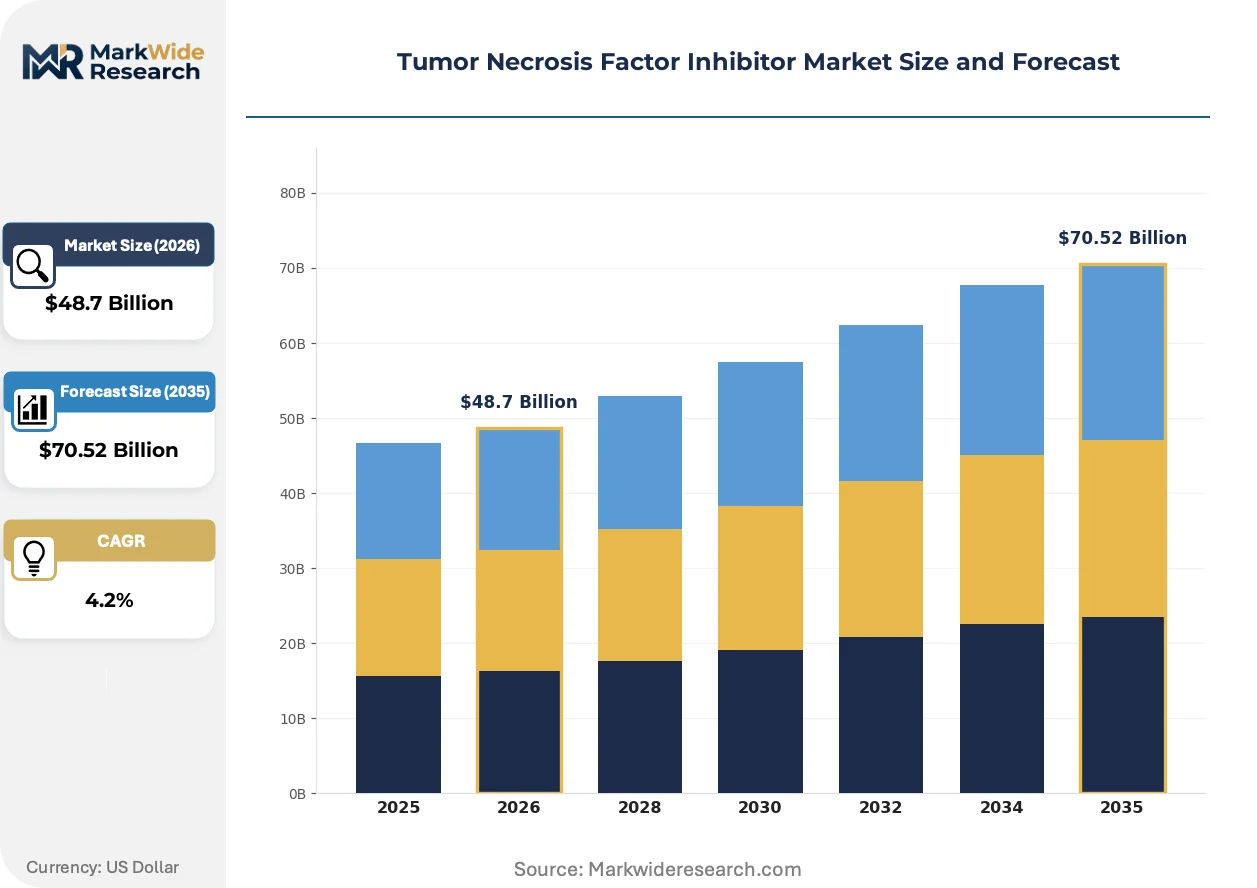
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adalimumab, Infliximab, Etanercept, Certolizumab End User: Hospitals, Clinics, Home Care, Specialty Pharmacies Indication: Rheumatoid Arthritis, Psoriasis, Crohn's Disease, Ulcerative Colitis Administration Route: Subcutaneous, Intravenous, Oral, Transdermal |
| Companies Covered | AbbVie Inc, Amgen Inc, Johnson & Johnson, Pfizer Inc, UCB, Janssen Biotech, Inc., Merck & Co., Inc., Samsung Bioepis Co., Ltd., Celltrion Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Necrosis Factor Inhibitor Market Emerging Trajectories
Biosimilar substitution mechanics and patient-administered delivery systems are restructuring competitive dynamics across rheumatology, dermatology, and gastroenterology prescribing environments.
Subcutaneous autoinjector devices are overtaking intravenous infusion as the dominant administration modality in rheumatoid arthritis care. Community rheumatology practices in the United States are converting infusion suites to injection training rooms. This shift compresses hospital pharmacy revenue from biologic administration while expanding home health monitoring service contracts.
EMA biosimilar extrapolation guidelines now permit approval across all TNF inhibitor indications without duplicate clinical trials in each therapeutic area. Hospital pharmacy committees in Germany are leveraging this regulatory efficiency to accelerate formulary adoption of adalimumab biosimilars. Statutory health insurance funds negotiate rebate contracts that favor these extrapolated products in Crohn's disease and ankylosing spondylitis.
Patient switching behavior between originator and biosimilar products is hardening around pharmacy benefit manager tier structures and prior authorization requirements. United States commercial plans are deploying step-therapy protocols that mandate biosimilar trial before originator coverage. Rheumatology practices report higher administrative burden but reduced patient cost-sharing friction under these arrangements.
Tumor Necrosis Factor Inhibitor Market Segmentation
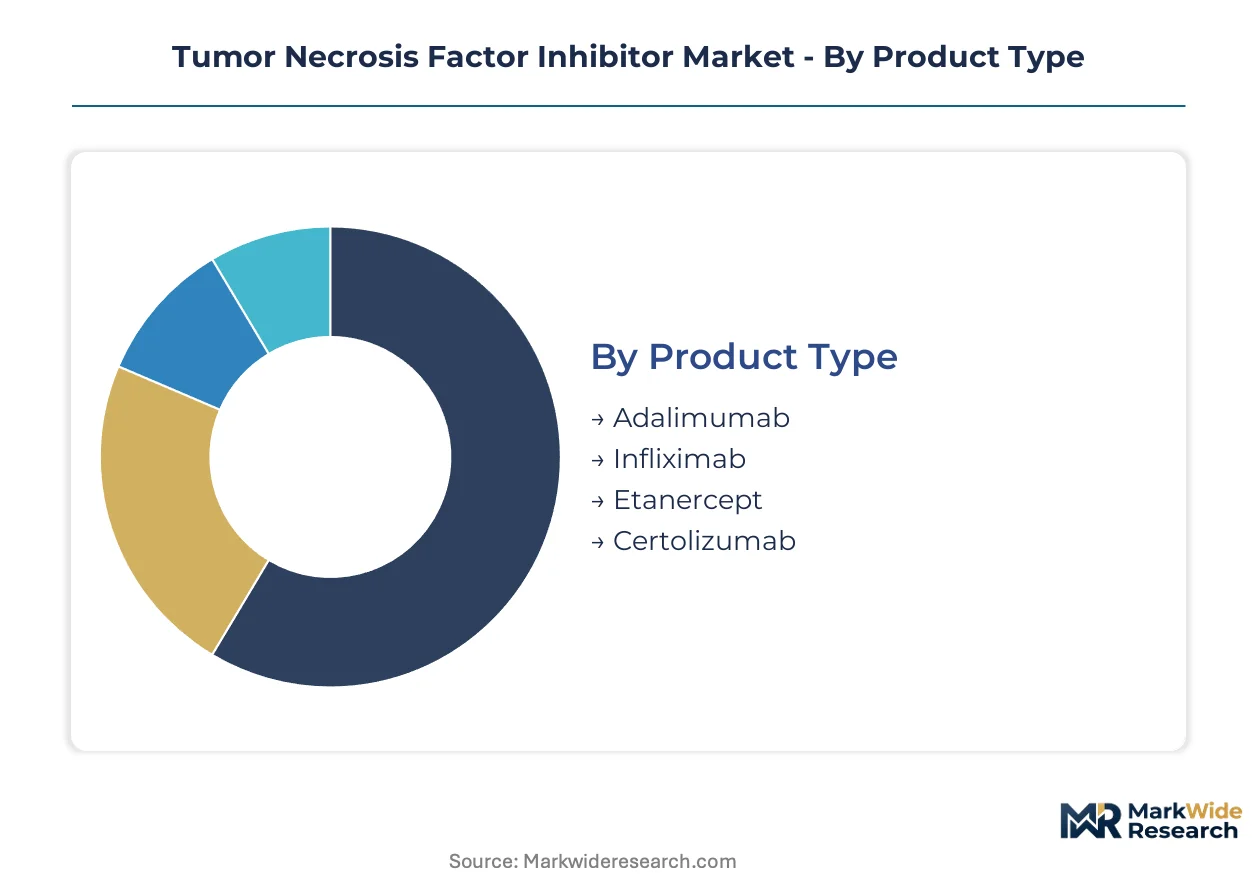
TNF inhibitor prescribing patterns diverge sharply across delivery settings and autoimmune indications, with reimbursement structures and patient acuity determining product selection. Manufacturers align formulation development with site-of-care economics rather than clinical efficacy alone.
Product Type:
Prescriber familiarity and biosimilar substitution rules determine formulary tier placement across rheumatology, dermatology, and gastroenterology practices.
- Adalimumab:A fully human immunoglobulin G1 monoclonal antibody targeting soluble and membrane-bound TNF-alpha, administered via subcutaneous prefilled pen or syringe. Rheumatology clinics in Germany favor this molecule for patient self-injection programs, though statutory health insurance rebate contracts increasingly mandate biosimilar alternatives.
- Infliximab:A chimeric monoclonal antibody requiring intravenous infusion in hospital-based settings, with dosing weight-adjusted and administered over two hours. Severe Crohn's disease cases in United States academic medical centers retain concentrated use despite subcutaneous alternatives, driven by infusion center revenue capture and gastroenterologist prescribing habits.
- Etanercept:A dimeric fusion protein combining TNF receptor 2 with human IgG1 Fc domain, delivered subcutaneously twice weekly.
- Certolizumab:A PEGylated Fab fragment lacking Fc region, reducing placental transfer in pregnant patients with inflammatory bowel disease.
Adalimumab leads on scale; certolizumab leads on momentum in maternal-fetal medicine applications.
End User:
Site-of-care economics and prior authorization complexity reshape patient flow between institutional and community settings.
- Hospitals:Inpatient infusion centers manage acute Crohn's flares and biologic-naive patients requiring loading dose supervision. United States hospital pharmacy committees leverage 340B drug pricing program discounts to capture margin on infliximab administration.
- Clinics:Community rheumatology practices in the United States are converting infusion suites to injection training rooms as subcutaneous products displace intravenous delivery.
- Home Care:Nurse-administered subcutaneous injections for patients with mobility limitations or rural access barriers.
- Specialty Pharmacies:Centralized dispensing hubs managing cold chain distribution and patient adherence monitoring for pharmacy benefit manager contracts.
Hospitals dominate revenue concentration; home care is expanding most quickly as self-injection protocols mature.
Indication:
Competitive intensity from JAK inhibitors and IL-23 antagonists varies by autoimmune disease, forcing TNF inhibitors to defend position through combination protocols and biosimilar pricing.
- Rheumatoid Arthritis:The largest prescription volume indication with established methotrexate combination protocols. German rheumatology clinics prioritize adalimumab and etanercept for first-line biologic therapy under statutory health insurance formularies.
- Psoriasis:Dermatology practices favor subcutaneous administration for patient convenience, though IL-17 and IL-23 inhibitors are gaining share in moderate-to-severe plaque disease.
- Crohn's Disease:Hospital-based gastroenterology retains infliximab preference for fistulizing disease and acute severe presentations.
- Ulcerative Colitis:TNF inhibitors face formulary pressure from tofacitinib and ustekinumab in maintenance therapy.
Rheumatoid arthritis anchors volume; psoriasis shows steepest competitive pressure from novel mechanisms.
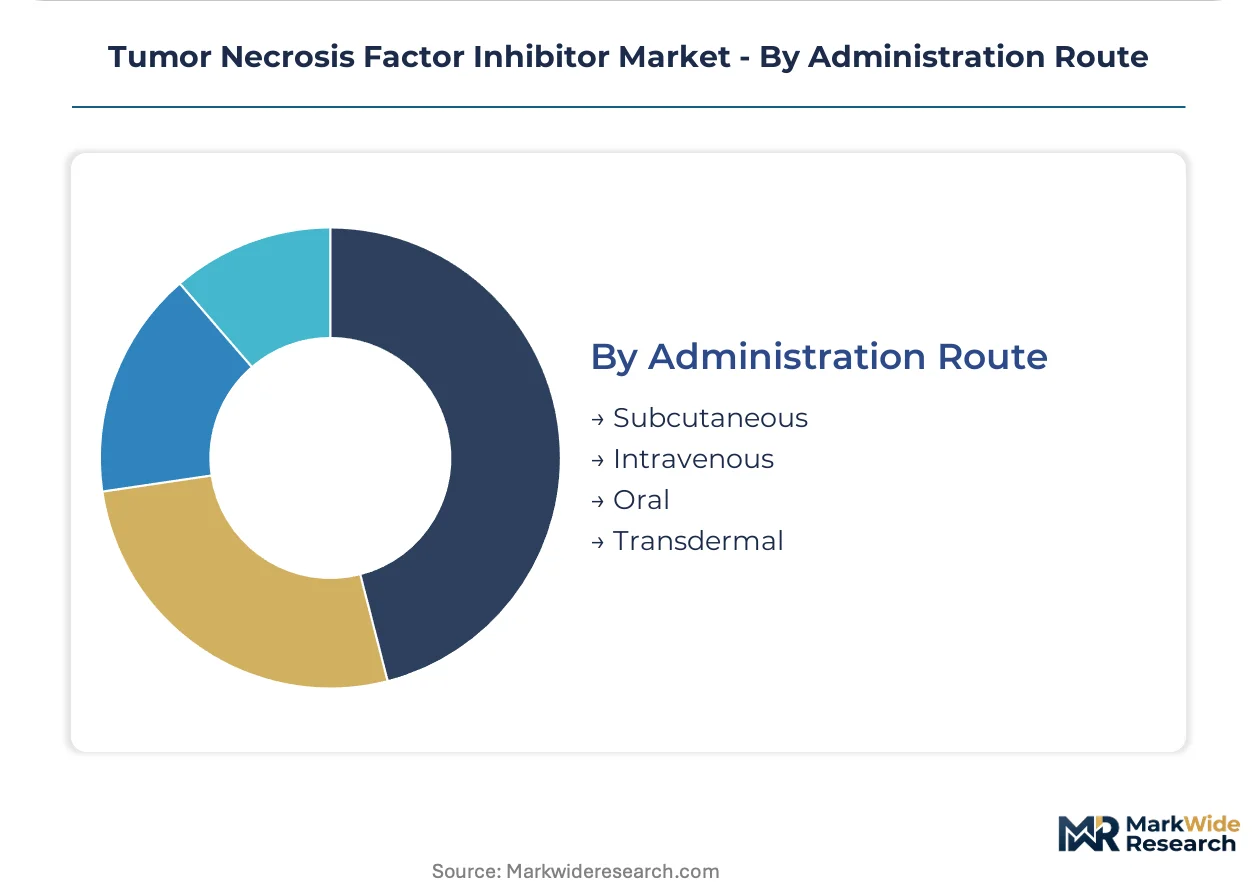
Administration Route:
Delivery technology investments concentrate where patient self-administration reduces total cost of care and expands prescriber capacity.
- Subcutaneous:Prefilled autoinjector devices and wearable injector systems enabling home administration. United States rheumatology practices report reduced nursing burden and expanded patient panel capacity under this model.
- Intravenous:Infusion center delivery requiring healthcare professional supervision, concentrated in Crohn's disease and patient populations with adherence concerns.
- Oral:Small molecule JAK inhibitors compete in this delivery space; no approved oral TNF inhibitors exist.
- Transdermal:Experimental patch delivery systems in early development for patient populations with needle aversion.
Subcutaneous delivery commands prescriber preference; intravenous retains hospital pharmacy revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance rebate contracts concentrate TNF inhibitor demand differently than the United States, where Medicare price negotiation reshapes commercial formulary placement.
United States
Rheumatology clinics in Texas and Florida are converting infusion suites to injection training rooms as subcutaneous protocols expand. The FDA's biosimilar interchangeability standards accelerate prescriber switching behavior. Boston and San Francisco biotech clusters anchor mammalian cell culture expertise for monoclonal antibody production.
Germany
Statutory health insurance funds in Bavaria and North Rhine-Westphalia negotiate rebate contracts favoring adalimumab and etanercept prescribing. EMA biosimilar extrapolation rules permit rapid formulary adoption across Crohn's disease and ankylosing spondylitis. The Frankfurt-Rhine-Main pharmaceutical corridor hosts biologics distribution hubs serving European cold chain requirements.
Japan
PMDA accelerated approval pathways for biosimilars are compressing originator exclusivity windows in rheumatoid arthritis. METI industrial policy supports domestic biologics manufacturing capacity expansion. The Kanto region around Tokyo concentrates hospital pharmacy committees managing infliximab infusion revenue.
Brazil
ANVISA accelerated approval pathways create first-mover positioning for etanercept and adalimumab biosimilars ahead of originator patent cliffs. São Paulo's hospital networks anchor biologic infusion capacity for severe Crohn's disease. The São Paulo-Rio de Janeiro corridor dominates specialty pharmacy distribution for temperature-controlled monoclonal antibodies.
India
CDSCO regulatory frameworks are evolving to accommodate biosimilar development programs for export markets. Maharashtra and Telangana biotech parks are attracting contract manufacturing organizations for mammalian cell culture. Hyderabad's vaccine and biologics cluster is expanding into TNF inhibitor active pharmaceutical ingredient production.
Tumor Necrosis Factor Inhibitor Market Vendor Landscape
United States producers anchor one tier; European specialists hold manufacturing concentration through Irish biologics capacity. The market structures around three player archetypes: vertically integrated originators with captive supply networks, biosimilar developers leveraging extrapolation rules for rapid indication expansion, and contract manufacturers capturing overflow demand from capacity-constrained innovators. Consolidation pressures intensify as Medicare price negotiation provisions compress revenue expectations for selected molecules, while strategic partnerships between biosimilar developers and specialty distributors reshape channel access.
Among originator-tier biopharmaceutical companies, AbbVie Inc and Amgen Inc exemplify vertically integrated production architectures spanning multiple continents. Pfizer Inc occupies a position within the biosimilar developer archetype, anchoring post-patent market participation through development programs targeting adalimumab and etanercept alternatives. These three entities represent the competitive spectrum from proprietary molecule defense to generic biologic penetration.
| Leading Market Players |
|---|
| AbbVie Inc |
| Amgen Inc |
| Johnson & Johnson |
| Pfizer Inc |
| UCB |
| Janssen Biotech, Inc. |
| Merck & Co., Inc. |
| Samsung Bioepis Co., Ltd. |
| Celltrion Healthcare |
| Others |
Supply Flow & Price Mechanics
Mammalian cell culture scale-up to 10,000-liter bioreactors is compressing per-gram production costs while concentrating active pharmaceutical ingredient output in Irish manufacturing parks. This process intensification simultaneously erodes originator pricing power and raises geographic supply vulnerability for European TNF inhibitor markets.
Pricing Analysis
Capacity additions in Ireland are reshaping price floors for adalimumab and infliximab across European markets. Three-tier pricing structure across originator, interchangeable biosimilar, and non-interchangeable biosimilar levels stratifies hospital pharmacy procurement. Cost compression in the biosimilar tier is intensifying because EMA extrapolation rules accelerate competitive entry. Statutory health insurance funds in Germany exhibit highest price sensitivity; United States academic medical centers retain lowest sensitivity due to 340B discount capture.
Supply Chain Analysis
Cold chain logistics costs from 2-8°C distribution anchor total delivered cost for subcutaneous autoinjector products. Active pharmaceutical ingredient production concentrates in Ireland, the United States, and Switzerland. Mammalian cell culture media, single-use bioreactor bags, and PEGylation reagents constitute critical input dependencies. Single-source vulnerability for high-titer cell line development expertise in Boston and Basel talent pools threatens supply continuity. Distribution runs through specialty pharmacy hubs managing temperature-controlled last-mile delivery to rheumatology practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in biosimilar manufacturing scale-up and subcutaneous delivery platform premiumization. Cost compression from process intensification and cold chain optimization underwrites this trajectory.
For Market Incumbents: To counter biosimilar substitution pressure from Samsung Bioepis and Celltrion, originators should deepen backward integration into mammalian cell culture media production and secure exclusive autoinjector device supply agreements. Captive control over fill-finish capacity in multiple regulatory jurisdictions preserves formulary tier placement against interchangeable competitors. For New Entrants and Emerging Players: Rural home care settings with limited infusion center access represent the most penetrable buyer archetype for subcutaneous biosimilar entry. ANVISA accelerated approval pathways in Brazil offer regulatory fast-track positioning ahead of patent cliffs. Partnership models with specialty pharmacy distributors enable rapid channel access without direct sales infrastructure buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturing organizations with mammalian cell culture capacity expansion underway. Long-term viability hinges on sustained biosimilar substitution rates and IRA Medicare price negotiation scope expansion. The signal to watch is FDA interchangeability designation grants for adalimumab biosimilars.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | 10,000-liter bioreactor deployment in Ireland reduces per-dose COGS for biosimilar producers. |
| Regulatory Approval Pathway | FDA interchangeability designation unlocks automatic substitution at pharmacy level without prescriber intervention. |
| Licensing Agreement | Autoinjector device technology licensing from Becton Dickinson or Ypsomed accelerates subcutaneous product differentiation. |
| Pipeline Diversification | Ulcerative colitis indication expansion leverages EMA extrapolation rules for rapid formulary access. |
| Strategic Partnership | Specialty pharmacy distribution alliances with CVS Specialty or Accredo secure cold chain logistics capacity. |
Methodological Framework
Multiple input streams — regulatory filing analysis, procurement database extraction, and manufacturing capacity surveys — were reconciled to construct market estimates. Primary interviews with drug development executives, formulary directors at German statutory health insurers, hospital procurement managers, and payer access specialists were cross-validated against secondary sources including FDA biosimilar approval records, EMA assessment reports, ClinicalTrials.gov protocols, and hospital 340B utilization data. Bottom-up patient volume modeling and top-down revenue reconciliation anchored final projections.
Historical prescription volume trajectories were cross-referenced against panel input from rheumatology practice administrators to calibrate adoption curve assumptions. Segmentation dimensions modeled include product type, administration route, indication, end-user setting, and regional regulatory cluster. CAGRs were derived from indication-specific patient population growth and biosimilar penetration rate assumptions. Forecast inputs incorporated IRA Medicare price negotiation selection rounds and EMA extrapolation rule evolution.
Underlying measurement precision varies by segment; rheumatoid arthritis prescription volumes carry tighter precision than emerging psoriasis combination protocols. Forecasts reflect assumptions regarding biosimilar substitution elasticity and cold chain logistics cost trajectories. A model refresh is warranted upon material change in FDA interchangeability designation standards or IRA negotiation scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Europe Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
US Biosimilars Market
Biosimilars
Global Biosimilars Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Dasatinib Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Oncology Biosimilars Market