
 Biologics and Biosimilars Market | 2026-2036
Biologics and Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Biologics and Biosimilars Market Analysis
Outcome-based contracting for biologics is recalibrating what pharmaceutical manufacturers actually sell, shifting transactions from vial volume to patient response metrics. Pfizer leverages its hospital channel control to bundle biosimilar portfolios with infusion services. Amgen anchors its position through captive manufacturing of active pharmaceutical ingredients for both originator biologics and follow-on products. Samsung Bioepis competes aggressively on price in European tenders while extending its pipeline into ophthalmology biosimilars.
Biologics and biosimilars comprise therapeutic proteins, monoclonal antibodies, vaccines, and living-cell-derived products manufactured through recombinant DNA technology in bioreactor systems, with molecular weights typically exceeding 1,000 daltons and structural complexity far beyond small-molecule drugs. Their primary purpose centers on targeting specific cellular mechanisms in oncology, autoimmune disorders, and metabolic diseases with precision unavailable to conventional pharmaceuticals. Monoclonal antibodies dominate value generation due to premium pricing in cancer immunotherapy, while the infectious diseases therapy area matures around established vaccine platforms with thinner margins. Injectable delivery modes capture the majority of administration volumes, though infusion maintains share in hospital-based oncology settings where clinician supervision remains mandatory.
The FDA, EMA, and WHO collectively shape market access through biosimilar interchangeability standards, Good Manufacturing Practice inspections, and prequalification programs that determine which products enter national procurement schemes. These frameworks create divergent commercial timelines, with US interchangeability designations accelerating pharmacy-level substitution while European reference pricing compresses margins across member states. Stakeholders must monitor how CMS reimbursement rulemaking for biosimilars under Medicare Part B and Part D alters physician prescribing incentives relative to originator biologics.
Market Dynamics
The FDA's Biosimilar User Fee Act reauthorization is compressing approval timelines for interchangeable products, while Medicare reimbursement rulemaking under Part B and Part D recalibrates physician prescribing economics away from originator biologics toward follow-on alternatives.
Growth Catalysts
- Interchangeability Pathways:The FDA's streamlined designation process accelerates pharmacy-level substitution without prescriber intervention, expanding automatic substitution eligibility across retail and specialty pharmacy networks.
- Oncology Formulary Expansion:Hospital systems are elevating biologics to first-line status in cancer immunotherapy protocols, driven by precision targeting capabilities unavailable to cytotoxic chemotherapy.
- Cell Culture Advances:Single-use bioreactor systems and perfusion manufacturing platforms are reducing batch-to-batch variability while compressing production cycle times for complex glycoproteins.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for monoclonal antibodies concentrates among a limited set of contract development and manufacturing organizations, creating vulnerability to single-source disruptions.
- Immunogenicity Surveillance Burden:Post-market immunogenicity monitoring requirements impose sustained pharmacovigilance costs that erode margin structures for biosimilar sponsors relative to small-molecule generics.
- Reference Product Lifecycle Extension:Originator manufacturers deploy secondary formulation patents and device combination claims to delay biosimilar entry beyond statutory exclusivity periods.
Strategic Opportunities
- Ophthalmology Biosimilars:Anti-VEGF agents for age-related macular degeneration represent underpenetrated therapeutic territory where biosimilar sponsors can establish precedent before reference product patent cliffs.
- Home Administration Models:Subcutaneous formulation development and connected injection devices enable migration from infusion centers to self-administration, capturing margin from site-of-care reimbursement differentials.
- European Tender Participation:National procurement frameworks in Germany, France, and the Nordics reward price-competitive biosimilar portfolios with multi-year hospital supply commitments and formulary anchoring.
Industry Challenges
- Analytical Biosimilarity Demonstration:Establishing structural and functional equivalence for complex glycoproteins requires sophisticated mass spectrometry and bioassay capabilities that strain quality control budgets.
- Switching Study Design Complexity:Designing adequately powered interchangeability trials that satisfy FDA statistical criteria while controlling for patient heterogeneity in autoimmune indications prolongs development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biologics and Biosimilars Market |
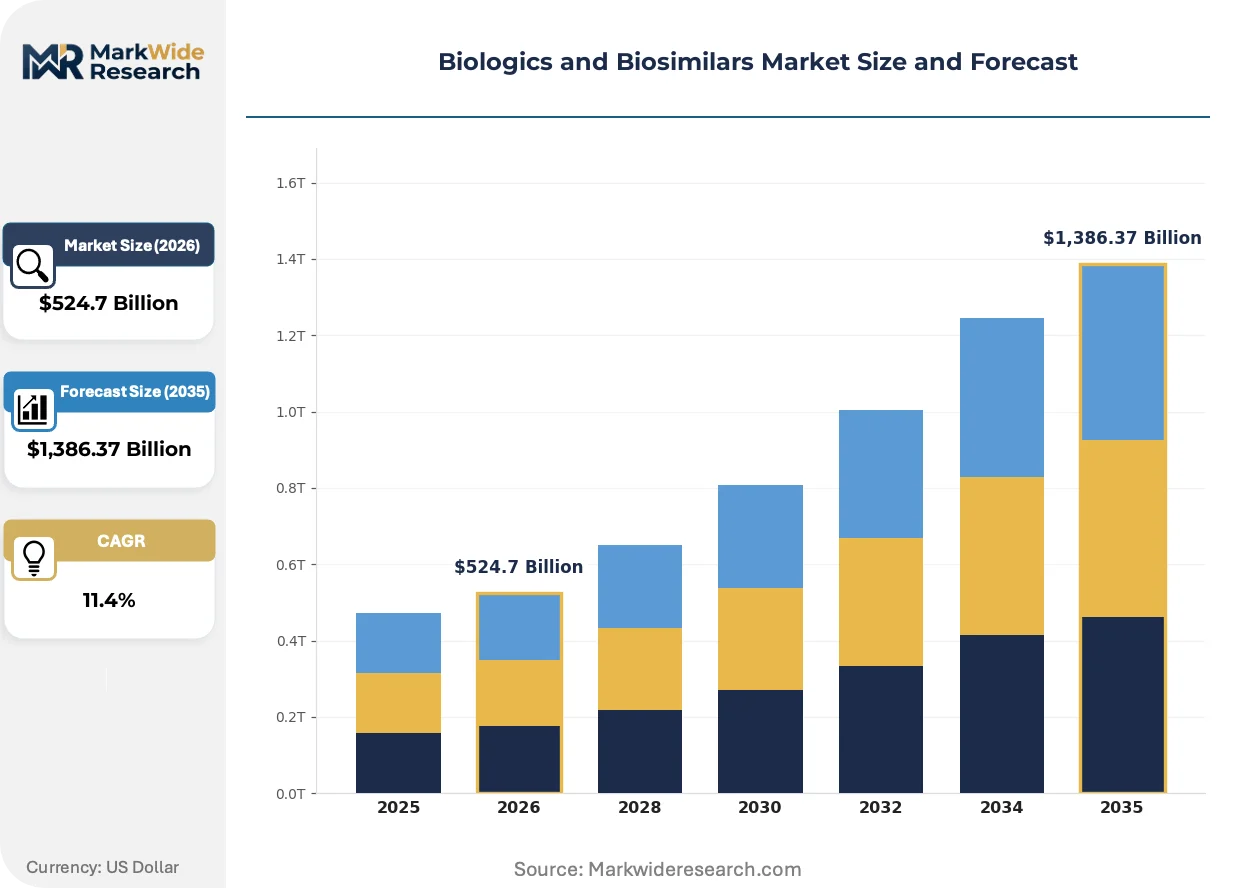
| Market Size in 2026 | $524.7 Billion |
| Market Size in 2035 | $1,386.37 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cytokines, Enzymes End User: Hospitals, Clinics, Research Institutions, Pharmacies Delivery Mode: Injectable, Infusion, Oral, Transdermal Therapy Area: Oncology, Autoimmune Disorders, Infectious Diseases, Metabolic Disorders |
| Companies Covered | Sandoz, Pfizer, Amgen, Novartis, Samsung Bioepis, Celltrion, Biocon Biologics, Roche, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biologics and Biosimilars Market Emerging Trajectories
Continuous manufacturing platforms and real-time release testing are displacing batch-oriented production paradigms, while outcome-based contracting models recalibrate commercial relationships from unit sales to patient response guarantees.
Continuous downstream processing technology is modularizing purification operations for monoclonal antibodies, collapsing multiple chromatography and filtration steps into integrated single-pass systems. Contract manufacturers in Singapore and Switzerland are adopting these platforms to reduce facility footprint and buffer consumption. This architecture is modularizing capacity expansion decisions, enabling sponsors to scale output through parallel train addition rather than greenfield construction.
The EMA's revised biosimilar guidelines now explicitly address extrapolation of indications for monoclonal antibodies with multiple approved uses, clarifying evidentiary requirements for sponsors seeking broad label claims. This regulatory precision reduces development uncertainty for sponsors targeting complex reference products with fragmented indication portfolios. Oncology and immunology biosimilars are responding by consolidating indication-seeking strategies to capture full label scope at initial approval.
Hospital systems are consolidating biologics purchasing through specialty pharmacy carve-outs and 340B program optimization, concentrating volume among a narrowing set of contracted distributors. This channel restructuring displaces traditional wholesale relationships with direct manufacturer-to-health-system agreements. The United States exhibits the most pronounced concentration, with integrated delivery networks capturing substantial share of infused biologic administration.
Biologics and Biosimilars Market Segmentation
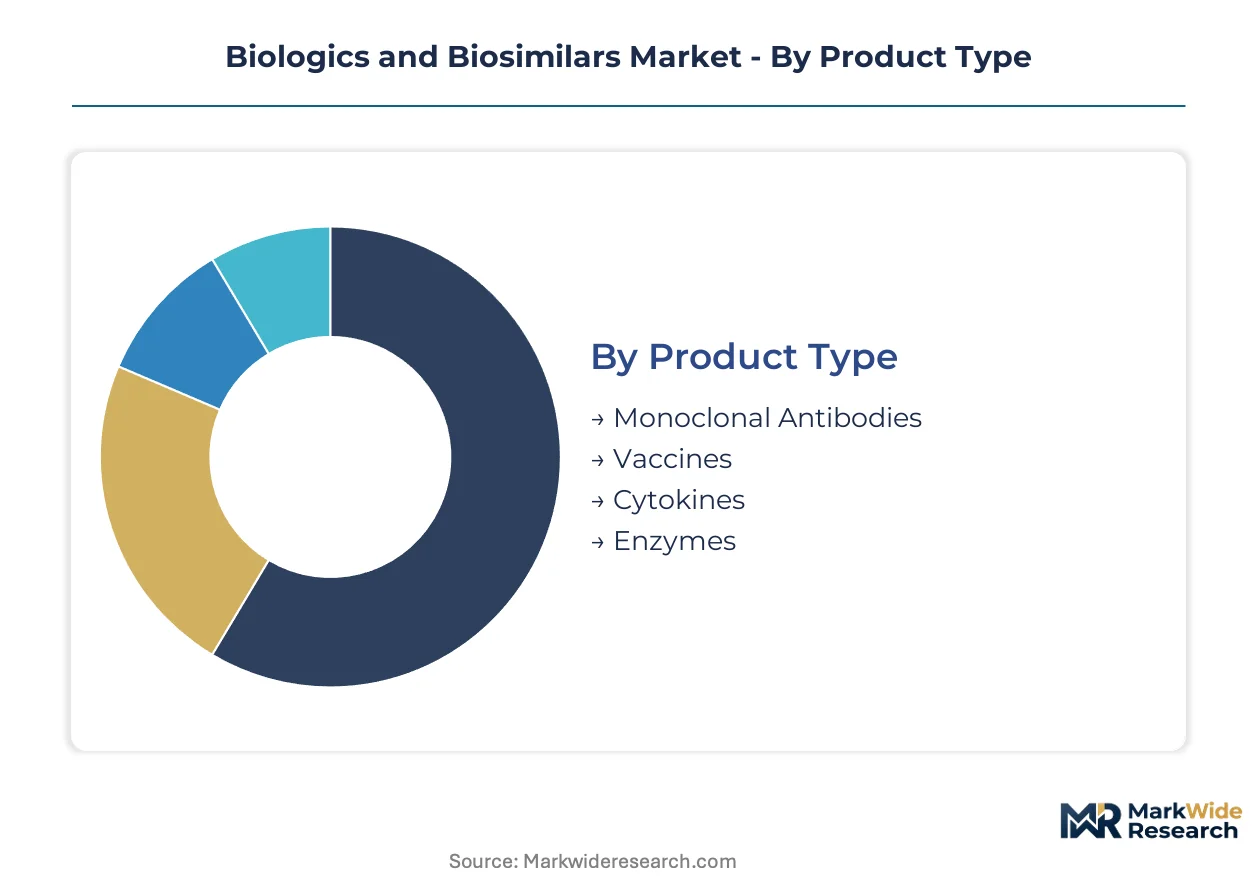
Biologics and biosimilars require precise segmentation to capture how molecular complexity, administration setting, and therapeutic application reshape procurement economics. Each dimension carries distinct margin structures, regulatory burdens, and substitution vulnerabilities that determine competitive positioning.
Product Type:
Purchasing decisions pivot on manufacturing complexity and interchangeability risk tolerance, with higher-margin segments commanding dedicated quality assurance infrastructure.
- Monoclonal Antibodies:Glycoprotein therapeutics engineered through hybridoma or recombinant DNA platforms, typically exceeding 150 kDa molecular weight with post-translational modifications critical to binding affinity. Demand concentrates in US hospital oncology departments where Medicare Part B reimbursement favors biosimilar substitution for reference products facing patent expiry. Manufacturing batch failures carry catastrophic financial exposure due to extended production cycles.
- Vaccines:Antigen-based immunological preparations spanning live-attenuated, inactivated, and subunit formulations produced in embryonated eggs or cell culture systems. European tender frameworks in Germany and France reward multi-year supply commitments for established pediatric and influenza platforms, compressing margins through volume aggregation while ensuring predictable offtake.
- Cytokines:Signaling protein therapies including interferons and interleukins manufactured through bacterial or mammalian expression systems.
- Enzymes:Catalytic protein replacements for metabolic deficiency disorders requiring ultra-purified formulations to minimize immunogenicity risk.
Monoclonal antibodies lead on scale; vaccines lead on momentum through pandemic preparedness procurement.
End User:
Site-of-care economics and reimbursement channel control determine volume allocation across institutional settings.
- Hospitals:Integrated delivery networks capturing infused biologic administration through 340B program optimization and specialty pharmacy carve-outs. US health systems are consolidating purchasing through direct manufacturer agreements that displace wholesale relationships, concentrating volume among contracted distributors with cold-chain capabilities.
- Clinics:Outpatient infusion centers and physician office settings managing subcutaneous and short-infusion biologic protocols. Reimbursement differentials between hospital outpatient departments and independent clinics are shifting site-of-care decisions for immunology and ophthalmology therapies.
- Research Institutions:Academic medical centers and contract research organizations sourcing investigational biologics for clinical trial supply.
- Pharmacies:Retail and specialty pharmacy networks handling self-administered biologics with interchangeability designation for automatic substitution.
Hospitals anchor volume concentration; pharmacies are climbing the fastest as interchangeability expands.
Delivery Mode:
Patient convenience and total cost of care are displacing clinical tradition in administration route selection.
- Injectable:Subcutaneous and intramuscular delivery via prefilled syringes and autoinjector devices enabling home administration. Connected injection technologies with adherence monitoring are capturing margin from site-of-care reimbursement differentials in US Medicare Advantage plans.
- Infusion:Intravenous delivery requiring clinician supervision in hospital or ambulatory infusion center settings. Oncology immunotherapy protocols mandate infusion capacity for monoclonal antibodies with infusion-related reaction risk profiles.
- Oral:Emerging peptide and protein formulations exploiting permeation enhancers and enteric coatings for gastrointestinal stability.
- Transdermal:Microneedle and iontophoresis systems for macromolecule delivery bypassing first-pass metabolism.
Infusion dominates current value; injectable formats show steepest expansion trajectory through self-administration migration.
Therapy Area:
Clinical unmet need and pricing authority vary dramatically across disease categories, with oncology commanding premium positioning.
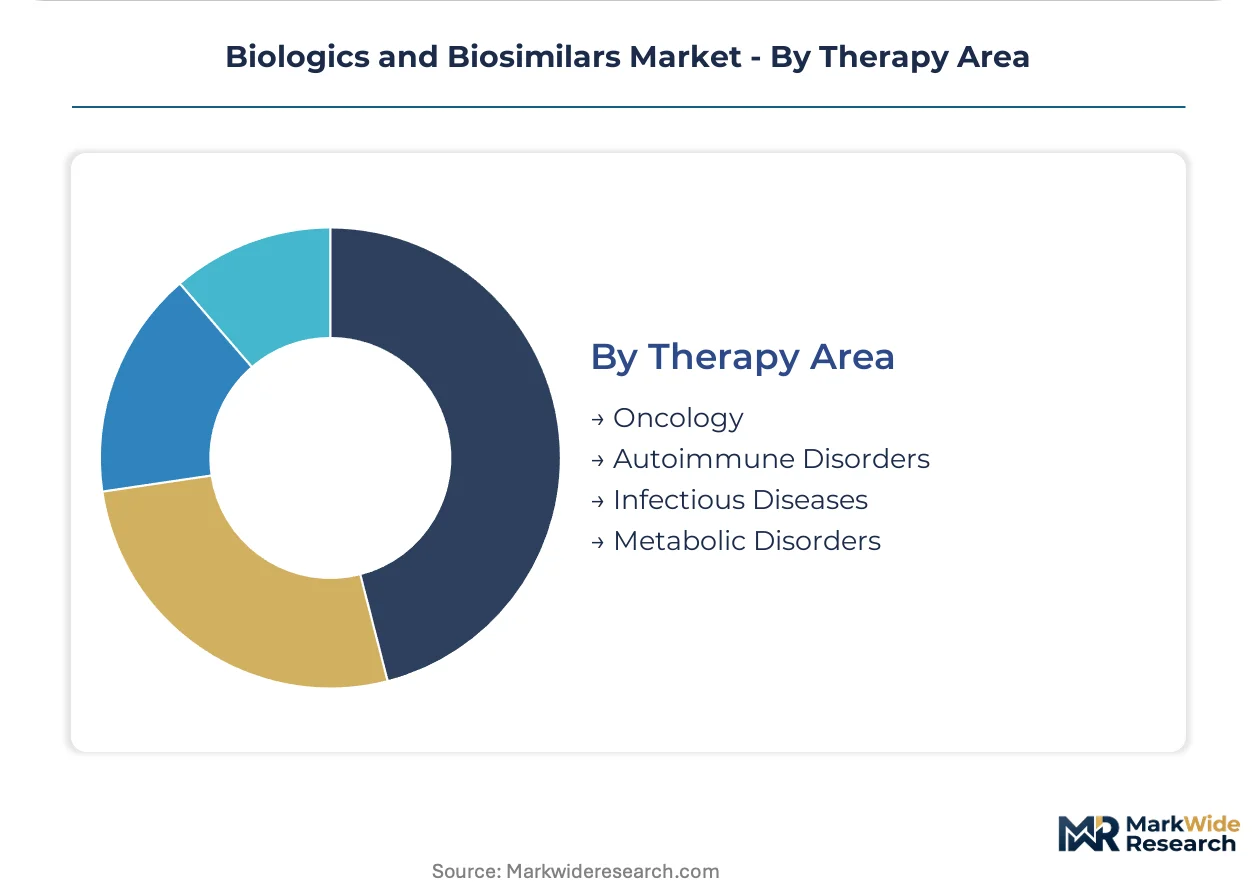
- Oncology:Immune checkpoint inhibitors and anti-angiogenic antibodies targeting tumor microenvironment mechanisms. Hospital systems are elevating these to first-line status in cancer protocols, with US formulary committees prioritizing precision targeting over cytotoxic chemotherapy where biomarker selection enables response prediction.
- Autoimmune Disorders:TNF-alpha inhibitors and interleukin antagonists for rheumatoid arthritis, psoriasis, and inflammatory bowel disease. European reference pricing across member states compresses margins for established anti-TNF biosimilars while volume expands through indication extrapolation.
- Infectious Diseases:Vaccines and monoclonal antibody prophylaxis for viral and bacterial pathogens.
- Metabolic Disorders:Enzyme replacement therapies and insulin analogs for diabetes, lysosomal storage diseases, and hormone deficiencies.
Oncology leads on pricing power; autoimmune disorders gain share fastest through biosimilar volume penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium pricing for monoclonal antibodies while Germany anchors European biosimilar procurement through national tender frameworks. Japan maintains stringent immunogenicity surveillance requirements that extend approval timelines relative to other developed markets. India and South Korea emerge as manufacturing hubs with distinct competitive strategies.
United States
Oncology formulary expansion and Medicare Part B reimbursement reform drive hospital system adoption of biosimilar substitution. The FDA's Biosimilar User Fee Act reauthorization compresses interchangeability designation timelines. The Boston-Cambridge biotech cluster anchors monoclonal antibody development, with contract manufacturers expanding single-use bioreactor capacity to serve integrated delivery networks.
Germany
Reference pricing across statutory health insurance funds compresses margins while expanding volume through automatic substitution mandates. The EMA's centralized marketing authorization enables rapid multi-country rollout post-approval. The Rhine-Main region concentrates fill-finish operations for biosimilar exports, with Frankfurt Airport's cold-chain logistics supporting just-in-time hospital delivery.
Japan
PMDA immunogenicity guidelines require extensive post-market surveillance that prolongs commercialization timelines for follow-on biologics. The Ministry of Health, Labour and Welfare's pricing reform introduces cost-effectiveness thresholds for biologic reimbursement. The Kansai region hosts mammalian cell culture facilities serving domestic oncology demand, with Osaka-based manufacturers investing in perfusion platform technology.
India
CDSCO accelerated approval pathways for well-characterized biosimilars reduce entry barriers for domestic sponsors targeting export markets. The government's PLI scheme for pharmaceuticals incentivizes biologics manufacturing investment. The Hyderabad-Bangalore corridor anchors contract development and manufacturing organization capacity, with Genome Valley facilities supplying active pharmaceutical ingredients to European and US sponsors.
South Korea
MFDS biosimilar guidelines align with ICH standards, enabling parallel FDA and EMA submission strategies for multinational sponsors. National health insurance price negotiations favor volume-based contracts for anti-TNF biosimilars. The Songdo biocluster concentrates monoclonal antibody production, with Incheon's free economic zone offering tax incentives for biologics export manufacturing.
Biologics and Biosimilars Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator biologics retaining pricing power in oncology while biosimilar sponsors compete on procurement tenders in immunology. The market structure exhibits tiered consolidation: multinational pharmaceutical conglomerates anchor premium therapeutic areas, mid-scale biologics specialists capture biosimilar volume, and contract manufacturers supply active pharmaceutical ingredients across both tiers. Three archetypes dominate: originator defenders with captive manufacturing infrastructure, biosimilar attackers leveraging cost-optimized production platforms, and vertically integrated CDMOs controlling critical bioreactor capacity. Competitive dynamics center on M&A-driven portfolio consolidation and strategic partnerships for cell culture technology licensing.
Among Swiss-based pharmaceutical conglomerates, Novartis and Roche exemplify originator-defender archetypes with established oncology biologics portfolios. Pfizer represents the diversified multinational pursuing biosimilar expansion through hospital channel integration. Samsung Bioepis anchors the Korean biosimilar specialist tier, competing aggressively on price in European tenders while extending into ophthalmology therapeutic areas. These three entities collectively illustrate the competitive tension between premium-priced innovation and cost-optimized follow-on substitution.
| Leading Market Players |
|---|
| Sandoz |
| Pfizer |
| Amgen |
| Novartis |
| Samsung Bioepis |
| Celltrion |
| Biocon Biologics |
| Roche |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in South Korea and India anchor capacity expansion financing, compressing cost structures for monoclonal antibody manufacturing while tightening pricing discipline across European tender markets. This ownership pattern concentrates supply-side investment in tax-advantaged bioclusters, with export credit agencies de-risking bioreactor construction that feeds into reference pricing negotiations.
Pricing Analysis
Capacity additions in South Korea and Singapore are reshaping price floors for monoclonal antibodies as perfusion manufacturing platforms reduce unit costs. Three-tier pricing structure across originator premium, biosimilar standard, and tender economy levels stratifies by interchangeability designation and indication breadth. Cost compression in the biosimilar tier is intensifying because automatic substitution mandates expand pharmacy-level substitution eligibility. Hospital procurement committees exhibit highest price sensitivity through competitive tender frameworks, while oncology departments retain lowest sensitivity due to precision targeting requirements and Medicare Part B reimbursement differentials.
Supply Chain Analysis
Cold-chain logistics costs for biologics hinge on Frankfurt Airport and Incheon International as primary distribution hubs for temperature-sensitive monoclonal antibodies. Active pharmaceutical ingredient manufacturing concentrates in Switzerland, South Korea, and India, with mammalian cell culture operations drawing from Chinese-sourced media components and German-engineered bioreactor systems. Single-source vulnerability permeates the contract manufacturing tier where limited CDMOs control perfusion platform expertise. Distribution runs through direct manufacturer-to-health-system agreements that displace wholesale relationships in US integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biologics and biosimilars market functions as a regulatory compounder where FDA interchangeability designations and Medicare reimbursement rulemaking create accelerating returns for sponsors navigating approval complexity. The Biosimilar User Fee Act reauthorization compresses timelines for automatic substitution eligibility, expanding addressable market for follow-on sponsors.
For Market Incumbents: Extend manufacturing capacity in tax-advantaged bioclusters to defend margin structures against Korean and Indian biosimilar price aggression. Secure captive active pharmaceutical ingredient supply through backward integration or long-term CDMO contracts to mitigate single-source disruption risk. Anchor hospital formulary position through bundled infusion service offerings that raise switching costs for biosimilar competitors. For New Entrants and Emerging Players: Ophthalmology anti-VEGF biosimilars represent an underserved buyer archetype with limited current competition and impending patent cliffs for reference products. Target European national tender frameworks in Germany and France where price-competitive portfolios secure multi-year hospital supply commitments. Pursue subcutaneous formulation development to capture site-of-care reimbursement differentials in US Medicare Advantage plans. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale CDMOs with perfusion platform capabilities and established FDA inspection histories. Five-to-ten year viability favors contract manufacturers with bioreactor capacity in Singapore and Switzerland serving both originator and biosimilar sponsors. Watch FDA interchangeability designation velocity as the inflection indicator for biosimilar substitution penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeability Designation Pursuit | FDA streamlined pathways accelerate pharmacy-level substitution without prescriber intervention. |
| Perfusion Manufacturing Scale-Up | Single-use bioreactor systems reduce batch variability and compress production cycle times. |
| European Tender Participation | German and French procurement frameworks reward price-competitive biosimilar portfolios. |
| Ophthalmology Pipeline Extension | Anti-VEGF agents for macular degeneration offer underpenetrated therapeutic territory. |
| Subcutaneous Formulation Development | Self-administration migration captures margin from site-of-care reimbursement differentials. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, formulary directors at integrated delivery networks, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient-flow modeling and top-down market sizing triangulated volume estimates across therapeutic areas and administration settings.
Historical reference periods anchored the projection framework to observed biosimilar adoption curves and patent expiry timelines across the analysis window. Segmentation dimensions modeled include product type, delivery mode, therapy area, end-user setting, and regional regulatory cluster. CAGRs derived from patent cliff sequencing, interchangeability designation velocity, and hospital formulary expansion patterns. Forecast inputs incorporated Medicare Part B reimbursement rulemaking and EMA guideline revisions affecting indication extrapolation.
Underlying measurement precision varies by segment; oncology and autoimmune disorder forecasts carry tighter precision than emerging ophthalmology categories due to established patient registries and claims data availability. Forecasts reflect assumptions regarding regulatory approval timelines, interchangeability study success rates, and hospital procurement consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Etanercept Market
Biosimilars
Imatinib Drug Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Dasatinib Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
US Biosimilars Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Fusion Protein and Biosimilars Market