
 Interchangeable Biosimilars Market | 2026-2036
Interchangeable Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Interchangeable Biosimilars Market Foresight
The EU Green Deal's pharmaceutical sustainability framework is restructuring procurement criteria across European hospital networks. Sandoz leverages its vertically integrated biologics manufacturing network to sustain cost leadership in monoclonal antibody production. Samsung Bioepis anchors its competitive position through deep specialization in oncology and immunology biosimilars.
Interchangeable biosimilars are biologic medicines that demonstrate no clinically meaningful differences from their reference products in terms of safety, purity, and potency, with additional switching studies required to support pharmacy-level substitution without prescriber intervention; they are manufactured through recombinant DNA technology in living cell lines under stringent controlled conditions. Their primary purpose is to expand patient access to high-cost biologic therapies while maintaining therapeutic equivalence standards that enable automatic substitution at the pharmacy counter. Monoclonal antibodies command the dominant revenue share within product type segmentation due to their concentration in oncology and immunology, where reference product costs run highest. Subcutaneous delivery modes are gaining fastest traction as patient preference shifts toward self-administration and reduced clinic burden. Hospitals remain the deepest margin pool among end users, though specialty pharmacies are capturing growing volume as outpatient biosimilar dispensing expands.
FDA interchangeability guidelines, EMA biosimilar pathways, and WHO prequalification standards collectively shape market access timelines, manufacturing investment decisions, and cross-border commercialization strategies for developers. The FDA's evolving immunogenicity requirements for switching studies directly influence R&D program costs and regulatory submission timelines. Stakeholders must monitor how payer consolidation and formulary exclusion policies will determine which interchangeable products achieve preferred tier status without originator rebate competition.
Market Dynamics
Statutory health insurance tendering mechanisms in Germany are compressing reference product pricing floors while the FDA's interchangeability designation pathway accelerates automatic pharmacy substitution without prescriber intervention.
Growth Catalysts
- IRA Medicare Price Negotiation:The Inflation Reduction Act's biologic price negotiation provisions create direct economic pressure on originator manufacturers to accelerate biosimilar uptake.
- EMA Biosimilar Pathway Harmonization:Streamlined European Medicines Agency approval processes reduce regulatory duplication costs for developers seeking multi-country market access.
- Oncology Reference Product Patent Cliffs:Concentrated expiration of monoclonal antibody exclusivities opens substitutable volume in the highest-cost therapeutic categories.
Market Restraints
- Immunogenicity Testing Burden:FDA switching study requirements for interchangeability designation impose substantial clinical trial costs that deter mid-cap developers from full substitution eligibility.
- Originator Rebate Trap:Pharmacy benefit managers in the United States retain formulary preference for reference products through opaque rebate structures that obscure true net pricing.
- Single-Source API Concentration:Cell culture media and bioreactor equipment supply concentrates among German and Swiss specialty chemical producers, creating input vulnerability.
Strategic Opportunities
- Subcutaneous Formulation Expansion:Self-administration preference among rheumatology and dermatology patients opens pharmacy-dispensed volume outside hospital infusion centers.
- Japan PMDA Fast-Track Designation:Japan's Pharmaceuticals and Medical Devices Agency offers accelerated review for biosimilars addressing unmet oncology need, compressing time-to-market.
- Specialty Pharmacy Channel Integration:Direct distribution partnerships with limited-distribution networks bypass traditional wholesale markups and capture patient adherence data.
Industry Challenges
- Cell Line Development Expertise Scarcity:Mammalian expression system optimization requires rare hybridoma engineering talent concentrated among legacy biologics manufacturers.
- Comparative Efficacy Trial Design Complexity:FDA immunogenicity endpoint standardization remains unsettled, forcing sponsors to over-engineer switching studies against regulatory uncertainty.
- Cold Chain Integrity at Last Mile:Temperature excursion risk in outpatient pharmacy dispensing threatens product integrity and substitution eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interchangeable Biosimilars Market |
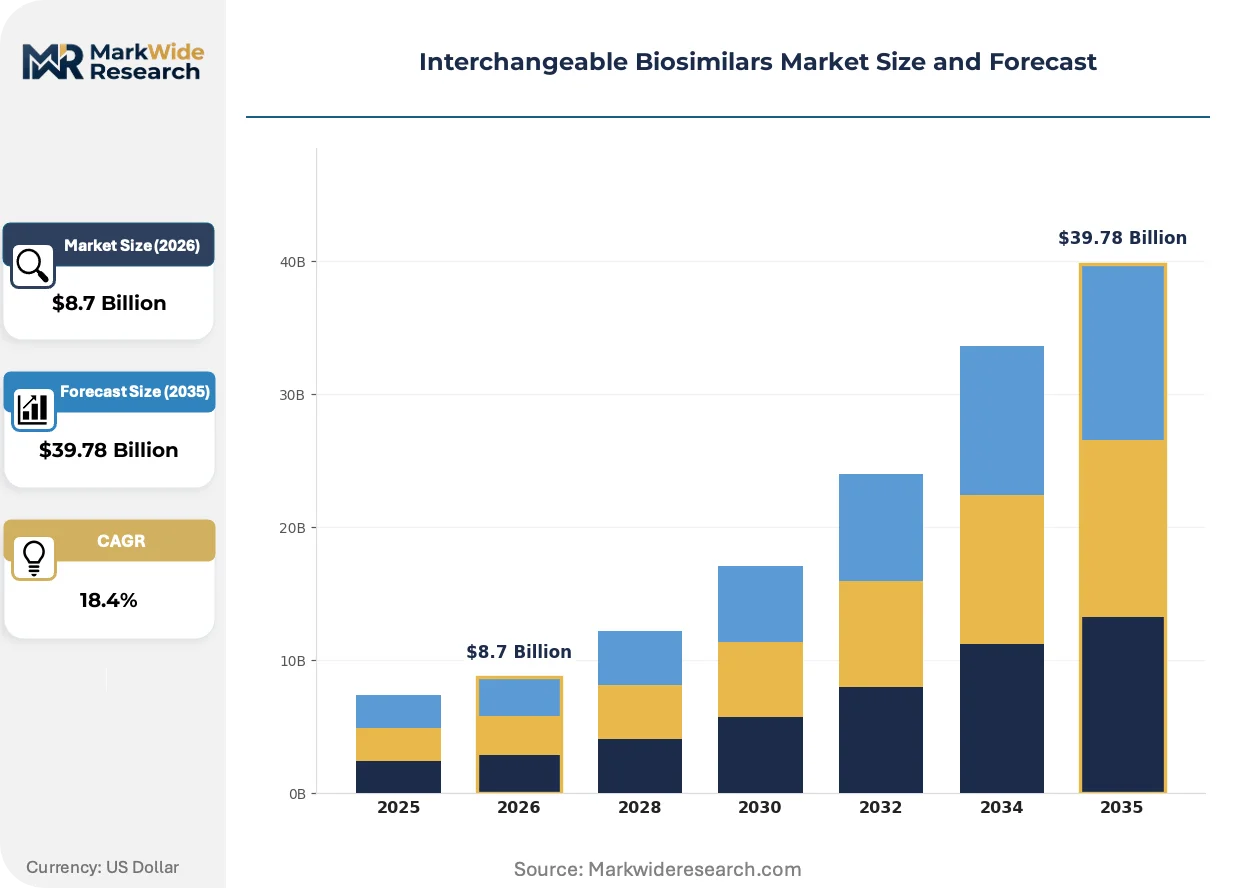
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Erythropoietin, Growth Hormones Therapy Area: Oncology, Rheumatology, Endocrinology, Nephrology Delivery Mode: Subcutaneous, Intravenous, Oral, Intramuscular End User: Hospitals, Clinics, Homecare, Specialty Pharmacies |
| Companies Covered | Sandoz, Amgen, Samsung Bioepis, Pfizer, Biocon Biologics, Celltrion, Boehringer Ingelheim, Coherus Biosciences, Fresenius Kabi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interchangeable Biosimilars Market Shifts & Advancements
Continuous manufacturing platforms and real-time quality analytics are compressing batch-to-batch variability while regulatory agencies converge on unified immunogenicity standards.
Single-use bioreactor systems are unifying upstream and downstream processing into integrated continuous manufacturing trains. Contract development and manufacturing organizations in South Korea and Singapore are adopting these platforms at scale for biosimilar production. This technology is unifying cost structures between originator and biosimilar manufacturers, eroding the traditional capital-intensity gap that protected reference product margins.
The EU Green Deal's pharmaceutical sustainability framework is mandating carbon footprint disclosure across active pharmaceutical ingredient supply chains. European hospital procurement networks are incorporating environmental criteria into tender evaluations alongside price and clinical equivalence. Oncology biosimilars face the steepest compliance burden due to energy-intensive monoclonal antibody production processes and complex international shipping requirements.
Patients with chronic inflammatory conditions are requesting pharmacy-level substitution to reduce clinic visit burden and infusion center exposure risk. Specialty pharmacies in the United States are capturing this preference through home delivery and nurse-supported self-injection training programs. Rheumatology practices in Texas and Florida report the highest patient-initiated switching requests, correlating with higher baseline out-of-pocket exposure in high-deductible health plans.
Interchangeable Biosimilars Market Segmentation
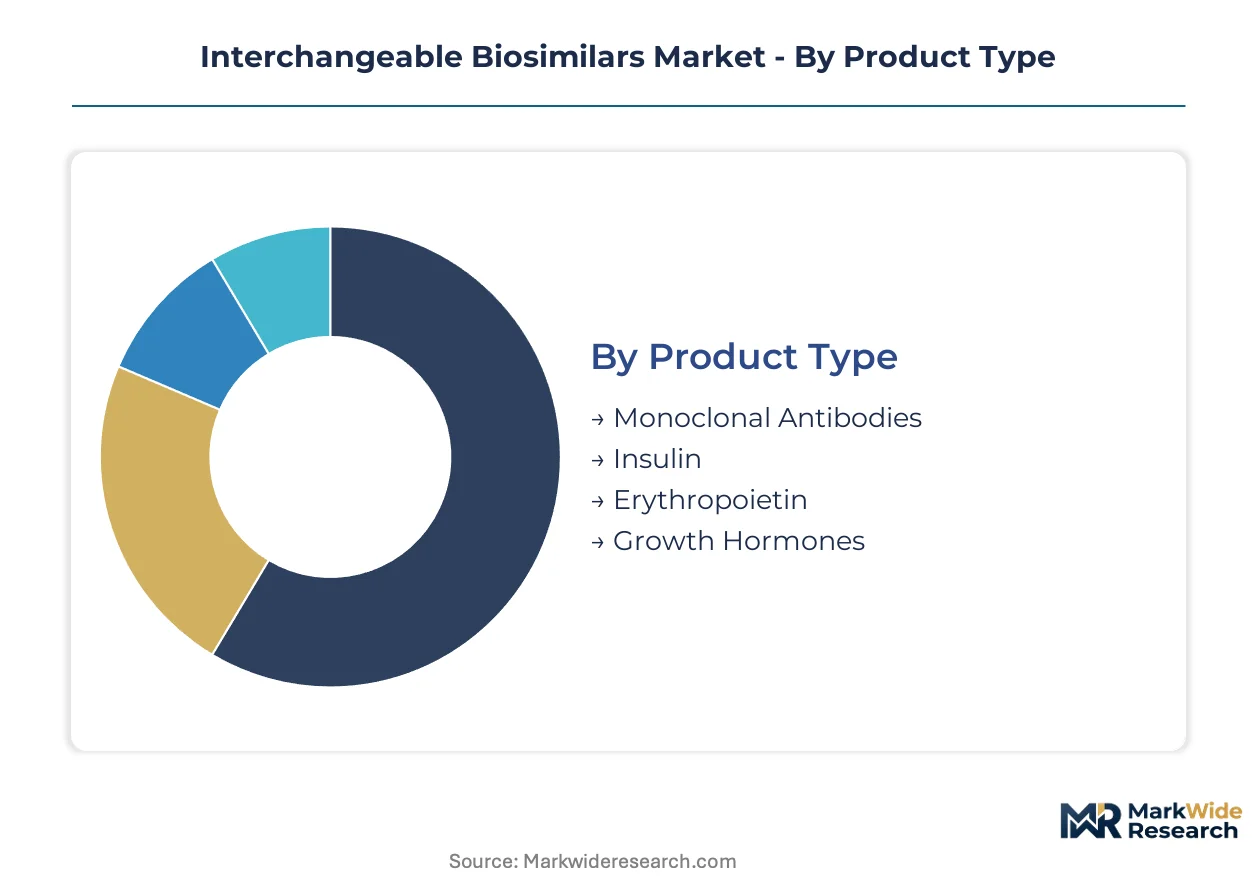
Interchangeable biosimilars demand fragments across molecular complexity, therapeutic application, and care setting. Each segmentation axis reveals distinct margin structures, regulatory burdens, and substitution economics that determine commercial viability.
Product Type:
Molecular architecture dictates manufacturing scale, immunogenicity risk profiles, and interchangeability study design.
- Monoclonal Antibodies:Complex glycosylated proteins manufactured in mammalian cell cultures under stringent conditions. Demand concentrates in US hospital infusion centers where reference product costs exceed $10,000 per treatment cycle, driving payer pressure for automatic substitution. EMA immunogenicity standards and FDA switching study requirements impose the heaviest clinical trial burden on this segment.
- Insulin:Recombinant peptide hormones produced through microbial fermentation with established analytical comparability pathways. German statutory health insurance tendering mechanisms compress pricing floors fastest here, where multiple interchangeable products already compete for formulary placement.
- Erythropoietin:Glycoprotein hormone stimulating red blood cell production, predominantly used in dialysis settings. European procurement networks favor these products due to mature biosimilar competition and well-characterized immunogenicity profiles.
- Growth Hormones:Polypeptide therapies for pediatric endocrine disorders requiring daily administration. US specialty pharmacy dispensing dominates volume capture, with patient adherence programs determining substitution persistence.
Mature deployment sits with Monoclonal Antibodies. Newer deployment is concentrated in Insulin.
Therapy Area:
Clinical indication determines prescriber specialization, patient switching tolerance, and reimbursement tier positioning.
- Oncology:Chemotherapy-supportive and targeted therapies where treatment interruption carries mortality risk. US oncology practices in Texas and Florida report highest patient-initiated switching requests, correlating with high-deductible health plan exposure. FDA interchangeability designation accelerates automatic substitution without oncologist consultation.
- Rheumatology:Chronic inflammatory conditions requiring sustained immunosuppression. Subcutaneous formulation preference among US rheumatology patients opens pharmacy-dispensed volume outside hospital infusion centers, with specialty pharmacies capturing home delivery demand.
- Endocrinology:Diabetes and hormone replacement therapies with established therapeutic drug monitoring protocols. German health insurance funds drive penetration through centralized tendering, compressing reference product net pricing.
- Nephrology:Dialysis-dependent populations with standardized treatment protocols. Hospital-based procurement in the United States favors interchangeables here due to bundled payment incentives under Medicare reimbursement structures.
Volume concentrates in Oncology. Expansion is climbing fastest in Rheumatology.
Delivery Mode:
Route of administration shapes manufacturing complexity, cold chain requirements, and patient self-management capability.
- Subcutaneous:Self-administered injections enabling outpatient dispensing and reduced clinic burden. US patient preference is shifting fastest toward this mode, with specialty pharmacies investing in nurse-supported injection training programs.
- Intravenous:Infusion center administration requiring healthcare professional supervision. US hospitals retain deepest margin pools here, though outpatient migration is eroding volume concentration.
- Oral:Peptide formulations with limited bioavailability, currently marginal in biosimilar development pipelines.
- Intramuscular:Depot injections for sustained hormone release, concentrated in pediatric endocrinology and long-acting contraceptive applications.
Infusion center dependence defines Intravenous deployment. Patient autonomy is driving Subcutaneous expansion.
End User:
Care setting determines procurement authority, substitution policy enforcement, and patient adherence monitoring.
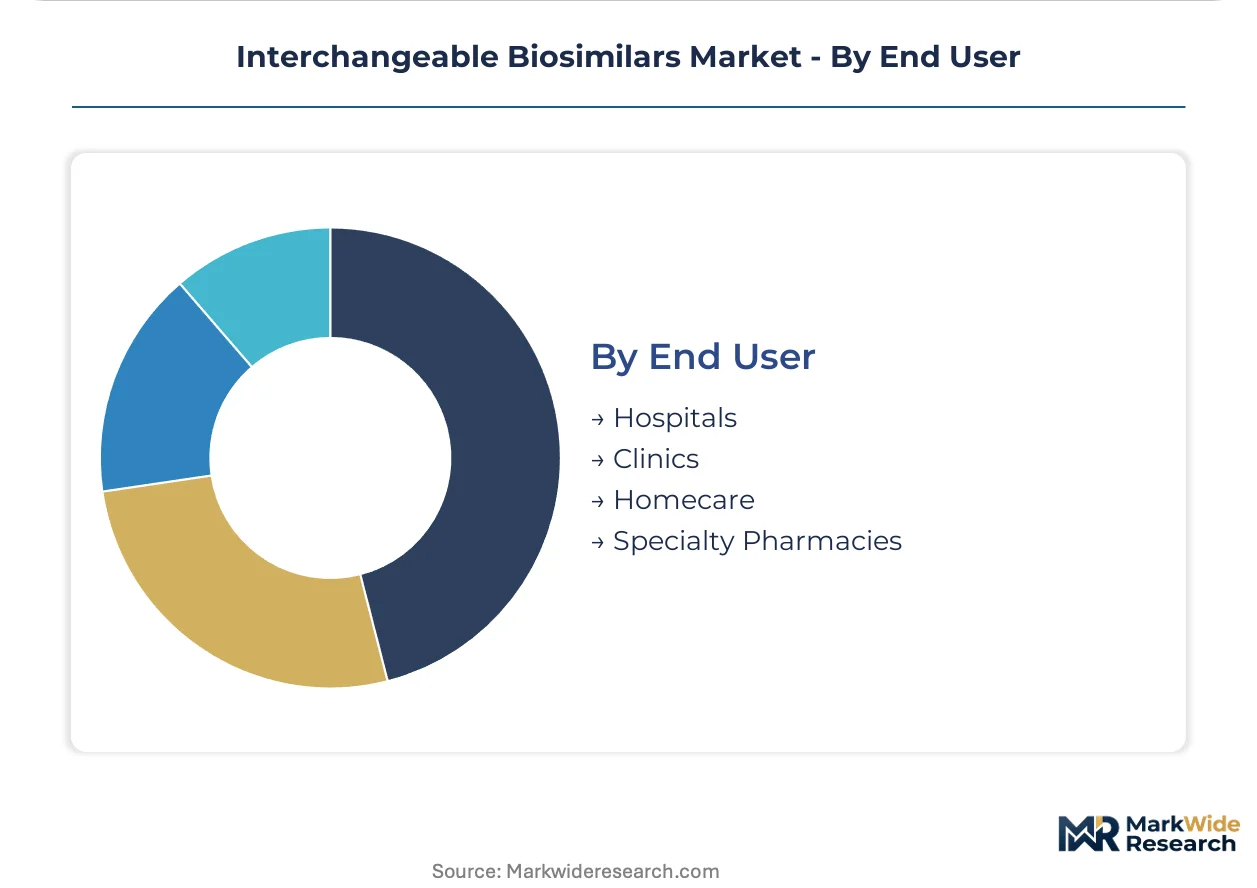
- Hospitals:Centralized pharmacy and therapeutics committees controlling formulary access. US hospital systems expanding interchangeable adoption leverage group purchasing organization contracts to secure preferred tier status.
- Specialty Pharmacies:Limited-distribution networks with direct manufacturer relationships. These entities capture growing US outpatient biosimilar volume through home delivery and adherence data monetization.
- Clinics:Physician-administered settings with buy-and-bill reimbursement. Medicare Part B payment structures influence substitution economics in US oncology and rheumatology clinics.
- Homecare:Nurse-supported administration for patients with mobility limitations. German domiciliary care networks incorporate interchangeable biosimilars into statutory insurance home treatment protocols.
Institutional procurement dominates Hospitals. Direct patient access is expanding fastest through Specialty Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors North American biosimilar development activity, with FDA interchangeability designations accelerating pharmacy substitution policies nationwide.
United States
Hospital formulary expansion and Medicare price negotiation pressure drive demand concentration. FDA interchangeability guidelines enable automatic pharmacy substitution without prescriber intervention. Texas and Florida oncology practices report highest patient-initiated switching requests, correlating with high-deductible health plan exposure.
Germany
Statutory health insurance tendering mechanisms compress reference product pricing floors fastest in Europe. EMA biosimilar pathway harmonization reduces regulatory duplication costs for multi-country market access. The Rhine-Ruhr industrial cluster hosts concentrated biologics manufacturing infrastructure serving centralized procurement networks.
Switzerland
Specialty chemical producers dominate cell culture media and bioreactor equipment supply, creating input concentration vulnerability. Swissmedic maintains stringent biosimilar approval standards aligned with EMA frameworks. Basel anchors European headquarters for legacy biologics manufacturers with captive biosimilar development pipelines.
Japan
PMDA fast-track designation compresses time-to-market for oncology biosimilars addressing unmet need. METI industrial policy supports domestic biologics manufacturing capacity expansion. The Kanto region around Tokyo concentrates regulatory expertise and clinical trial infrastructure for switching studies.
South Korea
Contract development and manufacturing organizations adopt single-use bioreactor platforms at scale for cost-competitive production. MFDS regulatory convergence with FDA immunogenicity standards accelerates export market access. The Songdo biocluster integrates continuous manufacturing technology into integrated processing trains.
Interchangeable Biosimilars Market Competitive Landscape
The competitive structure tilts toward vertically integrated biologics specialists with captive manufacturing networks. Market concentration remains moderate, with originator spin-offs and dedicated biosimilar developers contesting share against diversified pharmaceutical conglomerates. Two strategic archetypes dominate: legacy generics companies leveraging regulatory expertise, and biotech specialists with deep mammalian cell culture capabilities. Capacity expansion and strategic partnerships constitute the primary competitive moves, as developers seek to secure preferred formulary tier status.
Within the vertically integrated tier, Sandoz and Samsung Bioepis occupy distinct positions. Sandoz exemplifies the legacy generics-to-biologics transition archetype, drawing on decades of regulatory navigation experience. Samsung Bioepis anchors the Asia-Pacific specialist model, with its corporate structure reflecting deep specialization in oncology and immunology biosimilars. Boehringer Ingelheim represents the diversified pharmaceutical conglomerate pathway, where biosimilars complement broader biologics portfolios.
| Leading Market Players |
|---|
| Sandoz |
| Amgen |
| Samsung Bioepis |
| Pfizer |
| Biocon Biologics |
| Celltrion |
| Boehringer Ingelheim |
| Coherus Biosciences |
| Fresenius Kabi |
| Others |
Supply & Pricing Matrix
Cell culture media costs originating from German and Swiss specialty chemical producers cascade through monoclonal antibody manufacturing tiers, compressing margins at the contract manufacturing layer while statutory tendering mechanisms in Germany force reference product net pricing downward through centralized procurement.
Pricing Analysis
Value-based pricing anchors on therapeutic equivalence demonstrated through FDA interchangeability designation, with three-tier pricing structure across premium originator, standard biosimilar, and economy interchangeable tiers. Price differentiation rests on switching study certification, EMA approval pathway, and formulary tier placement. Cost compression in the economy tier intensifies because German health insurance funds consolidate volume through competitive tendering. Hospital procurement committees exhibit highest price sensitivity, while specialty pharmacies capturing outpatient volume show greater tolerance for premium positioning.
Supply Chain Analysis
Dual-sourcing requirements from US hospital systems and European procurement networks mandate multi-supplier qualification for cell culture media, bioreactor equipment, and active pharmaceutical ingredients. Manufacturing concentration centers on Germany, Switzerland, and South Korea for upstream bioprocessing inputs. Raw material dependencies include mammalian expression systems, single-use bioreactor bags, and chromatography resins. Single-source vulnerability in German specialty chemical supply creates structural risk for batch continuity. Distribution runs through limited-distribution specialty pharmacy networks and hospital group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive control over mammalian cell line development to secure switching study timelines and defend interchangeability designation timelines.
For Market Incumbents: Anchor formulary position through backward integration into cell line development capabilities, eliminating dependency on external hybridoma engineering talent. Consolidate manufacturing footprint around continuous processing platforms to compress batch-to-batch variability and accelerate FDA immunogenicity study completion. Defend against mid-cap developers by securing preferred tier status through exclusive distribution partnerships with specialty pharmacy networks. For New Entrants and Emerging Players: Enter via subcutaneous formulation development in rheumatology and dermatology, where patient self-administration preference opens pharmacy-dispensed volume outside hospital infusion centers. Target the US South and Southwest regions, where high-deductible health plan exposure drives patient-initiated switching requests. Pursue Japan PMDA fast-track designation as the go-to-market angle, compressing regulatory review timelines for oncology indications. For Investors and Strategic Acquirers: Distressed-cycle entries favor contract development and manufacturing organizations with single-use bioreactor platforms in South Korea and Singapore, where regulatory convergence with FDA standards accelerates export market access. Long-term viability hinges on securing captive cell line expertise and continuous manufacturing technology. Watch for inflection signals in Medicare price negotiation implementation timelines and originator rebate structure transparency.| Strategic Initiative | Industry Significance |
|---|---|
| Switching Study Advancement | FDA interchangeability designation accelerates automatic pharmacy substitution without prescriber intervention. |
| Continuous Manufacturing Scale-Up | Single-use bioreactor integration compresses batch variability and erodes originator cost advantages. |
| Specialty Pharmacy Partnership | Limited-distribution networks capture outpatient volume and patient adherence data monetization. |
| EMA Multi-Country Registration | Harmonized approval pathways reduce regulatory duplication costs across European procurement networks. |
| Subcutaneous Formulation Development | Self-administration preference shifts volume from hospital infusion centers to pharmacy dispensing. |
Research Methodology
Multi-period observation of FDA interchangeability designations, EMA approval timelines, and formulary adoption rates anchored the trend analysis, supplemented by interviews with regulatory affairs leads, formulary directors at US hospital systems, payer access specialists, and bioprocess engineering heads. Secondary validation drew from FDA filings, EMA submission databases, ClinicalTrials.gov switching study records, and hospital procurement databases. Bottom-up volume estimates triangulated against top-down therapeutic category spend analysis.
Input-output matrices modeled demand drivers across molecular complexity, therapeutic application, delivery mode, and care setting segmentation dimensions. CAGRs were derived from regression analysis of historical approval velocity and adoption curve patterns. Forecast inputs incorporated immunogenicity endpoint standardization timelines and payer consolidation trajectories across the projection horizon.
Revisions become necessary when FDA switching study requirements materially expand, originator rebate structures achieve regulatory transparency, or cell culture media supply disruptions propagate through manufacturing networks. Deviation in Medicare price negotiation implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Europe Generic Injectables Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Global Sirolimus Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Etanercept Market
Biosimilars
Imatinib Drug Market