
 Global Optical Genome Mapping Market | 2026-2036
Global Optical Genome Mapping Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Genome Mapping Market Foresight
Software-defined analysis pipelines is shifting how optical genome mapping platforms monetize value, with subscription-based bioinformatics modules now bundled alongside instrument placements. Bionano Genomics leverages its end-to-end platform architecture to anchor recurring revenue streams across clinical and research accounts. Hitachi High-Tech Corporation sustains competitive positioning through precision optics manufacturing scale and established distribution channels in Asia. PerkinElmer differentiates via integrated workflows that bridge optical mapping with complementary cytogenetic and molecular testing portfolios.
Optical genome mapping deploys nanochannel arrays and fluorescence labeling to visualize ultra-long DNA molecules at single-molecule resolution, detecting structural variants and genome architecture without amplification bias. The technology serves primarily to resolve complex genomic rearrangements that short-read sequencing platforms routinely miss in clinical and agricultural research settings. Consumables currently command the deepest margin pools as repeat reagent purchases outpace instrument installation cycles across academic and hospital laboratories. Cancer research applications attract the fastest-growing demand as oncology programs integrate optical mapping into companion diagnostic development and tumor profiling workflows. Single-molecule imaging technology leads in installed base and protocol maturity, though bioinformatics segments are expanding as analytical bottlenecks shift from data generation to interpretation.
FDA oversight of optical mapping-based diagnostic assays shapes clinical adoption timelines and validation requirements for laboratories seeking to offer testing services. EMA's In Vitro Diagnostic Regulation and evolving CE marking pathways for novel genomic technologies influence European market access and commercialization strategies for platform developers. ISO 15189 accreditation standards and CLIA certification requirements in the United States determine which laboratory settings can operationalize optical genome mapping at clinical scale. Stakeholders must monitor how regulatory precedents for structural variant calling accuracy and reporting standards crystallize across jurisdictions to anticipate where commercial infrastructure investments will yield sustainable returns.
Market Dynamics
Software-defined bioinformatics modules are shifting revenue capture from instrument sales to recurring subscription streams, forcing platform vendors to rearchitect commercial models around analytical workflow integration rather than hardware placement alone.
Growth Catalysts
- CLIA certification expansion:United States clinical laboratories are accelerating optical genome mapping validation under CLIA high-complexity testing frameworks, opening reimbursement pathways for constitutional disorder diagnostics.
- Single-molecule imaging resolution advances:Nanochannel array fabrication improvements now enable routine detection of structural variants below 500 base pairs, expanding addressable mutation classes in oncology workflows.
- Companion diagnostic pipelines:Pharmaceutical developers are embedding optical mapping into tumor profiling protocols for targeted therapy development, creating pull-through demand for platform standardization.
Market Restraints
- Fluorophore supply concentration:Specialized fluorescent label chemistries rely on captive production at three Asian chemical manufacturers, exposing reagent cost volatility to regional logistics disruptions.
- FDA premarket review timelines:De novo classification pathways for novel structural variant calling algorithms extend validation periods by 18-24 months versus established sequencing modalities.
- Short-read sequencing substitution:Illumina's long-read chemistry extensions and Pacific Biosciences' HiFi platforms capture overlapping structural variant use cases at lower per-sample cost points.
Strategic Opportunities
- India's genomic medicine program:The country's PLI scheme for medical device manufacturing offers tariff advantages for localized optical mapping instrument assembly serving South Asian research networks.
- Agricultural genomics convergence:Crop breeding programs in Brazil and Australia are adopting optical mapping for complex trait locus resolution, creating non-clinical demand diversification.
- ISO 15189 harmonization:Emerging mutual recognition agreements between European and Asia-Pacific accreditation bodies are compressing multi-jurisdictional laboratory certification timelines.
Industry Challenges
- Bioinformatics specialist scarcity:Clinical laboratories report 14-month average hiring timelines for computational biologists capable of optical mapping pipeline validation and regulatory documentation.
- Legacy cytogenetic workflow integration:Hospital systems face capital allocation conflicts between optical mapping infrastructure and existing karyotyping/FISH equipment with remaining depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Genome Mapping Market |
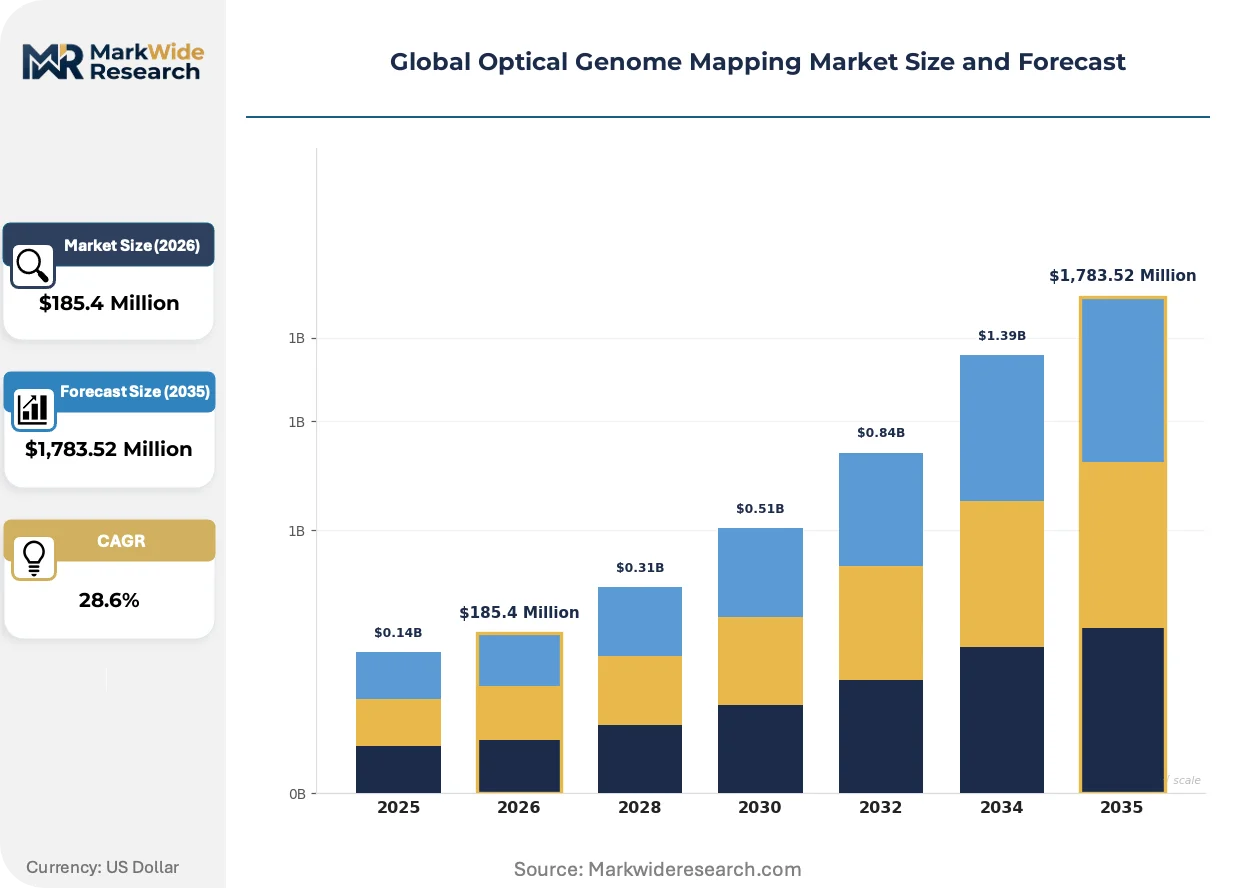
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,783.52 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Software, Consumables, Services End User: Academic Institutions, Research Laboratories, Hospitals, Diagnostic Centers Application: Cancer Research, Genomic Analysis, Rare Disease Detection, Crop Improvement Technology: Single-Molecule Imaging, Amplification Techniques, High-Throughput Sequencing, Bioinformatics |
| Companies Covered | Bionano Genomics, Hitachi High-Tech Corporation, Nucleome Informatics Private Limited, Praxis Genomics, LLC, SourceBio International Limited, MedGenome, PerkinElmer, Genohub Inc., OpGen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Genome Mapping Market Shifts & Advancements
Three intersecting developments are compressing the gap between research-grade optical mapping and clinical diagnostic deployment: instrumentation miniaturization, cloud-native analytical architectures, and reimbursement code consolidation for structural variant testing.
Deep learning-based variant calling algorithms are rewriting how optical mapping platforms handle signal interpretation, replacing rule-based image analysis with neural networks trained on synthetic molecule libraries. Academic medical centers in Germany and Japan are piloting these tools for constitutional disorder screening, compressing analytical turnaround from days to hours while reducing false positive structural variant calls by half. This capability is enabling same-result reporting workflows that match the operational cadence of established cytogenetic laboratories.
EMA's In Vitro Diagnostic Regulation performance criteria for structural variant detection accuracy are forcing platform developers to standardize reference material sets and inter-laboratory concordance protocols. Manufacturers must now demonstrate reproducible variant calling across multiple independent clinical sites before CE marking authorization, extending development timelines but elevating barrier to entry for speculative market entrants. German reference laboratories are leading compliance documentation, creating template validation packages adopted across Benelux and Nordic markets.
Hospital procurement committees are unbundling instrument acquisition from multi-year reagent supply agreements, shifting toward annual competitive bidding for consumables based on projected sample volumes. This pattern is most pronounced in United States academic medical centers, where centralized purchasing offices now separate capital equipment decisions from operational chemistry contracts. Vendors respond with modular pricing architectures that decouple hardware depreciation schedules from per-run reagent commitments.
Global Optical Genome Mapping Market Segmentation
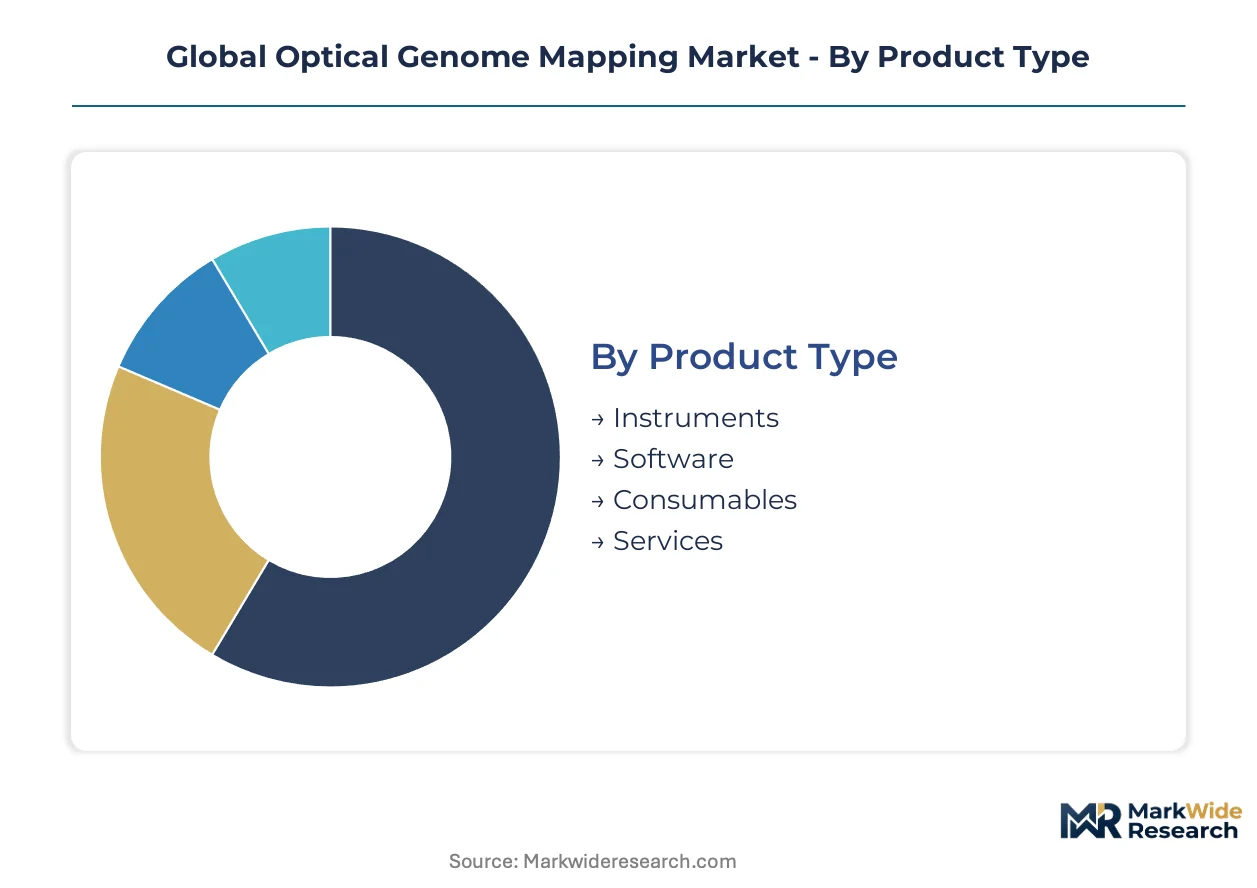
Optical genome mapping market segmentation reveals distinct capital requirements across product tiers, with infrastructure-heavy segments demanding multi-year depreciation schedules while software and services categories enable faster margin realization. Understanding these structural differences guides vendor portfolio allocation and laboratory procurement strategies.
Product Type:
Instruments require the steepest upfront capital commitment, with nanochannel array fabrication and fluorescence detection systems commanding seven-figure placement values and extended validation timelines.
- Instruments:Nanochannel array platforms and high-resolution imaging systems integrate precision optics with fluidics automation. Academic medical centers in the United States absorb the majority of new placements as CLIA-certified laboratories build dedicated structural variant detection infrastructure.
- Consumables:Fluorescent labels, DNA labeling kits, and nanochannel flow cells generate recurring revenue streams with shorter purchase cycles than hardware. Hospital laboratories in Germany and Japan concentrate demand as ISO 15189-accredited sites scale routine constitutional disorder testing.
- Software:Variant calling algorithms and visualization platforms compress analytical turnaround for high-volume laboratories.
- Services:Installation validation, training programs, and bioinformatics support reduce operational risk for first-time adopters.
Consumables absorb the bulk of installed capacity; software is expanding most quickly as laboratories prioritize analytical workflow integration over hardware expansion.
End User:
Customer type segmentation reflects divergent purchasing authority, with hospital procurement committees managing capital allocation differently than principal investigator-driven academic acquisitions.
- Academic Institutions:University genomics cores and medical school departments drive early technology adoption through grant-funded instrument purchases. Research laboratories at Stanford University and the Broad Institute anchor North American demand for single-molecule imaging platforms.
- Hospitals:Clinical laboratories within integrated health systems pursue CLIA certification for optical mapping-based diagnostics. Academic medical centers in Boston and San Francisco concentrate validation investment as reimbursement pathways for structural variant testing crystallize.
- Research Laboratories:Government institutes and contract research organizations scale sample throughput for pharmaceutical partnership programs.
- Diagnostic Centers:Independent reference laboratories build specialized structural variant testing menus to differentiate from hospital-affiliated competitors.
Hospitals command the largest committed capital; diagnostic centers are climbing the fastest as outsourced testing demand accelerates.
Application:
Use-case segmentation tracks how optical mapping resolves genomic architectures that confound conventional sequencing across clinical and agricultural domains.
- Cancer Research:Tumor profiling applications detect complex rearrangements and extrachromosomal DNA structures relevant to therapeutic resistance. Oncology programs at MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center integrate optical mapping into companion diagnostic development pipelines.
- Rare Disease Detection:Constitutional disorder diagnostics resolve pathogenic structural variants in pediatric and undiagnosed patient populations. Clinical laboratories in the United Kingdom and Netherlands concentrate adoption as national genomic medicine programs expand reimbursement coverage.
- Genomic Analysis:Population-scale studies and basic research applications leverage ultra-long molecule visualization for genome assembly improvement.
- Crop Improvement:Agricultural biotechnology programs in Australia and Brazil adopt optical mapping for complex trait locus resolution in polyploid crop species.
Cancer research anchors current installed base; crop improvement is gaining share fastest as non-clinical demand diversifies revenue exposure.
Technology:
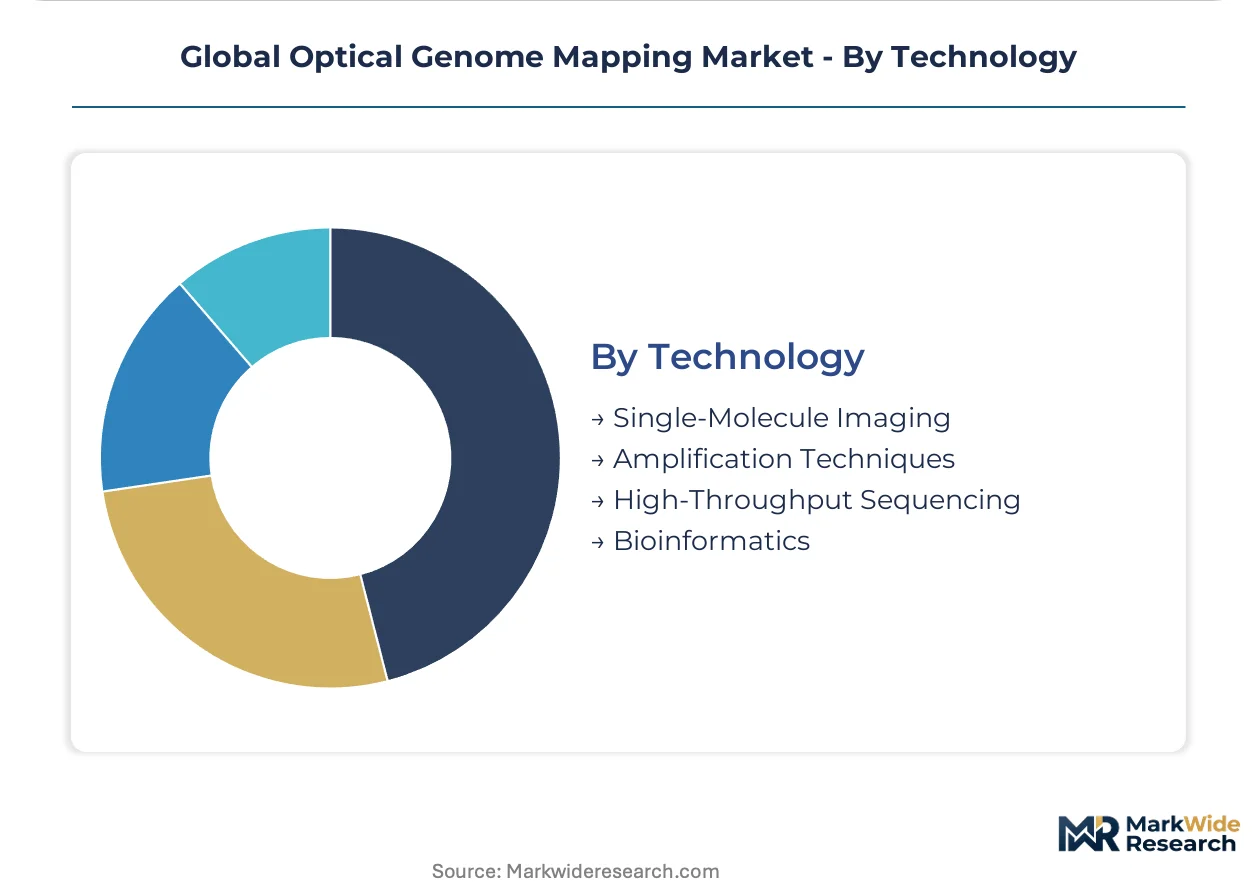
Technical segmentation distinguishes mature imaging modalities from emerging analytical layers that determine platform differentiation.
- Single-Molecule Imaging:Nanochannel array visualization of individually stretched DNA molecules enables direct structural variant detection without amplification bias. This modality dominates installed base and protocol maturity across Bionano Genomics platform deployments in the United States and European reference laboratories.
- Bioinformatics:Deep learning-based variant calling and cloud-native analytical architectures compress interpretation bottlenecks. German academic medical centers and Japanese national institutes pilot neural network approaches for same-result reporting workflows.
- Amplification Techniques:Targeted enrichment methods extend detection sensitivity for specific variant classes.
- High-Throughput Sequencing:Complementary short-read and long-read integration addresses hybrid analytical workflows.
Single-molecule imaging retains the deepest operational footprint; bioinformatics is expanding most steeply as analytical bottlenecks shift from data generation to interpretation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors clinical optical genome mapping adoption, with Massachusetts General Hospital and the Broad Institute driving platform validation for constitutional disorder diagnostics.
United States
FDA premarket review pathways for structural variant calling algorithms shape commercialization timelines for platform developers. CLIA high-complexity certification expansion accelerates laboratory adoption across academic medical centers. The San Francisco Bay Area concentrates precision medicine infrastructure investment as Stanford Medicine and UCSF Medical Center build dedicated optical mapping workflows.
Germany
EMA In Vitro Diagnostic Regulation performance criteria for structural variant detection accuracy force standardized reference material protocols. ISO 15189-accredited reference laboratories in Heidelberg and Berlin lead compliance documentation templates adopted across Benelux markets. The country's genomic medicine network concentrates validation investment in Baden-Württemberg and Bavaria.
Japan
PMDA consultation frameworks for novel genomic technologies influence clinical trial design for diagnostic assay developers. METI funding for single-molecule imaging infrastructure supports national institute adoption in Tsukuba and Kobe biomedical clusters. Osaka-based pharmaceutical partnerships create pull-through demand for tumor profiling applications.
India
PLI scheme tariff advantages for medical device manufacturing attract localized instrument assembly investment. CDSCO regulatory harmonization with ICH guidelines compresses diagnostic assay approval timelines for multinational platform vendors. Bangalore and Hyderabad research networks drive consumables demand through contract research organization scale-up.
United Kingdom
NHS Genomic Medicine Service reimbursement expansion for rare disease diagnostics accelerates hospital laboratory adoption. MHRA recognition of CE-marked optical mapping platforms streamlines procurement for NHS Trusts. The Cambridge-Oxford-London triangle concentrates academic and clinical validation investment for constitutional disorder screening.
Global Optical Genome Mapping Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the optical genome mapping value chain. The market structure concentrates around integrated platform vendors with captive nanochannel fabrication capabilities and specialized bioinformatics boutiques with cloud-native analytical architectures. Three archetypes dominate: end-to-end system integrators, consumables-focused reagent suppliers, and software-defined analytics providers. Strategic moves center on multi-year reagent supply agreement restructuring and bioinformatics module subscription conversion.
Within the integrated platform tier, Bionano Genomics represents the nanochannel array instrumentation archetype, while Hitachi High-Tech Corporation exemplifies precision optics manufacturing scale. PerkinElmer occupies a position bridging optical mapping with complementary cytogenetic testing portfolios. These three anchors illustrate how vendor strategies diverge between hardware-centric recurring revenue capture and workflow integration plays.
| Leading Market Players |
|---|
| Bionano Genomics |
| Hitachi High-Tech Corporation |
| Nucleome Informatics Private Limited |
| Praxis Genomics, LLC |
| SourceBio International Limited |
| MedGenome |
| PerkinElmer |
| Genohub Inc. |
| OpGen |
| Others |
Supply & Pricing Matrix
Academic medical center procurement committees in the United States negotiate multi-year reagent supply agreements alongside instrument placements, embedding consumables pricing into capital depreciation schedules that span seven-figure hardware investments. This buyer concentration enables vendors to bundle subscription-based bioinformatics modules with nanochannel array platforms, shifting revenue capture from transactional instrument sales toward recurring analytical workflow commitments.
Pricing Analysis
Throughput-based pricing anchors optical genome mapping commercial models, with per-sample rates scaling according to CLIA certification tier and ISO 15189 accreditation status. Premium-mid-economy pricing differentiation separates validated clinical diagnostics from research-grade reagents, while hospital laboratories exhibit highest price sensitivity due to capital allocation conflicts with legacy cytogenetic equipment. Cost compression in consumables tiers is intensifying as procurement offices unbundle hardware from chemistry contracts and move toward annual competitive bidding based on projected sample volumes.
Supply Chain Analysis
Specialized fluorescent label chemistries draw from concentrated manufacturing expertise in Japan, South Korea, and Taiwan, where precision optics fabrication and nanochannel array production anchor upstream capacity. Fluorophore synthesis, precision glass etching, and high-purity polymer substrates feed into instrument assembly and consumables production. Single-source vulnerability in specialized fluorescent dye supply exposes reagent cost volatility to regional logistics disruptions. Distribution runs through established life sciences distribution channels serving academic medical centers and reference laboratories across North America, Europe, and Asia-Pacific.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical genome mapping is consolidating around integrated platform vendors with captive nanochannel fabrication capabilities, as FDA premarket review timelines and EMA In Vitro Diagnostic Regulation compliance costs force speculative entrants toward exit or acquisition.
For Market Incumbents: Extend bioinformatics subscription conversion to capture recurring revenue beyond hardware replacement cycles, while deepening backward integration into precision optics manufacturing to defend margin position against Pacific Biosciences' HiFi platform substitution. Prioritize CLIA-certified laboratory partnerships in Boston and San Francisco corridors to anchor reference site networks before reimbursement code consolidation crystallizes. For New Entrants and Emerging Players: Begin with cloud-native analytical architectures targeting diagnostic centers in India and Brazil, where PLI scheme tariff advantages and agricultural genomics demand create white-space penetration opportunities. Agricultural biotechnology programs in Australia offer the most penetrable non-clinical segment, with crop breeding workflows lacking established optical mapping infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor asset-light bioinformatics boutiques with neural network variant calling pipelines in Germany and Japan, where EMA compliance documentation investments have already absorbed regulatory validation costs. Watch for FDA de novo classification pathway precedents for structural variant calling algorithms as the inflection signal indicating sustainable clinical adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Certification Expansion | Opens reimbursement pathways for constitutional disorder diagnostics at academic medical centers in Massachusetts and California. |
| Backward Integration into Fluorophore Manufacturing | Reduces reagent cost volatility exposure from Asian chemical supply concentration. |
| Cloud-Native Bioinformatics Launch | Compresses analytical turnaround for high-volume laboratories in German reference networks. |
| Agricultural Genomics Partnership | Diversifies revenue exposure through crop breeding programs in Brazil and Australia. |
| EMA Compliance Documentation Investment | Creates template validation packages adopted across Benelux and Nordic markets. |
Research Methodology
SEC filings, FDA 510(k) and de novo submission databases, and EMA In Vitro Diagnostic Regulation guidance documents formed the secondary backbone, cross-referenced against primary interviews with CLIA laboratory directors, biomedical engineers at academic medical centers, and procurement managers at integrated health systems. Bottom-up and top-down triangulation validated instrument placement volumes against consumables purchasing patterns and bioinformatics subscription conversion rates reported across vendor disclosures and hospital procurement databases.
Bottom-up modeling aggregated segment-level demand across product type, end user, application, and technology dimensions, while top-down approaches cross-checked aggregate market expansion against precision medicine infrastructure investment trends and genomic medicine program budget allocations. CAGRs were derived from fitted growth curves across the projection horizon, with oncology workflow integration rates and rare disease diagnostic reimbursement expansion serving as primary demand elasticity inputs.
Regulatory approval timeline delays, fluorophore supply disruptions, and short-read sequencing platform substitution are the dominant revision risks that could compress addressable market expansion or accelerate vendor consolidation. Forecasts reflect assumptions about CLIA certification expansion trajectories and EMA mutual recognition agreement harmonization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Japan Next Generation Sequencing Market
Genomics
Mitochondrial DNA Market
Genomics
Animal Genetics Market
Genomics
Global Gene Expression Market
Genomics
Genetic Analysis Services Market
Genomics
SNP Genotyping Market
Genomics
US Genetic Testing Market
Genomics
UAE Genetic Testing Market
Genomics
NGS Automation Market
Genomics
Forensic Genomics Market
Genomics
APO E Gene Test Kit Market
Genomics
North America Whole Exome Sequencing Market
Genomics
Europe Digital PCR Market
Genomics
Global Metagenomics Market
Genomics
Global Pharmacogenomics Market
Genomics
Reproductive Genetics Market