
 Europe Biosimilars Market | 2026-2036
Europe Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biosimilars Market Analytics
Hospital procurement consolidation across Western Europe is hardening price discipline for off-patent biologics. Sandoz leverages its established European manufacturing footprint to sustain volume leadership in oncology biosimilars. Pfizer Inc. anchors its position through hospital-centric distribution agreements in France and Italy. Celltrion, Inc. competes aggressively on manufacturing scale for monoclonal antibody copies.
Biosimilars are recombinant protein therapeutics demonstrating equivalent safety, purity, and potency to approved reference biologics through analytical and clinical comparability studies; they require living cell culture systems and stringent post-translational modification control to ensure batch-to-batch consistency for chronic disease management. Monoclonal antibodies dominate current revenue pools due to blockbuster patent expirations in oncology and autoimmune disorders, while insulin biosimilars face margin compression from reference product pricing defenses. Subcutaneous delivery modes are capturing expanded homecare volumes as patient self-administration protocols mature across European reimbursement frameworks.
EMA centralized marketing authorization under the EU pharmaceutical framework governs biosimilar approval pathways, while national health technology assessment bodies in Germany, France, and the United Kingdom determine regional reimbursement and tender access conditions. REACH and EU GMP standards enforce manufacturing quality benchmarks that shape facility investment requirements and supplier qualification timelines. Stakeholders must monitor evolving interchangeability designations and real-world evidence mandates that will determine competitive positioning in tender-driven European markets.
Market Dynamics
Hospital procurement coalitions across Western Europe are consolidating purchasing power into fewer, larger tender vehicles, compressing margins for off-patent biologics while accelerating formulary adoption of lower-cost alternatives.
Growth Catalysts
- EMA Centralized Pathway:The EU's single marketing authorization enables simultaneous market entry across member states, eliminating redundant national filings and compressing time-to-revenue for biosimilar developers.
- Homecare Subcutaneous Protocols:Patient self-administration frameworks in France and Germany are shifting chronic disease management from infusion centers to residential settings, expanding addressable patient populations.
- Patent Cliff Concentration:Blockbuster monoclonal antibody expirations in oncology and autoimmune disorders are creating immediate substitution opportunities within existing treatment pathways.
Market Restraints
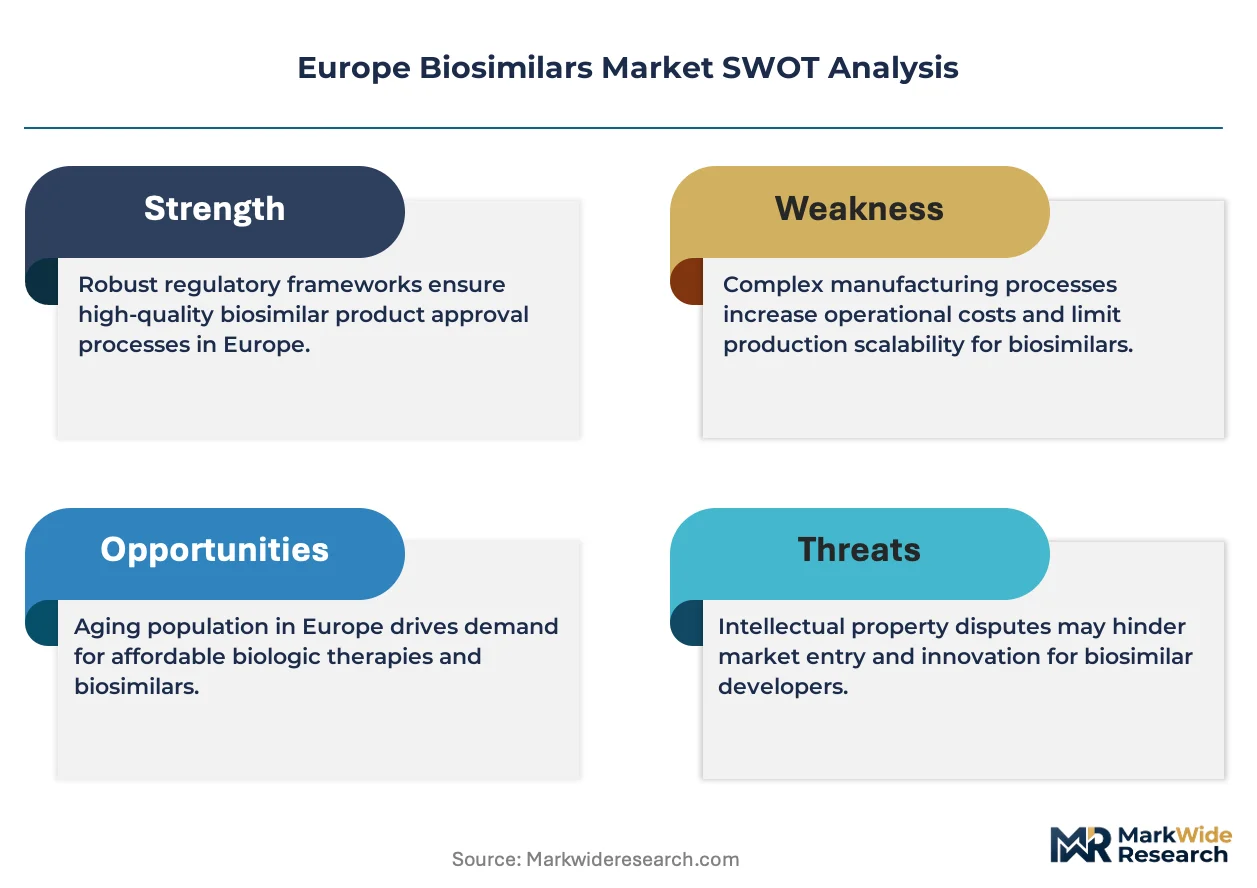
- Manufacturing Complexity:Living cell culture systems require stringent post-translational modification control, constraining batch-to-batch consistency and limiting qualified supplier pools.
- Reference Product Defense:Originators deploy loyalty rebates and indication expansion strategies that erode biosimilar net pricing power in tender negotiations.
- Interchangeability Uncertainty:Absence of formal EMA interchangeability designations creates physician hesitation and pharmacy-level substitution barriers in Germany and Italy.
Strategic Opportunities
- Eastern European Expansion:Poland, Romania, and Hungary present underpenetrated hospital segments with evolving reimbursement frameworks and lower reference product loyalty.
- Real-World Evidence Mandates:Post-market pharmacovigilance requirements under EU pharmaceutical law create competitive differentiation for sponsors with robust patient registry infrastructure.
- Bioconjugate Convergence:Biosimilar developers combining antibody platforms with linker-payload technologies are positioning for next-wave oncology opportunities.
Industry Challenges
- Analytical Characterization Expertise:Shortages of mass spectrometry and bioassay specialists delay comparability study completion and regulatory submission timelines.
- Cold Chain Reconfiguration:Temperature-controlled distribution networks require substantial capital redeployment as homecare volumes shift last-mile logistics away from hospital pharmacies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biosimilars Market |
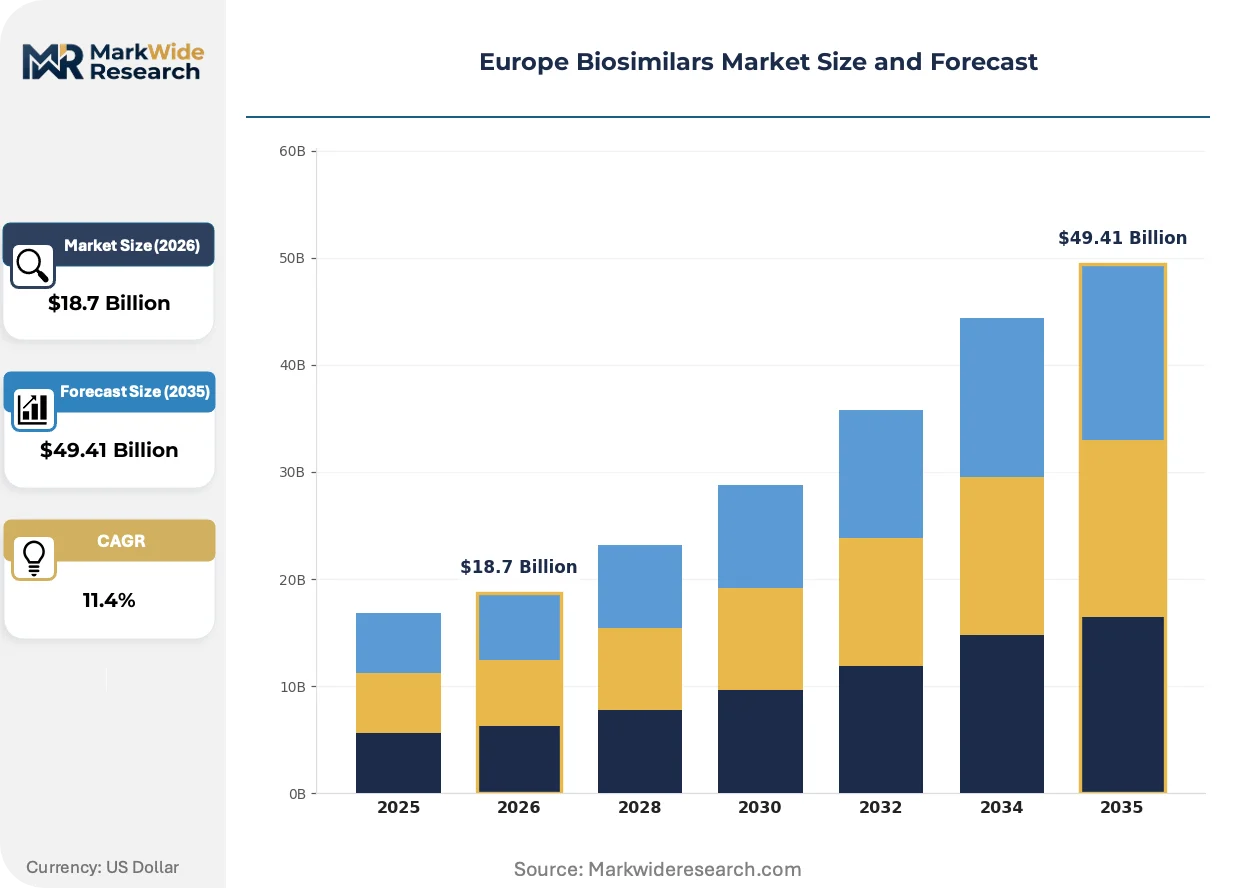
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Erythropoietin, Growth Hormones Therapy Area: Oncology, Diabetes, Neurology, Autoimmune Disorders End User: Hospitals, Clinics, Homecare, Research Institutions Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral |
| Companies Covered | Sandoz, Pfizer Inc., Amgen Inc., Celltrion, Inc., Biogen Inc., Fresenius Kabi, Samsung Bioepis Co., Ltd., Biocon Biologics Inc., Viatris, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biosimilars Market Evolving Landscape
Continuous manufacturing platforms and digital batch release systems are displacing traditional fed-batch processes, enabling real-time quality assurance while reducing facility footprint requirements for European biosimilar production.
Single-use bioreactor systems are integrating perfusion cell culture technologies with automated process analytical technology. Mid-scale European manufacturers are adopting these platforms to achieve flexible batch sizing without stainless steel infrastructure. The technology is integrating quality-by-design principles directly into production workflows, compressing validation timelines and enabling faster post-approval manufacturing changes.
EU GMP Annex 1 revisions governing sterile manufacturing are mandating enhanced contamination control strategies and barrier isolation systems. Facility retrofit costs are diverting capital from expansion projects toward compliance upgrades. Oncology injectable biosimilars face the steepest compliance burden, with German and French regulators conducting heightened inspection frequency at legacy manufacturing sites.
Hospital buying groups are consolidating oncology and immunology tenders into multi-year framework agreements with price-volume mechanisms. France's UNIH purchasing consortium and Germany's regional hospital alliances are displacing single-product negotiations. This concentration is most visible in hematology-oncology segments, where reference product originators face explicit market share erosion clauses in tender specifications.
Europe Biosimilars Market Segmentation
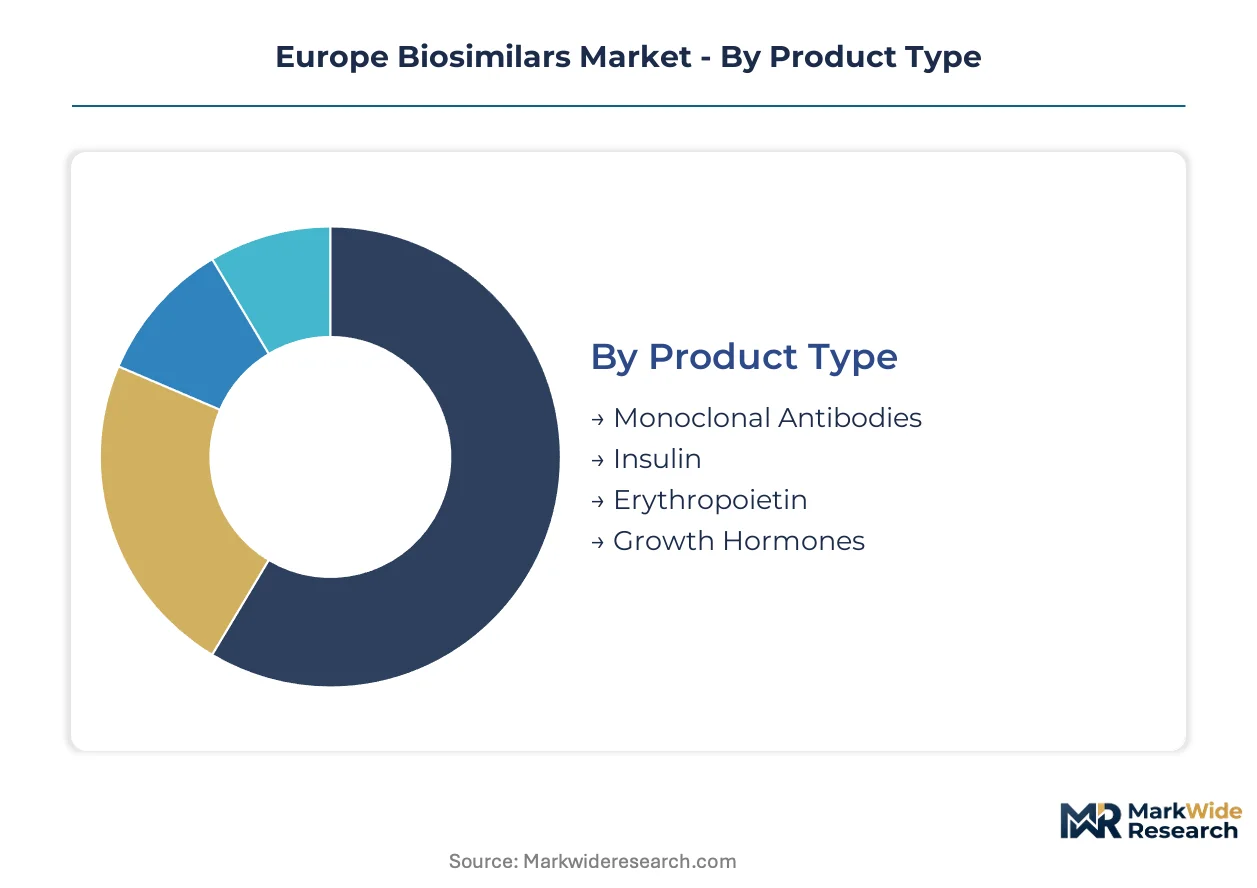
Segmentation in the Europe Biosimilars Market reveals distinct capital requirements, regulatory pathways, and tender dynamics across product categories. Each dimension shapes manufacturing investment priorities and market access strategies for sponsors competing within national reimbursement frameworks.
Product Type:
Capital intensity varies sharply across molecular classes, with monoclonal antibodies demanding the largest upstream bioreactor investments and analytical characterization spend.
- Monoclonal Antibodies:Complex glycoprotein therapeutics requiring mammalian cell culture systems and mass spectrometry comparability packages. Hospital oncology tenders in Germany and France concentrate demand for rituximab and trastuzumab copies, though originator loyalty rebates compress net realized prices.
- Insulin:Recombinant peptide hormones produced through microbial fermentation with established analytical release specifications. Pricing pressure from reference product defense strategies in Italy and Spain limits margin expansion despite volume growth in retail pharmacy channels.
- Erythropoietin:Renal dialysis centers in the United Kingdom drive procurement consolidation for this mature segment.
- Growth Hormones:Pediatric endocrinology clinics in France and the Netherlands represent the primary addressable patient population.
Monoclonal antibodies absorb the bulk of installed capacity; insulin is expanding most quickly through retail channel expansion.
Therapy Area:
Reimbursement generosity and tender frequency diverge across therapeutic categories, with oncology commanding premium pricing and fastest formulary adoption.
- Oncology:Hematology-oncology departments in French and German university hospitals anchor demand for biosimilar substitution within existing chemotherapy protocols. EMA centralized approvals for oncology indications carry the highest evidence requirements, extending development timelines but securing broad cross-border market access upon authorization.
- Autoimmune Disorders:Rheumatology and gastroenterology practices in the United Kingdom and the Netherlands are expanding biosimilar penetration for TNF-alpha inhibitors. Patient switching hesitancy and absence of formal interchangeability designations in Germany create pharmacy-level substitution barriers.
- Diabetes:Primary care prescribing in Spain and Poland concentrates volume for insulin analog copies.
- Neurology:Multiple sclerosis treatment centers in Scandinavia represent a concentrated but lower-volume opportunity.
Oncology captures the steepest pricing tier; autoimmune disorders are gaining share fastest through expanded indication approvals.
End User:
Procurement centralization and cold chain requirements create distinct operational profiles across patient care settings.
- Hospitals:Regional purchasing coalitions in Germany and France negotiate multi-year framework agreements with explicit market share erosion clauses for reference products. Infusion center infrastructure and pharmacist substitution authority accelerate intravenous biosimilar uptake in this channel.
- Homecare:Subcutaneous self-administration protocols in France and Belgium are shifting chronic disease management from clinical settings to residential environments, expanding addressable patient populations and requiring last-mile cold chain reconfiguration.
- Clinics:Specialist outpatient facilities in Italy and Spain concentrate rheumatology and endocrinology prescribing.
- Research Institutions:Academic medical centers in the Netherlands and Denmark drive pharmacovigilance data generation and real-world evidence collection.
Hospitals absorb the bulk of installed capacity; homecare is expanding most quickly through reimbursement framework evolution.
Delivery Mode:
Route of administration determines manufacturing fill-finish investment, cold chain complexity, and patient training requirements.
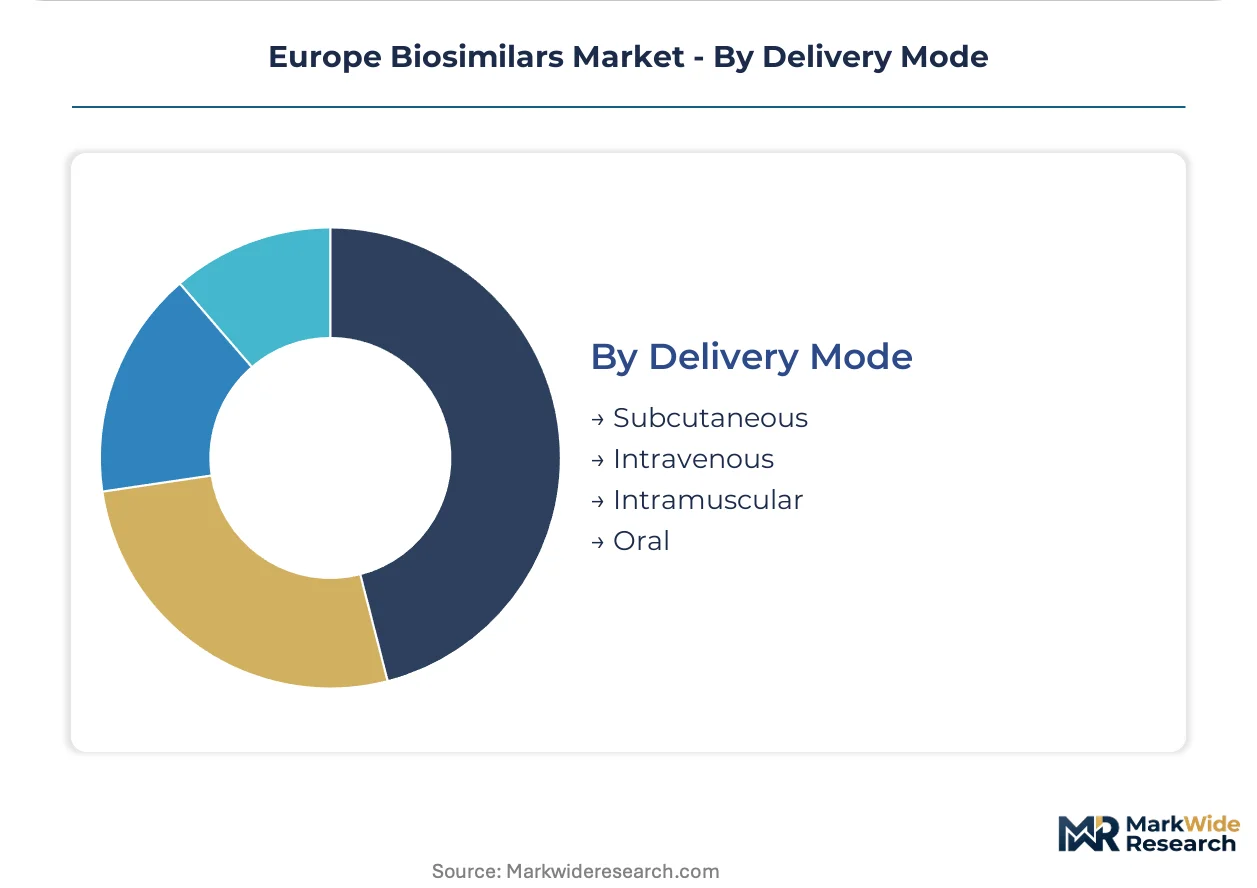
- Intravenous:Hospital-administered infusion therapies for oncology and autoimmune indications require lyophilized or liquid vial presentation with extended beyond-use dating. German hospital pharmacies maintain strict substitution protocols for IV biologics, creating formulary committee gatekeeping.
- Subcutaneous:Prefilled syringe and auto-injector devices for insulin and monoclonal antibodies enable patient self-administration. French reimbursement frameworks explicitly incentivize homecare subcutaneous protocols through reduced co-payment structures.
- Intramuscular:Growth hormone delivery in pediatric populations concentrates in specialty clinic settings.
- Oral:Limited current applicability for biosimilars given protein degradation in the gastrointestinal tract; emerging peptide formulation research in Swiss and Belgian academic centers.
Intravenous delivery absorbs the bulk of installed capacity; subcutaneous is expanding most quickly through device innovation and homecare protocol maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement coalitions in Germany, France, and the United Kingdom concentrate biosimilar demand within Western Europe's reimbursement frameworks. EMA centralized approvals enable cross-border market entry, while national tender mechanisms determine pricing and volume allocation.
Germany
Regional hospital alliances negotiate multi-year framework agreements with explicit market share erosion clauses for reference products. The Federal Joint Committee (G-BA) governs reimbursement decisions through health technology assessment protocols. Manufacturing clusters in Bavaria and Baden-Württemberg host sterile fill-finish operations serving oncology injectable demand.
France
UNIH purchasing consortium consolidates oncology and immunology tenders into price-volume mechanisms for university hospitals. HAS evaluates clinical benefit ratings that influence reimbursement generosity across therapeutic categories. The Paris-Saclay cluster anchors pharmacovigilance infrastructure for real-world evidence generation.
United Kingdom
NHS England's regional procurement hubs drive formulary adoption through national framework agreements for rituximab and trastuzumab copies. NICE technology appraisals determine cost-effectiveness thresholds for biosimilar substitution. The Golden Triangle biotech corridor between London, Oxford, and Cambridge concentrates analytical characterization expertise.
Italy
Regional health authorities in Lombardy and Emilia-Romagna administer tender processes for hospital-administered biologics. AIFA regulates biosimilar interchangeability protocols that create pharmacy-level substitution barriers. The Milan-Turin pharmaceutical corridor hosts distribution networks for subcutaneous self-administration devices.
Poland
Evolving reimbursement frameworks in Warsaw and Krakow hospital segments present underpenetrated opportunities with lower reference product loyalty. The national health fund negotiates volume-based contracts for renal dialysis and oncology indications. The Łódź special economic zone attracts fill-finish investment serving Eastern European distribution.
Europe Biosimilars Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue manufacturing scale and Eastern European geographic expansion. The vendor base stratifies across three maturity tiers: legacy generics divisions with European manufacturing footprints, Korean bioconjugate specialists, and Indian fermentation-scale players. Three archetypes dominate: integrated pharmaceutical conglomerates, dedicated biosimilar pure-plays, and contract development organizations extending into commercial supply. Competitive positioning hinges on hospital-centric distribution agreements and cold chain infrastructure rather than molecule-level differentiation alone.
Among Swiss-based integrated producers, Sandoz anchors volume leadership through oncology manufacturing scale. Pfizer Inc. exemplifies hospital-centric distribution strategy through French and Italian tender positioning. Celltrion, Inc. represents Korean manufacturing-scale competition for monoclonal antibody copies.
| Leading Market Players |
|---|
| Sandoz |
| Pfizer Inc. |
| Amgen Inc. |
| Celltrion, Inc. |
| Biogen Inc. |
| Fresenius Kabi |
| Samsung Bioepis Co., Ltd. |
| Biocon Biologics Inc. |
| Viatris |
| Others |
Value Network & Pricing Analysis
Hospital procurement coalitions rolled up through private-equity backed consolidation are reshaping supply behavior and pricing discipline across European biosimilar markets. These purchasing vehicles compress margins for reference product originators while rewarding manufacturers with cold chain infrastructure and volume scale.
Pricing Analysis
Volume-margin splits diverge sharply across molecular tiers. Hospital oncology tenders for monoclonal antibodies run on contract-based long-term offtake agreements with explicit market share erosion clauses. Price differentiation separates originator loyalty rebate tiers from biosimilar net realized prices based on tender volume commitments and G-BA health technology assessment ratings. Cost compression in the insulin segment is intensifying because reference product manufacturers deploy indication expansion defenses in Italian and Spanish retail channels. Dialysis centers in the United Kingdom represent the most price-sensitive buyer archetype, while university hospital hematology-oncology departments in France command premium positioning through HAS clinical benefit ratings.
Supply Chain Analysis
Temperature-controlled freight costs for subcutaneous auto-injector devices are restructuring last-mile logistics as homecare volumes expand. Mammalian cell culture supply concentrates in Germany, Switzerland, and Ireland, with Bavarian and Baden-Württemberg clusters anchoring sterile fill-finish operations. Raw material dependencies draw from Chinese-sourced recombinant protein media, German-engineered single-use bioreactor systems, and Belgian-produced prefilled syringe components. Single-source vulnerability in perfusion cell culture technology suppliers creates qualification bottlenecks for mid-scale European manufacturers. Distribution runs through regional hospital alliances in Germany and UNIH consortium channels in France, with cold chain reconfiguration toward direct-to-patient delivery models in Belgian and French homecare frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing platforms are displacing traditional fed-batch processes, compressing validation timelines and enabling real-time quality assurance for European biosimilar production.
For Market Incumbents: Anticipate accelerated tender consolidation by securing backward integration into single-use bioreactor component supply and expanding sterile fill-finish capacity in German manufacturing clusters. Defend against Korean manufacturing-scale competition by deepening hospital-centric distribution agreements with France's UNIH consortium and Germany's regional hospital alliances. Prioritize EU GMP Annex 1 compliance investments to preempt inspection-driven supply disruptions at legacy oncology injectable sites. For New Entrants and Emerging Players: Capture underpenetrated hospital segments in Poland, Romania, and Hungary where reference product loyalty remains lower and reimbursement frameworks are evolving. Target renal dialysis centers in Warsaw and Krakow with erythropoietin copies as the most penetrable entry point. Establish go-to-market positioning through real-world evidence generation partnerships with Dutch and Danish academic medical centers to differentiate in post-market pharmacovigilance-driven tender evaluations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European manufacturers with EU GMP-certified facilities in Bavaria and Baden-Württemberg but limited tender access scale. Long-term viability over the extended projection horizon rests on acquiring analytical characterization expertise and patient registry infrastructure rather than molecule pipelines alone. Monitor EMA interchangeability designation developments as the critical inflection signal for pharmacy-level substitution authority expansion in Germany and Italy.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Adoption | Real-time quality assurance from Sandoz and Samsung Bioepis compresses batch release timelines. |
| EU GMP Annex 1 Compliance Upgrade | Barrier isolation investments at German facilities preempt heightened regulatory inspection frequency. |
| Hospital Consortium Distribution Agreement | Multi-year framework contracts with France's UNIH secure volume allocation for oncology biosimilars. |
| Real-World Evidence Registry Development | Paris-Saclay cluster infrastructure enables competitive differentiation in post-market pharmacovigilance. |
| Eastern European Geographic Expansion | Poland's Łódź special economic zone attracts fill-finish investment for underpenetrated hospital segments. |
Research Methodology
EMA centralized approval filings, national health technology assessment databases, and hospital procurement tender records formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with regulatory affairs leads at biosimilar sponsors, formulary directors in German university hospitals, and payer access specialists in French regional health authorities validated secondary findings. Bottom-up patient population modeling across therapy areas combined with top-down manufacturer revenue triangulation to produce segment-level estimates.
Historical trendline analysis of monoclonal antibody patent expiration waves and tender adoption curves informed the projection framework across the analysis window. Segmentation modeling incorporated product type, therapy area, end user channel, and delivery mode dimensions with regional regulatory cluster variations. CAGRs derived from patent cliff timing, reimbursement framework evolution rates, and manufacturing capacity expansion announcements. Forecast inputs included EMA approval pipeline status, G-BA benefit assessment timelines, and UNIH consortium tender frequency patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA interchangeability designation decisions and reference product originator defense strategy shifts. Forecasts reflect documented assumptions regarding tender consolidation velocity and homecare reimbursement framework maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Global Sirolimus Market
Biosimilars
Imatinib Drug Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Etanercept Market