
 Biosimilar and Follow-On Biologics Market | 2026-2036
Biosimilar and Follow-On Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Biosimilar and Follow-On Biologics Market Outlook
The FDA interchangeable designation pathway is decoupling clinical trial requirements from commercial viability for well-characterized molecules. Pfizer Inc leverages its global manufacturing footprint to sustain cost leadership across multiple therapeutic classes. Samsung Bioepis Co., Ltd anchors its competitive position through deep specialization in oncology and immunology biosimilars. Celltrion Inc dominates the intravenous delivery segment with manufacturing scale that undercuts originator pricing.
Biosimilar and follow-on biologics are recombinant protein or monoclonal antibody therapeutics that demonstrate high similarity in structure, purity, and biological activity to an approved reference product, manufactured through living cell cultures in bioreactors with molecular weights typically exceeding 10 kDa. Their primary commercial purpose is to deliver equivalent clinical outcomes at reduced cost within hospital and specialty pharmacy formularies. Monoclonal antibodies represent the most contested margin pool as originator defenses erode across oncology and autoimmune indications. Injectable delivery modes sustain the highest volume throughput, though subcutaneous formulations are gaining fastest as patient-administration preferences shift.
EMA biosimilar guidelines, FDA 351(k) pathway requirements, and WHO prequalification standards collectively determine the analytical and clinical evidence threshold for market authorization. These frameworks shape demand by defining which products gain automatic substitution rights and which remain physician-selected alternatives. Stakeholders must monitor evolving interchangeability criteria and state-level pharmacy-level substitution laws as the primary determinants of volume acceleration versus gradual adoption curves.
Market Dynamics
Hospital procurement consolidation across Germany, the United States, and South Korea is compressing originator margins and forcing rapid formulary restructuring toward interchangeable biosimilar alternatives.
Growth Catalysts
- EMA biosimilar guidelines:The European Medicines Agency's streamlined analytical comparability requirements reduce clinical trial burdens for well-characterized monoclonal antibodies, accelerating market entry timelines.
- Injectable delivery modes:Hospital outpatient departments favor intravenous administration for oncology biosimilars, sustaining high-volume throughput and predictable reimbursement coding.
- South Korea:The Ministry of Food and Drug Safety's explicit reimbursement tiering favors domestic biosimilar manufacturers, creating automatic substitution incentives in national health insurance formularies.
Market Restraints
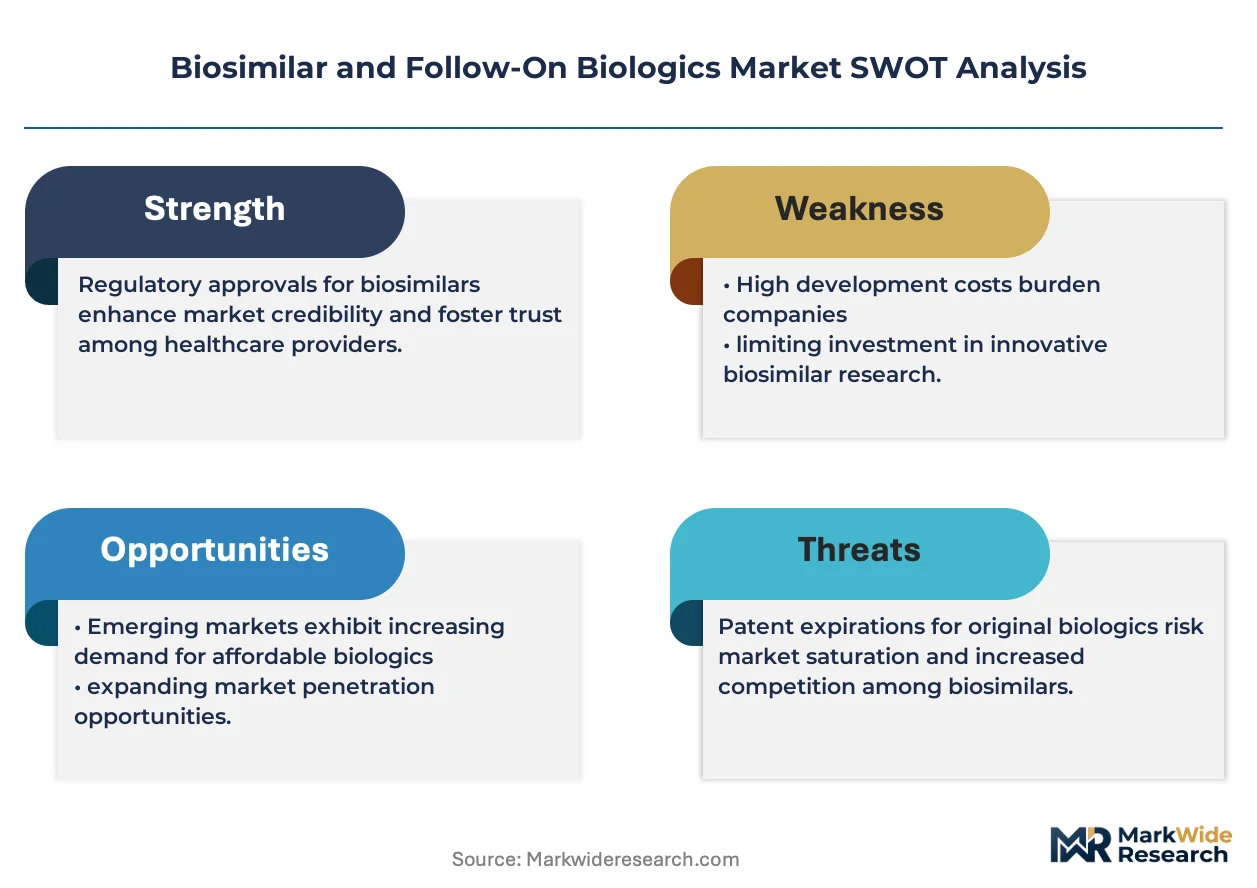
- Cell culture media costs:Serum-free media formulations and single-use bioreactor consumables constitute 35-45% of COGS, exposing manufacturers to supply volatility from specialty chemical suppliers.
- FDA interchangeability designation delays:The 351(k) pathway's switching study requirements create regulatory friction for subcutaneous formulations, delaying automatic pharmacy substitution rights.
- Originator patent thickets:Secondary patents on manufacturing processes and formulation modifications extend market exclusivity for reference biologics beyond primary composition-of-matter expiration.
Strategic Opportunities
- Ophthalmology biosimilars:Anti-VEGF agents for age-related macular degeneration represent an underpenetrated therapeutic class with limited current competition and high physician willingness to switch.
- WHO prequalification:The World Health Organization's biosimilar standards enable access to low- and middle-income country procurement pools, opening volume contracts previously reserved for originators.
- Continuous bioprocessing:Perfusion cell culture technology converges with single-use automation to reduce facility footprints and enable distributed manufacturing closer to demand centers.
Industry Challenges
- Analytical characterization expertise:Mass spectrometry and higher-order structure analysis require specialized protein chemists, creating talent scarcity in emerging manufacturing hubs.
- Immunogenicity surveillance:Post-market pharmacovigilance systems must detect rare adverse events across heterogeneous patient populations, straining regulatory affairs and medical affairs functions.
- Legacy cold chain infrastructure:Temperature-controlled distribution networks designed for small-molecule pharmaceuticals lack the precision required for protein stability, necessitating capital-intensive reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosimilar and Follow-On Biologics Market |
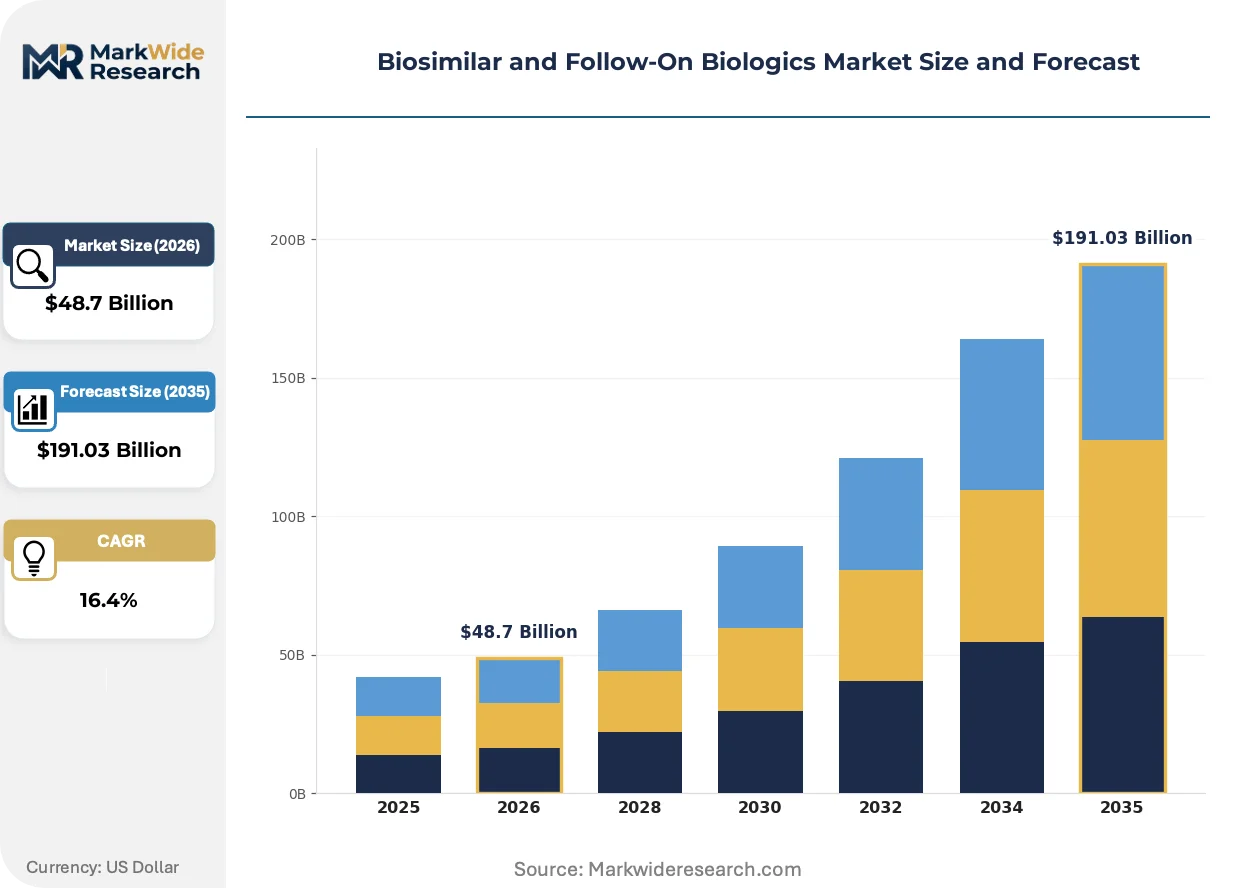
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Recombinant Proteins, Vaccines, Cell-Based Therapies Delivery Mode: Injectable, Intravenous, Subcutaneous, Oral End User: Hospitals, Clinics, Pharmacies, Research Institutions Regulatory Pathway: BLA, EMA, IND, 505(b)(2) |
| Companies Covered | Sandoz International GMBH, Pfizer Inc, Amgen Inc, Novartis AG, Celltrion Inc, Samsung Bioepis Co., Ltd, Biocon Biologics, Coherus Biosciences Inc, Alvotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosimilar and Follow-On Biologics Market Strategic Shifts
Single-use bioprocessing technologies and real-time release testing are compressing batch cycle times while regulatory convergence on analytical comparability is reducing redundant clinical development.
Modular single-use bioreactor systems is modularizing facility design for biosimilar manufacturing. Contract development and manufacturing organizations in Germany and South Korea are adopting these skid-mounted units to enable rapid capacity scaling without fixed stainless-steel infrastructure. This modularity is compressing capital deployment timelines from 36 months to 18 months for new production lines.
The FDA's interchangeable designation pathway is clarifying substitution rights for pharmacy-level dispensing. This policy shift creates commercial certainty for manufacturers investing in switching studies, with subcutaneous autoimmune indications capturing the initial wave of approvals. Rheumatology practices in the United States are responding by pre-authorizing interchangeable alternatives in electronic health record order sets.
Hospital purchasing cooperatives are consolidating biosimilar sourcing decisions through centralized formulary committees. Group purchasing organizations are displacing individual hospital pharmacy directors as the primary decision nodes, with oncology and immunology therapeutic classes experiencing the fastest consolidation. This concentration is most visible in German university hospital networks and United States integrated delivery networks where annual contract values exceed 50 million euros.
Biosimilar and Follow-On Biologics Market Segmentation
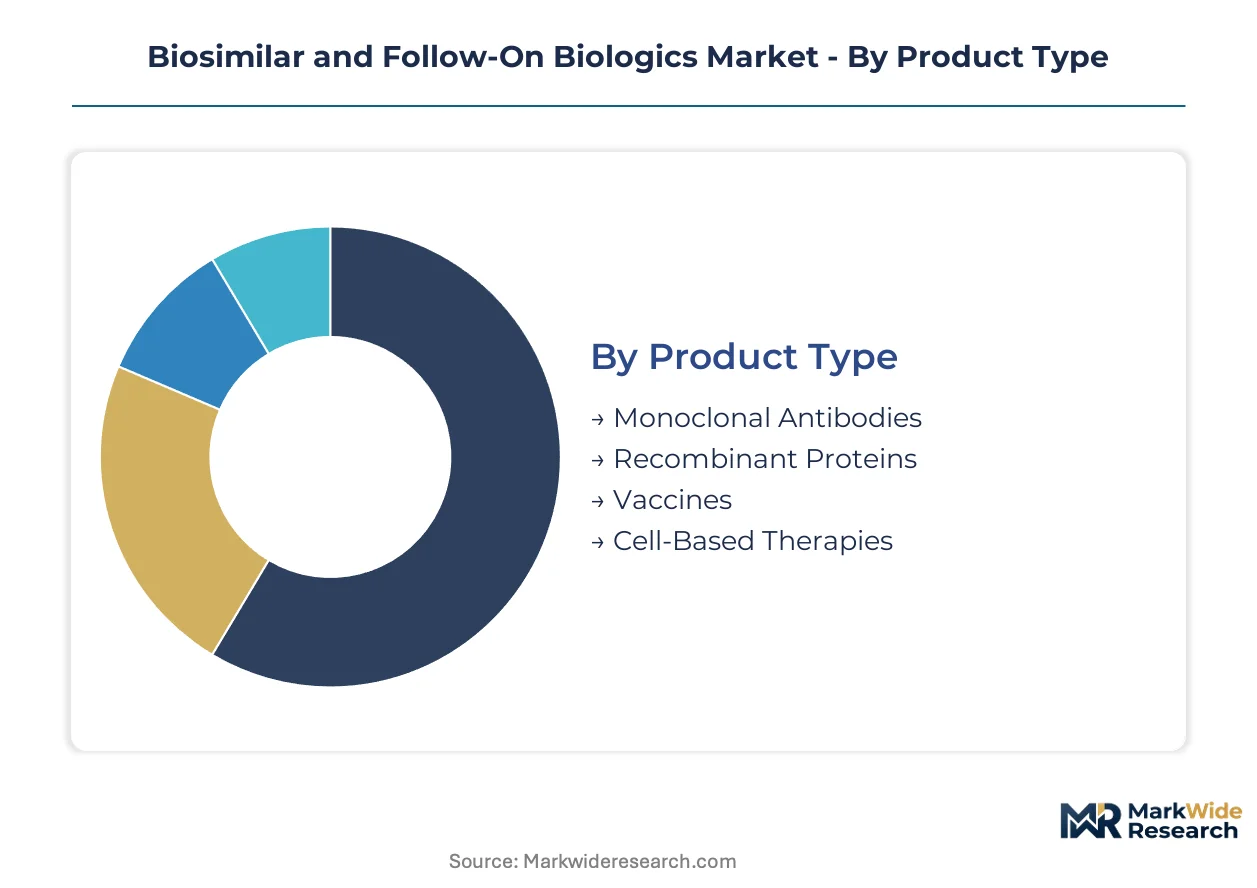
Biosimilar manufacturers configure product portfolios around molecular complexity, administration logistics, and reimbursement coding rather than traditional therapeutic categories. Segmentation choices directly determine which development programs secure hospital formulary placement and which face exclusion from group purchasing contracts.
Product Type:
Cost tier separates blockbuster-chasing monoclonal antibodies from commodity recombinant proteins and emerging cell-based platforms.
- Monoclonal Antibodies:Complex glycoproteins targeting TNF-alpha, HER2, and CD20 antigens with molecular weights exceeding 140 kDa. Demand concentrates in German university hospitals and United States oncology centers where originator price erosion creates immediate substitution incentives for adalimumab and trastuzumab biosimilars.
- Recombinant Proteins:Insulin analogs, erythropoietins, and growth hormones manufactured through bacterial or yeast expression systems. South Korean national health insurance formularies explicitly tier reimbursement for these molecules, accelerating automatic substitution at community pharmacies.
- Vaccines:Recombinant subunit and conjugate vaccines following reference product immunogenicity profiles.
- Cell-Based Therapies:Allogeneic and autologous cellular products entering biosimilar-equivalence frameworks.
Volume sits with monoclonal antibodies; growth tilts toward cell-based therapies.
Delivery Mode:
Application context determines whether products capture hospital outpatient revenue or retail pharmacy dispensing.
- Injectable:Prefilled syringes and auto-injectors for self-administered rheumatology and dermatology indications. United States rheumatology practices pre-authorize interchangeable alternatives in electronic health record order sets, compressing adoption timelines for subcutaneous formulations.
- Intravenous:Infusion-center administration for oncology and immunology biosimilars with complex dosing protocols. Hospital outpatient departments favor intravenous delivery for predictable reimbursement coding and higher-margin administration fees.
- Subcutaneous:Patient-administered alternatives to intravenous reference products.
- Oral:Peptide and protein formulations with limited bioavailability currently.
Revenue concentrates in intravenous delivery; patient preference is expanding subcutaneous fastest.
End User:
Procurement authority and reimbursement mechanics fragment demand across institutional settings.
- Hospitals:Integrated delivery networks and university hospital systems with centralized formulary committees controlling annual contract values exceeding 50 million euros. Group purchasing organizations displace individual pharmacy directors as primary decision nodes in German and United States networks.
- Clinics:Specialty infusion centers and physician office-based administration sites.
- Pharmacies:Retail and specialty pharmacy channels where interchangeable designation triggers automatic substitution.
- Research Institutions:Academic medical centers conducting head-to-head switching studies.
Procurement authority concentrates in hospitals; pharmacy-level dispensing is gaining regulatory momentum.
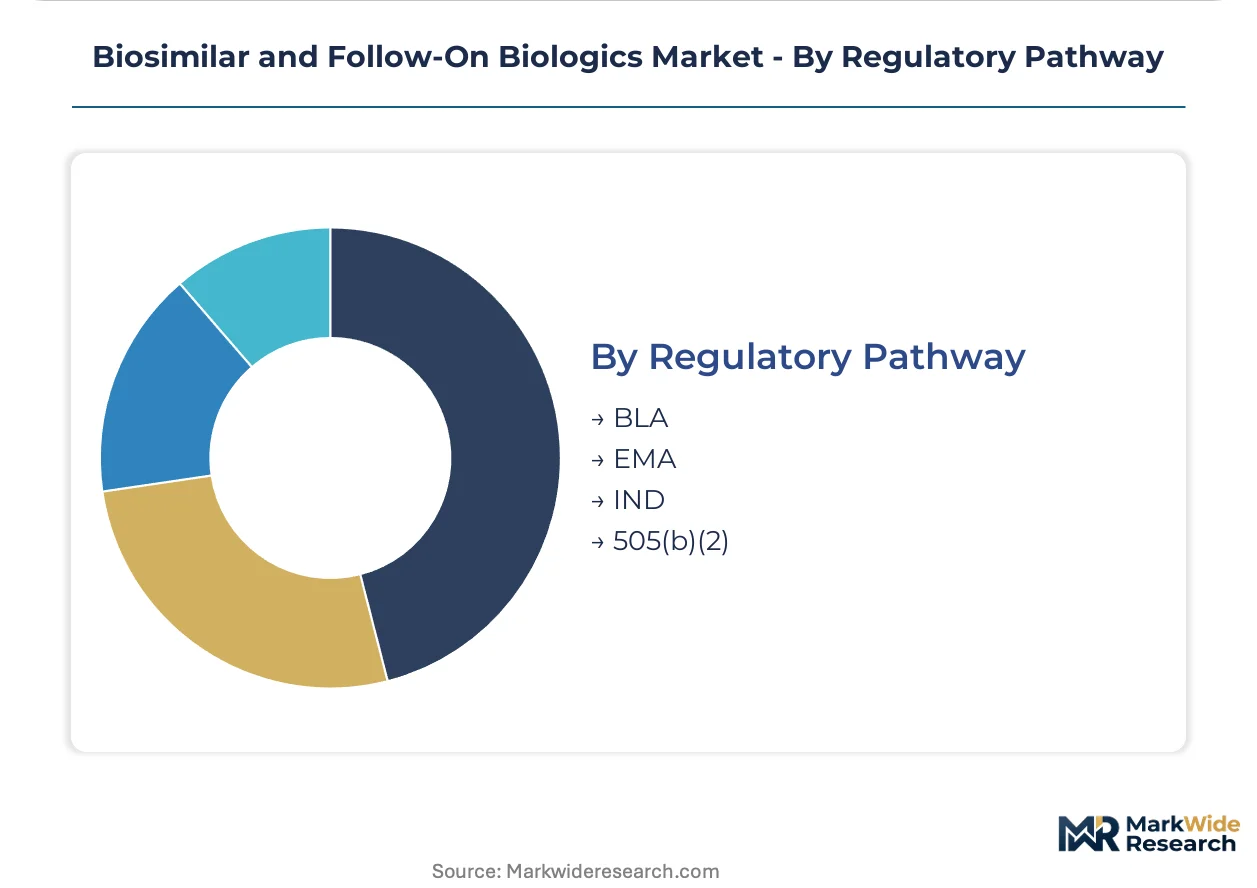
Regulatory Pathway:
Jurisdiction-specific evidence requirements determine development cost and commercial certainty.
- BLA:FDA biologics license application pathway requiring analytical comparability, pharmacokinetic equivalence, and often clinical immunogenicity studies. Switching study requirements for interchangeable designation create regulatory friction for subcutaneous formulations.
- EMA:European Medicines Agency centralized procedure with streamlined analytical comparability reducing clinical trial burdens for well-characterized molecules.
- IND:Investigational new drug applications for early-phase biosimilar development programs.
- 505(b)(2):FDA abbreviated new drug application pathway for certain protein products.
Submission volume concentrates in BLA and EMA pathways; 505(b)(2) utilization is expanding for peptide products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Incheon Free Economic Zone tax incentives concentrate South Korean biosimilar manufacturing capacity. German BioPharma-Cluster Bayern and North Carolina Research Triangle Park anchor European and United States production respectively.
United States
FDA interchangeability designations and Medicare reimbursement tiering drive hospital formulary adoption. The 351(k) pathway's switching study requirements create regulatory friction for subcutaneous formulations. North Carolina's Research Triangle Park hosts contract manufacturing organizations scaling single-use bioreactor capacity.
Germany
University hospital procurement consolidation and statutory health insurance rebate contracts compress originator margins. EMA centralized procedures enable streamlined analytical comparability submissions. Munich and Bavaria's BioPharma-Cluster anchors monoclonal antibody manufacturing for European distribution.
South Korea
Ministry of Food and Drug Safety reimbursement tiering favors domestic manufacturers with automatic substitution incentives. National health insurance formularies explicitly prioritize biosimilar uptake over reference products. Incheon Free Economic Zone hosts Samsung Bioepis and Celltrion production facilities serving export markets.
India
CDSCO abbreviated approval pathways and WHO prequalification standards enable access to low-income country procurement pools. PLI scheme incentives for biologics manufacturing attract contract development investment. Hyderabad and Bengaluru biotech clusters specialize in recombinant protein production for emerging markets.
Switzerland
Swissmedic streamlined biosimilar guidelines and originator company presence create specialized analytical services demand. Basel's pharmaceutical cluster supports contract research organizations conducting comparability studies. Zürich and Geneva academic medical centers lead European switching study enrollment.
Biosimilar and Follow-On Biologics Market Competitive Environment
South Korean producers anchor one tier; Swiss and United States specialists hold differentiated positions in regulatory consulting and manufacturing scale. The market structures around three tiers: integrated pharmaceutical conglomerates with global distribution, pure-play biosimilar developers with therapeutic focus, and contract manufacturing organizations with modular capacity. Dominant competitive moves include backward integration into cell line development and geographic expansion through WHO prequalification.
Among South Korea-based developers, Samsung Bioepis Co., Ltd and Celltrion Inc exemplify the scale-driven archetype through manufacturing footprint concentration. Pfizer Inc represents the integrated pharmaceutical conglomerate tier with global distribution infrastructure. These three companies occupy positions across the competitive spectrum without overlapping strategic emphasis.
| Leading Market Players |
|---|
| Sandoz International GMBH |
| Pfizer Inc |
| Amgen Inc |
| Novartis AG |
| Celltrion Inc |
| Samsung Bioepis Co., Ltd |
| Biocon Biologics |
| Coherus Biosciences Inc |
| Alvotech |
| Others |
Value Chain & Pricing Dynamics
Single-use bioprocessing technology adoption is compressing capital deployment timelines from 36 months to 18 months for new production lines, simultaneously reducing facility footprints and concentrating manufacturing scale among early adopters in Germany and South Korea. This technological shift is reshaping cost economics by lowering barrier-to-entry for contract manufacturers while amplifying pricing power for integrated players with captive bioreactor capacity.
Pricing Analysis
Lead-time-driven pricing stratification separates originator reference products commanding premium positioning from interchangeable biosimilars competing on contract value and formulary access speed. Three-tier pricing structure across premium originator, standard biosimilar, and economy vial-sourcing tiers reflects FDA interchangeability designation status and EMA centralized approval pathways. Cost compression in the standard tier is intensifying because hospital purchasing cooperatives are consolidating annual contract values exceeding 50 million euros. Community pharmacies demonstrate highest price sensitivity due to automatic substitution mechanics, while oncology centers maintain lowest sensitivity given administration fee structures.
Supply Chain Analysis
WHO prequalification standards and FDA 351(k) pathway requirements function as certification gates that filter supplier eligibility for institutional procurement pools. Manufacturing concentration rests on Germany, South Korea, and the United States as primary production hubs anchored by BioPharma-Cluster Bayern, Incheon Free Economic Zone, and North Carolina Research Triangle Park respectively. Serum-free media formulations, single-use bioreactor consumables, and temperature-controlled distribution infrastructure constitute critical input dependencies. Single-source vulnerability concentrates in specialty chemical suppliers for cell culture media. Distribution runs through hospital group purchasing organizations and integrated delivery networks with centralized formulary authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing technology is displacing legacy batch-fed cell culture methods, creating a transition window where manufacturing technology choices determine competitive positioning for the next decade.
For Market Incumbents: Cement formulary lock-in through backward integration into cell line development and analytical characterization capabilities. Originators defending adalimumab and trastuzumab franchises face erosion from Samsung Bioepis and Celltrion manufacturing scale. Priority lever centers on interchangeable designation switching studies for subcutaneous formulations to secure automatic pharmacy substitution rights. For New Entrants and Emerging Players: Ophthalmology anti-VEGF biosimilars represent an underserved buyer archetype with limited current competition and high physician willingness to switch. WHO prequalification pathways open procurement pools in low- and middle-income countries previously reserved for originators. Go-to-market angle should target national health insurance formularies with explicit biosimilar tiering such as South Korea's Ministry of Food and Drug Safety framework. For Investors and Strategic Acquirers: Exit pathways concentrate in contract manufacturing organization acquisitions by integrated pharmaceutical conglomerates seeking modular capacity. Long-term viability hinges on analytical characterization expertise scarcity and regulatory affairs talent concentration. Acquisition target archetype includes pure-play biosimilar developers with therapeutic focus in oncology or immunology. Signal to watch is FDA interchangeability designation approval velocity for subcutaneous autoimmune indications.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeability Designation Pursuit | FDA 351(k) switching studies unlock automatic pharmacy substitution rights for subcutaneous formulations. |
| Continuous Bioprocessing Adoption | Perfusion cell culture technology reduces facility footprints and enables distributed manufacturing closer to demand centers. |
| WHO Prequalification Pathway | World Health Organization standards open volume contracts in low- and middle-income country procurement pools. |
| Backward Integration into Cell Lines | In-house production of proprietary expression systems reduces dependency on external licensors and accelerates development timelines. |
| Hospital GPO Partnership Consolidation | Group purchasing organization contracts displace individual pharmacy directors as primary decision nodes in integrated delivery networks. |
Study Parameters
FDA 351(k) pathway filings, EMA centralized procedure submissions, and ClinicalTrials.gov enrollment data formed the secondary backbone of this analysis. Primary interviews with regulatory affairs leads, formulary directors at German university hospitals, hospital procurement managers in United States integrated delivery networks, and payer access specialists validated secondary findings. Bottom-up modeling of molecular type, delivery mode, and end-user procurement authority combined with top-down triangulation against national health insurance formulary data.
Historical trendline analysis of biosimilar approval velocity and formulary adoption curves informed projection mechanics across the analysis window. Segmentation dimensions modeled include product type complexity tier, administration route logistics, procurement authority concentration, and regional regulatory cluster. CAGRs were derived from curve-fitting against comparable therapeutic class penetration patterns. Forecast inputs incorporated EMA biosimilar guideline evolution and Medicare reimbursement tiering mechanics.
Revisions become necessary when FDA interchangeability designation criteria materially expand or contract, or when originator patent thicket strategies successfully extend market exclusivity beyond primary composition-of-matter expiration. Forecasts reflect assumptions regarding regulatory convergence on analytical comparability standards and hospital purchasing cooperative consolidation velocity. A model refresh is warranted upon material change in WHO prequalification standards or national health insurance formulary tiering policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Global Biosimilars Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Etanercept Market
Biosimilars
Europe Biosimilars Market
Biosimilars
US Biosimilars Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Global Sirolimus Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Immunology Biosimilars Market