
 Insulin API Market | 2026-2036
Insulin API Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin API Market Analysis
Hospital procurement of biosimilar insulin is restructuring the end-use vertical mix, shifting volume away from originator brands toward cost-controlled formularies. Novo Nordisk A/S anchors European supply through vertically integrated fermentation facilities in Denmark. Biocon Biologics Ltd. leverages its Malaysian manufacturing base to serve emerging market tenders. Eli Lilly and Company sustains dominance in the United States through captive API-to-finished-dose production.
Insulin API denotes the biologically active recombinant peptide produced via microbial or mammalian cell culture, requiring chromatographic purification to achieve purity exceeding ninety-nine percent for therapeutic use. Long-acting insulin commands the largest value share due to patent-protected analog formulations and complex synthesis protocols that limit generic replication. Rapid-acting insulin represents the fastest-expanding segment, driven by pump-compatible analog demand and postprandial glucose management protocols. Pen injectors lead delivery mode adoption in developed markets, while syringes retain volume in cost-sensitive procurement environments.
FDA enforces Current Good Manufacturing Practice standards through facility inspections that determine API import eligibility, while EMA's biosimilar framework mandates comparative immunogenicity studies for market authorization. India's CDSCO aligns with WHO prequalification norms to facilitate export-oriented production from BIS-certified plants. Stakeholders must monitor regulatory divergence between reference product extrapolation rules and evolving interchangeability designations.
Market Dynamics
Hospital formulary consolidation is compressing originator insulin margins while biosimilar tenders restructure procurement hierarchies across developed markets. CDSCO-aligned manufacturing in India now supplies regulated channels, tightening purity benchmarks and compressing lead times for API sourcing.
Growth Catalysts
- EMA Biosimilar Framework:Comparative immunogenicity mandates accelerate reference product extrapolation, streamlining market entry for second-generation analogs across European hospital networks.
- Microbial Fermentation Advances:Recombinant peptide yields from high-cell-density E. coli cultures now exceed mammalian systems, lowering unit costs for rapid-acting insulin APIs.
- Pump-Compatible Analog Demand:Continuous glucose monitoring integration drives formulary preference for ultra-rapid formulations in ambulatory care settings.
Market Restraints
- Chromatographic Resin Costs:Protein A and ion-exchange media account for disproportionate downstream processing expense, squeezing margins at contract manufacturing scale.
- Danish Supply Concentration:Vertically integrated fermentation clusters near Copenhagen create geographic single-point vulnerability for European API security.
- FDA Facility Inspection Backlogs:Import alert delays at BIS-certified Indian plants extend qualification timelines for new API suppliers seeking US market access.
Strategic Opportunities
- Malaysian Export Hub Expansion:BIS-certified facilities in Penang serve emerging market tenders with WHO-prequalified insulin APIs, bypassing originator patent thickets.
- Prefilled Pen Device Convergence:Dual-chamber cartridge designs compatible with both analog and biosimilar formulations open channel access beyond vial-syringe segments.
- India PLI Scheme:Production-linked incentives for biopharma API manufacturing attract fermentation capacity expansion toward export-oriented recombinant peptide output.
Industry Challenges
- Bioprocess Engineer Scarcity:GMP-compliant cell culture and chromatography scale-up expertise concentrates in Copenhagen and Bangalore, constraining facility expansion elsewhere.
- Comparative Clinical Trial Burden:EMA-equivalence studies for biosimilar interchangeability designation require patient cohorts exceeding originator development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin API Market |
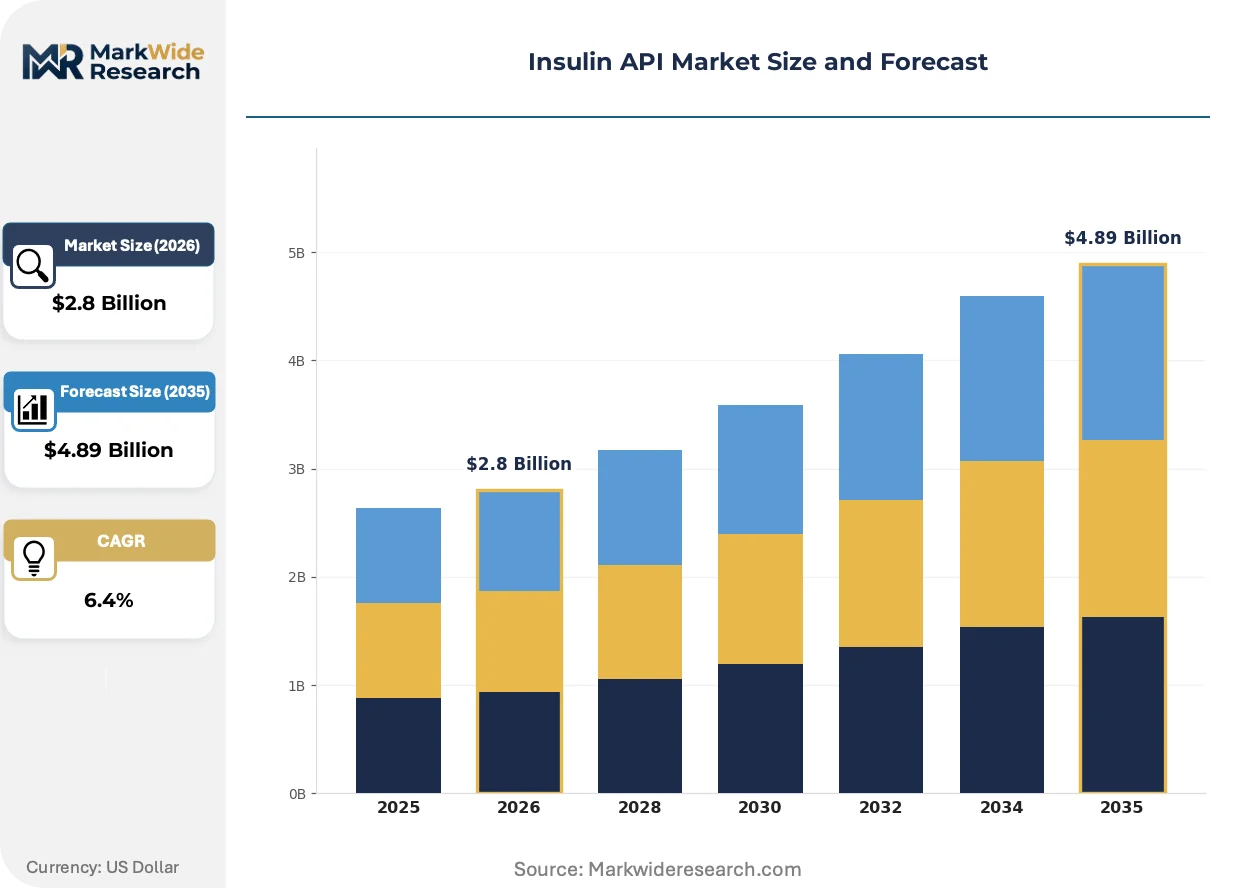
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Intermediate-Acting Insulin, Pre-Mixed Insulin Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pre-Diabetes Delivery Mode: Pen Injectors, Syringes, Insulin Pumps, Inhalable Insulin End User: Hospitals, Clinics, Home Care, Diabetes Education Centers |
| Companies Covered | Biocon Biologics Ltd., Gan & Lee Pharmaceutical Co., Ltd., Novo Nordisk A/S, Amphastar Pharmaceuticals, Inc., Wockhardt Ltd., Sanofi S.A., Tonghua Dongbao Pharmaceutical Co., Ltd., Torrent Pharmaceuticals Ltd., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin API Market Emerging Trajectories
Continuous manufacturing platforms and real-time release testing are compressing batch cycle times for insulin API production. These shifts reduce working capital intensity while tightening impurity profiles beyond traditional validation protocols.
Single-use bioreactor systems with integrated perfusion control are modularizing upstream operations for insulin API fermentation. Mid-scale CDMOs in India and Malaysia adopt these skid-mounted configurations to avoid fixed stainless-steel infrastructure. This technology is modularizing capacity deployment, enabling rapid site qualification for regulated market supply without multi-year construction timelines.
EMA's revised biosimilar guidance on immunogenicity assessment now mandates anti-drug antibody monitoring through 12-month extension studies. This extends development timelines for rapid-acting analog submissions by eight to fourteen months. European hospital procurement groups are responding by consolidating tender awards toward suppliers with existing interchangeability designations, raising barriers for late entrants.
Group purchasing organizations in the United States are unbundling API sourcing from finished-dose contracts, creating direct procurement relationships with BIS-certified Indian manufacturers. This disintermediation bypasses traditional wholesale distribution markups for hospital system formularies. The shift is most visible in Medicaid-managed care networks seeking cost-controlled biosimilar insulin for high-volume diabetes populations.
Insulin API Market Segmentation
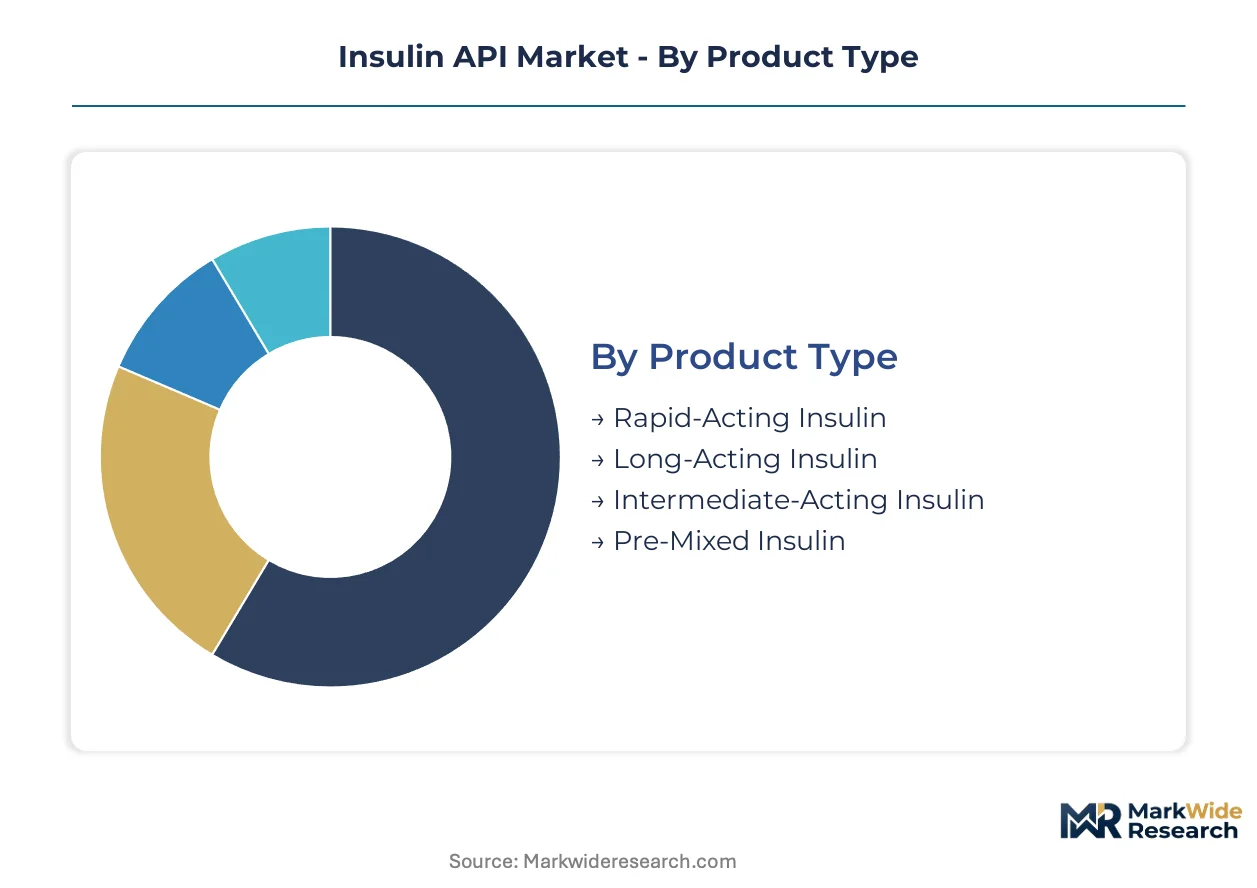
Insulin API demand fragments across formulation chemistry, disease severity, and care setting economics. Each dimension carries distinct purity requirements, regulatory pathways, and margin structures that shape supplier positioning.
Product Type:
Upgrade cycles from human insulin toward analog formulations are compressing batch volumes while expanding per-gram value capture.
- Long-Acting Insulin:Recombinant peptide analogs with extended pharmacokinetic profiles require complex acylation chemistry and chromatographic resolution. Hospital formularies in Denmark and Germany concentrate procurement toward patent-protected glargine and degludec variants for basal glucose control.
- Rapid-Acting Insulin:Ultra-rapid formulations engineered for pump compatibility and postprandial targeting. Ambulatory care networks in the United States prioritize lispro and aspart analogs with accelerated absorption kinetics for continuous glucose monitoring integration.
- Intermediate-Acting Insulin:NPH formulations retain procurement share in cost-controlled tenders across India and Malaysia where neutral protamine hagedorn suspensions satisfy basic glycemic management.
- Pre-Mixed Insulin:Fixed-ratio combinations of rapid and intermediate fractions simplify dosing protocols for patient populations with limited self-monitoring capacity in emerging market clinics.
Long-acting insulin sits at the top of the volume ranking, with rapid-acting insulin climbing the fastest.
Therapy Area:
Patient acuity and reimbursement intensity vary sharply across disease progression stages, concentrating API demand in chronic management segments.
- Type 2 Diabetes:Metabolic syndrome progression drives the largest absolute API consumption, with oral-to-injectable escalation protocols expanding basal analog requirements in Medicare and NHS formularies.
- Type 1 Diabetes:Absolute insulin deficiency mandates intensive replacement therapy with rapid-acting and long-acting combination regimens. Pediatric endocrinology centers in the United States and United Kingdom specify pump-compatible analogs with reduced immunogenicity profiles.
- Gestational Diabetes:Pregnancy-specific glycemic targets require human insulin preference over analogs due to limited teratogenicity data, constraining API specification to NPH and regular formulations.
- Pre-Diabetes:Lifestyle intervention focus limits pharmaceutical penetration, though prediabetes-to-diabetes conversion monitoring in Indian primary care networks creates early insulinization opportunity.
Type 2 diabetes commands the dominant share of API volume, while type 1 diabetes exhibits the steepest per-patient consumption intensity.
Delivery Mode:
Device-consumable bundling economics are restructuring procurement relationships between API suppliers and delivery system manufacturers.
- Pen Injectors:Cartridge-based systems with dial-dose precision dominate developed market ambulatory care. Prefilled pen contracts in Germany and France now unbundle API sourcing from device supply, enabling direct biosimilar procurement.
- Syringes:Vial-and-syringe administration retains volume in Medicaid-managed care and emerging market tenders where unit cost minimization overrides convenience premiums.
- Insulin Pumps:Tubed and patch pump systems require ultra-rapid analog formulations with stability profiles compatible with 72-hour reservoir dwell times.
- Inhalable Insulin:Pulmonary delivery of Technosphere insulin powder addresses needle-averse patient segments, though API manufacturing complexity and pulmonary safety surveillance limit formulary penetration.
Pen injectors lead value capture, with insulin pumps gaining share fastest among technology-adopting patient cohorts.
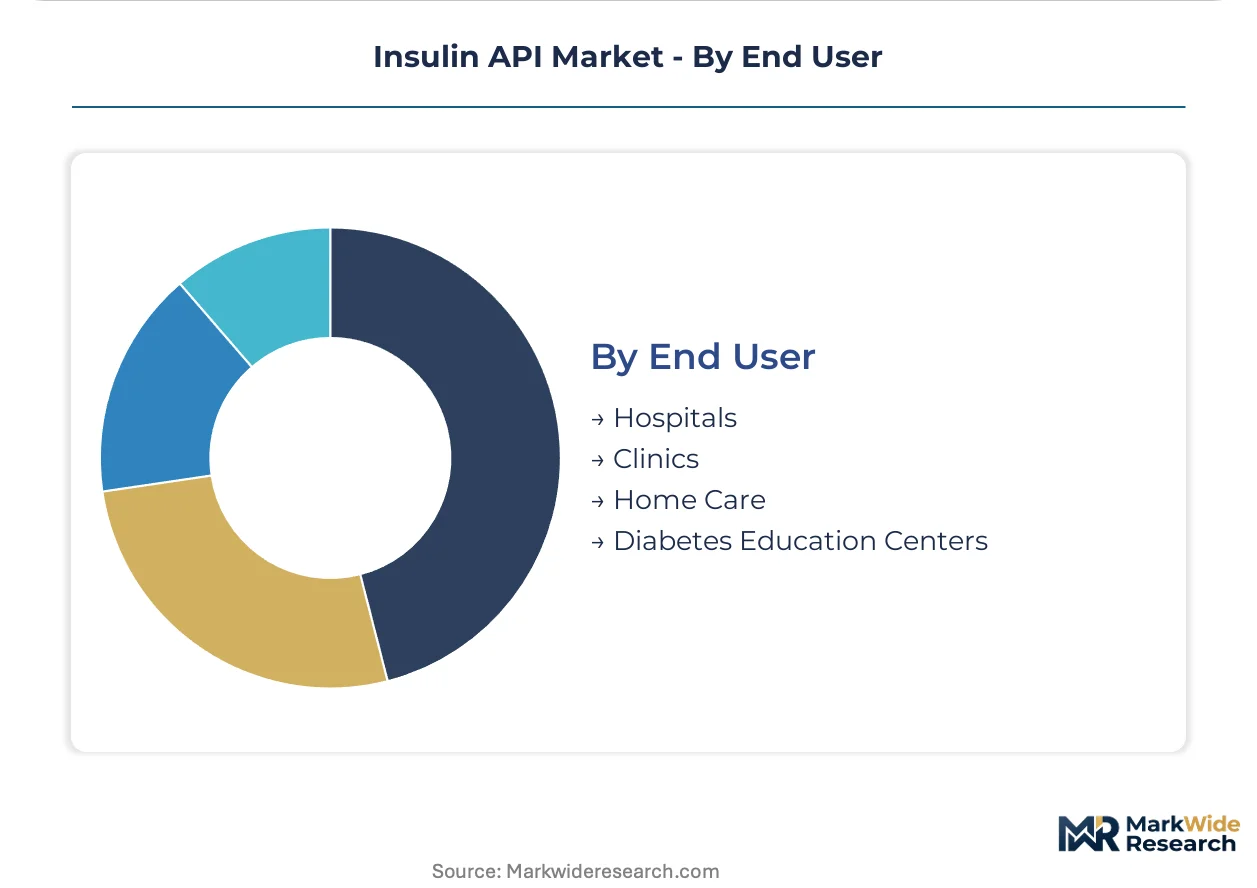
End User:
Procurement consolidation across integrated delivery networks is compressing supplier margins while expanding contract volumes.
- Hospitals:Inpatient glycemic management protocols and perioperative insulinization drive concentrated API demand. Group purchasing organizations in the United States consolidate biosimilar tenders across multi-hospital systems.
- Home Care:Self-administration trends shift volume toward patient-direct distribution channels with cold-chain logistics requirements.
- Clinics:Outpatient diabetes centers in India and Malaysia manage high patient volumes with protocol-driven insulin initiation pathways.
- Diabetes Education Centers:Counseling-focused facilities influence product selection through patient training on device technique, indirectly shaping API specification through downstream prescribing.
Hospitals dominate procurement volume, with home care expanding most quickly as remote patient monitoring reduces clinic dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting insulin API production toward jurisdictions where BIS-certified facilities and CDSCO-aligned protocols reduce cost-of-compliance burdens relative to FDA and EMA jurisdictions. Indian contract manufacturers exploit this gap to serve regulated export markets. Danish and German clusters retain premium-tier supply through vertically integrated fermentation infrastructure.
United States
Medicaid-managed care networks drive biosimilar insulin procurement through unbundled API sourcing from BIS-certified Indian manufacturers. FDA import alert backlogs at foreign facilities extend qualification timelines for new suppliers. Indianapolis anchors captive API-to-finished-dose production for domestic hospital formularies.
Germany
Hospital procurement groups consolidate tender awards toward suppliers with existing EMA interchangeability designations. The EMA biosimilar framework mandates comparative immunogenicity studies that extend development timelines. The Rhine-Ruhr corridor hosts vertically integrated fermentation capacity serving European basal analog demand.
India
CDSCO-aligned manufacturing supplies regulated channels with recombinant peptide APIs from BIS-certified plants. The PLI scheme for biopharma API manufacturing attracts fermentation capacity expansion toward export-oriented output. Karnataka and Maharashtra clusters specialize in high-cell-density E. coli cultures for rapid-acting insulin production.
Denmark
Vertically integrated fermentation clusters near Copenhagen create geographic concentration for European API security. The EMA's revised biosimilar guidance on immunogenicity assessment tightens purity benchmarks for active pharmaceutical ingredients. The Copenhagen cluster specializes in long-acting analog formulations with extended pharmacokinetic profiles.
Malaysia
BIS-certified facilities in Penang serve emerging market tenders with WHO-prequalified insulin APIs. WHO prequalification norms facilitate export-oriented production bypassing originator patent thickets. The Penang pharmaceutical corridor specializes in modular single-use bioreactor deployments for rapid site qualification.
Insulin API Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers deploy single-use bioreactor systems to compress batch cycle times. The market structure concentrates around three strategic archetypes: vertically integrated originators with captive fermentation infrastructure, emerging-market contract manufacturers with BIS-certified export capacity, and mid-scale CDMOs adopting modular upstream technologies. M&A activity targets chromatography purification capabilities, while strategic partnerships secure long-term offtake agreements for hospital formulary consolidation.
Among Denmark-based integrated biopharmaceuticals, Novo Nordisk A/S occupies a position exemplifying originator-tier vertical control over fermentation and finished-dose production. Indian specialists Biocon Biologics Ltd. and Wockhardt Ltd. represent the contract manufacturing archetype, anchoring export-oriented supply from BIS-certified facilities to regulated markets. These three entities illustrate the competitive tension between patent-protected analog portfolios and cost-controlled biosimilar procurement hierarchies restructuring global insulin API commerce.
| Leading Market Players |
|---|
| Biocon Biologics Ltd. |
| Gan & Lee Pharmaceutical Co., Ltd. |
| Novo Nordisk A/S |
| Amphastar Pharmaceuticals, Inc. |
| Wockhardt Ltd. |
| Sanofi S.A. |
| Tonghua Dongbao Pharmaceutical Co., Ltd. |
| Torrent Pharmaceuticals Ltd. |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Captive fermentation infrastructure at vertically integrated Danish and Indian facilities anchors both supply security and pricing power across insulin API tiers. Novo Nordisk's Copenhagen cluster and Biocon's Malaysian operations demonstrate how upstream control over high-cell-density E. coli cultures and chromatographic purification capacity translates into formulary negotiation leverage against unbundled procurement.
Pricing Analysis
Distributor markups in hospital group purchasing organization channels are compressing as US Medicaid-managed care networks unbundle API sourcing from finished-dose contracts. Three-tier pricing structure across originator analog, designated biosimilar, and emerging-market tender grades reflects EMA interchangeability certification and FDA facility inspection status. Cost compression in the biosimilar tier is intensifying because chromatographic resin expenses and comparative immunogenicity study burdens concentrate margin pressure on second-generation entrants. Tender-based procurement in European hospital networks shows the least price sensitivity, while Indian and Malaysian emerging-market tenders prioritize unit cost minimization over purity premiums.
Supply Chain Analysis
Regional distribution centers in Copenhagen, Indianapolis, and Penang orchestrate hub-and-spoke cold-chain logistics for temperature-sensitive recombinant peptide shipments. API production concentrates in Denmark, India, and Malaysia, with fermentation capacity expansion in Karnataka and Maharashtra clusters feeding export-oriented output. Downstream processing draws from protein A and ion-exchange chromatography media, high-purity water systems, and single-use bioreactor assemblies. Single-source vulnerability at Danish vertically integrated clusters creates European supply security exposure. Distribution runs through BIS-certified contract manufacturers serving regulated markets with WHO-prequalified documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
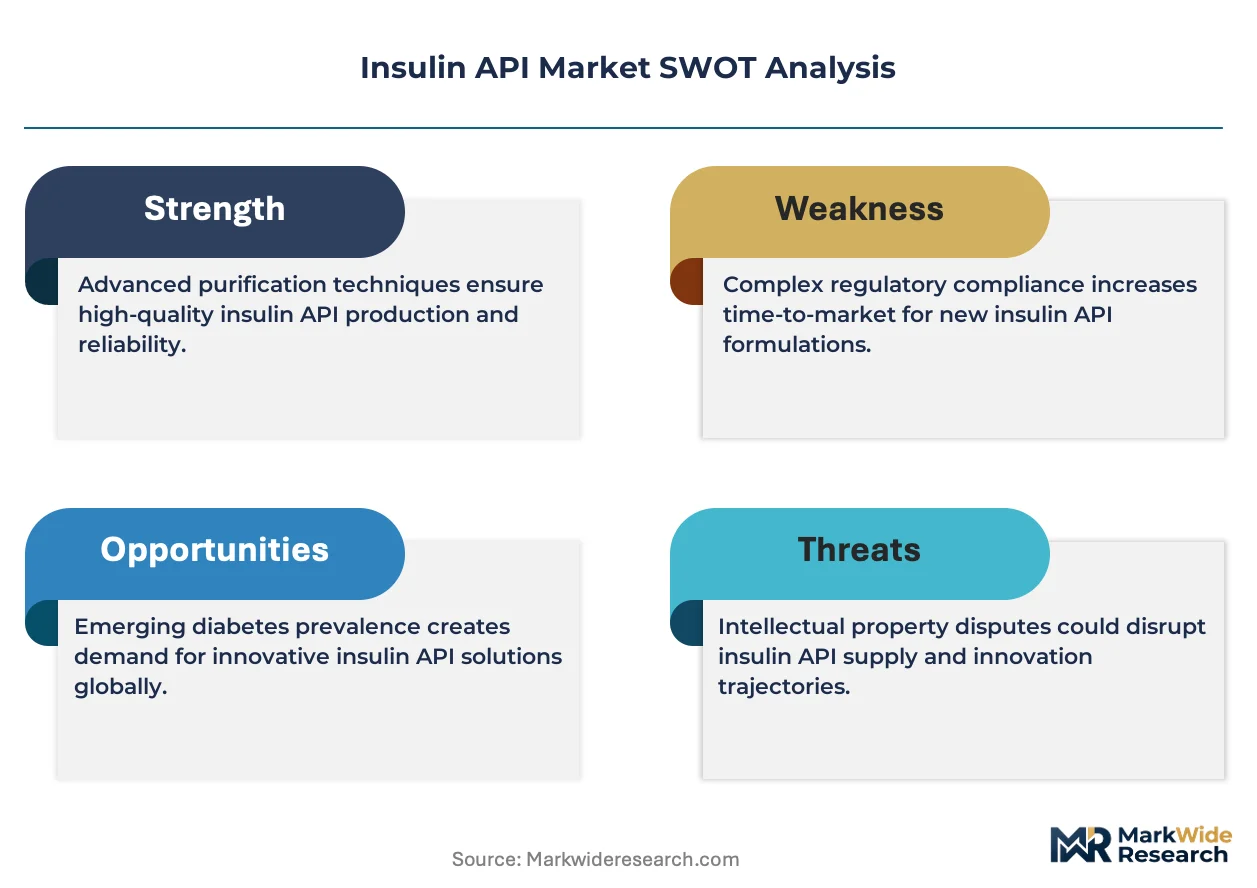
Margin expansion in insulin API supply rests on biosimilar cost-down trajectories in high-cell-density fermentation and modular single-use bioreactor deployment, while originator analog portfolios capture premium-tier value through pump-compatible formulation innovation.
For Market Incumbents: To counter biosimilar tender compression in European hospital networks, Novo Nordisk and Eli Lilly should deepen backward integration into chromatography resin supply and expand captive fermentation capacity in Copenhagen and Indianapolis clusters. Securing EMA interchangeability designation through 12-month immunogenicity extension studies becomes essential for formulary retention as procurement groups consolidate awards toward pre-qualified suppliers. For New Entrants and Emerging Players: The price-point gap between EMA-designated biosimilars and Indian CDSCO-aligned tender products creates white-space opportunity in Medicaid-managed care networks seeking cost-controlled alternatives to originator analogs. Malaysian BIS-certified facilities offer the most penetrable production geography for rapid site qualification. A direct procurement partnership with US hospital group purchasing organizations bypasses traditional wholesale distribution markups. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale CDMOs with modular single-use bioreactor capabilities because hospital formulary consolidation demands flexible capacity expansion without multi-year stainless-steel construction timelines. Platform aggregation targets should emphasize chromatography purification expertise and existing BIS certification for regulated market access. Watch FDA import alert resolution timelines at Indian facilities as the inflection signal for new supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Interchangeability Designation | Twelve-month immunogenicity extension studies unlock European hospital tender access beyond reference product extrapolation. |
| Modular Single-Use Bioreactor Deployment | Skid-mounted perfusion systems in Penang and Bangalore compress site qualification timelines for regulated supply. |
| Backward Integration into Chromatography Media | Captive protein A and ion-exchange resin supply insulates margins from downstream processing cost volatility. |
| Direct GPO Procurement Partnership | Unbundled API sourcing contracts with US hospital systems bypass wholesale distribution markups in Medicaid networks. |
| CDSCO-Aligned Manufacturing Expansion | BIS-certified Karnataka clusters leverage PLI incentives for export-oriented recombinant peptide output to regulated markets. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative findings in operational reality across insulin API supply chains. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up fermentation capacity modeling and top-down tender award analysis were triangulated to reconcile production economics with procurement flow data.
Segment-level volume and value trajectories across the analysis window reflect disaggregated modeling by product type, therapy area, delivery mode, and end-user procurement channel. CAGRs were derived from curve-fitting historical biosimilar penetration patterns against originator analog pricing elasticity. Forecast inputs incorporated EMA guidance revision timelines, FDA facility inspection queue dynamics, and PLI scheme uptake rates in Indian biopharma manufacturing.
The model assumes a particular technology adoption path for continuous manufacturing platforms; alternative pathways for batch processing with real-time release testing would alter the capacity expansion outlook. Forecasts reflect documented assumptions regarding regulatory divergence between reference product extrapolation and interchangeability designation rules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Global Protein Expression Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Macrolide Drugs Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Triclabendazole Market