
 Europe Generic Injectables Market | 2026-2036
Europe Generic Injectables Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Generic Injectables Market Intelligence
Market Context
Italy is tilting toward expanded sterile injectable capacity through dedicated manufacturing zones in Lombardy and Emilia-Romagna. Fresenius SE & Co. KGaA leverages its Kabi division's European hospital channel network to sustain high-volume contracts for generic anesthesia and oncology injectables. Hikma Pharmaceuticals PLC anchors its position through specialized manufacturing in Portugal and Germany, competing on cost efficiency for anti-infective parenterals. Pfizer Inc. differentiates via legacy hospital trust and integrated distribution across Nordic and Benelux markets.
Technical Definition and Segment Structure
Europe Generic Injectables comprise sterile, bioequivalent parenteral drug products—solutions, suspensions, or lyophilized powders—packaged in vials, ampoules, pre-filled syringes, or infusion bags for administration via intravenous, intramuscular, subcutaneous, or intra-articular routes, primarily serving hospital and clinical settings where patent expiration enables lower-cost therapeutic substitution. Pre-filled syringes command attention for their dosing precision and reduced medication error rates, though vials retain dominance in high-volume oncology and anesthesia applications where multi-dose protocols prevail. Intravenous delivery generates the largest revenue pool across therapy areas, while subcutaneous formulations in diabetes and neurology represent the fastest structural expansion as homecare protocols expand beyond hospital walls.
Regulatory Framework and Outlook
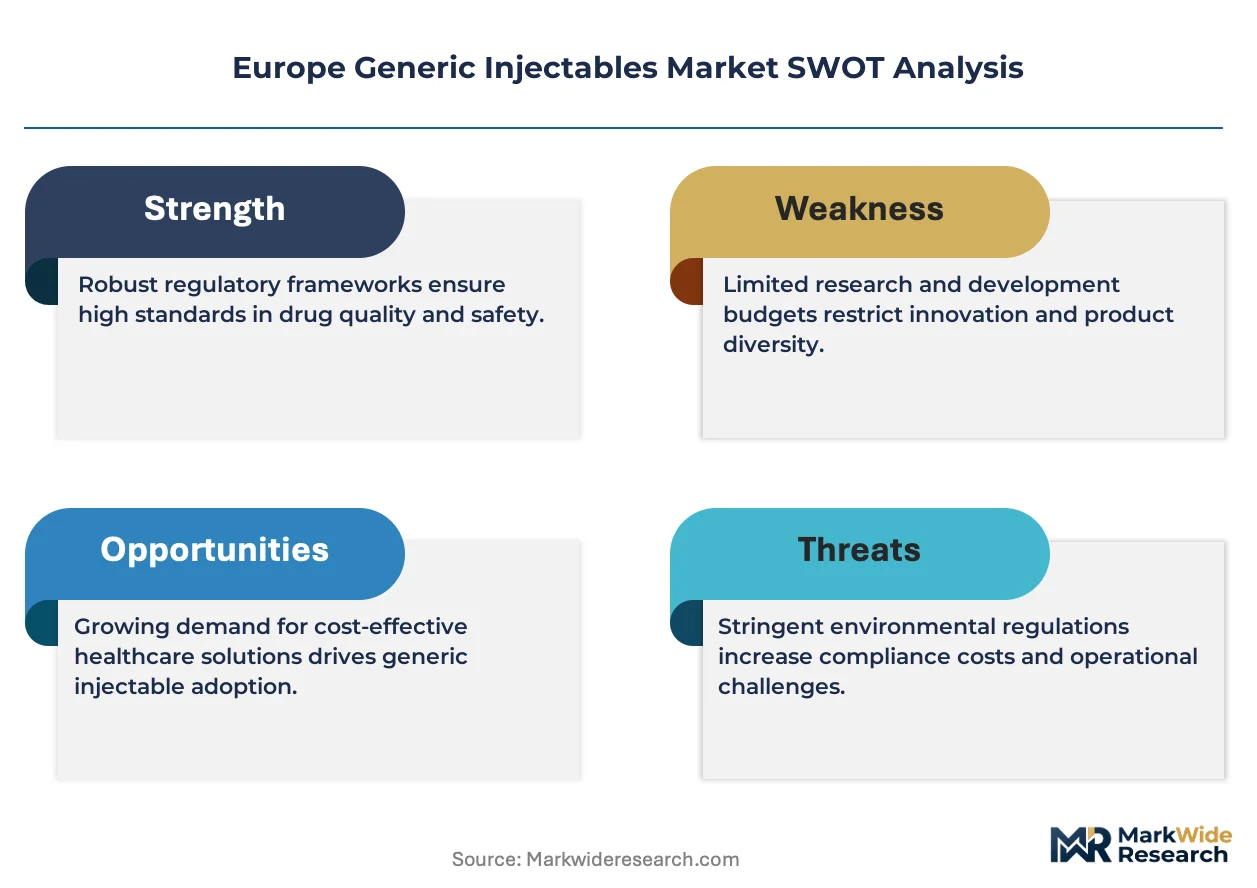
The European Medicines Agency (EMA) coordinates centralized marketing authorization for generic injectables alongside national competent authorities in Germany, France, and Italy, with the EU's revised Pharmaceutical Legislation introducing stricter environmental risk assessments and accelerated approval pathways for critical parenteral medicines. The Medical Device Regulation (MDR) and REACH compliance requirements for device-drug combination products, particularly pre-filled syringes and infusion systems, add layered conformity obligations that reshape supplier qualification criteria. Stakeholders must monitor how the EU Green Deal's pharmaceutical waste directives and upcoming carbon footprint disclosure rules for active pharmaceutical ingredient manufacturing will alter sourcing economics for sterile injectable supply chains.
Market Dynamics
Hospital purchasing consolidation across Germany, France, and Italy is compressing supplier margins while amplifying volume commitments for generic parenteral manufacturers. Centralized tendering mechanisms now bundle anesthesia, oncology, and anti-infective injectables into multi-year framework agreements that favor scale over specialization.
Growth Catalysts
- EU Pharmaceutical Legislation revision:Accelerated approval pathways for critical parenteral medicines shorten time-to-market for sterile generic entrants addressing shortages in hospital formularies.
- Homecare protocol expansion:Subcutaneous delivery systems for diabetes and neurology therapies are extending injectable consumption beyond acute care settings into ambulatory and patient-administered channels.
- Lombardy manufacturing cluster development:Dedicated sterile injectable zones in Northern Italy are attracting contract manufacturing investment to serve pan-European hospital networks.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient sourcing for generic parenterals remains dependent on concentrated Asian manufacturing, exposing European fill-finish operations to geopolitical disruption and customs delays.
- REACH compliance escalation:Environmental risk assessments for device-drug combination products, particularly pre-filled syringes with elastomer components, are extending qualification timelines and raising formulation costs.
- Glass vial input volatility:Borosilicate glass and rubber closure supply constraints are inflating primary packaging costs for high-volume oncology and anesthesia multi-dose applications.
Strategic Opportunities
- Portuguese manufacturing expansion:Underutilized sterile capacity in Iberia offers cost-competitive fill-finish options for anti-infective parenterals targeting Benelux and Nordic procurement consortia.
- Pre-filled syringe automation convergence:Integration of robotic aseptic processing with nested container closure systems is enabling small-batch flexibility for biologic biosimilars requiring differentiated delivery formats.
- EU Green Deal pharmaceutical waste directives:Carbon footprint disclosure requirements for API manufacturing are creating first-mover advantage for suppliers with verified renewable energy sourcing in sterile injectable production.
Industry Challenges
- Aseptic processing technician scarcity:Qualified personnel for isolator-based sterile manufacturing operations remain concentrated in established German and Swiss clusters, constraining capacity expansion in Southern and Eastern Europe.
- MDR device-drug recertification:Medical Device Regulation conformity obligations for combination products are forcing parallel regulatory tracks that fragment submission timelines and strain quality assurance resources.
- Lyophilization cycle validation:Complex freeze-dry protocol development for unstable parenteral formulations demands specialized equipment investment that smaller generic entrants struggle to amortize across limited product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Generic Injectables Market |
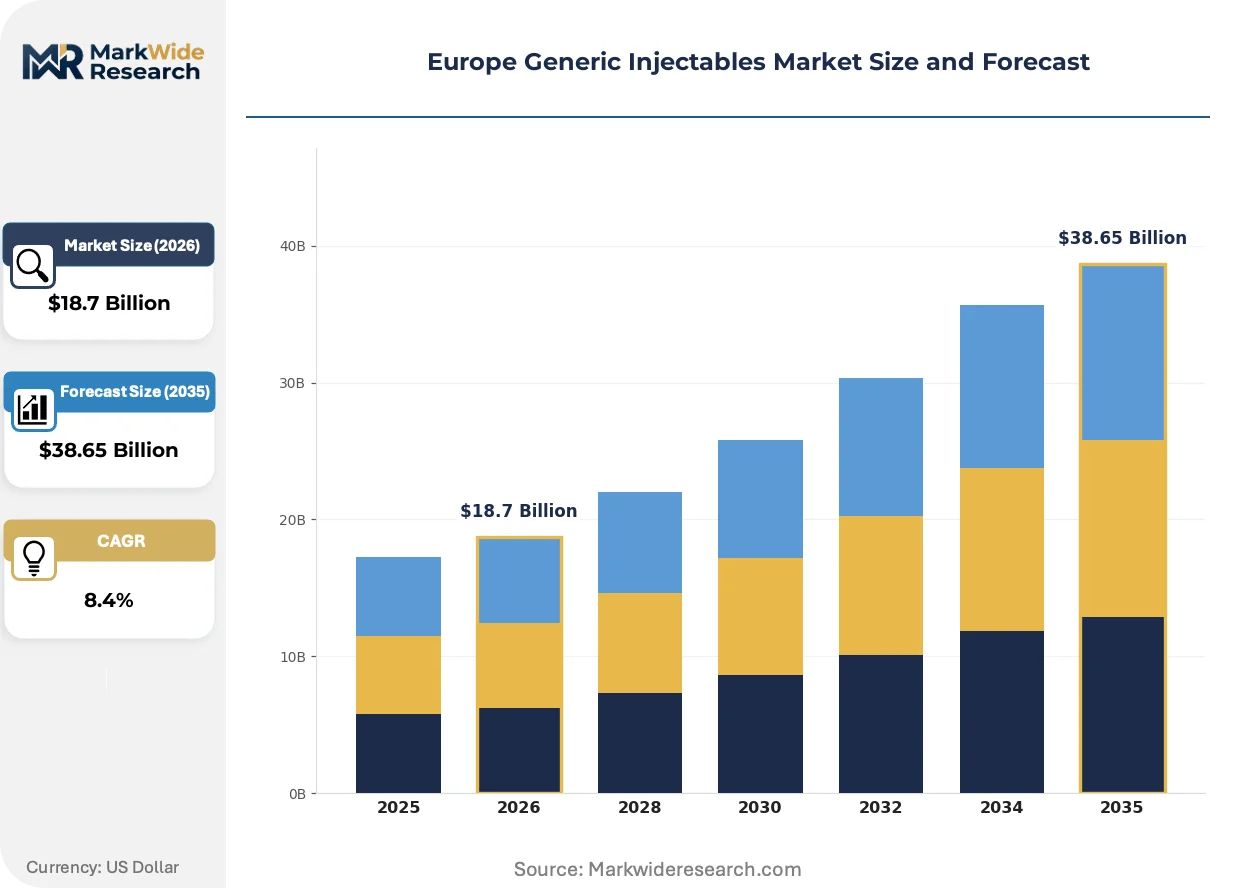
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Pre-filled Syringes, Infusion Bags Therapy Area: Oncology, Cardiovascular, Diabetes, Neurology Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Intra-articular End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers |
| Companies Covered | Novartis Pharmaceuticals Corporation, Hikma Pharmaceuticals PLC, Pfizer Inc., Viatris Inc., Dr. Reddy's Laboratories Ltd., Teva Pharmaceutical Industries Ltd., Fresenius SE & Co. KGaA, Aurobindo Pharma Limited, Baxter, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Generic Injectables Market Strategic Shifts & Innovations
Technological substitution in primary packaging and delivery systems is redrawing competitive boundaries between vial-centric and syringe-focused suppliers. Regulatory digitization and environmental compliance mandates are simultaneously elevating quality system investments and reshaping sourcing criteria.
Ready-to-administer infusion bags are displacing traditional vial-to-bag compounding in hospital pharmacy operations. Nordic and Benelux health systems are adopting these closed-system transfer devices at the fastest pace in Europe. The technology is migrating from high-cost oncology biologics into standard anti-infective and fluid replacement therapies, compressing preparation labor costs and contamination risk premiums.
EMA's strengthened environmental risk assessment requirements for marketing authorization applications are mandating expanded API manufacturing data disclosure. Generic injectable sponsors must now document aquatic toxicity and biodegradation profiles that previously applied only to novel chemical entities. Pre-filled syringe manufacturers with integrated device-drug filings face the steepest compliance burden as ECHA REACH obligations layer atop MDR technical documentation.
Hospital procurement consortia are unbundling distribution from product supply in tender structures across Germany and France. Traditional wholesale relationships are yielding to direct-to-hospital logistics contracts with specialized cold-chain handlers for temperature-sensitive parenterals. This disintermediation is most visible in Bavaria and Rhône-Alpes, where regional purchasing bodies now qualify standalone logistics providers independently of manufacturing sponsors.
Europe Generic Injectables Market Segmentation
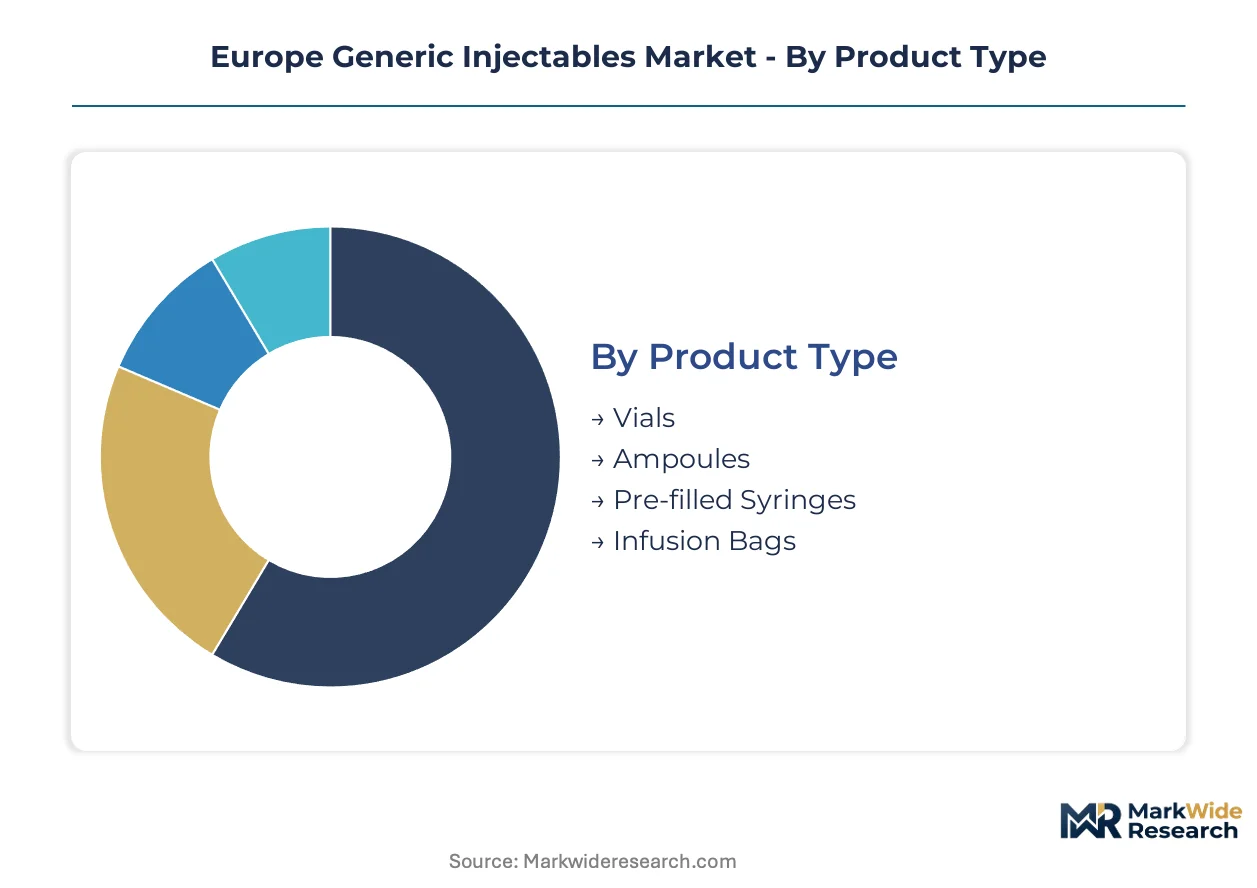
Generic injectable suppliers across Europe compete through differentiated packaging formats and delivery configurations that align with specific therapy protocols. Hospital procurement teams segment tenders by clinical application and administration route, creating distinct competitive arenas with divergent margin profiles and technical qualification requirements.
Product Type:
After-sales service intensity varies sharply across primary packaging formats, with combination products demanding integrated device support and single-unit vials requiring minimal technical follow-through.
- Vials:Multi-dose borosilicate glass containers with rubber closures dominate high-volume oncology and anesthesia applications across German hospital networks. Demand concentrates in Bavaria and North Rhine-Westphalia where centralized purchasing favors standardized multi-dose protocols over single-use alternatives.
- Pre-filled Syringes:Nested container closure systems with integrated needles or Luer-lock connectors reduce medication error rates in insulin and anticoagulant administration. Momentum accelerates in Nordic homecare programs where patient self-administration protocols require precise unit-dose delivery without pharmacy compounding steps.
- Ampoules:Single-use glass units for emergency and field applications retain niche positioning in Italian and Spanish hospital emergency departments.
- Infusion Bags:Flexible PVC or non-PVC containers for large-volume parenteral nutrition and fluid replacement therapies serve French and Benelux intensive care units.
Vials hold the largest share; momentum sits with pre-filled syringes.
Therapy Area:
Cost tier stratification separates premium-positioned oncology biologics from commoditized cardiovascular and metabolic therapies where reference pricing compresses margins.
- Oncology:Cytotoxic and supportive care injectables for chemotherapy protocols command the highest price points within generic portfolios. German hospital consortia bundle these into multi-year framework agreements that lock in volume commitments for platinum-based and taxane formulations.
- Diabetes:Insulin analogs and GLP-1 receptor agonist biosimilars delivered via subcutaneous injection are expanding beyond hospital formularies into reimbursed homecare channels across Netherlands and Denmark.
- Cardiovascular:Heparin and thrombolytic generics face intense price competition in Italian and Portuguese tender structures where multiple suppliers qualify for identical therapeutic indications.
- Neurology:Antiepileptic and migraine parenterals for acute seizure management and cluster headache protocols serve specialized hospital units with limited generic substitution to date.
Oncology commands premium positioning; diabetes is expanding most quickly into ambulatory settings.
Delivery Mode:
Application context determines route selection, with acute care favoring intravenous access and chronic disease management shifting toward patient-administered subcutaneous alternatives.
- Intravenous:Direct vascular administration for immediate bioavailability dominates anesthesia, oncology, and anti-infective applications. French and German hospital pharmacies specify IV as default route for inpatient parenteral therapy, driving demand for infusion pumps and closed-system transfer devices.
- Subcutaneous:Depot formulations and biologic biosimilars for diabetes, multiple sclerosis, and rheumatoid arthritis enable home-based administration. Swedish and Norwegian regional health authorities are reimbursing training programs that shift subcutaneous delivery from nurse-administered to patient-managed protocols.
- Intramuscular:Vaccine and long-acting antipsychotic depot injections retain established positioning in public health and psychiatric service delivery.
- Intra-articular:Corticosteroid and hyaluronic acid injections for osteoarthritis management serve orthopedic and rheumatology outpatient clinics with limited generic penetration.
Intravenous generates the largest revenue pool; subcutaneous is gaining share fastest through homecare expansion.
End User:
Customer type segmentation separates capital-intensive hospital purchasers from dispersed clinic and homecare channels with divergent logistics and cold-chain requirements.
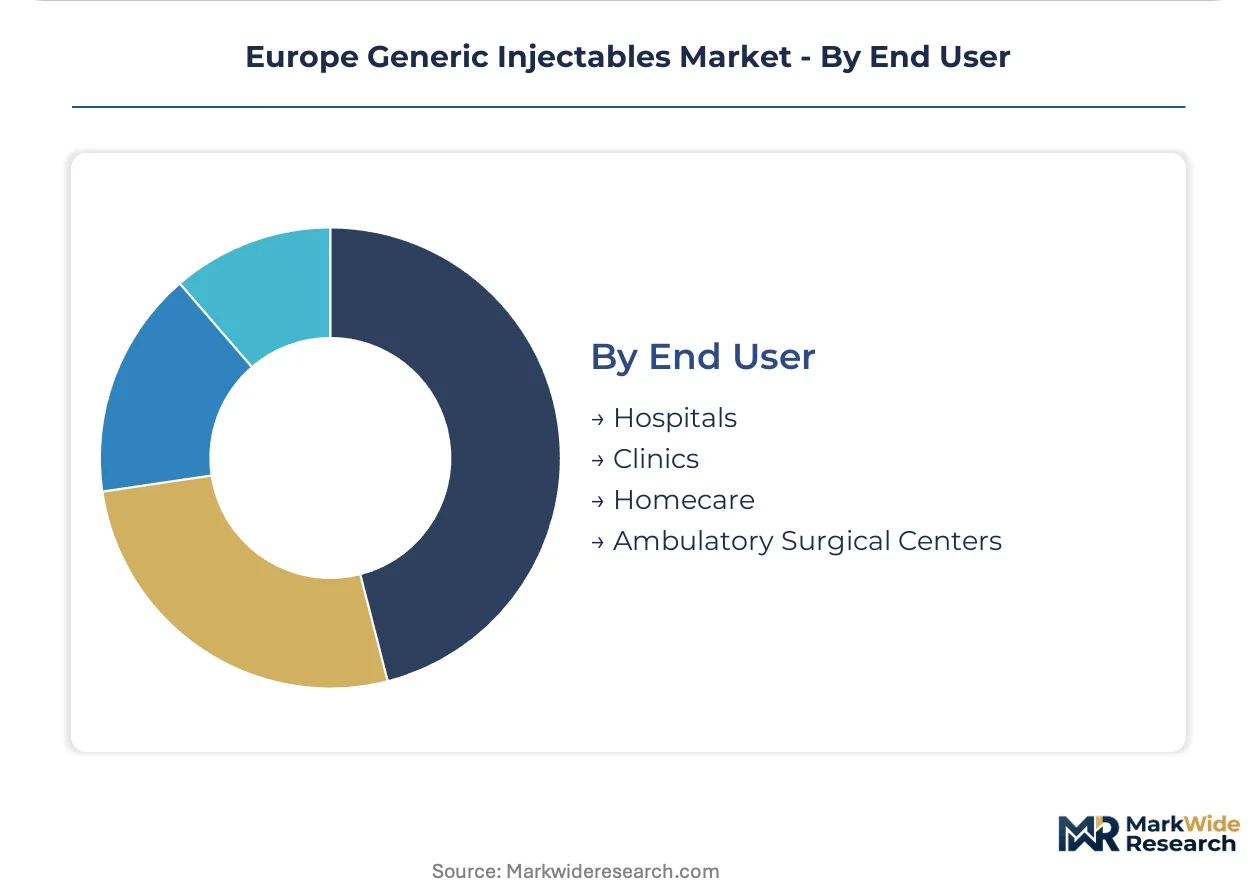
- Hospitals:Acute care institutions with centralized pharmacy operations and formulary committees represent the dominant procurement channel for high-volume parenteral generics. Rhône-Alpes and Lombardy regional purchasing bodies aggregate demand across multiple hospital sites to extract volume discounts from anesthesia and oncology suppliers.
- Homecare:Specialized infusion services and patient self-administration programs for subcutaneous biologics are expanding in Netherlands, Belgium, and Denmark where reimbursement supports nursing visits and delivery logistics.
- Clinics:Outpatient dialysis, oncology day units, and rheumatology centers purchase smaller lot sizes with less stringent cold-chain infrastructure than hospital central pharmacies.
- Ambulatory Surgical Centers:Same-day procedure facilities in Germany and Switzerland require rapid-turn anesthesia and analgesic injectables with minimal inventory carrying costs.
Hospitals retain the dominant volume position; homecare shows the steepest expansion trajectory as chronic disease protocols migrate beyond institutional settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA approval pathways anchor European generic injectable distribution, with national procurement bodies translating centralized authorizations into volume contracts. Hospital purchasing consolidation across Germany, France, and Italy compresses margins while amplifying scale requirements for sterile parenteral suppliers.
Germany
Centralized hospital procurement through regional purchasing bodies like Rhön-Klinikum and Vivantes drives volume concentration for anesthesia and oncology injectables. The German Social Code Book V (SGB V) mandates reference pricing for off-patent medicines, accelerating therapeutic substitution in hospital formularies. Bavaria and North Rhine-Westphalia host the densest clusters of sterile manufacturing capacity, with isolator-based fill-finish operations concentrated around Frankfurt and Munich.
France
Regional health agencies (ARS) bundle hospital demand through unified tender platforms, favoring multi-year framework agreements for anti-infective and fluid replacement parenterals. ANSM enforces stringent batch release protocols for sterile products, extending qualification timelines for new generic entrants. The Rhône-Alpes corridor around Lyon maintains specialized lyophilization capacity for unstable oncology formulations serving pan-European distribution.
Italy
Lombardy and Emilia-Romagna regional governments have designated dedicated manufacturing zones for sterile injectable production, attracting contract manufacturing investment from mid-scale European suppliers. The Italian Medicines Agency (AIFA) coordinates with EMA on centralized marketing authorizations while maintaining national pricing negotiation procedures. Milan's pharmaceutical cluster hosts advanced aseptic processing facilities targeting German and Benelux procurement consortia.
Netherlands
Hospital procurement through Zorgverzekeraars Nederland and regional preferred provider networks emphasizes ready-to-administer infusion systems for oncology and parenteral nutrition. The Dutch Healthcare Authority (NZa) monitors pricing transparency for generic medicines, limiting excessive margin extraction on established parenteral therapies. Rotterdam's logistics hub serves as the primary distribution gateway for temperature-sensitive injectables entering Nordic markets.
Spain
Regional health services in Catalonia and Madrid aggregate hospital demand through centralized purchasing platforms, though fragmentation across autonomous communities limits pan-Spanish volume concentration. The Spanish Agency for Medicines and Health Products (AEMPS) implements EMA guidelines with additional national stability testing requirements for imported generic injectables. Barcelona's pharmaceutical manufacturing base specializes in high-volume anti-infective parenterals for Southern European tender markets.
Europe Generic Injectables Market Key Industry Players
Capability concentration sits with specialized sterile manufacturers possessing isolator-based aseptic processing expertise; scale advantage sits with diversified pharmaceutical conglomerates leveraging integrated hospital channel networks. The market structures around three tiers: global diversified majors with legacy hospital relationships, mid-scale European specialists with regional manufacturing footprints, and emerging contract manufacturers exploiting underutilized Southern European capacity. Dominant competitive moves include backward integration into active pharmaceutical ingredient sourcing and strategic partnerships with automated packaging technology providers.
Among the diversified pharmaceutical conglomerates, Novartis Pharmaceuticals Corporation, Pfizer Inc., and Fresenius SE & Co. KGaA exemplify the scale-driven tier, occupying positions anchored by established hospital formulary access and pan-European distribution infrastructure. These entities represent the consolidation endpoint for procurement bodies seeking single-source accountability across multiple therapeutic categories. Mid-scale specialists including Hikma Pharmaceuticals PLC and Viatris Inc. sit within a differentiated positioning tier, emphasizing cost-competitive manufacturing configurations and targeted therapy area depth. Teva Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd. exemplify the emerging market-originated challengers expanding European footprint through portfolio breadth and aggressive tender participation. Aurobindo Pharma Limited and Baxter occupy intermediate positions, with the former representing Indian-origin vertical integration models and the latter exemplifying device-drug combination specialization.
| Leading Market Players |
|---|
| Novartis Pharmaceuticals Corporation |
| Hikma Pharmaceuticals PLC |
| Pfizer Inc. |
| Viatris Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Fresenius SE & Co. KGaA |
| Aurobindo Pharma Limited |
| Baxter |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp corridor freight dynamics amplify cost differentials between German hospital consortia and Southern European tender markets, concentrating pricing power among fill-finish operators with captive Iberian capacity while forcing margin compression on suppliers dependent on Asian API transit.
Pricing Analysis
Geographic price spreads of 15-25% separate Nordic ready-to-administer infusion bag premiums from Portuguese anti-infective vial tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by EMA certification tier and batch release jurisdiction, with ANSM-enforced French protocols commanding highest qualification premiums. Pricing pressure stems from German reference pricing mandates under SGB V that accelerate therapeutic substitution. Hospital procurement consortia in Bavaria exhibit lowest price sensitivity due to bundled framework agreements, while Spanish regional health services show highest sensitivity amid autonomous community fragmentation.
Supply Chain Analysis
Contract manufacturing concentration sits with Fresenius Kabi's German isolator networks, Hikma's Portuguese fill-finish facilities, and Baxter's Swiss device-drug integration plants. API sourcing draws from concentrated Indian and Chinese manufacturing for oncology and anesthesia actives, with borosilicate glass and rubber closures tethered to German and Italian component suppliers. Single-source vulnerability in Asian API supply exposes European fill-finish operations to customs delays and geopolitical disruption. Distribution runs through direct-to-hospital logistics contracts with specialized cold-chain handlers displacing traditional wholesale relationships across Rhône-Alpes and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic biosimilar substitution threatens incumbent generic parenteral franchises as EMA accelerated approval pathways shorten time-to-market for sterile biologic entrants, forcing defensive repositioning across anesthesia and oncology portfolios.
For Market Incumbents: Harden formulary lock-in through multi-year framework agreements with German regional purchasing bodies that bundle anesthesia, oncology, and anti-infective injectables into single-source accountability structures. Deepen backward integration into API sourcing for critical cytotoxic actives to mitigate Asian supply concentration risk. Invest in isolator-based aseptic processing automation to offset qualified technician scarcity constraining Southern European capacity expansion. For New Entrants and Emerging Players: Build out underutilized Portuguese sterile manufacturing capacity to serve Benelux and Nordic procurement consortia seeking cost-competitive anti-infective fill-finish alternatives to established German suppliers. Target Lombardy manufacturing cluster incentives for greenfield aseptic processing investment serving pan-European hospital networks. Pursue EMA centralized marketing authorization pathways for critical parenteral medicines addressing documented hospital formulary shortages. For Investors and Strategic Acquirers: EU Pharmaceutical Legislation revision reshapes the acquisition landscape by elevating environmental risk assessment capabilities and accelerated approval expertise as premium valuation drivers. Mid-scale European specialists with isolator-based manufacturing and established EMA rapporteur relationships offer strongest 5-10 year viability within tightening regulatory frameworks. Monitor EMA marketing authorization application backlogs for critical parenteral therapy categories as inflection indicator for shortage-driven pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Captive supply of oncology actives insulates German fill-finish operations from Asian customs disruption. |
| Isolator-Based Aseptic Automation | Robotic processing offsets qualified technician scarcity constraining Portuguese and Italian capacity expansion. |
| EMA Critical Parenteral Pathway | Accelerated approval for shortage-listed medicines compresses time-to-revenue for sterile generic entrants. |
| Direct-to-Hospital Logistics Contracts | Bypassing wholesale intermediaries captures margin from Bavaria and Rhône-Alpes regional purchasing consolidation. |
| Pre-Filled Syringe Device Integration | MDR-compliant combination products command premium positioning in Nordic homecare reimbursement channels. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EMA marketing authorization databases, hospital procurement tender platforms, and REACH compliance filings. Primary interviews engaged sterile manufacturing executives, hospital pharmacy directors, regulatory affairs specialists, and GPO contracts managers across German, French, and Italian markets. Secondary validation incorporated ANSM batch release protocols, AIFA pricing negotiation records, and customs trade data for API import flows. Bottom-up demand modeling from hospital formulary audits triangulates against top-down market sizing from manufacturer capacity disclosures.
Forecast inputs encompass therapy area substitution rates, regional procurement consolidation trajectories, and regulatory pathway duration across the analysis window. Segmentation dimensions include primary packaging format, administration route, end-user channel, and national regulatory cluster. CAGRs derive from volume-weighted average of segment growth rates adjusted for pricing erosion assumptions. Industry-specific inputs incorporate EMA environmental risk assessment implementation timelines and MDR device-drug recertification backlogs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian-origin challengers or accelerated biologic biosimilar substitution would shift outcomes beyond projected ranges. Quarterly review of EMA critical medicines shortage lists, German hospital tender award announcements, and API import customs delays is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Global Biosimilars Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Dasatinib Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
US Biosimilars Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Global Sirolimus Market
Biosimilars
Pegfilgrastim Biosimilar Market