
 Pegfilgrastim Biosimilar Market | 2026-2036
Pegfilgrastim Biosimilar Market Size, Share, and Industry Trends Forecast 2026-2036
Pegfilgrastim Biosimilar Market Outlook
The capital-intensity divergence between large-scale biomanufacturers and emerging biosimilar developers is rotating competitive advantage toward integrated production networks. Coherus BioSciences leverages its vertically controlled biologics manufacturing to sustain price leadership in U.S. oncology channels. Fresenius Kabi anchors European hospital contracts through dedicated fill-finish capacity for prefilled syringe formats. Pfizer competes across multiple geographies with established cold-chain logistics that extend distribution reach into community clinic settings.
Pegfilgrastim biosimilars are recombinant granulocyte colony-stimulating factor (G-CSF) proteins conjugated with polyethylene glycol to prolong serum half-life, produced through mammalian cell culture and purified via multi-step chromatography for subcutaneous administration in chemotherapy-induced neutropenia. The biosimilar segment dominates volume as reference product erosion accelerates in mature markets, while next-generation biosimilars concentrate margin pools through improved delivery device integration. Prefilled syringe formats lead delivery mode adoption due to reduced pharmacy preparation burden and lower infection risk in hospital outpatient units.
FDA interchangeability designation pathways, EMA biosimilar comparability guidelines, and WHO prequalification standards collectively shape market access timelines and prescriber confidence in substitution policies. The IRA Medicare price negotiation provisions for reference biologics are compressing originator pricing floors and expanding biosimilar volume eligibility in U.S. federal reimbursement channels. Stakeholders must monitor evolving pharmacovigilance requirements and real-world evidence mandates that determine post-approval commercial traction across regulated markets.
Market Dynamics
IRA Medicare price negotiation provisions for reference biologics are compressing originator pricing floors and accelerating biosimilar volume eligibility in U.S. federal reimbursement channels, forcing manufacturers to compete on manufacturing scale and cold-chain reliability rather than clinical differentiation alone.
Growth Catalysts
- FDA Interchangeability Pathways:Designation standards now permit pharmacy-level substitution without prescriber intervention, expanding automatic dispensing in oncology outpatient settings and reducing administrative friction for biosimilar uptake.
- Prefilled Syringe Adoption:Hospital outpatient units are migrating from vial-and-syringe preparation to ready-to-administer formats, cutting pharmacy compounding burden and infection risk while shortening patient throughput times.
- EMA Biosimilar Comparability Guidelines:Streamlined analytical comparability requirements for well-characterized biologics are compressing development timelines and reducing residual uncertainty for developers with established mammalian cell culture platforms.
Market Restraints
- Mammalian Cell Culture Input Concentration:Single-use bioreactor bags and serum-free media supply chains concentrate among three dominant suppliers, exposing manufacturers to input cost volatility and allocation constraints during demand surges.
- Immunogenicity Surveillance Burden:Post-marketing pharmacovigilance requirements for anti-drug antibody monitoring impose persistent data collection obligations that scale with patient volume and complicate label expansion efforts.
- Reference Product Patent Thickets:Remaining formulation and process patents on originator pegfilgrastim create licensing complexity that delays launch timing and erodes effective exclusivity periods for first-wave biosimilars.
Strategic Opportunities
- Community Oncology Clinic Penetration:Independent oncology practices in the United States remain underpenetrated relative to hospital outpatient departments, presenting volume expansion potential for distributors with direct-to-clinic cold-chain capabilities.
- On-Body Injector Convergence:Integration of pegfilgrastim biosimilars with wearable delivery devices addresses patient adherence gaps in home administration settings and commands premium positioning against conventional syringe formats.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive framework for biopharmaceuticals is attracting fill-finish capacity investments that could reposition the country as an export hub for prefilled syringe supply to emerging markets.
Industry Challenges
- Analytical Method Transfer Complexity:Migrating complex multi-attribute method suites between development and commercial quality control sites requires 18-24 month validation timelines that compress launch windows.
- Cold-Chain Infrastructure Capex:Maintaining 2-8°C distribution integrity through last-mile oncology clinic delivery demands refrigerated vehicle fleet expansion and real-time temperature monitoring systems that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pegfilgrastim Biosimilar Market |
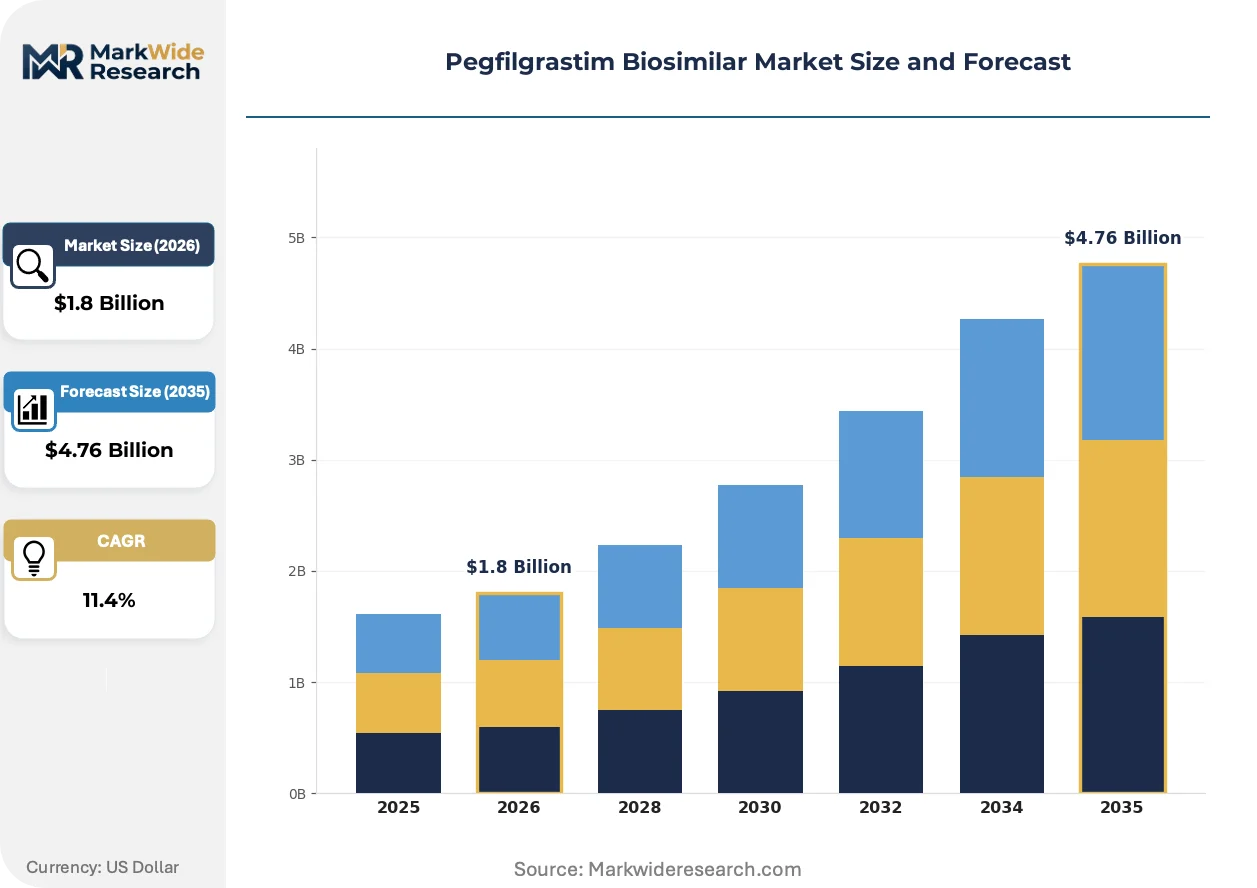
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reference Product, Biosimilar, Differentiated Product, Next-Generation Biosimilar Application: Chemotherapy, Autoimmune Disorders, Neutropenia Management, Hematological Cancers Delivery Mode: Injectable, Subcutaneous, Intravenous, Prefilled Syringe End User: Hospitals, Research Institutions, Clinics, Home Healthcare |
| Companies Covered | Biocon, Teva Pharmaceutical Industries Ltd., Mylan N.V., Dr. Reddy's Laboratories, Fresenius Kabi, Coherus BioSciences, Pfizer, Intas Pharmaceuticals, Sandoz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pegfilgrastim Biosimilar Market Strategic Shifts
Delivery device integration and regulatory data harmonization are compressing competitive differentiation timelines, forcing developers to concentrate R&D expenditure on patient-administration experience rather than molecular engineering alone.
On-body injector systems for pegfilgrastim administration are miniaturizing pump mechanisms and electronic controls to enable discreet patient-worn delivery over 45-minute infusion windows. Community oncology clinics in the United States are piloting these devices for neutropenia prophylaxis in curative-intent chemotherapy regimens. The technology is miniaturizing hardware requirements to sub-50 gram form factors that displace conventional syringe-based administration in convenience-sensitive patient segments.
EMA's revised biosimilar guideline on immunogenicity assessment now permits extrapolation of anti-drug antibody data across indications when analytical similarity is robustly demonstrated, reducing redundant clinical study requirements. Developers with existing pegfilgrastim approvals are leveraging this framework to accelerate label expansion into pediatric febrile neutropenia prophylaxis. European hospital formularies are responding by consolidating purchasing across adult and pediatric indications under single contract structures.
Hospital procurement committees are consolidating biosimilar sourcing decisions under centralized pharmacy and therapeutics committees, displacing individual prescriber discretion in product selection. Group purchasing organizations are capturing aggregate volume commitments from health systems that span multiple states, extracting price concessions in exchange for sole-source or dual-source formulary placement. This concentration is most visible in the United States, where three national GPOs now control biosimilar access for over 60 percent of acute-care hospital beds.
Pegfilgrastim Biosimilar Market Segmentation
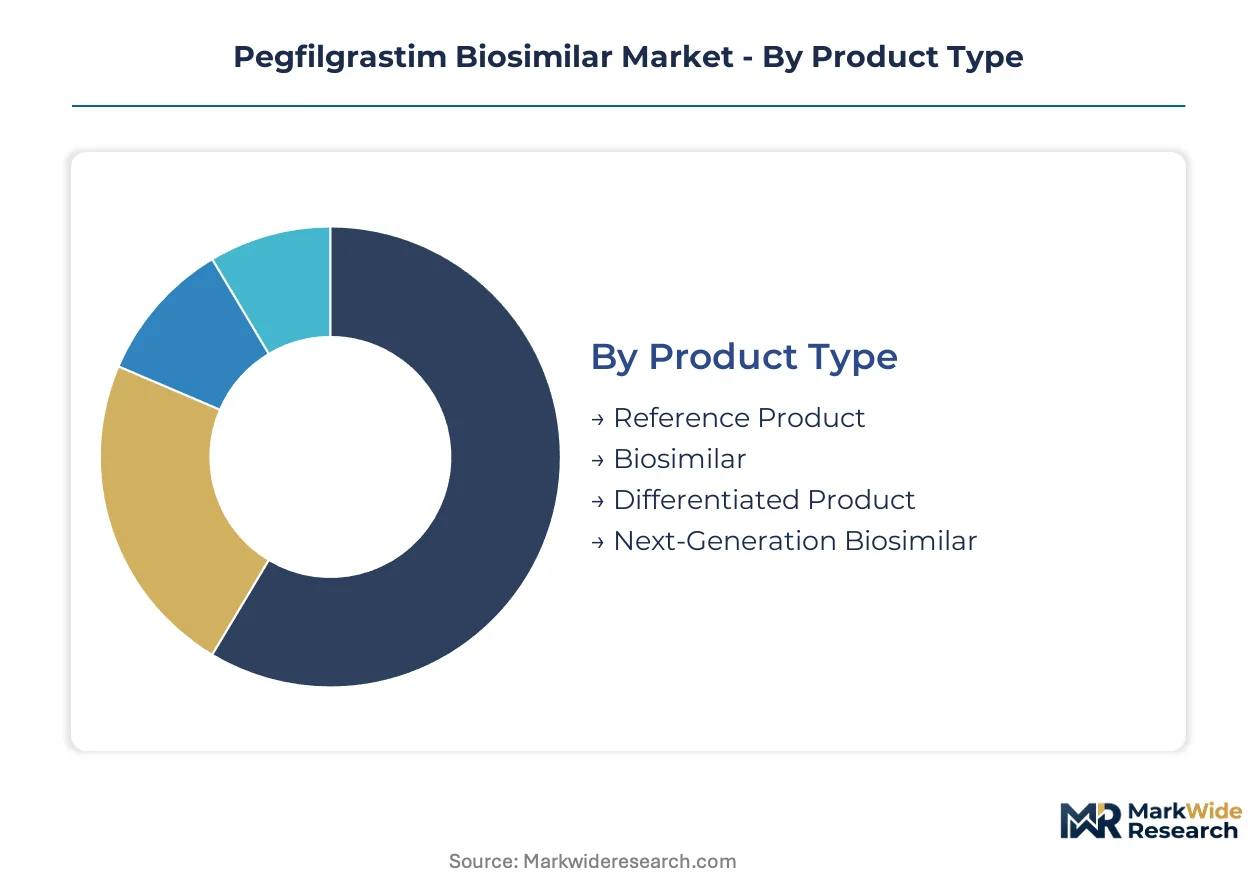
Pegfilgrastim biosimilar segmentation reveals how regulatory pathways, delivery technologies, and care settings fragment commercial opportunity. Each dimension carries distinct margin profiles and access barriers that determine competitive positioning across oncology markets.
Product Type:
FDA interchangeability designation and EMA biosimilar comparability protocols create tiered market access tiers that stratify pricing power and substitution eligibility.
- Biosimilar:Recombinant G-CSF proteins demonstrating analytical similarity to reference pegfilgrastim through rigorous comparability studies. Hospital outpatient departments in the United States and Germany concentrate procurement volume here as formulary substitution policies mature and IRA Medicare provisions expand reimbursement eligibility.
- Next-Generation Biosimilar:Advanced formulations integrating improved delivery devices or modified pharmacokinetic profiles beyond basic biosimilarity requirements. Community oncology clinics and home healthcare settings in North America drive adoption as patient convenience and adherence become purchasing criteria.
- Reference Product:Originator pegfilgrastim facing accelerating volume erosion as regulatory exclusivities expire and biosimilar penetration deepens.
- Differentiated Product:Novel constructs with substantiated clinical differentiation claims, occupying niche positioning where biosimilar substitution is restricted.
Biosimilar handles the majority of throughput; next-generation biosimilar is the fastest mover on share.
Application:
Clinical indication breadth determines addressable patient populations and pharmacovigilance burden across regulated markets.
- Chemotherapy:Prophylaxis against febrile neutropenia in myelosuppressive cancer regimens, representing the foundational use case for pegfilgrastim across all product generations. Academic medical centers and comprehensive cancer networks in the United States, Germany, and India anchor demand as curative-intent treatment volumes expand.
- Neutropenia Management:Broad-spectrum prophylaxis and treatment of chemotherapy-induced neutropenia across diverse oncology protocols. European hospital systems leverage EMA immunogenicity extrapolation guidelines to consolidate purchasing across adult and pediatric indications.
- Hematological Cancers:Specialized protocols for leukemia and lymphoma patients requiring intensive myelosuppressive therapy.
- Autoimmune Disorders:Off-label and investigational applications in severe autoimmune neutropenia, capturing limited but high-value prescribing.
Chemotherapy commands the dominant patient volume; neutropenia management is climbing the fastest as indication labeling broadens.
Delivery Mode:
Administration format selection hinges on pharmacy compounding capacity, infection control protocols, and patient self-administration readiness.
- Prefilled Syringe:Ready-to-administer single-dose presentations eliminating vial reconstitution and reducing medication errors. Hospital outpatient units and community oncology clinics in the United States and Europe prioritize this format for throughput efficiency and reduced pharmacy labor burden.
- Injectable:Conventional vial-based presentations requiring healthcare professional preparation, retaining relevance in cost-constrained settings and institutional procurement.
- Subcutaneous:The established route of administration for pegfilgrastim, compatible with both prefilled syringe and on-body injector configurations.
- Intravenous:Limited applications where subcutaneous delivery is contraindicated, representing minimal commercial share.
Prefilled syringe carries the highest volume trajectory; subcutaneous remains the standard route across all formats.
End User:
Care setting economics and reimbursement mechanisms concentrate purchasing power among institutional buyers with cold-chain infrastructure.
- Hospitals:Integrated health systems with centralized pharmacy and therapeutics committees controlling formulary access for acute and outpatient oncology services. Group purchasing organizations in the United States aggregate demand across multi-state health systems, extracting price concessions through sole-source or dual-source contracts.
- Clinics:Independent and hospital-affiliated oncology practices administering chemotherapy in ambulatory settings. Community oncology clinics represent underpenetrated volume relative to hospital outpatient departments, particularly for biosimilar products with direct-to-clinic distribution capabilities.
- Home Healthcare:Emerging channel for on-body injector and prefilled syringe administration, supported by specialty pharmacy networks and remote patient monitoring.
- Research Institutions:Academic medical centers conducting clinical trials and investigator-initiated studies, generating limited commercial volume but influencing prescribing patterns.
Hospitals dominate procurement volume; clinics are expanding most quickly as site-of-care shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States oncology clinics prioritize prefilled syringe convenience and FDA interchangeability, while European hospital systems emphasize EMA-guided analytical comparability, and Indian manufacturers exploit PLI scheme incentives to build export-oriented fill-finish capacity.
United States
Hospital outpatient departments and community oncology clinics drive prefilled syringe adoption as IRA Medicare price negotiations compress originator pricing floors. FDA interchangeability designations enable pharmacy-level substitution without prescriber intervention. The Greater Boston biopharma corridor anchors cold-chain distribution infrastructure serving Northeast corridor health systems.
Germany
Academic medical centers in Baden-Württemberg and Bavaria consolidate purchasing through centralized pharmacy committees under EMA biosimilar comparability guidelines. Hospital formularies leverage immunogenicity data extrapolation across adult and pediatric indications. The Rhine-Main metropolitan region concentrates fill-finish contract manufacturing for European hospital networks.
India
Domestic oncology volume expansion and export manufacturing incentives reshape competitive positioning through CDSCO regulatory pathways. PLI scheme subsidies attract biopharmaceutical investments in Karnataka and Telangana. Hyderabad's biotech corridor hosts multiple mammalian cell culture facilities targeting prefilled syringe supply to emerging markets.
United Kingdom
NHS England procurement frameworks accelerate biosimilar uptake through national tendering mechanisms that aggregate hospital demand. MHRA post-Brexit regulatory autonomy maintains alignment with EMA scientific standards while streamlining UK-specific approval timelines. The Oxford-Cambridge-London golden triangle concentrates clinical trial infrastructure supporting label expansion efforts.
Japan
PMDA biosimilar guidelines emphasize extensive clinical comparability studies that extend development timelines but build prescriber confidence in substitution policies. Hospital reimbursement mechanisms under universal health coverage prioritize cost containment through biosimilar volume incentives. The Kansai region's pharmaceutical manufacturing base supplies domestic oncology networks with cold-chain verified products.
Pegfilgrastim Biosimilar Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with manufacturing scale and cold-chain reliability separating competitive positions. Coherus BioSciences leverages vertically controlled biologics production to sustain price leadership in U.S. oncology channels. Fresenius Kabi anchors European hospital contracts through dedicated fill-finish capacity. Strategic moves concentrate on backward integration into mammalian cell culture inputs and geographic expansion through regulatory filing synchronization across FDA, EMA, and WHO pathways.
Among integrated biomanufacturers, Coherus BioSciences represents the vertically controlled production archetype, while Fresenius Kabi exemplifies European hospital-centric positioning through dedicated fill-finish infrastructure. Pfizer occupies a position spanning multiple geographies with established cold-chain logistics. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Biocon |
| Teva Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Dr. Reddy's Laboratories |
| Fresenius Kabi |
| Coherus BioSciences |
| Pfizer |
| Intas Pharmaceuticals |
| Sandoz |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between U.S. hospital systems and integrated biomanufacturers lock in prefilled syringe supply commitments while anchoring price visibility against IRA Medicare price negotiation volatility. These contracts bundle cold-chain distribution with volume guarantees, compressing spot market participation and concentrating procurement leverage among group purchasing organizations.
Pricing Analysis
Contract-based long-term offtake dominates hospital procurement, with pricing stratifying across interchangeability designation tier, delivery device sophistication, and manufacturing scale. FDA-designated interchangeable products command premium positioning against standard biosimilars, while cost compression in standard-tier products intensifies as Indian manufacturers exploit PLI scheme subsidies. Community oncology clinics exhibit highest price sensitivity due to limited cold-chain infrastructure investment capacity.
Supply Chain Analysis
Inventory buffers for single-use bioreactor bags and serum-free media concentrate among three dominant suppliers, extending lead times during demand surges. Mammalian cell culture inputs draw from the United States, Germany, and India, with fill-finish capacity expanding in Hyderabad's biotech corridor and the Rhine-Main region. Single-source vulnerability in specialized chromatography resins exposes manufacturers to allocation constraints. Distribution runs through temperature-controlled logistics networks serving hospital outpatient departments and community oncology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
On-body injector miniaturization and FDA interchangeability pathway maturation are disrupting competitive dynamics, compressing differentiation timelines and elevating manufacturing scale as the decisive capability.
For Market Incumbents: Compound backward integration into mammalian cell culture inputs to secure supply against single-source concentration risks in bioreactor bag and serum-free media markets. Expand fill-finish capacity in Hyderabad or the Rhine-Main region to capture PLI scheme benefits and European hospital contract consolidation. Cold-chain reliability investments anchor GPO contract renewals against emerging Indian exporters. For New Entrants and Emerging Players: Community oncology clinic direct-to-clinic distribution gaps offer white-space penetration where hospital-affiliated networks under-serve independent practices. Target on-body injector convergence for home administration settings, leveraging specialty pharmacy partnerships to bypass hospital formulary gatekeepers. CDSCO regulatory pathway synchronization with FDA and EMA filings accelerates multi-market entry. For Investors and Strategic Acquirers: CDSCO-authorized manufacturers with established mammalian cell culture platforms and prefilled syringe fill-finish capacity represent acquisition targets with export-oriented positioning. Long-term viability hinges on regulatory filing synchronization capabilities and immunogenicity surveillance infrastructure. Watch for EMA immunogenicity extrapolation guideline expansion into pediatric indications as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Vertically controlled biologics production secures price leadership in U.S. oncology channels against IRA compression. |
| Regulatory Approval Pathway | FDA interchangeability designation enables pharmacy-level substitution without prescriber intervention in hospital outpatient settings. |
| Backward Integration | In-house mammalian cell culture capacity reduces exposure to single-use bioreactor bag supply concentration among three dominant suppliers. |
| Long-term Supply Agreement | Group purchasing organization contracts spanning multi-state health systems aggregate volume and extract price concessions. |
| Geographic Expansion | PLI scheme manufacturing incentives in Karnataka and Telangana reposition India as export hub for emerging market prefilled syringe supply. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down market sizing triangulated against manufacturer capacity disclosures and GPO contract aggregation data.
Across the projection horizon, the analytical framework modeled segmentation across product type, delivery mode, end user, and regional regulatory cluster. CAGRs derived from patient volume trajectories, biosimilar penetration curves, and reimbursement policy shifts. Forecast inputs incorporated IRA Medicare price negotiation provisions, EMA immunogenicity extrapolation guideline adoption rates, and PLI scheme capacity investment timelines.
Underlying assumptions cover regulatory pathway maturation and manufacturing scale realization, with deviation risk concentrated in single-source input supply disruptions and interchangeability designation timeline delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Global Tofacitinib Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Global Sirolimus Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
US Biosimilars Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Etanercept Market
Biosimilars
Global Biosimilars Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Europe Biosimilars Market