
 Imatinib Drug Market | 2026-2036
Imatinib Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Imatinib Drug Market Analysis
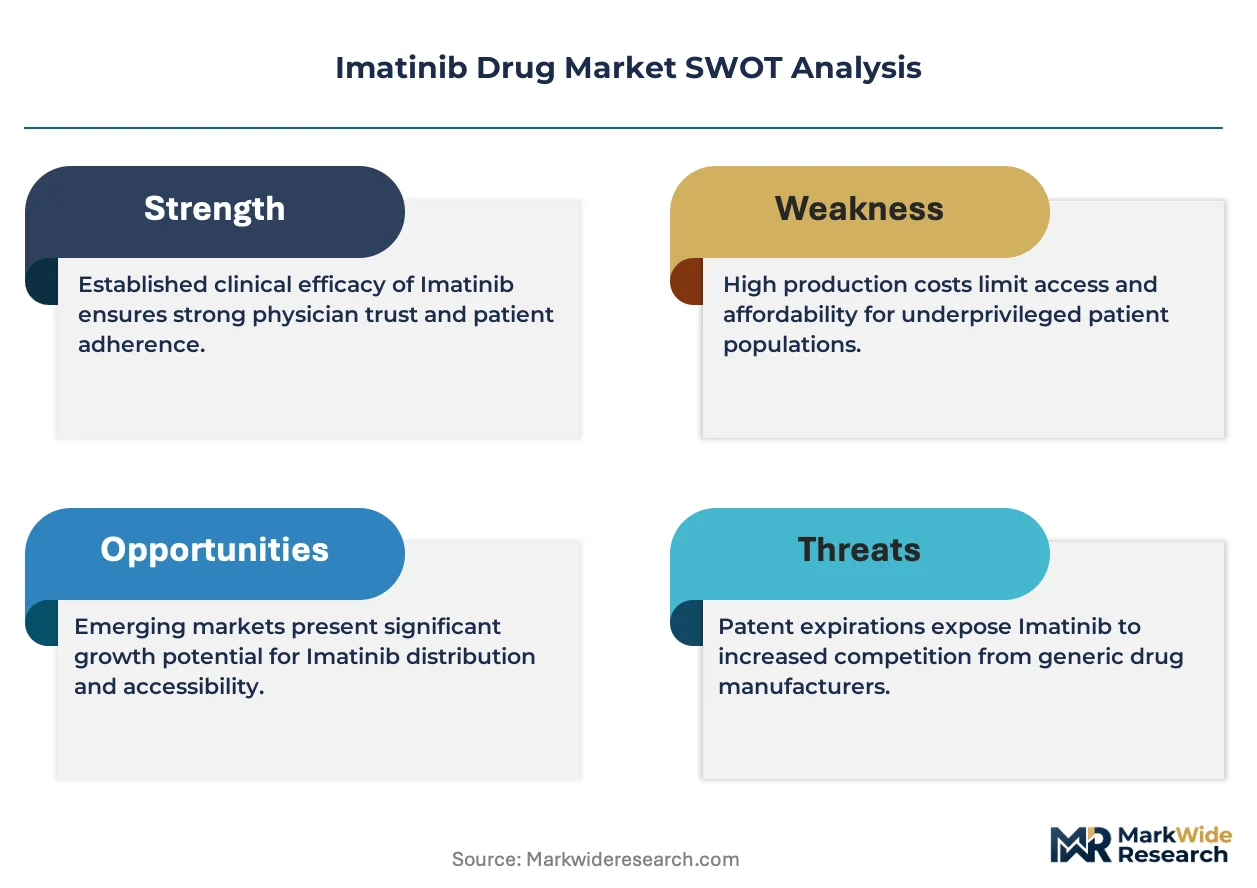
Capital-intensity divergence between originator and generic manufacturing footprints is bifurcating competitive dynamics in imatinib supply. Novartis sustains proprietary formulation expertise and regulatory dossier depth across high-barrier markets. Sun Pharmaceutical Industries leverages vertically integrated API-to-finished-dose operations in India to command cost structures that Western generics cannot replicate. Teva Pharmaceutical Industries anchors its position through established hospital tender networks in Europe and North America.
Imatinib mesylate functions as a selective tyrosine kinase inhibitor that blocks the BCR-ABL fusion protein driving chronic myeloid leukemia proliferation, typically administered as 100 mg or 400 mg oral tablets. The drug's primary commercial purpose centers on first-line and salvage therapy for Philadelphia chromosome-positive malignancies, with dosing protocols extending across indefinite maintenance regimens. Tablet formulations occupy the dominant volume position due to patient familiarity and reimbursement alignment with chronic oral therapy models. Gastrointestinal stromal tumor applications represent a faster-growing therapy area as adjuvant prescribing protocols expand post-surgical guidelines. Oncology centers capture the most concentrated margin pool through bundled care pathways that integrate drug procurement with diagnostic monitoring services.
FDA bioequivalence standards and EMA quality guidelines govern generic substitution thresholds, while India's CDSCO regulates export batch certification for domestic manufacturers serving regulated markets. These frameworks determine which suppliers gain formulary access versus remaining confined to non-regulated channels. Stakeholders must monitor evolving pharmacovigilance reporting obligations and traceability mandates as serialization requirements tighten across distribution networks.
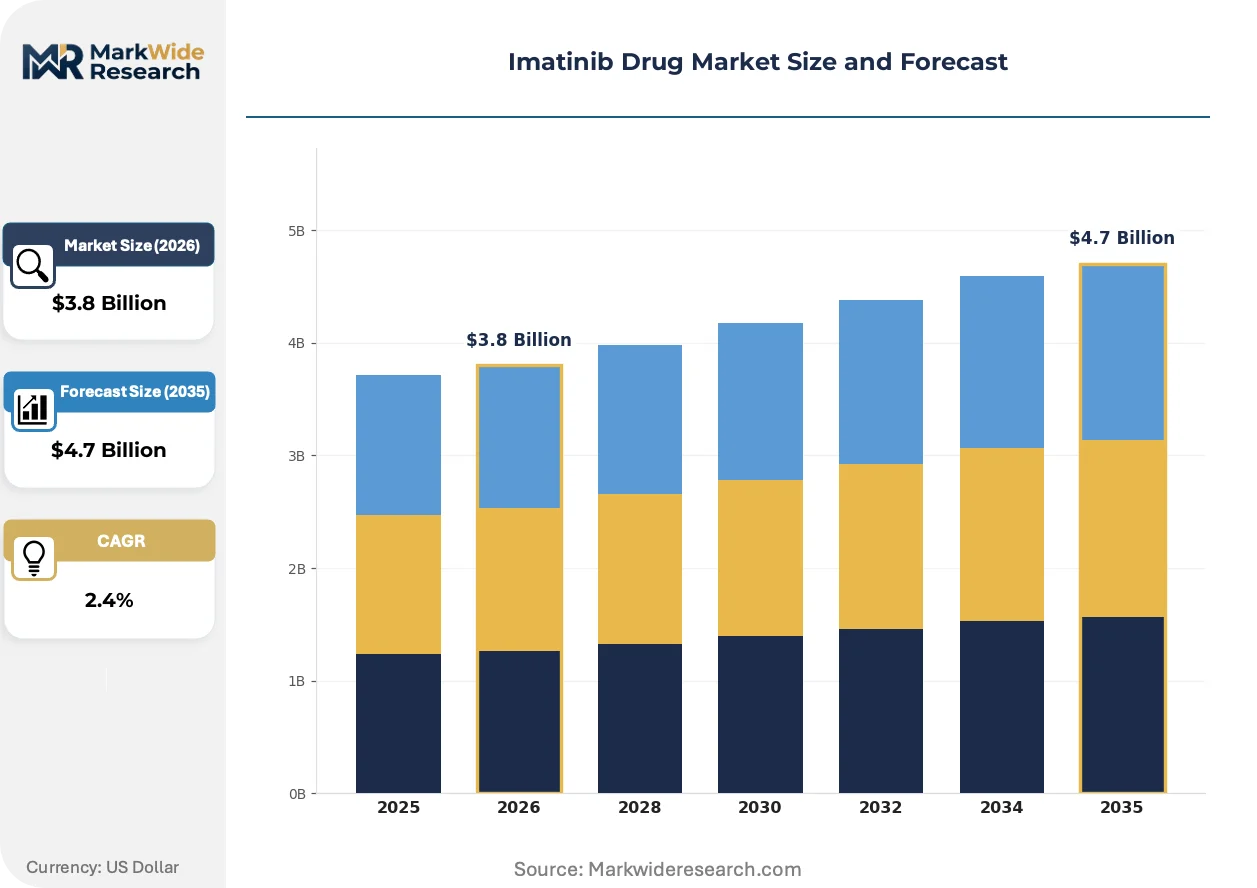
Market Dynamics
Patent cliff dynamics are fragmenting the imatinib value chain as originator formulations lose exclusivity and generic manufacturers capture procurement volume across regulated and emerging markets simultaneously.
Growth Catalysts
- EMA bioequivalence pathways:Accelerated generic approval frameworks in Germany and France are compressing substitution timelines and expanding formulary access for chronic myeloid leukemia patients.
- API manufacturing clustering:Gujarat and Hyderabad production zones in India are achieving cost structures below Western competitors through captive intermediate supply and batch scale efficiencies.
- Chronic therapy protocols:Indefinite maintenance regimens for Philadelphia chromosome-positive malignancies are creating predictable, recurring demand that stabilizes procurement planning for oncology centers.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India control over 70% of global tyrosine kinase inhibitor intermediate supply, creating single-source vulnerability for European and North American formulators.
- FDA bioequivalence testing costs:Complex pharmacokinetic study requirements for 400 mg tablet formulations impose six-figure validation burdens that exclude smaller generic entrants from US market participation.
- Next-generation TKI substitution:Dasatinib and nilotinib frontline protocols in academic medical centers are compressing imatinib share in newly diagnosed chronic myeloid leukemia cases.
Strategic Opportunities
- Brazilian adjuvant GIST expansion:ANVISA oncology guideline updates are extending post-surgical imatinib protocols for gastrointestinal stromal tumor patients previously limited to observation-only care.
- Fixed-dose combination development:Co-formulation with hydroxyurea or interferon-alpha is creating differentiation pathways for manufacturers seeking to bypass pure price competition in commoditized tablet markets.
- Direct-to-hospital distribution:Bypassing wholesale intermediaries through contracted oncology center relationships is capturing margin previously allocated to distribution tier markups in Spain and Italy.
Industry Challenges
- Serialization compliance timelines:EU Falsified Medicines Directive traceability mandates are forcing batch-level aggregation infrastructure investments that strain mid-tier generic manufacturers with limited IT capital.
- BCR-ABL mutation surveillance integration:Real-time therapeutic monitoring requirements are complicating bundled drug-and-service contracts as diagnostic vendors and pharmaceutical suppliers negotiate data ownership terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Imatinib Drug Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.7 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injectable, Oral Solution, Extended-Release Therapy Area: Chronic Myeloid Leukemia, Gastrointestinal Stromal Tumors, Myelodysplastic Syndromes, Acute Lymphoblastic Leukemia End User: Hospitals, Pharmacies, Clinics, Oncology Centers Distribution Channel: Direct Sales, Retail Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Novartis, Sun Pharmaceutical Industries, Teva Pharmaceutical Industries, Dr. Reddy's Laboratories, Mylan, Cipla, Apotex, Sanofi, Glenmark Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Imatinib Drug Market Emerging Trajectories
Manufacturing technology maturation and regulatory data transparency are compressing development cycles while procurement centralization is rewiring traditional channel economics across oncology supply chains.
Continuous manufacturing platforms for oral solid dose production are supplanting batch processing in high-volume generic facilities. Indian and Chinese contract manufacturers are retrofitting Hyderabad and Shanghai plants with direct compression lines that reduce API exposure and accelerate changeover times. This technology shift is enabling same-facility production of multiple tyrosine kinase inhibitors, compressing capital recovery periods and accelerating generic erosion timelines.
CDSCO export certification harmonization with WHO prequalification standards is streamlining Indian manufacturer access to African and Southeast Asian procurement programs. The regulatory convergence is eliminating redundant stability study requirements and reducing dossier preparation timelines from 18 to 12 months for emerging market submissions. Oncology centers in Kenya and Vietnam are responding by expanding tender volumes to Indian suppliers previously excluded by documentation gaps.
Hospital system consolidation is compressing vendor lists and demanding outcome-linked contracting terms that bundle drug supply with adherence monitoring and resistance testing services. Integrated delivery networks in the United States and hospital chains in Germany are displacing independent pharmacy procurement with centralized oncology pharmacy committees that negotiate multi-year sole-source agreements. This purchasing concentration is most visible in academic medical centers where pharmacy and therapeutics committees now control 80% of tyrosine kinase inhibitor allocation decisions.
Imatinib Drug Market Segmentation
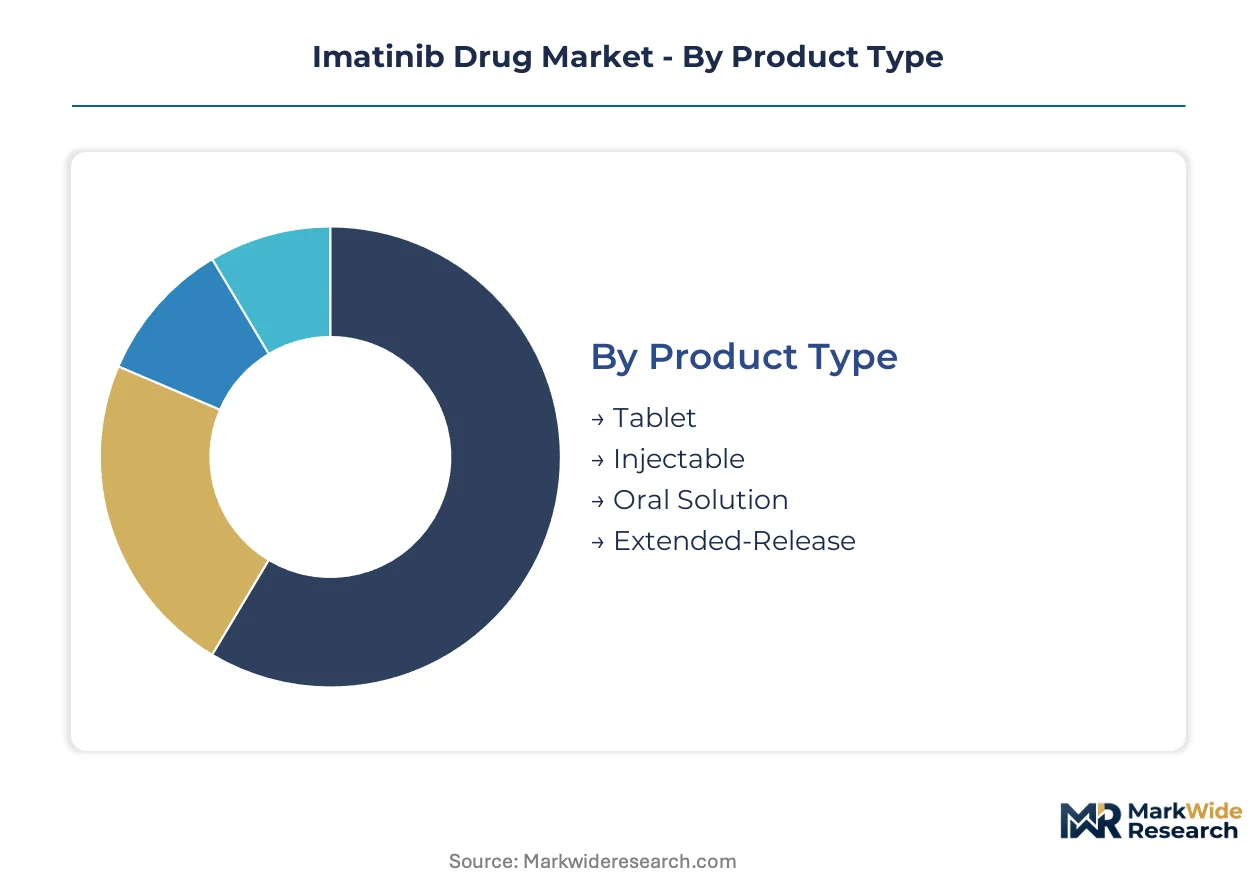
Imatinib procurement flows through distinct channel configurations that vary by formulation complexity and therapy setting. Tablet formulations dominate hospital tenders through direct sales agreements, while specialty oncology centers capture higher-margin injectable volumes bundled with diagnostic services.
Product Type:
Channel economics diverge sharply between solid oral doses and parenteral formats, with hospital systems favoring direct procurement for high-volume tablets and specialty distributors handling complex formulations.
- Tablet:Compressed imatinib mesylate in 100 mg and 400 mg strengths constitutes the procurement backbone for chronic myeloid leukemia maintenance regimens. Hospital pharmacy committees in Germany and the United States negotiate multi-year direct contracts for this format, locking in formulary preference through volume commitments that exclude wholesale markups.
- Injectable:Lyophilized powder for intravenous reconstitution serves acute lymphoblastic leukemia induction protocols and patients with compromised gastrointestinal absorption. Oncology centers in academic medical settings capture this segment through bundled care pathways that integrate drug administration with therapeutic drug monitoring.
- Oral Solution:Liquid formulation accommodates pediatric patients and adults with swallowing difficulties, flowing through specialty pharmacy channels that require cold-chain handling capabilities.
- Extended-Release:Modified-release matrix tablets enable once-daily dosing compliance, distributed through retail pharmacy networks in markets where patient convenience drives brand substitution.
By volume, Tablet leads. By growth pace, Injectable is ahead.
Therapy Area:
Clinical protocol evolution is resegmenting demand across malignancy types, with adjuvant expansions in solid tumors outpacing front-line leukemia substitution pressures.
- Chronic Myeloid Leukemia:Philadelphia chromosome-positive CML remains the anchor indication, with indefinite tyrosine kinase inhibitor maintenance creating predictable recurring demand. FDA and EMA guidelines support generic substitution in this setting, compressing originator share as bioequivalent tablets penetrate Medicare and national health service formularies.
- Gastrointestinal Stromal Tumors:Post-surgical adjuvant protocols for KIT-positive GIST are expanding as oncology societies update guidelines to extend imatinib duration beyond previous observation-only standards. ANVISA regulatory alignment in Brazil is accelerating access in Latin American markets previously limited to metastatic disease treatment.
- Myelodysplastic Syndromes:Off-label use in myelodysplastic syndromes with PDGFR rearrangements represents a niche segment concentrated in academic referral centers with molecular diagnostic capabilities.
- Acute Lymphoblastic Leukemia:Philadelphia chromosome-positive ALL induction and consolidation protocols utilize imatinib in combination with chemotherapy, with demand concentrated in pediatric oncology centers and adult academic medical centers.
Chronic Myeloid Leukemia commands the largest patient volume. Gastrointestinal Stromal Tumors is climbing the fastest on adjuvant protocol expansion.
End User:
Procurement centralization is consolidating purchasing power among integrated delivery networks, displacing fragmented clinic purchasing with system-wide oncology pharmacy committees.
- Hospitals:Inpatient oncology services and emergency departments manage acute presentations and treatment complications, capturing imatinib volumes through 340B discount programs in the United States and national tender frameworks in European single-payer systems.
- Pharmacies:Community and specialty pharmacy channels handle maintenance prescription fulfillment, with mail-order penetration rising in markets where 90-day dispensing aligns with chronic therapy models.
- Clinics:Private oncology practices and infusion centers manage stable chronic myeloid leukemia patients, though independent clinic procurement is contracting as hospital system acquisition accelerates.
- Oncology Centers:Dedicated cancer centers and academic comprehensive cancer programs integrate drug procurement with clinical trial access and resistance monitoring services, commanding premium positioning through bundled value propositions.
Hospitals transact the highest absolute volumes. Oncology Centers are expanding their share fastest through vertical integration of pharmacy and diagnostic services.
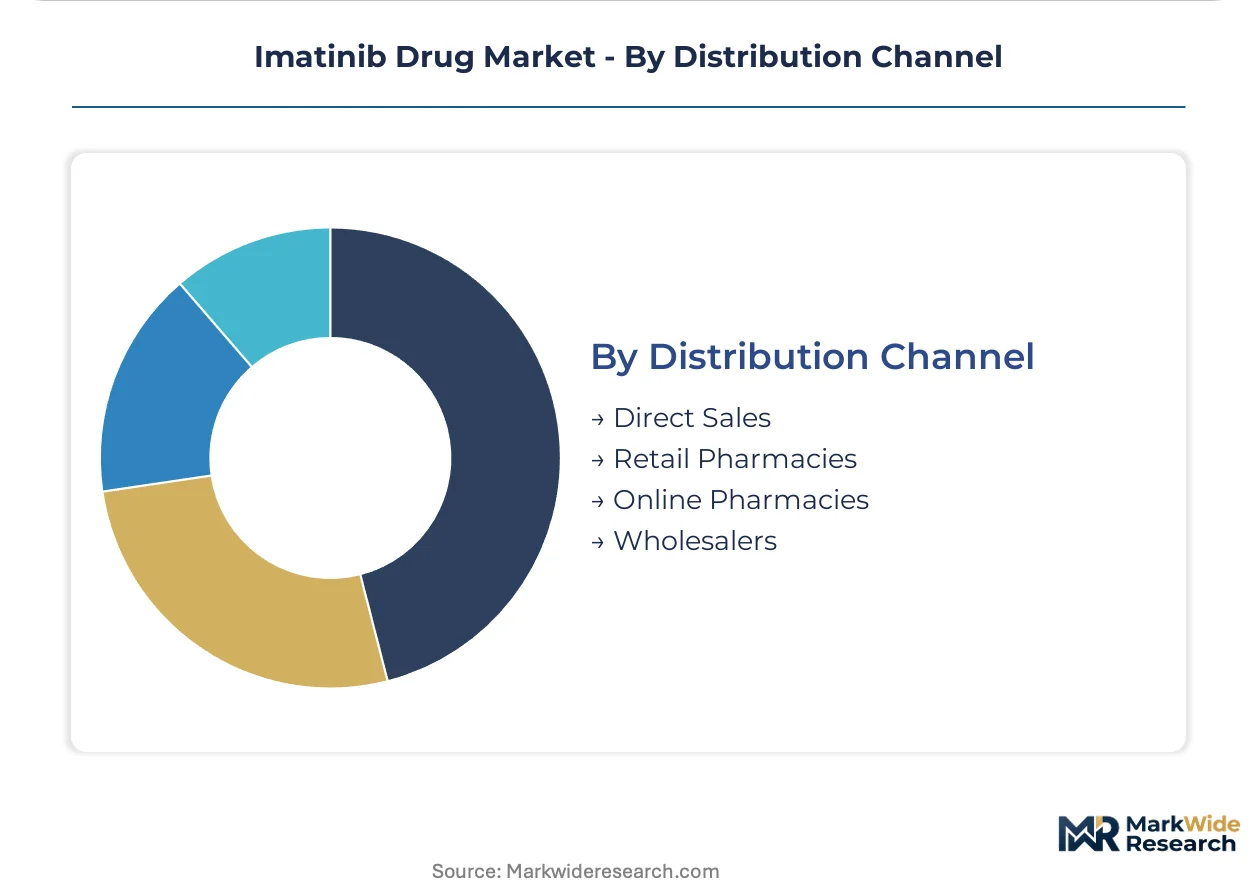
Distribution Channel:
Margin compression in wholesale intermediaries is driving manufacturer investment in direct-to-provider logistics infrastructure, particularly for temperature-sensitive and high-value formulations.
- Direct Sales:Manufacturer-contracted hospital relationships bypass distributor markups through dedicated account management and consignment inventory models, capturing 15-20 point margin improvements in high-volume tablet procurement.
- Retail Pharmacies:Community pharmacy networks serve maintenance therapy patients with established reimbursement relationships, though specialty pharmacy carve-outs are displacing generalist retail in oral oncology.
- Online Pharmacies:Digital dispensing platforms are penetrating cash-pay and high-deductible patient segments, with regulatory compliance for controlled substance handling limiting expansion in some jurisdictions.
- Wholesalers:Traditional three-tier distribution retains relevance for fragmented clinic and small hospital procurement, though consolidated buying groups are eroding wholesale leverage through direct contracting alternatives.
Direct Sales dominates value capture. Online Pharmacies is gaining share fastest on patient convenience and price transparency platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and United States oncology centers through direct tender mechanisms, while Indian manufacturers capture volume through export-oriented production clusters serving price-sensitive emerging markets.
United States
Academic medical centers in Boston and Houston drive demand through integrated delivery networks that bundle drug procurement with resistance monitoring services. FDA bioequivalence standards govern generic substitution thresholds, compressing originator share as 340B discount programs expand hospital access. Philadelphia and New York oncology pharmacy committees now control the majority of tyrosine kinase inhibitor allocation decisions.
Germany
Hospital system consolidation across Bavaria and North Rhine-Westphalia is centralizing procurement through multi-year sole-source agreements. EMA quality guidelines and Germany's national tender frameworks accelerate generic penetration in chronic myeloid leukemia maintenance regimens. Heidelberg and Berlin cancer centers anchor demand through bundled care pathways integrating diagnostic and therapeutic services.
India
Domestic chronic myeloid leukemia patients and African export markets sustain production volumes from Gujarat and Hyderabad manufacturing zones. CDSCO export certification harmonization with WHO prequalification standards streamlines access to Southeast Asian procurement programs. Mumbai-based hospital chains are expanding oncology capacity to serve both local patients and medical tourism segments.
Brazil
Post-surgical gastrointestinal stromal tumor protocols are expanding as ANVISA oncology guidelines extend adjuvant imatinib duration. São Paulo and Rio de Janeiro academic medical centers drive adoption through molecular diagnostic capabilities that identify KIT-positive patient populations. Federal procurement programs are negotiating volume commitments with Indian generic suppliers to reduce import dependency.
China
Yangtze River Delta oncology centers are upgrading therapeutic drug monitoring capabilities to support indefinite maintenance regimens. NMPA regulatory pathways for tyrosine kinase inhibitor generics are compressing approval timelines as domestic manufacturers scale API-to-finished-dose operations. Shanghai and Suzhou biopharma clusters are attracting contract manufacturing investment from multinational suppliers seeking cost-competitive production.
Imatinib Drug Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the imatinib value chain. Originator manufacturers retain proprietary formulation expertise and regulatory dossier depth in high-barrier markets, while vertically integrated Indian and Chinese producers command cost structures through captive intermediate supply. Three archetypes dominate: patent-era incumbents with legacy brand equity, API-to-tablet integrated generics, and hospital-tender specialists with established account management infrastructure. Competitive moves concentrate on direct-to-hospital distribution bypassing wholesale intermediaries, and fixed-dose combination development to escape pure price competition.
Among the established pharmaceutical conglomerates, Novartis represents the originator archetype with residual brand presence in premium-tier markets. Sun Pharmaceutical Industries and Teva Pharmaceutical Industries exemplify divergent scale strategies—Sun through Indian-based vertical integration, Teva through European and North American hospital network anchoring. Dr. Reddy's Laboratories occupies a position bridging export-oriented manufacturing and regulated market dossier accumulation. These named entities serve as anchors for understanding how competitive positioning fragments across technology-intensive versus cost-driven market segments.
| Leading Market Players |
|---|
| Novartis |
| Sun Pharmaceutical Industries |
| Teva Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Mylan |
| Cipla |
| Apotex |
| Sanofi |
| Glenmark Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day API inventory cycles at Indian formulators create pricing leverage that shifts with intermediate availability from Gujarat and Hyderabad production zones. This lead-time band concentrates procurement power among vertically integrated manufacturers while compressing margins for Western generics dependent on spot API purchases.
Pricing Analysis
The customization-premium spread between originator formulations and commodity generics spans three-tier pricing structure across premium, standard, and economy levels. FDA bioequivalence certification and EMA quality dossiers command premium positioning in German and United States hospital tenders, while CDSCO-export-certified tablets compete on volume in African procurement programs. Price differentiation hinges on regulatory tier and captive API production, with cost compression in economy tiers intensifying as Chinese intermediate suppliers expand batch scale. Oncology centers in academic medical settings exhibit lowest price sensitivity due to bundled diagnostic service margins, while federal procurement programs in Brazil and Southeast Asia prioritize per-unit cost minimization.
Supply Chain Analysis
Strategic-stockpile preferences dominate API procurement as formulators buffer against intermediate supply disruptions from China and India, which together anchor over two-thirds of global tyrosine kinase inhibitor raw material output. Manufacturing draws from 3-(4-methylpiperazin-1-yl)methylbenzoic acid and 4-(chloromethyl)benzoyl chloride intermediates, with single-source vulnerability concentrated in Yangtze River Delta chemical parks. Distribution runs through direct-to-hospital contracts in regulated markets and tender-based wholesale channels in emerging economies, with serialization compliance mandates forcing batch-level aggregation investments that strain mid-tier IT infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise and regulatory dossier depth constitute scarce capabilities that fragment competitive positioning between technology-intensive incumbents and cost-driven challengers. The widening patent cliff exposes which manufacturers possess sustainable API-to-finished-dose control versus wholesale-dependent intermediaries.
For Market Incumbents: Shield residual premium positioning through proprietary modified-release formulation investments and resistance-monitoring service bundling that locks oncology centers into multi-year contracts. Deepen backward integration into high-purity intermediate production to offset API price volatility from Chinese suppliers. Prioritize FDA supplemental approval pathways for fixed-dose combinations that escape pure generic substitution pressure. For New Entrants and Emerging Players: Anchor in Brazilian adjuvant GIST protocols where ANVISA guideline expansion outpaces supply localization, capturing volume before Indian exporters consolidate tender relationships. Target Southeast Asian oncology centers seeking WHO-prequalified alternatives to originator sourcing. Pursue CDSCO export certification harmonization as the primary go-to-market credential for African procurement program access. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational pharmaceutical parents divesting mature oncology assets to refocus on biologic pipelines. Five-to-ten-year viability hinges on whether acquired manufacturing footprints retain API supply contracts or face intermediate cost reset. Monitor BCR-ABL mutation surveillance integration mandates as the signal indicating which bundled drug-and-service models capture sustainable margin.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA bioequivalence submission unlocks 340B hospital access and Medicare formulary placement. |
| Manufacturing Scale-Up | Continuous direct compression retrofit at Hyderabad facilities compresses changeover times across multiple TKIs. |
| Backward Integration | Captive intermediate supply from Gujarat chemical parks insulates margin against Chinese API price volatility. |
| Hospital System Partnership | Oncology pharmacy committee relationships in Heidelberg and Berlin secure multi-year sole-source agreements. |
| Pipeline Diversification | Fixed-dose combination development with hydroxyurea creates differentiation beyond commoditized tablet markets. |
Methodological Framework
Initial hypotheses were tested against primary input from regulatory affairs leads, hospital procurement managers, oncology pharmacy directors, and API manufacturing executives and refined through secondary validation against FDA Orange Book filings, EMA assessment reports, CDSCO export certifications, and WHO prequalification records. Bottom-up patient-volume modeling across chronic myeloid leukemia and gastrointestinal stromal tumor indications was triangulated with top-down pharmaceutical market sizing from national tender databases and hospital purchasing disclosures.
Variance-decomposition across the projection horizon isolates volume, price, and mix effects within segmented treatment lines, dosage forms, and regional regulatory clusters. CAGRs were derived from patient cohort flow analysis incorporating therapy initiation rates, discontinuation patterns, and generic substitution elasticities. Forecast inputs incorporate indefinite maintenance protocol adherence assumptions and BCR-ABL mutation surveillance penetration curves.
Decision-makers should treat outputs as directional under stable bioequivalence substitution policies and uninterrupted API trade flows; material deviation would warrant model refresh. Revision becomes warranted when next-generation TKI frontline adoption crosses thresholds that compress imatinib maintenance initiation rates or when serialization compliance timelines force mid-tier manufacturer exit.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Europe Generic Injectables Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Etanercept Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Dasatinib Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Global Sirolimus Market
Biosimilars
Fusion Protein and Biosimilars Market
Biosimilars
Global Biosimilars Market
Biosimilars
Adalimumab Biosimilar Market