
 Biosimilar Monoclonal Antibody Comparability Test Platforms Market | 2026-2036
Biosimilar Monoclonal Antibody Comparability Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Biosimilar Monoclonal Antibody Comparability Test Platforms Market Insights
Analytical biochemist talent scarcity is bifurcating the competitive landscape between platform vendors with embedded scientific support and equipment-only suppliers. Thermo Fisher Scientific leverages its integrated service-and-instrument model to anchor large-pharma relationships. Merck KGaA sustains dominance in chromatography consumables through backward integration into resin manufacturing. Bio-Rad Laboratories differentiates via specialized electrophoresis workflows tailored to biosimilar charge-variant profiling.
Biosimilar monoclonal antibody comparability test platforms comprise analytical instrumentation and associated reagents used to demonstrate structural, functional, and physicochemical similarity between a biosimilar candidate and its reference biologic, employing techniques such as peptide mapping with mass spectrometry detection at resolution thresholds below 10 ppm mass accuracy. These platforms serve the primary commercial purpose of generating regulatory-submission-quality data packages that justify reduced clinical trial scope. Mass spectrometry and chromatography command the deepest margin pools due to high consumables pull-through and method-transfer complexity that locks in customer switching costs. Surface plasmon resonance within the technology dimension exhibits the fastest expansion trajectory as label-free binding kinetics replace slower ELISA protocols for affinity confirmation.
The FDA's Biosimilar Action Plan and EMA's Q5E comparability guidelines jointly elevate analytical similarity evidence standards, forcing platform vendors to pre-validate method templates that accelerate client regulatory submissions. ISO 17025 accreditation requirements for contract testing laboratories are expanding addressable demand for qualified platform installations. Stakeholders must monitor how the EU AI Act's algorithmic transparency mandates affect automated data-analysis modules embedded in next-generation instrumentation.
Market Dynamics
Reference product exclusivity expiries across the United States and European Union are compressing biosimilar development timelines, forcing developers to front-load analytical similarity investments before patent cliffs rather than after.
Growth Catalysts
- EMA Q5E Comparability Guidelines:The European Medicines Agency's analytical similarity evidence standards are mandating higher-resolution physicochemical characterization, expanding platform utilization rates among contract testing laboratories.
- Surface Plasmon Resonance Adoption:Label-free binding kinetics platforms are replacing slower ELISA protocols for affinity confirmation, accelerating regulatory submission timelines for biosimilar developers.
- ISO 17025 Laboratory Accreditation:Mandatory quality management system certifications for contract testing facilities are driving qualified platform installations across analytical service providers.
Market Restraints
- High-Purity Resin Supply Concentration:Chromatography consumables depend on captive resin manufacturing controlled by a limited supplier base, creating input cost volatility and procurement risk.
- Mass Spectrometer Capital Intensity:Orbitrap and Q-TOF platforms require seven-figure capital commitments, constraining mid-tier biosimilar developer access to in-house analytical capabilities.
- Method Transfer Complexity:Platform switching costs lock customers into incumbent vendors, limiting competitive entry and compressing pricing flexibility for new market entrants.
Strategic Opportunities
- India Biosimilar Manufacturing Expansion:CDSCO regulatory pathway maturation and PLI scheme incentives are attracting platform vendors to establish localized service-and-instrument presence.
- Automated Data Analysis Integration:Convergence of mass spectrometry hardware with artificial intelligence-driven peptide mapping interpretation is reducing analytical biochemist headcount requirements.
- Multi-Attribute Method Standardization:Emerging regulatory acceptance of MAM workflows for simultaneous critical quality attribute monitoring creates white space for integrated platform offerings.
Industry Challenges
- Analytical Biochemist Talent Scarcity:Specialized expertise in mass spectrometry method development and regulatory submission preparation remains concentrated among a limited professional pool.
- Cross-Platform Data Harmonization:Integrating outputs from disparate instrumentation vendors into unified regulatory submission packages requires substantial custom validation effort.
- EU AI Act Algorithmic Transparency:Automated data-analysis modules embedded in next-generation instrumentation face emerging compliance requirements for explainable decision logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosimilar Monoclonal Antibody Comparability Test Platforms Market |
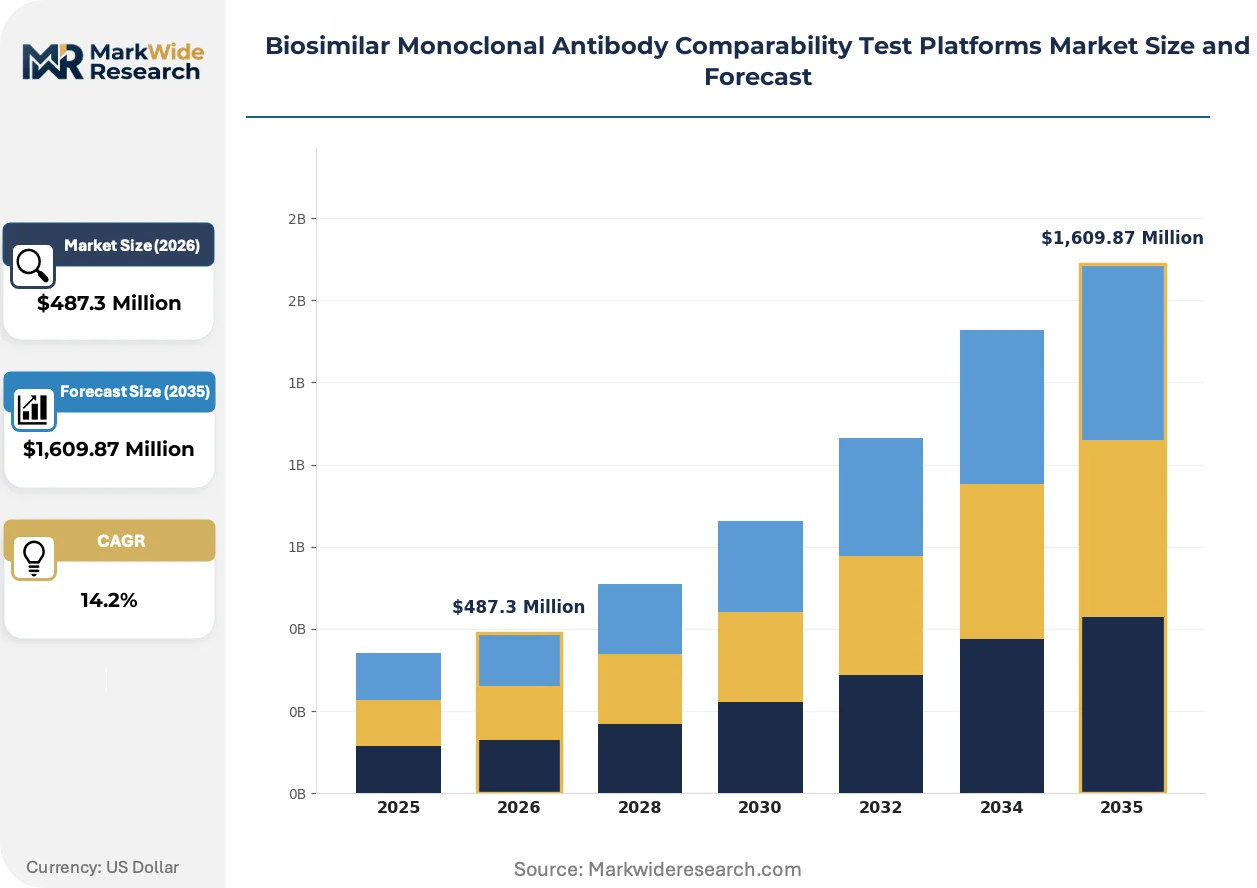
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Platform Type: Chromatography, Bioassay, Electrophoresis, Mass Spectrometry, Flow Cytometry Application: Pharmacokinetics, Immunogenicity, Potency, Purity Assessment, Binding Affinity End User: Contract Research Organizations, Biotechnology Firms, Government Laboratories, Academic Institutions Technology: Surface Plasmon Resonance, ELISA, PCR, Western Blotting, Capillary Electrophoresis |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, Waters, Shimadzu Corporation, Danaher, Bio-Rad Laboratories, Sartorius, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosimilar Monoclonal Antibody Comparability Test Platforms Market Trends and Innovations
Label-free biosensor technologies and artificial intelligence-enhanced data interpretation are compressing analytical development cycles while elevating the evidence standards required for regulatory acceptance.
High-resolution mass spectrometry platforms with sub-10 ppm mass accuracy are displacing lower-resolution alternatives for peptide mapping applications. Large-pharma biosimilar divisions and specialized contract research organizations are adopting these systems at accelerated replacement cycles. This displacement is compressing the timeline for generating regulatory-submission-quality structural similarity data packages.
The FDA's Biosimilar Action Plan and EMA's scientific guidelines for analytical similarity are jointly elevating evidence standards for physicochemical and functional characterization. These frameworks are forcing platform vendors to pre-validate method templates that accelerate client regulatory submissions. Biosimilar developers in the United States face the most stringent documentation requirements and are responding by consolidating procurement with vendors offering embedded scientific support.
Service-based pricing models are unbundling after-sales support from instrument capital sales. Contract research organizations and mid-tier biosimilar developers are shifting toward per-sample analytical service contracts rather than platform ownership. This behavioral shift is most visible in the United States, where reference product exclusivity expiries have created pipeline urgency and capital constraint pressures simultaneously.
Biosimilar Monoclonal Antibody Comparability Test Platforms Market Segmentation
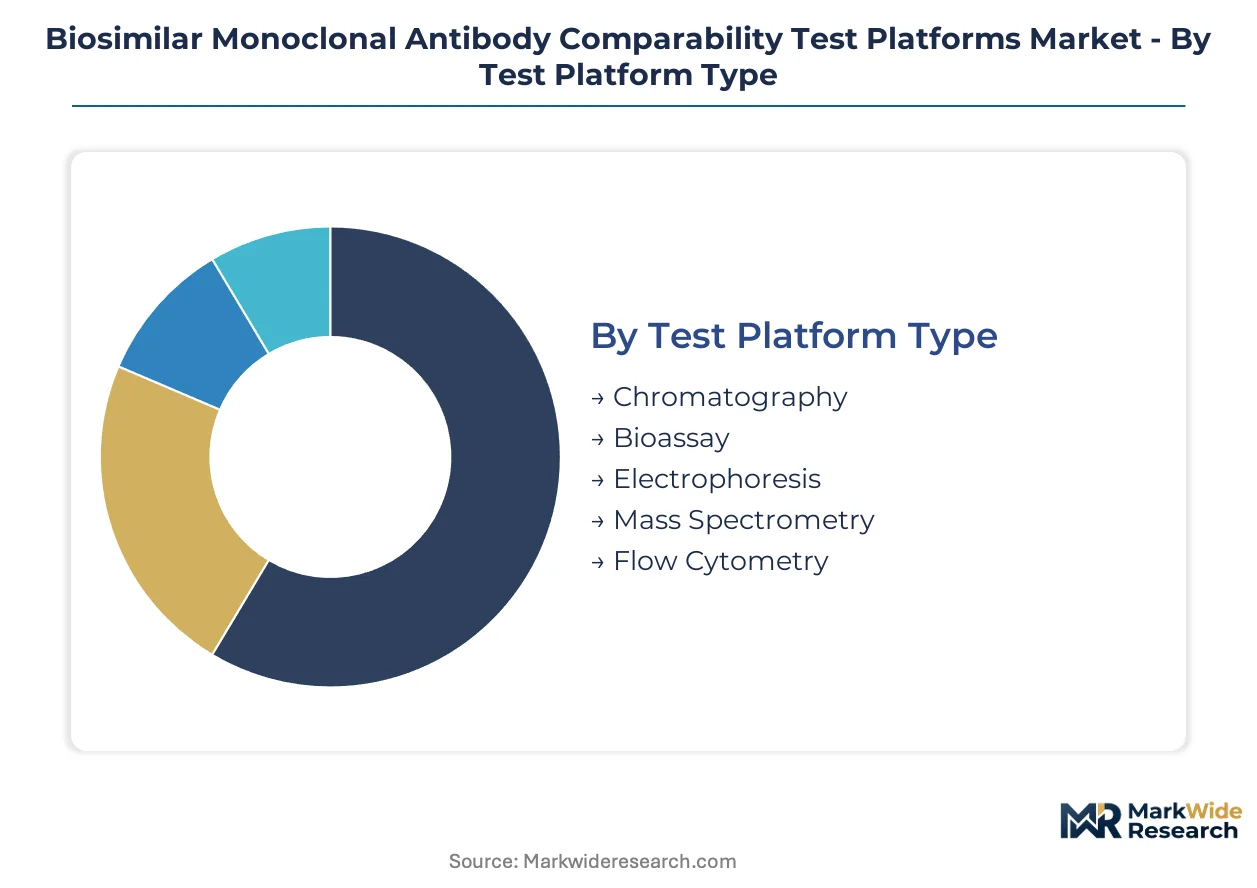
Platform selection in biosimilar comparability testing follows distinct procurement channels that shape vendor access and pricing leverage. Each segment category exhibits different concentration patterns between direct instrument sales, consumables pull-through, and service-based contracts.
Test Platform Type:
Platform sales flow through three primary channels: direct capital equipment purchases by large-pharma biosimilar divisions, reagent rental programs for mid-tier developers, and full-service contracts through contract research organizations.
- Mass Spectrometry:High-resolution Orbitrap and Q-TOF systems deliver sub-10 ppm mass accuracy for peptide mapping applications. United States-based biosimilar developers concentrate procurement here due to FDA analytical similarity documentation requirements that demand the highest physicochemical resolution.
- Chromatography:Ion-exchange and size-exclusion systems separate charge variants and aggregates with consumables generating recurring revenue streams. European Union contract testing laboratories drive installed base expansion as EMA Q5E guidelines tighten method validation standards.
- Bioassay:Cell-based potency assays measure biological activity against reference products through reporter gene and proliferation formats.
- Electrophoresis:Capillary and gel-based systems profile molecular weight distributions and isoform patterns.
- Flow Cytometry:Multiparameter cell analysis platforms support immunogenicity screening and receptor binding studies.
Chromatography dominates installed base. Mass spectrometry is where expansion concentrates.
Application:
Application demand correlates directly with regulatory submission sequence—early-phase developers prioritize pharmacokinetics and binding affinity, while late-stage filings require comprehensive purity and potency dossiers.
- Pharmacokinetics:Quantitative bioanalytical methods measure drug concentration-time profiles in biological matrices. United States biosimilar developers front-load these investments to compress development timelines ahead of reference product patent cliffs.
- Immunogenicity:Anti-drug antibody detection assays assess patient immune responses with tiered screening and confirmatory protocols. European Union regulatory submissions require more extensive immunogenicity bridging studies than other geographies.
- Potency:Mechanism-of-action assays demonstrate equivalent biological activity to reference products.
- Purity Assessment:Aggregate and fragment quantification ensures product quality consistency.
- Binding Affinity:Kinetic and thermodynamic characterization confirms target engagement equivalence.
Pharmacokinetics commands the largest service contract volumes. Immunogenicity is climbing the fastest.
End User:
Customer type determines pricing architecture—biotechnology firms negotiate instrument-acquisition financing, while contract research organizations demand per-sample service pricing with embedded scientific support.
- Contract Research Organizations:Full-service analytical providers generate regulatory-submission-quality data packages for biosimilar developers lacking in-house capabilities. United States CROs are expanding platform adoption most aggressively as reference product exclusivity expiries create pipeline urgency.
- Biotechnology Firms:Emerging and mid-cap developers balance capital constraints against analytical control requirements.
- Government Laboratories:National reference standards bodies and regulatory science centers maintain comparability methodology.
- Academic Institutions:Research universities advance platform innovation through method development and training programs.
Contract research organizations dominate installed base. Biotechnology firms are where expansion concentrates.
Technology:
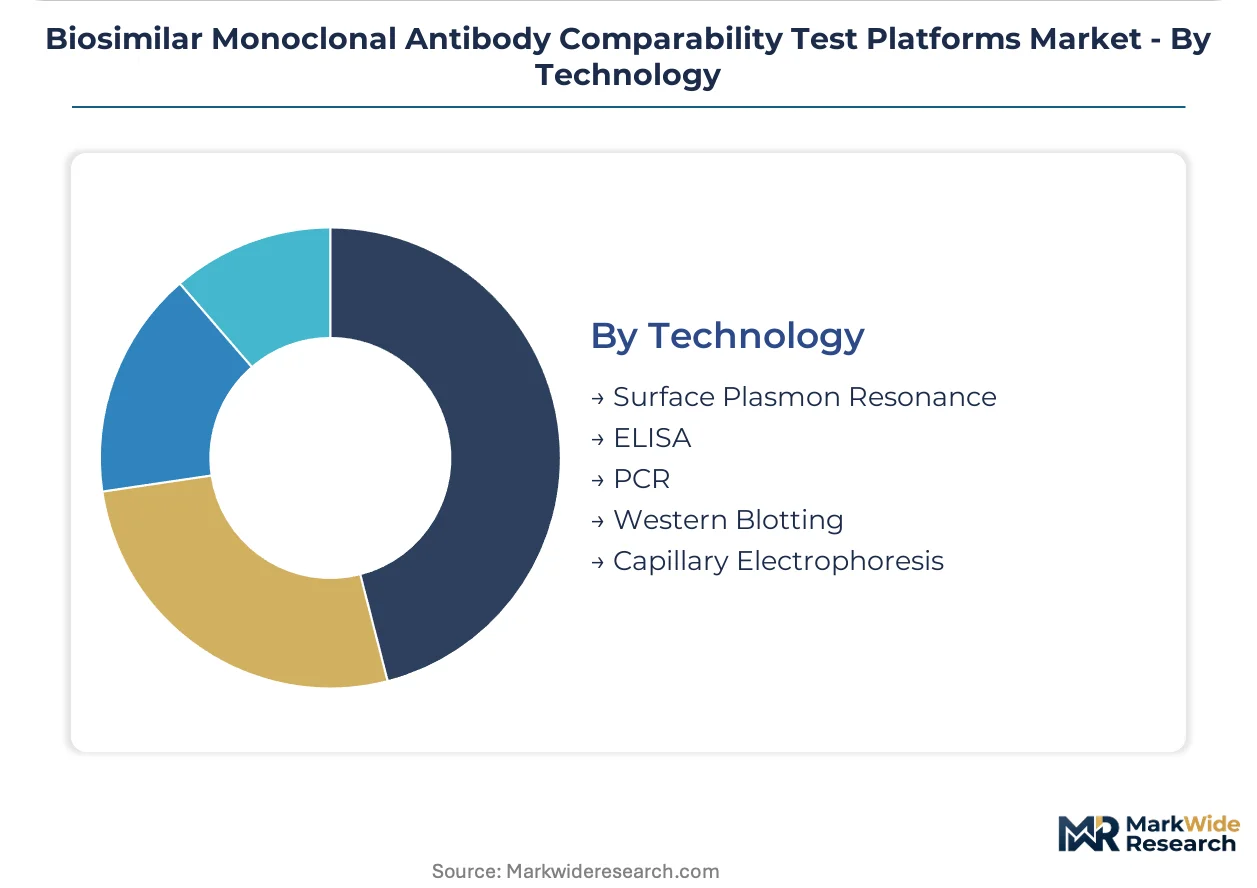
Technology selection reflects a trade-off between throughput, capital intensity, and regulatory precedent—label-free methods displace legacy protocols where method transfer validation has been established.
- Surface Plasmon Resonance:Label-free biosensors deliver real-time binding kinetics without fluorescent or enzymatic labels. United States biosimilar developers are displacing ELISA protocols fastest here as FDA submissions increasingly accept SPR-derived affinity constants.
- ELISA:Enzyme-linked immunosorbent assays remain the regulatory default for quantity and impurity detection.
- PCR:Nucleic acid amplification supports adventitious agent testing and cell line authentication.
- Western Blotting:Antibody-based protein detection confirms identity and molecular weight.
- Capillary Electrophoresis:High-resolution separation techniques profile charge heterogeneity and glycoform distribution.
ELISA dominates installed base. Surface plasmon resonance is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform procurement patterns diverge sharply across major markets. United States developers prioritize high-resolution mass spectrometry for FDA submission rigor, while European laboratories emphasize chromatography standardization under EMA guidelines, and Asian manufacturers concentrate on cost-efficient multi-attribute method adoption.
United States
Biosimilar developers front-load analytical investments to compress timelines ahead of reference product patent cliffs. FDA's Biosimilar Action Plan mandates comprehensive physicochemical documentation that drives Orbitrap and Q-TOF platform adoption. The Greater Boston cluster anchors contract research organization expansion as CROs build service capacity for accelerated submission support.
Germany
Contract testing laboratories expand chromatography installations to meet tightening EMA Q5E validation standards. The country's national pharmaceutical regulator enforces ISO 17025 accreditation requirements that elevate platform qualification thresholds. The Rhine-Main biotech corridor concentrates method development expertise for European biosimilar developers seeking regulatory submission support.
India
Domestic biosimilar manufacturers scale analytical capabilities to serve export markets and emerging CDSCO pathway requirements. PLI scheme incentives attract platform vendors to establish localized service-and-instrument presence. The Hyderabad-Bengaluru pharmaceutical belt drives regional demand for automated peptide mapping workflows that reduce specialized biochemist headcount requirements.
Switzerland
Specialized contract laboratories maintain reference standard methodology under Swissmedic oversight for global biosimilar developers. The national regulatory framework emphasizes multi-attribute method validation for critical quality attribute monitoring. The Basel biopharma cluster anchors precision analytical service provision for European and international submission portfolios.
Japan
Domestic biosimilar developers adopt surface plasmon resonance platforms as PMDA submissions increasingly accept label-free binding kinetics data. METI industrial policy supports analytical infrastructure modernization for emerging biogeneric manufacturers. The Kanto region concentrates platform vendor technical support operations serving Asia-Pacific method transfer requirements.
Biosimilar Monoclonal Antibody Comparability Test Platforms Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in platform supply. Thermo Fisher Scientific and Danaher anchor the integrated segment through combined instrument-and-service offerings that lock in large-pharma relationships. Merck KGaA and Sartorius occupy the consumables-dominant archetype with backward integration into resin manufacturing. Specialist vendors differentiate through workflow-specific configurations rather than breadth. Competitive dynamics center on method template pre-validation for regulatory acceleration and embedded scientific support contracts that elevate switching costs.
Within the integrated instrumentation tier, Thermo Fisher Scientific exemplifies the service-anchored model that dominates United States procurement patterns. Merck KGaA represents the consumables-led archetype sustaining recurring revenue through chromatography resin supply concentration. Bio-Rad Laboratories occupies a specialist position emphasizing electrophoresis workflow differentiation for charge-variant profiling applications. These three anchors illustrate how competitive positioning stratifies across platform breadth, consumables pull-through depth, and application-specific workflow optimization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Agilent Technologies |
| Waters |
| Shimadzu Corporation |
| Danaher |
| Bio-Rad Laboratories |
| Sartorius |
| Charles River Laboratories |
| Others |
Pricing and Supply Chain Analysis
High-purity chromatography resin substitution for legacy agarose matrices simultaneously shifts procurement geography toward German and Japanese specialty chemical manufacturers and compresses per-unit consumables pricing for mid-tier biosimilar developers. This input transition concentrates vendor power among backward-integrated resin suppliers while forcing platform vendors to absorb margin pressure through bundled service contracts.
Pricing Analysis
Long-term reagent rental contracts dominate United States procurement, locking in large-pharma biosimilar divisions through embedded scientific support and method validation services. Price differentiation hinges on ISO 17025 accreditation tier and after-sales service bundling, with premium tiers commanding substantial markups for regulatory submission preparation. Cost compression in mid-tier instrumentation is intensifying because capital-constrained developers are displacing Orbitrap purchases with lower-resolution Q-TOF alternatives. Biotechnology firms exhibit the highest price sensitivity, while contract research organizations prioritize regulatory acceleration over unit economics.
Supply Chain Analysis
Captive resin manufacturing in Germany, Switzerland, and the United States anchors chromatography consumables supply for analytical platform vendors. High-purity silica particles, synthetic polymer beads, and surface chemistries for biosensor chips draw from specialty chemical producers concentrated in the Rhine-Main corridor and Basel region. Single-source vulnerability in affinity resin supply creates procurement risk for surface plasmon resonance platform manufacturers. Distribution runs through authorized distributor networks serving contract testing laboratories and direct sales teams for large-pharma accounts.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent platform vendors face displacement pressure from artificial intelligence-enhanced data interpretation modules that reduce specialized analytical biochemist headcount requirements for regulatory submissions.
For Market Incumbents: Compound switching costs through pre-validated method templates that accelerate FDA and EMA submission timelines for biosimilar developers. Deepen backward integration into high-purity resin manufacturing to defend consumables pull-through revenue against specialty chemical entrants. Lock in contract research organization relationships with embedded scientific support contracts that exceed ISO 17025 accreditation requirements.
For New Entrants and Emerging Players: Differentiate on automated peptide mapping interpretation that compresses analytical development cycles for India-based biosimilar manufacturers scaling export capabilities. Target the Hyderabad-Bengaluru pharmaceutical belt with localized service-and-instrument presence under CDSCO pathway maturation. Pursue multi-attribute method standardization as a go-to-market wedge against established mass spectrometry vendors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors consumables-dominant archetypes with captive resin manufacturing and recurring revenue visibility. Platform vendors with integrated service-and-instrument models command premium valuations due to regulatory submission acceleration capabilities. Watch for EMA Q5E guideline revisions as an inflection indicator for chromatography platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Method Template Pre-validation | FDA and EMA submission acceleration locks in large-pharma biosimilar division loyalty. |
| Backward Integration into Resin Manufacturing | Captive high-purity consumables supply defends margin pools against specialty chemical competitors. |
| Automated Data Analysis Integration | Artificial intelligence-driven peptide mapping reduces analytical biochemist headcount requirements for mid-tier developers. |
| Localized Service Presence in India | CDSCO pathway maturation and PLI scheme incentives attract platform vendor technical support operations. |
| Multi-Attribute Method Standardization | Regulatory acceptance of MAM workflows creates white space for integrated platform offerings against point solutions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biosimilar development executives, regulatory affairs leads, contract research organization scientific directors, and analytical biochemist laboratory heads. Secondary validation drew from FDA Biosimilar Action Plan documentation, EMA Q5E comparability guidelines, ISO 17025 accreditation registries, and CDSCO regulatory pathway circulars. Bottom-up platform installation counts and top-down consumables revenue estimates were triangulated to derive market sizing.
Across the analysis window, the forecasting framework modeled test platform type, application sequence, end-user procurement channel, and technology substitution dynamics. CAGRs were computed from segment-level growth trajectories calibrated to regulatory submission volume projections and reference product exclusivity expiry schedules. Surface plasmon resonance displacement rates for ELISA protocols and mass spectrometry resolution tier adoption curves informed technology dimension projections.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EMA analytical similarity evidence standards; material deviation would warrant model refresh. Forecasts reflect assumptions of continued chromatography resin supply concentration and biosimilar developer capital constraint persistence. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
US Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Imatinib Drug Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Global Sirolimus Market
Biosimilars
Remicade Biosimilar Market