
 Dasatinib Market | 2026-2036
Dasatinib Market Size, Share, and Industry Trends Forecast 2026-2036
Dasatinib Market Outlook
FDA New Drug Application (NDA) and EMA Marketing Authorization Application (MAA) cycles is reorganizing competitive entry barriers for dasatinib manufacturers. Bristol-Myers Squibb Company leverages its originator patent estate and clinical data packages to sustain branded positioning in regulated markets. Teva Pharmaceutical Industries Ltd. anchors its portfolio through generic dossier submissions across multiple regulatory jurisdictions. Sun Pharmaceutical Industries Limited competes on cost-optimized manufacturing scale for emerging market supply.
Dasatinib is a dual SRC/ABL kinase inhibitor with a molecular weight of 488.01 g/mol, formulated as tablets and oral suspensions for daily administration in Philadelphia chromosome-positive leukemias. Its primary commercial purpose centers on targeted disruption of BCR-ABL signaling in chronic myeloid leukemia and acute lymphoblastic leukemia, with off-label exploration in myelodysplastic syndromes. The therapy area segmentation shows chronic myeloid leukemia commanding the largest patient volume pool, while acute lymphoblastic leukemia represents the fastest-growing indication subset driven by pediatric protocol expansion. Distribution channel dynamics reveal hospital pharmacies capturing the majority of value through institutional contracting, even as online pharmacies gain regulatory traction for maintenance therapy refills.
FDA, EMA, and WHO prequalification standards govern dasatinib manufacturing compliance, bioequivalence thresholds, and post-market pharmacovigilance reporting obligations that directly determine market access timelines. India's CDSCO and the EU MDR impose additional layer requirements on active pharmaceutical ingredient sourcing and finished dosage form stability data. Stakeholders must monitor evolving biosimilar-like guidance for kinase inhibitors and track national essential medicines list inclusions that reshape procurement and pricing authority across oncology networks.
Market Dynamics
Accelerated oncology approval pathways at FDA and EMA are compressing competitive entry timelines for dasatinib manufacturers, forcing originators to defend market position through lifecycle management while generic filers exploit abbreviated review windows.
Growth Catalysts
- Pediatric protocol expansion:Clinical trial enrollment for Philadelphia chromosome-positive acute lymphoblastic leukemia in children is widening the addressable patient base beyond adult chronic myeloid leukemia populations.
- EMA accelerated assessment:The centralized procedure's priority review track for oncology medicines is shortening time-to-market for second-line kinase inhibitors.
- Hematology center consolidation:Specialty hospital networks in the United States and Germany are standardizing dasatinib on formulary through institutional purchasing agreements.
Market Restraints
- API sourcing concentration:Active pharmaceutical ingredient production for dasatinib concentrates among Indian and Chinese manufacturers, creating single-point-of-failure exposure.
- Bioequivalence threshold escalation:FDA's tightening pharmacokinetic equivalence standards for highly variable drugs are extending generic development timelines.
- Tyrosine kinase inhibitor substitution:Imatinib and nilotinib compete for first-line chronic myeloid leukemia positioning, pressuring dasatinib's front-line adoption.
Strategic Opportunities
- Japanese maintenance therapy segment:PMDA's streamlined approval for reduced-intensity dosing protocols is opening post-remission refill markets.
- Online pharmacy channel development:Regulatory traction for telehealth-prescribed oncology maintenance is creating direct-to-patient distribution alternatives.
- CDSCO essential medicines inclusion:India's national list expansion for oncology therapies is unlocking centralized procurement volumes at state hospital networks.
Industry Challenges
- Pharmacovigilance reporting scale:Post-market adverse event surveillance for kinase inhibitors demands specialized hematology expertise that contract research organizations struggle to staff.
- Stability data package complexity:WHO prequalification requirements for tropical climate zone storage conditions are extending validation timelines for oral suspension formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dasatinib Market |
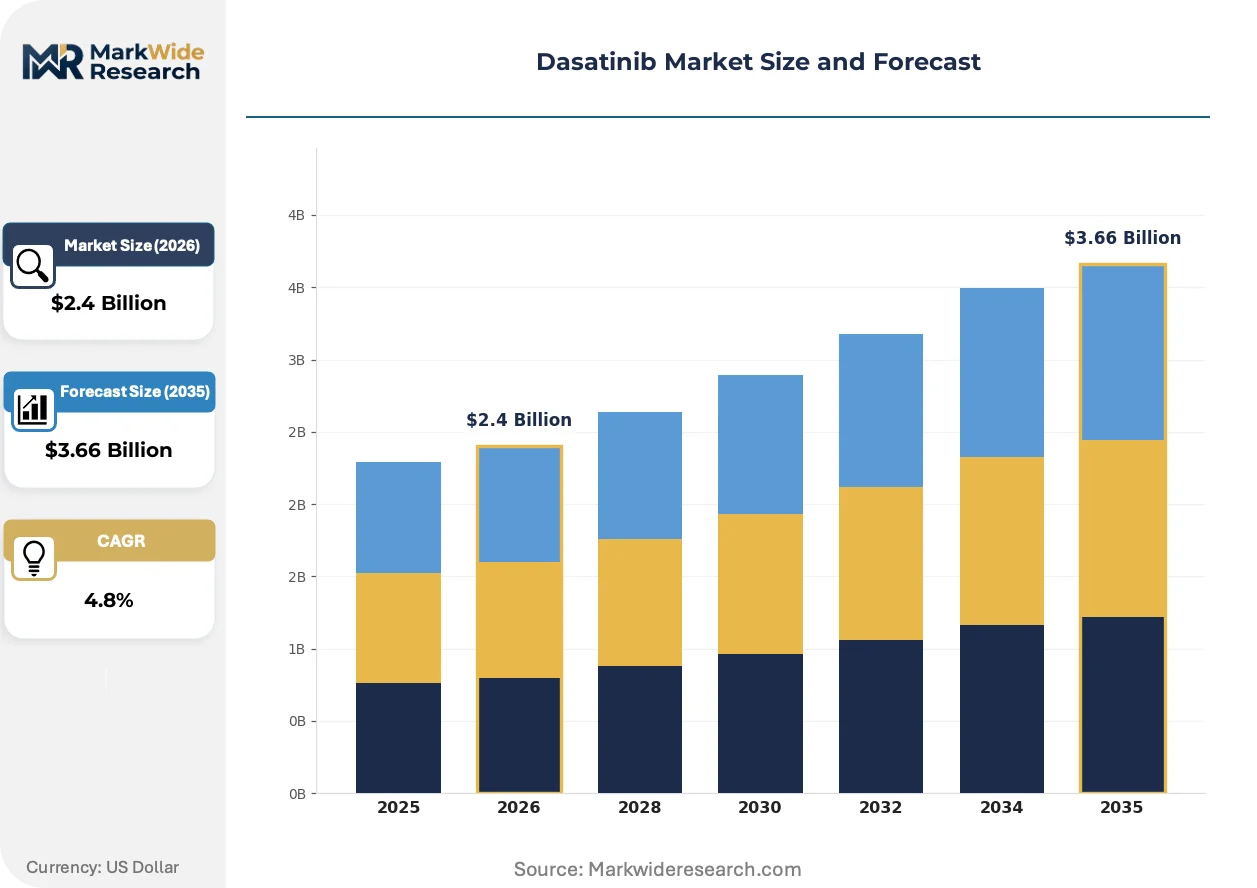
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Oral Suspension, Extended Release, Generic, Branded Therapy Area: Chronic Myeloid Leukemia, Acute Lymphoblastic Leukemia, Myelodysplastic Syndromes, Solid Tumors End User: Oncology Clinics, Hematology Centers, Specialty Hospitals, Research Institutes Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | Bristol-Myers Squibb Company, Teva Pharmaceutical Industries Ltd., Sandoz Group AG, Sun Pharmaceutical Industries Limited, Dr. Reddy’s Laboratories Limited, Hetero Drugs Limited, Cipla Limited, Lupin Limited, Aurobindo Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dasatinib Market Strategic Shifts
Formulation science and regulatory science are converging to reshape how dasatinib reaches patients, with manufacturers competing on administration convenience and geographic access rather than molecular novelty alone.
Oral suspension formulations are fragmenting the tablet-dominated product landscape. Pediatric oncology centers and geriatric hematology units are adopting liquid dosage forms at accelerating rates to address swallowing difficulties. This technology is fragmenting hospital pharmacy procurement patterns, forcing wholesalers to stock dual-format inventories and compressing margins on single-format suppliers.
REACH compliance for pharmaceutical excipients is tightening supply chain documentation requirements across European manufacturing. ECHA's expanded substance of very high concern candidate list is forcing reformulation of tablet coatings and suspension vehicles. German and French contract manufacturers are responding by qualifying alternative excipient suppliers and accelerating internal toxicology testing programs.
Maintenance therapy refills are migrating from hospital outpatient clinics to specialty pharmacy channels. Hematology practices in the United States are unbundling drug dispensing from infusion services, redirecting patients to mail-order oncology pharmacies for 90-day supply fulfillment. This pattern is most visible in Medicare Part D networks, where prior authorization automation has reduced friction for chronic oral oncology therapy continuity.
Dasatinib Market Segmentation
Dasatinib market segmentation reveals distinct procurement patterns across dosage forms and care settings. Each dimension carries implications for regulatory dossier requirements, cold-chain logistics, and reimbursement coding that manufacturers must navigate simultaneously.
Product Type:
Domestic manufacturing concentrates on conventional tablets for established markets, while export-led growth centers on pediatric-appropriate oral suspensions and extended-release formats targeting emerging economies with limited cold-chain infrastructure.
- Tablet:Standard immediate-release film-coated tablets containing dasatinib monohydrate dominate institutional procurement in the United States and Germany. Hematology centers in these markets prefer unit-dose packaging for medication adherence monitoring in chronic myeloid leukemia maintenance protocols.
- Oral Suspension:Liquid formulations enable dose titration for pediatric acute lymphoblastic leukemia patients and geriatric populations with dysphagia. Demand from oncology clinics in Japan and specialty hospital networks in India is accelerating as PMDA and CDSCO expand pediatric indication approvals.
- Extended Release:Once-daily modified-release tablets reduce dosing frequency for maintenance therapy patients. The format appeals to mail-order pharmacy channels in Medicare Part D networks seeking 90-day supply efficiency.
- Generic:Bioequivalent copies from Indian and Israeli manufacturers compete on cost in centralized procurement tenders across European hospital networks and Latin American public health systems.
- Branded:Originators maintain position through lifecycle management, pediatric exclusivity extensions, and co-pay assistance programs in commercial insurance segments of the United States and Switzerland.
Tablet formats hold the largest share; momentum sits with oral suspension as pediatric protocol expansion accelerates across Asian and European regulatory jurisdictions.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention protocols, with pricing and reimbursement intensity varying accordingly across national health technology assessment frameworks.
- Chronic Myeloid Leukemia:First-line and second-line BCR-ABL kinase inhibition for Philadelphia chromosome-positive patients generates the highest prescription volumes. Germany's G-BA and England's NICE have issued positive technology appraisals supporting broad reimbursement access.
- Acute Lymphoblastic Leukemia:Pediatric and adult salvage therapy applications are expanding most quickly as cooperative trial groups incorporate dasatinib into front-line protocols. The Children's Oncology Group in the United States and BFM study group in Europe are driving enrollment expansion.
- Myelodysplastic Syndromes:Off-label use in myelodysplastic neoplasms with myeloproliferative features remains investigational, concentrated at academic medical centers with active phase II programs.
- Solid Tumors:Preclinical and early clinical exploration in SRC-driven malignancies represents a niche research segment with limited current commercial footprint.
Chronic myeloid leukemia commands the largest patient volume pool; acute lymphoblastic leukemia is climbing the fastest on pediatric protocol adoption.
End User:
Customer type fragmentation reflects divergent purchasing authority, with institutional buyers consolidating volume through group purchasing organizations while academic centers maintain independent formulary control.
- Oncology Clinics:Community-based infusion centers in the United States are unbundling drug dispensing from administration services, shifting maintenance prescriptions to external specialty pharmacies.
- Hematology Centers:University-affiliated units in France, Italy, and Spain anchor clinical trial enrollment and drive protocol standardization across regional hospital networks.
- Specialty Hospitals:Dedicated cancer centers in Japan and South Korea concentrate high-acuity cases and maintain direct relationships with manufacturers for managed access programs.
- Research Institutes:National cancer research organizations in the United Kingdom and Netherlands sponsor investigator-initiated studies exploring combination regimens and resistance mechanisms.
Hematology centers hold the largest share; momentum sits with oncology clinics as care decentralization accelerates in North American markets.
Distribution Channel:
Supply concentration varies by channel, with hospital pharmacies maintaining captive relationships with wholesalers while online channels fragment last-mile delivery across multiple logistics providers.
- Hospital Pharmacies:Institutional pharmacies in Germany and Japan capture the majority of value through 340B-equivalent discount programs and diagnosis-related group bundled payments.
- Retail Pharmacies:Community pharmacies in urban India and Brazil serve cash-pay patients and supplemental insurance holders outside national reimbursement schemes.
- Online Pharmacies:Telehealth-integrated platforms in the United States and United Kingdom are gaining regulatory traction for maintenance therapy refills, particularly for stable chronic myeloid leukemia patients.
- Direct Sales:Manufacturer-to-institution contracts in Saudi Arabia and South Africa bypass wholesale markup for high-volume hematology center networks.
Hospital pharmacies hold the largest share; momentum sits with online pharmacies as prior authorization automation reduces friction for oral oncology continuity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and EMA priority review tracks are compressing market entry timelines for dasatinib manufacturers across regulated jurisdictions, while national essential medicines list inclusions in emerging economies are reshaping procurement volumes and pricing authority.
United States
Medicare Part D prior authorization automation is reducing friction for chronic myeloid leukemia maintenance therapy continuity. The FDA's tightening bioequivalence standards for highly variable drugs are extending generic development timelines. Philadelphia and Boston hematology centers anchor clinical trial enrollment and drive protocol standardization across regional hospital networks.
Germany
G-BA positive technology appraisals support broad reimbursement access for first-line and second-line BCR-ABL kinase inhibition. REACH compliance for pharmaceutical excipients is tightening supply chain documentation requirements across European manufacturing. Frankfurt and Munich contract manufacturers are qualifying alternative excipient suppliers and accelerating internal toxicology testing programs.
Japan
PMDA streamlined approval for reduced-intensity dosing protocols is opening post-remission refill markets for maintenance therapy. The country's national pharmaceutical regulator maintains direct relationships with manufacturers for managed access programs at specialty cancer centers. Tokyo and Osaka hematology units concentrate high-acuity cases and drive pediatric protocol adoption.
India
CDSCO essential medicines list expansion for oncology therapies is unlocking centralized procurement volumes at state hospital networks. The national pharmaceutical regulator imposes additional layer requirements on active pharmaceutical ingredient sourcing and finished dosage form stability data. Hyderabad and Ahmedabad manufacturers concentrate active pharmaceutical ingredient production for export-led growth.
Switzerland
Swissmedic maintains rigorous post-market pharmacovigilance reporting obligations that directly determine market access timelines for kinase inhibitors. Originators defend market position through lifecycle management and co-pay assistance programs in commercial insurance segments. Basel and Zurich anchor originator patent estate management and clinical data package development for regulated markets.
Dasatinib Market Competitive Environment
Listed leaders compete with private specialists across regulatory dossier capabilities and manufacturing scale. The market structure concentrates around originator defense of branded positioning against generic filers exploiting abbreviated review windows. Three archetypes dominate: patent-holding originators with clinical data packages, multi-jurisdiction generic filers with bioequivalence expertise, and cost-optimized emerging market suppliers. Competitive moves center on lifecycle management extensions and pediatric exclusivity claims.
Within the originator tier, Bristol-Myers Squibb Company occupies a position defending branded markets through patent estate management. Among generic specialists, Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Limited exemplify multi-jurisdiction dossier submission strategies. These three anchors represent the competitive tension between innovation-driven and scale-driven market participation.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Teva Pharmaceutical Industries Ltd. |
| Sandoz Group AG |
| Sun Pharmaceutical Industries Limited |
| Dr. Reddy's Laboratories Limited |
| Hetero Drugs Limited |
| Cipla Limited |
| Lupin Limited |
| Aurobindo Pharma Limited |
| Others |
Value Chain & Pricing Dynamics
Institutional purchasing agreements with hematology center networks lock in multi-year supply access and price visibility for dasatinib manufacturers serving regulated markets. These contracts anchor volume commitments against API sourcing volatility while capping annual price escalation through diagnosis-related group bundled payment frameworks.
Pricing Analysis
Certification level (FDA-grade, EMA-grade, WHO-prequalified) creates the primary spread between originator and generic tiers. Pricing stratifies across premium branded, standard authorized generic, and economy unbranded tiers based on bioequivalence data package completeness and pediatric exclusivity status. Cost compression in the economy tier is intensifying because Indian manufacturers are consolidating API-to-finished-dose vertical integration. Government hospital networks in emerging economies exhibit highest price sensitivity; commercial insurance segments in the United States and Switzerland show lowest sensitivity due to co-pay assistance program absorption.
Supply Chain Analysis
Port congestion on India-Europe pharmaceutical trade lanes is elevating inbound logistics costs for API shipments bound to European contract manufacturers. Active pharmaceutical ingredient production concentrates in India and China, with finished dose formulation anchored in Germany, India, and Japan. The supply chain draws from N-methylpiperazine, 4-chloro-3-nitrobenzoic acid, and specialized kinase inhibitor synthesis catalysts as critical inputs. Single-source vulnerability in Chinese intermediate manufacturing poses structural risk. Distribution runs through hospital pharmacy captive wholesalers in regulated markets and direct-manufacturer contracting in Gulf Cooperation Council states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dasatinib sits in early-cycle expansion as pediatric protocol adoption widens the addressable patient base beyond adult chronic myeloid leukemia populations. This tailwind justifies capacity positioning ahead of indication label expansions across Asian and European regulatory jurisdictions.
For Market Incumbents: Consolidate formulary position through lifecycle management investments in oral suspension formulations and pediatric exclusivity extensions. Deepen backward integration into API synthesis to offset margin pressure from bioequivalence threshold escalation at FDA. Lock in hematology center purchasing agreements before abbreviated new drug application windows open for second-wave generic filers.
For New Entrants and Emerging Players: Post-remission maintenance therapy refill services represent a service-layer gap where incumbents under-serve stable chronic myeloid leukemia patients. Target telehealth-integrated specialty pharmacy channels in Medicare Part D networks as the most penetrable segment. Pursue CDSCO essential medicines list inclusion as the primary go-to-market angle for Indian state hospital network procurement.
For Investors and Strategic Acquirers: Multi-jurisdiction generic dossier specialists with WHO prequalification track records present the most attractive acquisition target archetype. Long-term viability hinges on regulatory navigation capabilities rather than molecular novelty, positioning these assets for sustained cash generation across patent cliff cycles. Watch FDA bioequivalence guidance revisions for kinase inhibitors as the signal to watch for inflection in generic development timeline economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Development | PMDA and CDSCO pediatric indication approvals unlock new patient volumes in Asia-Pacific markets. |
| API Backward Integration | Captive supply of dasatinib intermediates insulates margins from Indian and Chinese sourcing concentration risks. |
| Online Pharmacy Channel Partnership | Telehealth-prescribed maintenance therapy refills reduce patient attrition in chronic myeloid leukemia protocols. |
| WHO Prequalification Submission | Tropical climate zone stability data packages enable access to African and Southeast Asian public procurement tenders. |
| REACH Excipient Reformulation | ECHA substance of very high concern compliance preserves European manufacturing access for tablet coatings. |
Study Parameters
Desk research of FDA new drug application filings, EMA marketing authorization submissions, and ClinicalTrials.gov enrollment databases preceded structured interviews with regulatory affairs leads, formulary directors at hematology centers, and hospital procurement managers. Secondary validation drew from WHO prequalification assessments, national essential medicines list publications, and SEC 10-K pharmaceutical segment disclosures. Bottom-up patient volume modeling and top-down market sizing triangulation anchored value estimates.
Variance decomposition across dosage form, therapy area, and regional regulatory cluster segmentation dimensions informed projection construction. Growth trajectories were derived from indication expansion rates, generic entry probability assessments, and reimbursement policy elasticity estimates across the analysis window. Forecast inputs incorporated pediatric protocol enrollment curves from cooperative trial groups and bioequivalence study completion timelines from abbreviated new drug application filers.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO approval pathways; material policy shifts would require re-modeling of generic entry timelines and reimbursement access assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Insulin Biosimilars Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Biosimilar Testing Services Market
Biosimilars
Etanercept Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Global Sirolimus Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Imatinib Drug Market
Biosimilars
Global Biosimilars Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Biologics and Biosimilars Market