
 Retinal Biosimilars Market | 2026-2036
Retinal Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Biosimilars Market Analytics
Recombinant protein expression in mammalian cell culture is rewriting manufacturing economics for retinal biosimilars. Samsung Bioepis leverages its CHO-platform scale to drive cost parity with reference biologics. Biocon Biologics anchors its position through integrated fill-finish capabilities in emerging markets. Novartis (Sandoz) competes on regulatory dossier breadth across multiple ophthalmic indications.
Retinal biosimilars are recombinant monoclonal antibodies or fusion proteins that bind vascular endothelial growth factor (VEGF) to inhibit pathological angiogenesis in retinal diseases; they are produced in bioreactor systems with glycosylation profiles matched to reference products for clinical equivalence. Ranibizumab biosimilars dominate current volume owing to expired patent cliffs and established intravitreal injection protocols. Bevacizumab biosimilars occupy the fastest-expanding margin pool as off-label retinal use gains formal regulatory endorsement. Intravitreal injection sustains its position as the leading delivery method due to direct vitreous humor access and validated safety databases.
The FDA's interchangeable designation and EMA's biosimilar authorization framework shape market access timelines and prescriber trust. India's CDSCO and CDSCO-aligned state regulators accelerate domestic manufacturing approvals for export-oriented producers. Stakeholders must monitor evolving pharmacovigilance requirements for long-acting aflibercept biosimilars as patent expiries approach.
Market Dynamics
The FDA's interchangeable biosimilar designation pathway is compressing prescriber hesitation windows and accelerating formulary adoption in hospital ophthalmology departments, fundamentally restructuring how retinal care providers select VEGF inhibitors.
Growth Catalysts
- Medicare Part B reimbursement policies:The United States federal reimbursement framework incentivizes biosimilar uptake through favorable payment differentials, driving volume migration from reference biologics in outpatient retinal clinics.
- Intravitreal injection protocols:Established administration techniques in vitreoretinal surgery reduce training barriers and accelerate biosimilar onboarding without procedural modification.
- Patent cliff maturation:Expired exclusivity periods for ranibizumab reference products unlock multi-source competition and price compression across mature markets.
Market Restraints
- Glycosylation matching complexity:Mammalian cell culture variability creates analytical characterization burdens that extend development timelines and raise CMC costs for biosimilar developers.
- Reference product supply concentration:Originator biologics maintain residual market presence through brand loyalty and long-term safety databases, limiting rapid share erosion.
- Immunogenicity surveillance requirements:Pharmacovigilance obligations for anti-drug antibody monitoring impose post-market cost structures that erode margin projections.
Strategic Opportunities
- Brazil's ANVISA accelerated pathway:The South American regulator's streamlined biosimilar authorization creates first-mover positioning for export-oriented manufacturers seeking emerging market access.
- Long-acting aflibercept formulations:Extended-duration VEGF inhibition technologies promise reduced injection frequency and improved patient compliance in chronic retinal disease management.
- Teleophthalmology screening integration:Remote diagnostic platforms expand addressable patient pools for anti-VEGF therapy by identifying treatment-naive cases in underserved regions.
Industry Challenges
- Comparative clinical trial design:Equivalence study requirements for retinal indications demand large patient cohorts and extended follow-up periods, straining development budgets.
- Cold chain integrity maintenance:Temperature-sensitive biologic logistics complicate distribution to rural ophthalmology practices and ambulatory surgery centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Biosimilars Market |
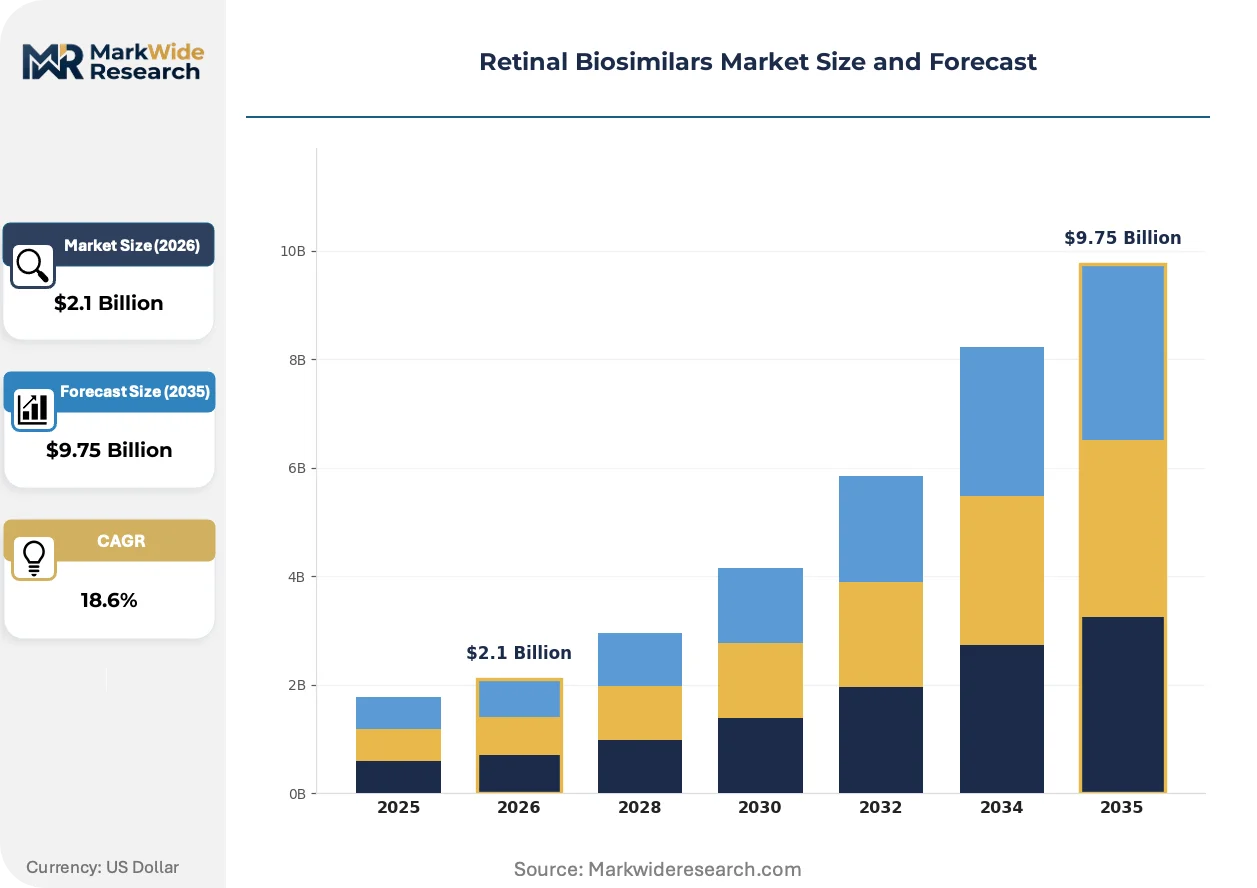
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ranibizumab, Bevacizumab, Aflibercept, Others Delivery Method: Intravitreal Injection, Subconjunctival Injection, Retrobulbar Injection, Others End User: Ophthalmic Clinics, Hospitals, Research Laboratories, Others Sales Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Wholesale Distributors |
| Companies Covered | Novartis (Sandoz), Samsung Bioepis, Biocon Biologics, Regeneron Pharmaceuticals, Bayer, Takeda, Reliance Life Sciences, Hetero Drugs, Coherus BioSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Biosimilars Market Evolving Landscape
Bioprocess intensification and regulatory science advances are compressing development-to-commercialization timelines while reshaping competitive differentiation beyond mere price parity.
Continuous manufacturing platforms for monoclonal antibody production are rendering obsolete batch-process economics in biosimilar manufacturing. Samsung Bioepis and Biocon Biologics deploy perfusion bioreactor systems that yield higher cell densities with reduced facility footprints. Hospital purchasing committees now weight manufacturing reliability alongside unit cost in formulary decisions.
EMA's biosimilar authorization framework and FDA's interchangeable designation pathway are converging toward mutual recognition principles that streamline multi-territory launches. European retinal specialists increasingly accept extrapolated indications, reducing the need for indication-specific clinical trials. German statutory health insurers now mandate biosimilar prescribing quotas for anti-VEGF therapies.
Hospital ophthalmology departments are consolidating procurement authority through centralized pharmacy committees, displacing individual physician autonomy in product selection. Academic medical centers in the United States negotiate system-wide contracts that bundle ranibizumab and bevacizumab biosimilars under single vendor agreements. This concentration shifts negotiating leverage toward large integrated delivery networks and away from distributed private practices.
Retinal Biosimilars Market Segmentation
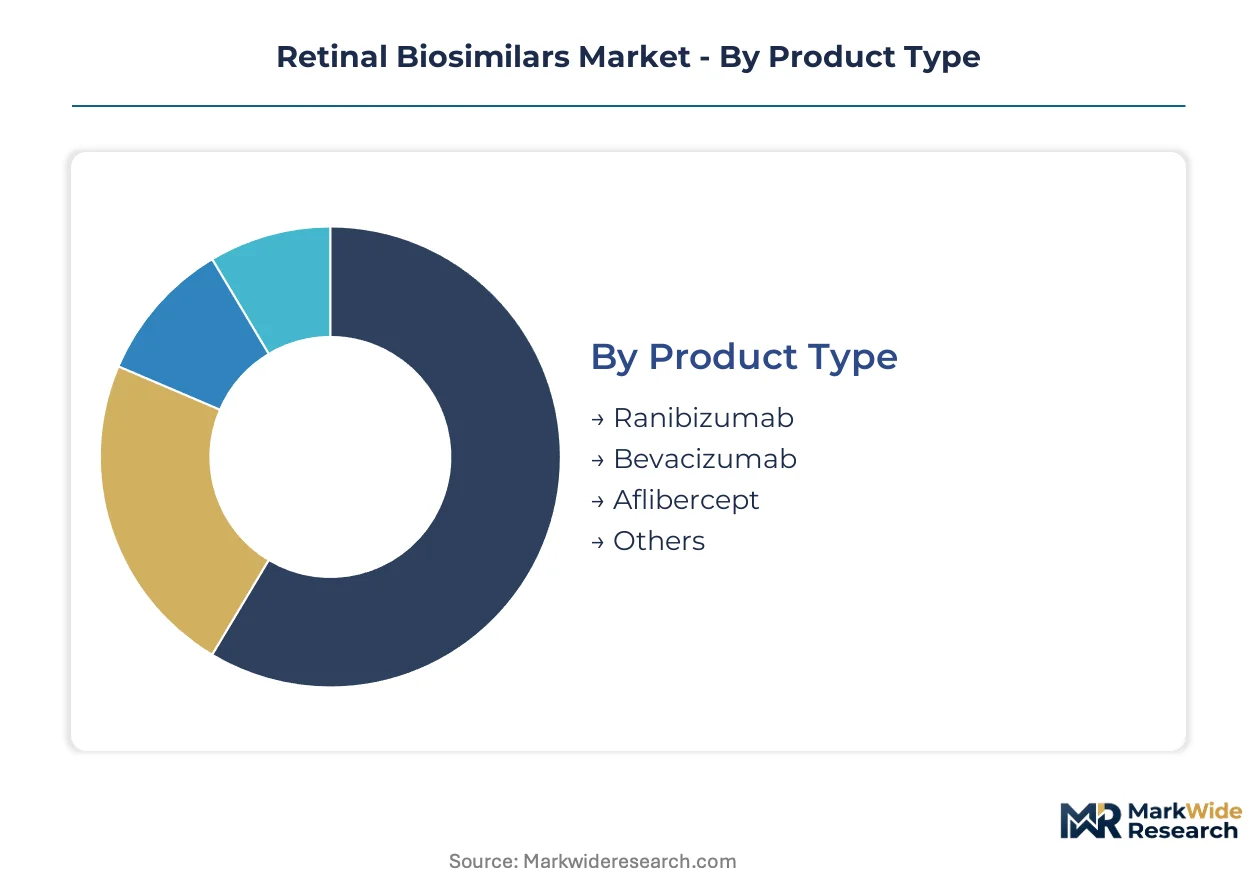
Retinal biosimilar manufacturers deploy distinct positioning strategies across molecular types, delivery modalities, and procurement channels. Segmentation reveals where price compression, clinical validation requirements, and supply chain investments concentrate competitive resources.
Product Type:
Mature anti-VEGF molecules anchor current revenue pools while emerging formulations reshape development pipelines.
- Ranibizumab:The Fab fragment antibody binds VEGF-A with high affinity for intravitreal administration. United States hospital formularies favor ranibizumab biosimilars for Medicare Part B reimbursement efficiency, though reference product loyalty persists in academic medical centers.
- Bevacizumab:Full-length humanized monoclonal antibody requires compounding pharmacy preparation for ocular use. Off-label retinal adoption accelerates as regulatory bodies formalize ophthalmic indications, expanding the addressable patient base beyond oncology-originated supply chains.
- Aflibercept:VEGF trap fusion protein with extended binding kinetics to VEGF-A, VEGF-B, and PlGF.
- Others:Emerging biosimilar candidates targeting novel angiogenic pathways and sustained-release formulations.
Ranibizumab retains volume leadership; bevacizumab holds the steepest expansion curve.
Delivery Method:
Cost tier stratification separates validated intravitreal protocols from emerging administration techniques.
- Intravitreal Injection:Direct vitreous humor delivery via pars plana puncture achieves therapeutic drug concentrations with minimal systemic exposure. Vitreoretinal surgery suites in Germany and Japan standardize this technique, reducing training barriers for biosimilar onboarding.
- Subconjunctival Injection:Scleral surface administration targets anterior segment vascularization with lower penetration depth. Emerging markets explore this route for cost-sensitive settings where specialized surgical infrastructure remains limited.
- Retrobulbar Injection:Orbital fat space delivery for posterior segment access in specific surgical contexts.
- Others:Sustained-release implants and topical formulations under investigation for injection burden reduction.
Intravitreal injection commands the premium tier; subconjunctival approaches are climbing fastest in cost-constrained environments.
End User:
Customer type determines procurement authority concentration and clinical validation requirements.
- Ophthalmic Clinics:Specialized outpatient facilities perform the majority of anti-VEGF injections in the United States. Independent practices in Florida and California negotiate directly with biosimilar manufacturers for volume-based pricing outside hospital system contracts.
- Hospitals:Integrated delivery networks consolidate purchasing through centralized pharmacy committees. Academic medical centers in Massachusetts and Pennsylvania mandate biosimilar formulary placement for cost containment.
- Research Laboratories:Clinical trial sites and pharmacovigilance centers generate real-world evidence for interchangeability designations.
- Others:Ambulatory surgery centers and teleophthalmology platforms expanding treatment access.
Hospital systems concentrate procurement leverage; ophthalmic clinics are expanding most quickly in patient-facing volume.
Sales Channel:
Supply concentration varies across direct hospital contracting and distributed retail networks.
- Hospital Pharmacies:Captive distribution within integrated delivery networks enables just-in-time inventory for temperature-sensitive biologics. United States group purchasing organizations bundle retinal biosimilars with surgical supplies under single-source agreements.
- Wholesale Distributors:Cold chain specialists maintain validated logistics for multi-site ophthalmology practices. McKesson and Cardinal Health networks cover rural clinics in Texas and Arizona where direct manufacturer relationships prove uneconomical.
- Retail Pharmacies:Community-based dispensing for specialty pharmacy benefit management programs.
- Online Pharmacies:Emerging direct-to-patient models for chronic therapy management and refill coordination.
Hospital pharmacies dominate high-value transactions; wholesale distributors are gaining share fastest in geographic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian manufacturers export ranibizumab and bevacizumab biosimilars to hospital systems across the United States, Germany, and Brazil, establishing a south-north trade corridor that anchors supply security for Western retinal care markets.
United States
Medicare Part B reimbursement differentials drive biosimilar volume migration in Florida and California ophthalmology clusters. FDA's interchangeable designation pathway compresses formulary adoption timelines for hospital pharmacy committees. The Cleveland Clinic and Mayo Clinic systems negotiate bundled contracts covering ranibizumab and bevacizumab biosimilars under single-source agreements.
Germany
Statutory health insurance mandates for anti-VEGF biosimilar prescribing quotas reshape procurement in Bavaria and North Rhine-Westphalia. EMA's centralized authorization framework enables rapid multi-state formulary placement. Heidelberg and Berlin academic medical centers consolidate purchasing through centralized pharmacy committees that displace individual physician autonomy.
India
CDSCO accelerates domestic manufacturing approvals for export-oriented producers targeting regulated markets. The country's national pharmaceutical regulator aligns state-level inspectors to international GMP standards. Hyderabad and Bangalore biotech clusters integrate perfusion bioreactor systems with captive fill-finish capabilities for cost-competitive mammalian cell culture production.
Brazil
ANVISA's streamlined biosimilar authorization pathway creates first-mover positioning for manufacturers seeking Latin American market access. São Paulo hospital ophthalmology departments expand biosimilar formularies for age-related macular degeneration treatment. The Southeast region concentrates intravitreal injection volume in academic medical centers that train vitreoretinal specialists for national distribution.
Japan
PMDA's biosimilar approval framework emphasizes extrapolated indication acceptance for retinal therapies. Kansai and Kanto regions host specialized vitreoretinal surgery suites that standardize intravitreal protocols. Osaka and Tokyo university hospitals generate real-world evidence for interchangeability designations through pharmacovigilance networks.
Retinal Biosimilars Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers, producing a bifurcated structure where hospital system contracts concentrate volume while regional distributors capture geographic expansion. The vendor base separates into three strategic archetypes: integrated biopharmaceutical conglomerates with regulatory dossier breadth, cell-culture platform specialists leveraging manufacturing scale, and emerging-market producers with backward-integrated fill-finish capabilities. Dominant competitive moves include capacity expansion in perfusion bioreactor systems and strategic partnerships for multi-territory commercialization rights.
Among integrated biopharmaceutical conglomerates, Novartis (Sandoz) and Bayer exemplify the regulatory dossier breadth archetype, occupying positions that span multiple ophthalmic indications beyond retinal care. Samsung Bioepis and Biocon Biologics represent the cell-culture platform specialist tier, with geographic origins in South Korea and India respectively anchoring their manufacturing economics. Coherus BioSciences sits within the United States-based commercialization-focused archetype, emphasizing payer contracting expertise over captive production infrastructure.
| Leading Market Players |
|---|
| Novartis (Sandoz) |
| Samsung Bioepis |
| Biocon Biologics |
| Regeneron Pharmaceuticals |
| Bayer |
| Takeda |
| Reliance Life Sciences |
| Hetero Drugs |
| Coherus BioSciences |
| Others |
Value Network & Pricing Analysis
The Hyderabad-to-Frankfurt cold chain corridor anchors supply security for temperature-sensitive retinal biosimilars, with per-kilogram freight costs compressing margin structures for Indian exporters while enabling three-tier pricing stratification across premium reference-matched, standard biosimilar, and economy bevacizumab-repurposed tiers in Western European hospital formularies.
Pricing Analysis
Cost-plus contracts indexed to mammalian cell culture media prices dominate hospital system negotiations, with formulary placement contingent on glycosylation batch consistency rather than unit cost alone. Price differentiation separates FDA-interchangeable designated products from standard biosimilar authorizations, with German statutory insurers mandating lowest-cost prescribing for anti-VEGF therapies. Pricing pressure stems from Medicare Part B reimbursement compression in United States outpatient clinics, where academic medical centers resist rapid switching despite payer incentives. Ophthalmic clinics in Florida and California exhibit highest price sensitivity, while Massachusetts academic centers prioritize clinical validation over acquisition cost.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk planning for export-oriented manufacturers, with CDSCO-aligned state inspectors accelerating GMP certification timelines to maintain market access. Production concentrates in India, South Korea, and Germany, with perfusion bioreactor systems drawing from Chinese-sourced single-use bioreactor bags and German chromatography resins. Single-source vulnerability in fill-finish equipment creates bottlenecks for multi-product facilities. Distribution runs through hospital pharmacy captive networks in integrated delivery systems, with wholesale distributors covering geographic expansion into rural ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The retinal biosimilars market sits in early-cycle expansion, with FDA interchangeable designations accelerating prescriber confidence beyond historical biosimilar adoption curves in ophthalmology.
For Market Incumbents: Pre-empt long-acting aflibercept formulation launches by securing perfusion bioreactor capacity expansion in South Korean manufacturing clusters before patent cliff maturation. Samsung Bioepis and Novartis (Sandoz) must defend formulary position through backward integration into single-use assembly components, insulating margin structures from Chinese supply volatility. Hospital system contract bundling represents the priority defensive lever against emerging Indian exporters. For New Entrants and Emerging Players: Pursue Brazil's ANVISA accelerated pathway for first-mover positioning in Latin American ophthalmology departments, where São Paulo academic medical centers generate training pipelines for national distribution. Subconjunctival injection formulations in cost-constrained Southeast Asian markets offer the most penetrable white-space, with teleophthalmology screening partnerships as the go-to-market angle for treatment-naive patient identification. For Investors and Strategic Acquirers: Cell-culture platform specialists with captive fill-finish capabilities in Indian biotech clusters represent the acquisition target archetype, with CDSCO export certification timelines as the inflection indicator for manufacturing scalability. Long-term viability across the analysis window hinges on regulatory dossier breadth across multiple ophthalmic indications rather than single-molecule concentration. Monitor EMA-FDA mutual recognition progression for multi-territory launch leverage.| Strategic Initiative | Industry Significance |
|---|---|
| Interchangeable Designation Pursuit | FDA interchangeable status compresses formulary adoption timelines in hospital ophthalmology departments. |
| Perfusion Bioreactor Scale-Up | Samsung Bioepis leverages continuous manufacturing platforms to achieve cost parity with reference biologics. |
| ANVISA Pathway Entry | Brazil's streamlined authorization creates first-mover positioning for Latin American market access. |
| Hospital System Contract Bundling | Integrated delivery networks in the United States negotiate single-vendor agreements covering multiple anti-VEGF molecules. |
| Teleophthalmology Platform Integration | Remote diagnostic networks expand addressable patient pools for anti-VEGF therapy in underserved regions. |
Research Methodology
Desk research of FDA 351(k) submission databases, EMA CHMP assessment reports, and ClinicalTrials.gov ophthalmology trial registries preceded structured interviews with vitreoretinal surgeons, hospital pharmacy directors, formulary committee chairs, and payer access specialists. Primary fieldwork across United States integrated delivery networks, German statutory health insurers, and Indian CDSCO inspection records combined with secondary validation from CMS Medicare Part B claims data and hospital procurement databases. Bottom-up patient volume modeling and top-down manufacturer capacity triangulation anchored market sizing.
Assumptions held fixed include current FDA interchangeable designation criteria and existing Medicare Part B reimbursement differentials, while variables spanned patent litigation outcomes and EMA-FDA mutual recognition progression. Segmentation dimensions encompassed molecular type, delivery method, end user procurement authority, and regional regulatory cluster. CAGRs derived from patient population epidemiology and injection frequency modeling, with biosimilar penetration curves calibrated to historical ophthalmology adoption patterns and interchangeability designation timelines.
Macroeconomic conditions sit as an overlay; deviation in bioreactor equipment capital costs or cold chain logistics pricing would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and reference product supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Oncology Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Global Biosimilars Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
Imatinib Drug Market
Biosimilars
US Biosimilars Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Middle East and Africa Biologics and Biosimilar Market
Biosimilars
Insulin Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Global Sirolimus Market