
 Biosimilar Testing Services Market | 2026-2036
Biosimilar Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Biosimilar Testing Services Market Outlook
The capital-intensity divergence between full-service analytical platforms and specialized immunogenicity boutiques is bifurcating competitive dynamics in biosimilar testing. Thermo Fisher Scientific leverages its integrated mass spectrometry and cell-line development infrastructure to anchor large-molecule comparability programs across multiple geographies. Charles River Laboratories competes through its captive biologics testing capacity, while WuXi AppTec extends cost-advantaged bioanalytical scale from China into European sponsor workflows.
Biosimilar testing services encompass analytical and biological characterization activities that establish similarity between a candidate biosimilar and its reference biologic, employing techniques such as peptide mapping via LC-MS, glycan profiling, and binding kinetics measurement to satisfy regulatory comparability criteria. These services reduce sponsor risk by generating the quality, safety, and efficacy evidence required for marketing authorization submissions. Immunogenicity testing and mass spectrometry now capture expanding margin pools as regulators demand deeper characterization of anti-drug antibody responses and higher-order protein structure. Stability testing retains volume leadership due to mandatory long-term protocol requirements, though clinical trial support services show the fastest growth trajectory as biosimilar pipelines diversify beyond oncology into immunology and ophthalmology.
The FDA's Biosimilar User Fee Act and EMA's biosimilar guidelines jointly elevate analytical rigor, directly expanding the scope and cost of outsourced testing programs. BIS in India and NMPA in China are developing localized biosimilar standards that create additional jurisdiction-specific testing obligations for multinational sponsors. Stakeholders must monitor regulatory divergence on interchangeability standards and analytical comparability thresholds as these definitions will determine which testing packages command premium pricing versus commoditized execution.
Market Dynamics
The FDA's Biosimilar User Fee Act reauthorization and EMA's evolving interchangeability guidance are tightening analytical requirements, forcing sponsors to expand outsourced testing programs across mass spectrometry, immunogenicity, and stability protocols.
Growth Catalysts
- Regulatory stringency:The FDA's interchangeability designation pathway demands expanded analytical comparability packages, compelling pharmaceutical sponsors to outsource complex characterization studies.
- Reference product patent cliffs:Expiring exclusivity on blockbuster biologics in the United States and Germany accelerates biosimilar pipeline submissions and associated testing volumes.
- High-resolution mass spectrometry:Advanced LC-MS platforms enable deeper glycan profiling and higher-order structure analysis, satisfying evolving regulatory expectations for molecular similarity evidence.
Market Restraints
- Capital intensity:Establishing compliant bioanalytical laboratories requires substantial investment in mass spectrometry suites, cell-based assay infrastructure, and qualified personnel.
- Specialized talent scarcity:Shortages of analytical scientists with large-molecule characterization expertise constrain capacity expansion at contract testing organizations.
- Regulatory divergence:BIS in India and NMPA in China are developing jurisdiction-specific biosimilar standards, fragmenting testing protocols and complicating multinational sponsor strategies.
Strategic Opportunities
- Ophthalmology pipeline expansion:Biosimilar development for ranibizumab and aflibercept analogues creates demand for specialized ocular tissue penetration and stability testing services.
- Immunology diversification:Adalimumab and infliximab follow-on programs require expanded immunogenicity surveillance, opening premium service tiers for anti-drug antibody assay development.
- Integrated analytical-bioanalytical bundles:Sponsors seek single-provider solutions spanning physicochemical characterization through clinical pharmacokinetics, favoring full-service contract research organizations.
Industry Challenges
- Cross-platform data harmonization:Sponsors must reconcile analytical outputs across multiple contract laboratories using divergent instrumentation and standard operating procedures.
- Interchangeability study complexity:FDA requirements for switching studies and pharmacovigilance planning extend program timelines and escalate documentation burdens.
- Reference product sourcing:Securing consistent, well-characterized innovator biologic lots for comparability testing remains operationally constrained.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosimilar Testing Services Market |
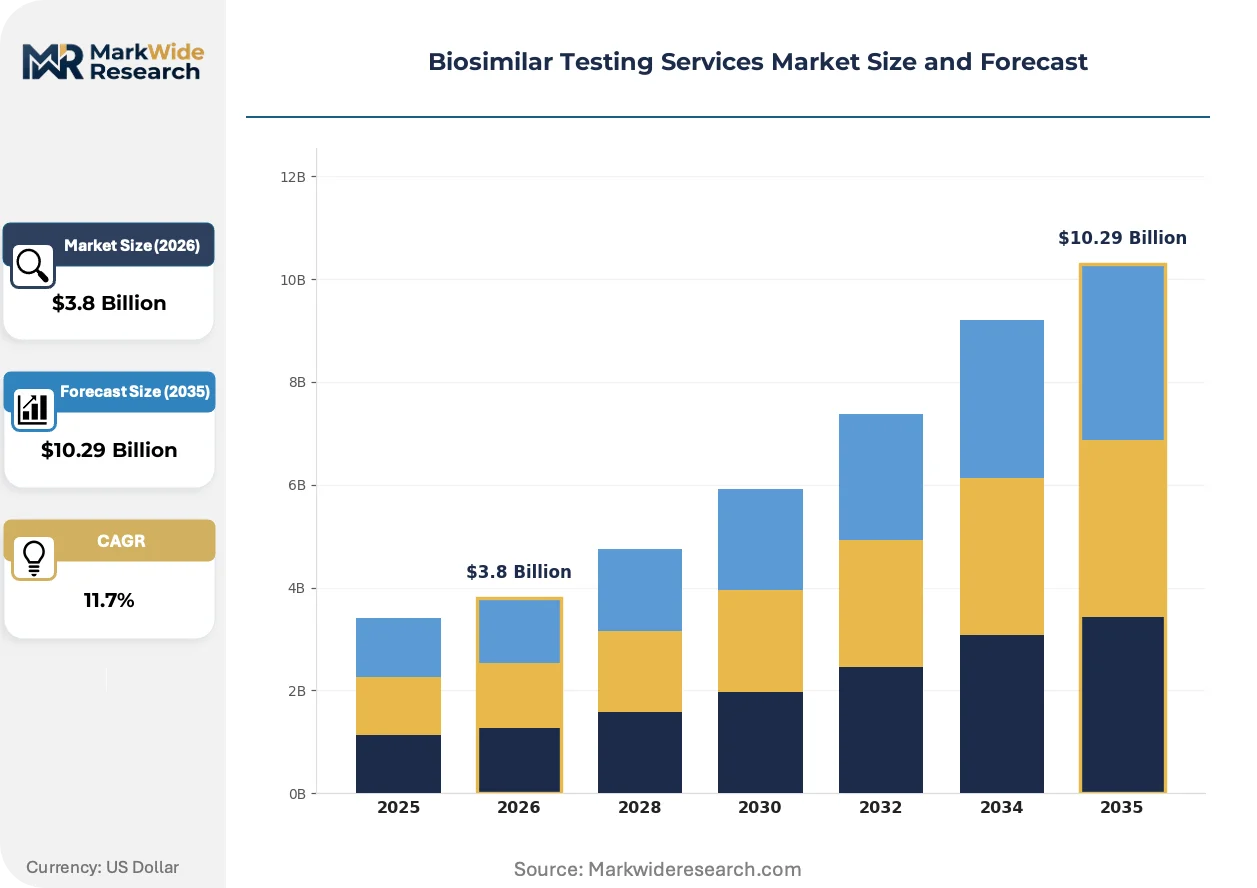
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Stability Testing, Bioanalytical Testing, Clinical Trials, Immunogenicity Testing End User: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Academic Institutions Technology: ELISA, QCM, HPLC, Mass Spectrometry Application: Regulatory Submissions, Quality Assurance, Market Authorization, Therapeutic Development |
| Companies Covered | Thermo Fisher Scientific, Charles River Laboratories, WuXi AppTec, Eurofins Scientific, Labcorp, SGS, Merck KGaA, BioReliance (MilliporeSigma), PACE Analytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosimilar Testing Services Market Strategic Shifts
Advanced analytical instrumentation and regulatory data requirements are reshaping how biosimilar sponsors structure their outsourcing relationships and testing program architectures.
High-resolution mass spectrometry is bifurcating service provider capabilities. Full-service contract research organizations deploy Orbitrap and Q-TOF platforms for comprehensive higher-order structure analysis, while specialized boutiques focus on niche glycan microheterogeneity profiling. Large pharmaceutical sponsors consolidate programs with integrated providers capable of end-to-end comparability packages. This capability split is compressing margins for mid-tier laboratories lacking capital depth for platform investment.
EMA's revised biosimilar guidelines emphasize immunogenicity risk assessment and post-authorization surveillance. The framework mandates more extensive anti-drug antibody characterization and neutralizing antibody assays. European sponsors now embed extended immunogenicity testing into Phase III protocols rather than treating it as a post-hoc requirement. Contract laboratories with captive immunogenicity centers capture disproportionate share of expanded analytical spending.
Sponsor procurement of biosimilar testing services is consolidating under preferred provider arrangements with multi-year analytical development partnerships. Large pharmaceutical companies reduce vendor counts from eight to three relationships, exchanging volume commitments for priority scheduling and dedicated scientific teams. This concentration shift is most pronounced in Germany and the United States, where reference product litigation risk and regulatory scrutiny elevate the cost of analytical program disruption.
Biosimilar Testing Services Market Segmentation
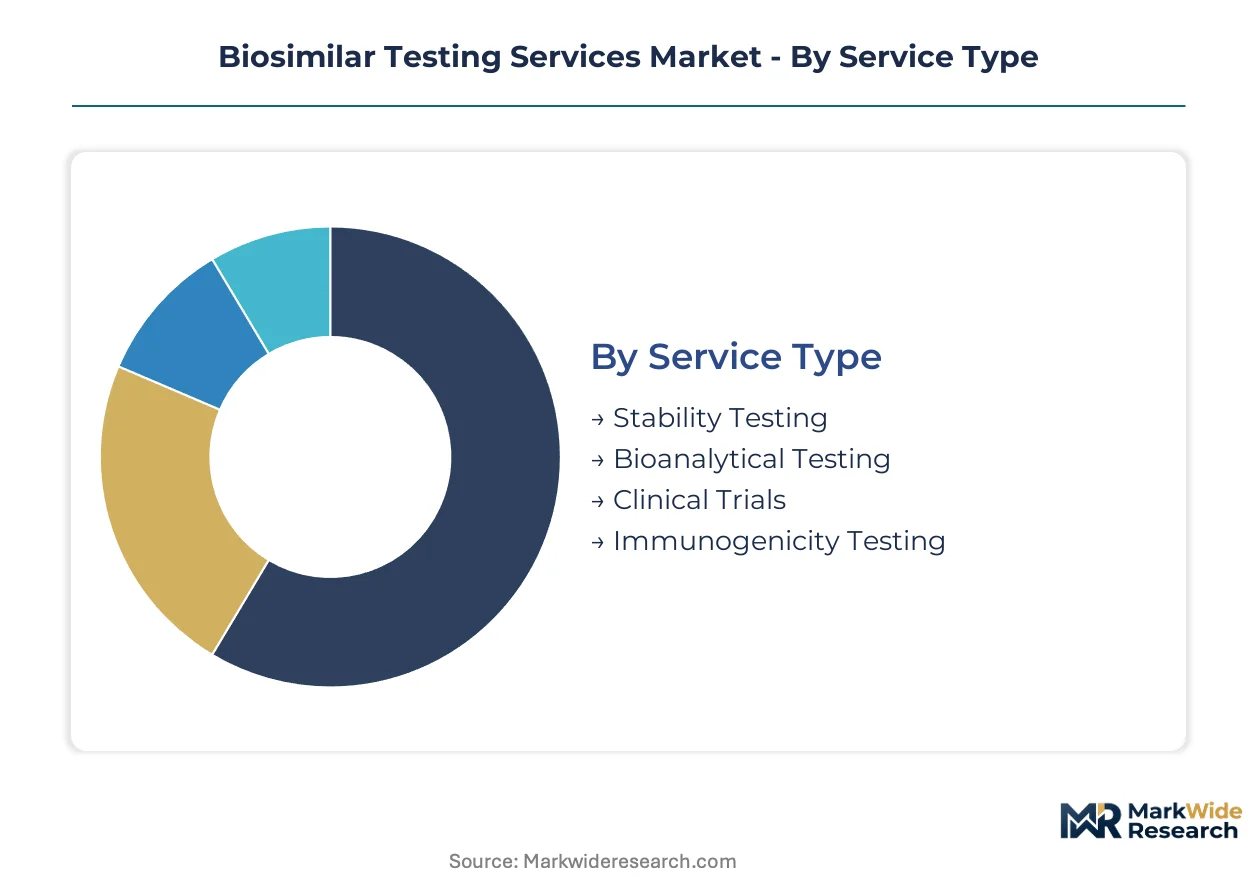
Segmentation in biosimilar testing services reveals how analytical capabilities align with regulatory pathways and sponsor risk profiles. Testing providers configure service portfolios around mandatory stability protocols, high-margin immunogenicity suites, and the bioanalytical demands of interchangeability designations.
Service Type:
Substitution pressure concentrates in standardized stability protocols where automated systems and reference product sourcing networks create commodity-like execution, while specialized immunogenicity and mass spectrometry services retain differentiation through scientific expertise and platform investment.
- Stability Testing:Long-term forced degradation studies and real-time storage condition monitoring generate the bulk of regulatory submission data for biosimilar sponsors. Pharmaceutical companies in the United States and Germany outsource these protocols to avoid capital expenditure on climate-controlled storage infrastructure and accelerated aging chambers.
- Immunogenicity Testing:Anti-drug antibody assay development and neutralizing antibody characterization command premium pricing as FDA interchangeability guidelines mandate expanded immunogenicity surveillance. Sponsors developing adalimumab and infliximab biosimilars embed these services into Phase III programs rather than treating them as post-hoc requirements.
- Bioanalytical Testing:Pharmacokinetic and pharmacodynamic assay support for clinical comparability studies.
- Clinical Trials:End-to-end analytical support for switching studies and pharmacovigilance planning.
Stability Testing anchors the volume base while Immunogenicity Testing gains share at the steepest rate.
End User:
Cost tier stratification separates large pharmaceutical sponsors with integrated outsourcing strategies from emerging biotech firms purchasing discrete analytical modules.
- Pharmaceutical Companies:Multinational sponsors consolidate testing relationships under preferred provider arrangements, exchanging multi-year volume commitments for priority scheduling and dedicated scientific teams. These organizations drive demand for bundled analytical-bioanalytical services spanning physicochemical characterization through clinical pharmacokinetics.
- Biotech Firms:Emerging developers lack captive analytical infrastructure and purchase discrete testing modules on a study-by-study basis. These sponsors concentrate in United States innovation clusters and German biotech hubs, where reference product patent cliffs accelerate pipeline submissions.
- Contract Research Organizations:Mid-tier CROs subcontract specialized capabilities to full-service providers with mass spectrometry and immunogenicity platforms.
- Academic Institutions:Research programs generate limited commercial testing volumes focused on method development and analytical innovation.
Pharmaceutical Companies dominate current spending while Biotech Firms expand most quickly as biosimilar development democratizes beyond established players.
Technology:
Application requirements dictate technology selection, with regulatory submission standards elevating certain platforms over alternatives.
- Mass Spectrometry:High-resolution LC-MS platforms enable peptide mapping, glycan profiling, and higher-order structure analysis required for molecular similarity evidence. Full-service providers deploy Orbitrap and Q-TOF systems to anchor large-molecule comparability programs.
- ELISA:Enzyme-linked immunosorbent assays remain the workhorse for anti-drug antibody detection and binding kinetics measurement in immunogenicity workflows.
- HPLC:Chromatographic separation supports purity assessment and impurity profiling across stability protocols.
- QCM:Quartz crystal microbalance techniques address niche real-time binding analysis applications in early-stage characterization.
Mass Spectrometry commands the steepest expansion trajectory as regulators demand deeper structural characterization, while ELISA retains volume leadership through immunogenicity protocol ubiquity.
Application:
Customer type and regulatory maturity segment demand across the application spectrum.
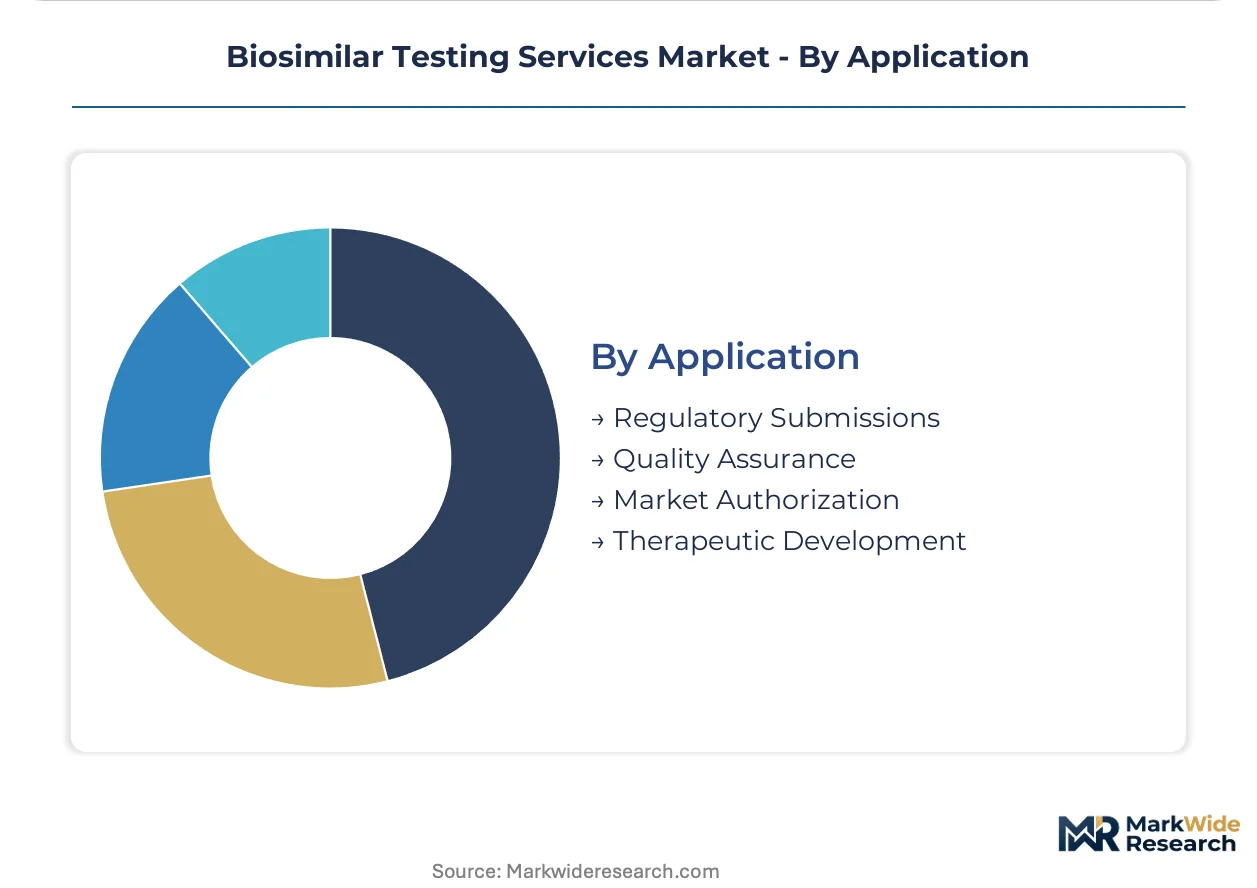
- Regulatory Submissions:Comprehensive comparability packages for FDA, EMA, and emerging authority filings represent the highest-value application. Sponsors in the United States and Germany commission integrated analytical programs combining mass spectrometry, stability data, and immunogenicity evidence to satisfy interchangeability thresholds.
- Quality Assurance:Release testing and lot-to-lot consistency monitoring support manufacturing compliance.
- Market Authorization:Post-approval analytical surveillance and pharmacovigilance planning extend testing relationships beyond initial submissions.
- Therapeutic Development:Early-stage biosimilar candidate screening and reference product characterization generate lower-margin method development work.
Regulatory Submissions anchor revenue concentration while Market Authorization services climb the fastest as post-approval surveillance obligations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany consume biosimilar testing services through integrated outsourcing partnerships spanning full analytical programs, while India and China fragment demand across discrete module purchases from emerging biotech developers lacking captive infrastructure.
United States
FDA interchangeability designations drive demand for expanded mass spectrometry and immunogenicity packages among large pharmaceutical sponsors. The Biosimilar User Fee Act reauthorization tightens analytical comparability thresholds for switching studies. Greater Boston and San Francisco Bay Area biotech clusters concentrate sponsor headquarters commissioning end-to-end testing bundles.
Germany
Reference product patent cliffs on adalimumab and infliximab accelerate biosimilar pipeline submissions from domestic developers. EMA evolving guidance on immunogenicity risk assessment mandates extended anti-drug antibody surveillance. Munich and Frankfurt Rhine-Main pharmaceutical hubs anchor preferred provider arrangements with multi-year volume commitments.
India
Domestic biotech firms purchase discrete analytical modules on a study-by-study basis rather than integrated programs. BIS develops localized biosimilar standards creating jurisdiction-specific testing obligations for multinational sponsors. Hyderabad and Bangalore biotech corridors concentrate emerging developers outsourcing stability and bioanalytical protocols.
China
NMPA biosimilar pathway maturation expands demand for regulatory submission packages from domestic innovators. Dual carbon goals and green chemistry initiatives reshape laboratory infrastructure investment criteria. Shanghai and Suzhou pharmaceutical zones attract full-service providers establishing captive mass spectrometry and cell-based assay capacity.
Switzerland
Swissmedic alignment with EMA standards simplifies regulatory submission requirements for biosimilar sponsors. Basel and Zurich pharmaceutical clusters concentrate headquarters of multinational firms consolidating testing relationships under single-provider arrangements. Local contract laboratories specialize in high-resolution structural characterization for premium pricing tiers.
Biosimilar Testing Services Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with full-service contract research organizations commanding preferred provider status through bundled analytical-bioanalytical capabilities. Mid-tier laboratories lacking capital depth for Orbitrap and Q-TOF platform investment face margin compression on standardized stability protocols. Two strategic archetypes dominate: integrated full-service providers spanning physicochemical characterization through clinical pharmacokinetics, and specialized immunogenicity boutiques capturing premium pricing through anti-drug antibody assay expertise. Competitive moves concentrate on multi-year analytical development partnerships and geographic expansion of captive biologics testing capacity.
Among integrated full-service providers, Thermo Fisher Scientific and Charles River Laboratories exemplify the capital-intensive archetype anchoring large-molecule comparability programs. WuXi AppTec occupies a position representing cost-advantaged bioanalytical scale extending from China into European sponsor workflows. These three entities sit within the preferred provider tier where pharmaceutical sponsors exchange volume commitments for priority scheduling and dedicated scientific teams.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Charles River Laboratories |
| WuXi AppTec |
| Eurofins Scientific |
| Labcorp |
| SGS |
| Merck KGaA |
| BioReliance (MilliporeSigma) |
| PACE Analytical |
| Others |
Value Chain & Pricing Dynamics
Multi-year preferred provider arrangements lock in supply access for pharmaceutical sponsors while anchoring price visibility across mass spectrometry and immunogenicity service tiers. These contracts exchange volume commitments for priority scheduling and dedicated scientific teams, compressing margin variability for full-service contract research organizations in the United States and Germany.
Pricing Analysis
Extended immunogenicity surveillance contracts drive lifetime value for biosimilar testing providers. Three-tier pricing structure across premium, standard, and economy levels separates integrated analytical-bioanalytical bundles from discrete stability protocols and commodity method development. Cost compression in standardized stability testing intensifies as automated systems proliferate, while mass spectrometry suites retain pricing power through platform scarcity. Emerging biotech firms exhibit highest price sensitivity, purchasing modular services on a study-by-study basis without volume leverage.
Supply Chain Analysis
The United States and Germany anchor high-value analytical service delivery for regulatory submission packages, while China and India feed cost-advantaged bioanalytical capacity into European sponsor workflows. Orbitrap and Q-TOF instrumentation, qualified analytical scientists, and reference product sourcing networks constitute critical input dependencies. Single-source vulnerability concentrates in specialized immunogenicity assay development expertise. Distribution runs through direct preferred provider relationships rather than spot-market procurement, with sponsor consolidation reducing vendor counts from eight to three relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biosimilar testing services represent an early-cycle expansion story as reference product patent cliffs accelerate pipeline submissions beyond oncology into immunology and ophthalmology. Regulatory stringency on interchangeability designations deepens outsourcing penetration among sponsors lacking captive analytical infrastructure.
For Market Incumbents: Fortify preferred provider status by embedding dedicated scientific teams within sponsor organizations and securing multi-year analytical development partnerships. Capacity addition in Germany and the United States addresses proximity demands from EMA and FDA submission programs. Certification investment in BIS and NMPA alignment opens jurisdiction-specific revenue streams as emerging markets localize biosimilar standards.
For New Entrants and Emerging Players: Anchor in ophthalmology biosimilar testing, where ranibizumab and aflibercept analogues create unmet demand for specialized ocular tissue penetration protocols. India and China biotech corridors offer the most penetrable geography, with domestic developers purchasing discrete modules rather than integrated bundles. A go-to-market angle targeting cost-advantaged stability testing for emerging biotech firms bypasses direct competition with full-service incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among immunogenicity boutiques with captive anti-drug antibody assay expertise and long-term Phase III surveillance contracts. The five-to-ten year viability window favors acquisition targets with Orbitrap platform deployment and EMA-preferred provider status. Watch FDA interchangeability designation volume as the inflection signal for premium pricing tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA alignment accelerates multi-jurisdiction submission capacity for sponsor consolidation. |
| Manufacturing Scale-Up | Captive biologics testing infrastructure reduces reference product sourcing bottlenecks. |
| Platform Integration | Mass spectrometry-bioanalytical bundles satisfy FDA interchangeability analytical thresholds. |
| Geographic Expansion | China-based capacity addresses NMPA pathway maturation and dual carbon compliance. |
| Acquisition of Specialist Firm | Immunogenicity boutiques capture premium pricing through anti-drug antibody assay lock-in. |
Study Parameters
Desk research of regulatory submission databases, FDA and EMA guidance documents, and clinical trial registries preceded structured interviews with biosimilar development executives, regulatory affairs leads, contract laboratory scientific directors, and pharmaceutical procurement managers. Bottom-up triangulation across service type demand curves and top-down validation against sponsor R&D spending patterns anchored volume estimates.
Variance decomposition across service type, end user, technology, and application segments structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation and sponsor pipeline velocity assumptions. Treatment line diversification and regional regulatory cluster maturity constituted industry-specific forecast inputs.
Material uncertainties — patent litigation delays, interchangeability standard divergence, and reference product supply disruption — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory pathway stability and sponsor outsourcing propensity. Recalibration cycles align with material shifts in FDA and EMA guidance issuance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Pegfilgrastim Biosimilar Market
Biosimilars
Herceptin Biosimilar Market
Biosimilars
US Biosimilars Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Interchangeable Biosimilars Market
Biosimilars
Biosimilar Monoclonal Antibody Comparability Test Platforms Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Dasatinib Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Global Biosimilars Market
Biosimilars
Global Sirolimus Market