
 US Biosimilars Market | 2026-2036
US Biosimilars Market Size, Share, and Industry Trends Forecast 2026-2036
US Biosimilars Market Analysis
Subscription-based patient support and data-monitoring services is expanding what manufacturers bundle with biosimilar products. Amgen Inc. leverages its established biologics infrastructure to sustain manufacturing reliability for complex molecules. Pfizer Inc. anchors its competitive stance through vertical control over active pharmaceutical ingredient supply. Samsung Bioepis competes aggressively on price while maintaining European regulatory credentials that ease FDA pathway navigation.
A biosimilar constitutes a biological product highly similar to an FDA-approved reference product with no clinically meaningful differences in safety, purity, or potency, manufactured through living cell lines in bioreactor systems with rigorous analytical comparability testing. Monoclonal antibodies command the deepest development pipelines due to the expiration of blockbuster reference biologics. Oncology applications generate the most advanced substitution activity as payers prioritize cost containment in infused therapy settings. The 351(k) regulatory pathway structures approval economics by permitting reliance on reference product safety and efficacy data.
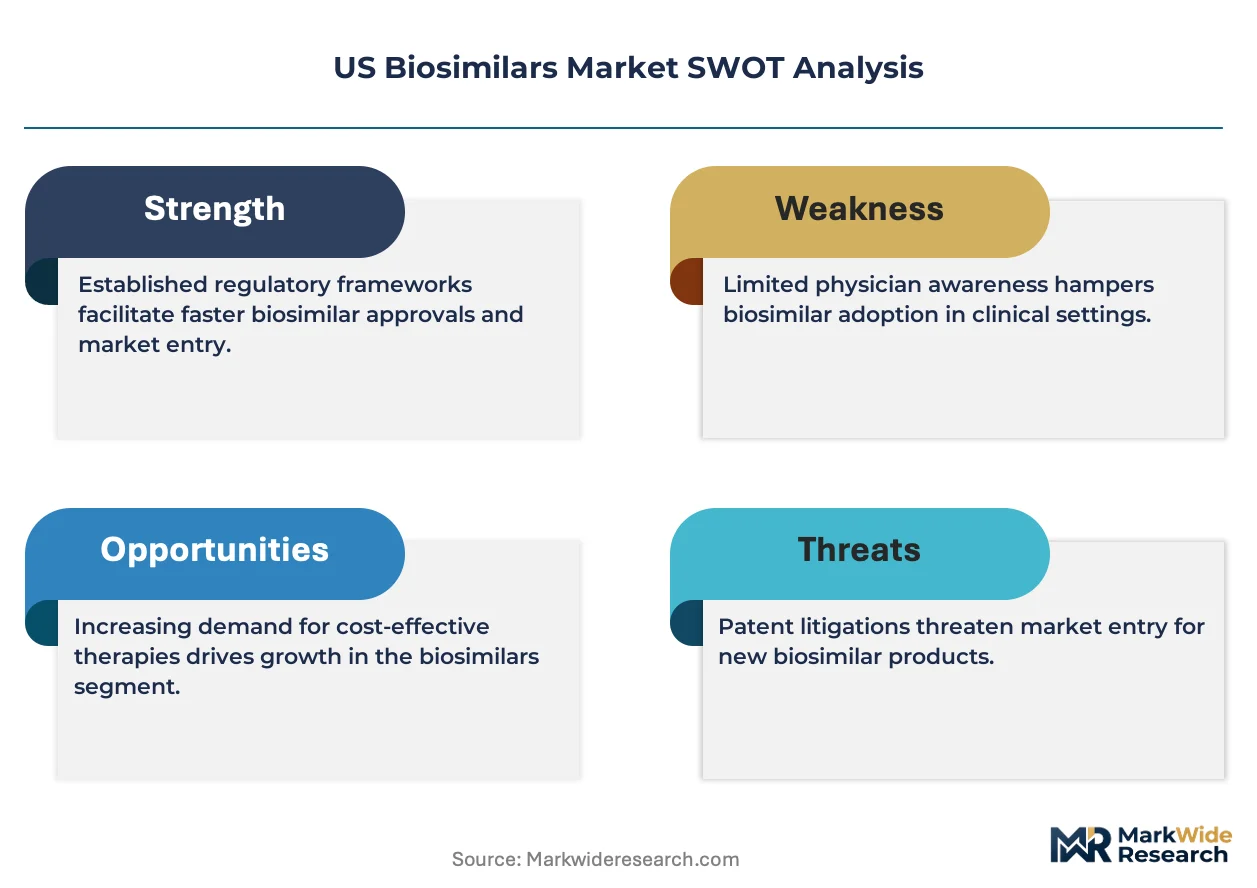
FDA interchangeability standards and CMS reimbursement parity rules shape prescriber behavior and pharmacy-level substitution authority across state Medicaid programs. State-level pharmacy board regulations create uneven automatic substitution frameworks that fragment market access. Stakeholders must monitor evolving FDA guidance on analytical similarity thresholds and state legislation governing pharmacist-level interchange.
Market Dynamics
CMS reimbursement parity rules and FDA interchangeability designations are compressing prescriber hesitation cycles, converting hospital formulary decisions into automatic substitution protocols across Medicare-served populations.
Growth Catalysts
- IRA Medicare price negotiation:The Inflation Reduction Act's biosimilar pricing provisions accelerate hospital procurement shifts toward lower-cost alternatives in oncology infusion centers.
- Reference biologic patent cliffs:Expiring exclusivity periods for blockbuster monoclonal antibodies open 351(k) pathway filings for complex molecule developers.
- State pharmacy substitution laws:Expanding automatic interchange authority permits pharmacist-level switching without prescriber consultation in Medicaid programs.
Market Restraints
- Bioreactor capacity concentration:Contract manufacturing organizations cluster in Massachusetts and North Carolina, creating geographic supply vulnerability for high-volume monoclonal antibody production.
- Analytical testing cost structure:Extensive immunogenicity and pharmacokinetic comparability studies require specialized reference laboratory networks that extend development timelines.
- Originator litigation strategies:Patent thickets surrounding manufacturing process patents generate inter partes review proceedings that delay FDA approval decisions.
Strategic Opportunities
- Opthalmology biosimilar white space:Ranibizumab and aflibercept reference products face limited follow-on competition, creating first-mover potential in retina therapy segments.
- 340B hospital program expansion:Eligible entities in rural and underserved areas gain enhanced margin capture from biosimilar substitution in oncology clinics.
- Real-world evidence integration:FDA's draft guidance on analytical similarity threshold refinement permits post-approval efficacy data to support interchangeability petitions.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization requires specialized bioprocess engineers that command premium compensation in Boston and San Francisco labor markets.
- State-by-state substitution heterogeneity:Fragmented pharmacy board regulations force manufacturers to maintain multiple label configurations and distribution protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Biosimilars Market |
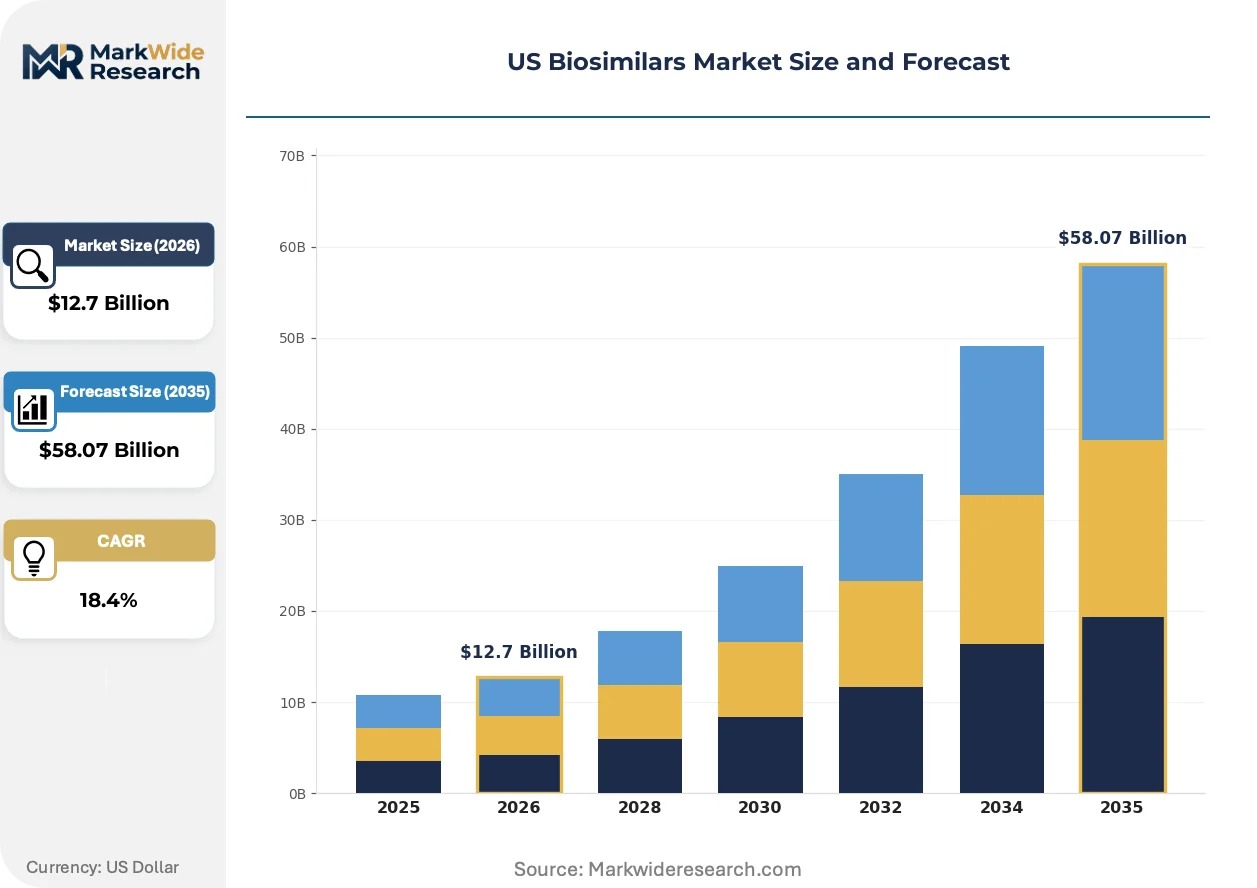
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $58.07 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Insulin, Erythropoietin, Growth Hormones End User: Hospitals, Specialty Clinics, Retail Pharmacies, Online Pharmacies Application: Oncology, Autoimmune Disorders, Infectious Diseases, Diabetes Management Regulatory Pathway: BLA, 351(k), 351(a), Original Abbreviated |
| Companies Covered | Amgen Inc., Pfizer Inc., Sandoz, Novartis AG, Celltrion Inc., Viatris Inc., Samsung Bioepis, Coherus BioSciences, Samsung Biologics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Biosimilars Market Emerging Trajectories
Continuous manufacturing platforms and single-use bioreactor systems are displacing stainless-steel batch processes, reducing cross-contamination risk while accelerating product changeover in multi-product facilities.
Single-use bioreactor technology is absorbing capital investment from traditional stainless-steel infrastructure as contract manufacturers seek production flexibility. CDMOs serving the US market are retrofitting legacy facilities in Research Triangle Park and Puget Sound corridors. This shift is absorbing fixed-cost depreciation schedules while enabling rapid product switches between monoclonal antibody programs.
FDA's evolving interchangeability guidance creates regulatory clarity for switching studies design. The agency's 2024 draft recommendations on pharmacokinetic bridging data reduce uncertainty for 351(k) applicants pursuing automatic substitution status. Oncology infusion centers in Medicare Advantage networks are restructuring formularies to exploit this clarity.
Hospital purchasing cooperatives are consolidating biosimilar procurement decisions through group purchasing organizations. Premier and Vizient contracts now specify biosimilar minimum volume commitments that displace individual hospital negotiations. This concentration is most visible in California and Texas health systems managing mixed-payer oncology populations.
US Biosimilars Market Segmentation
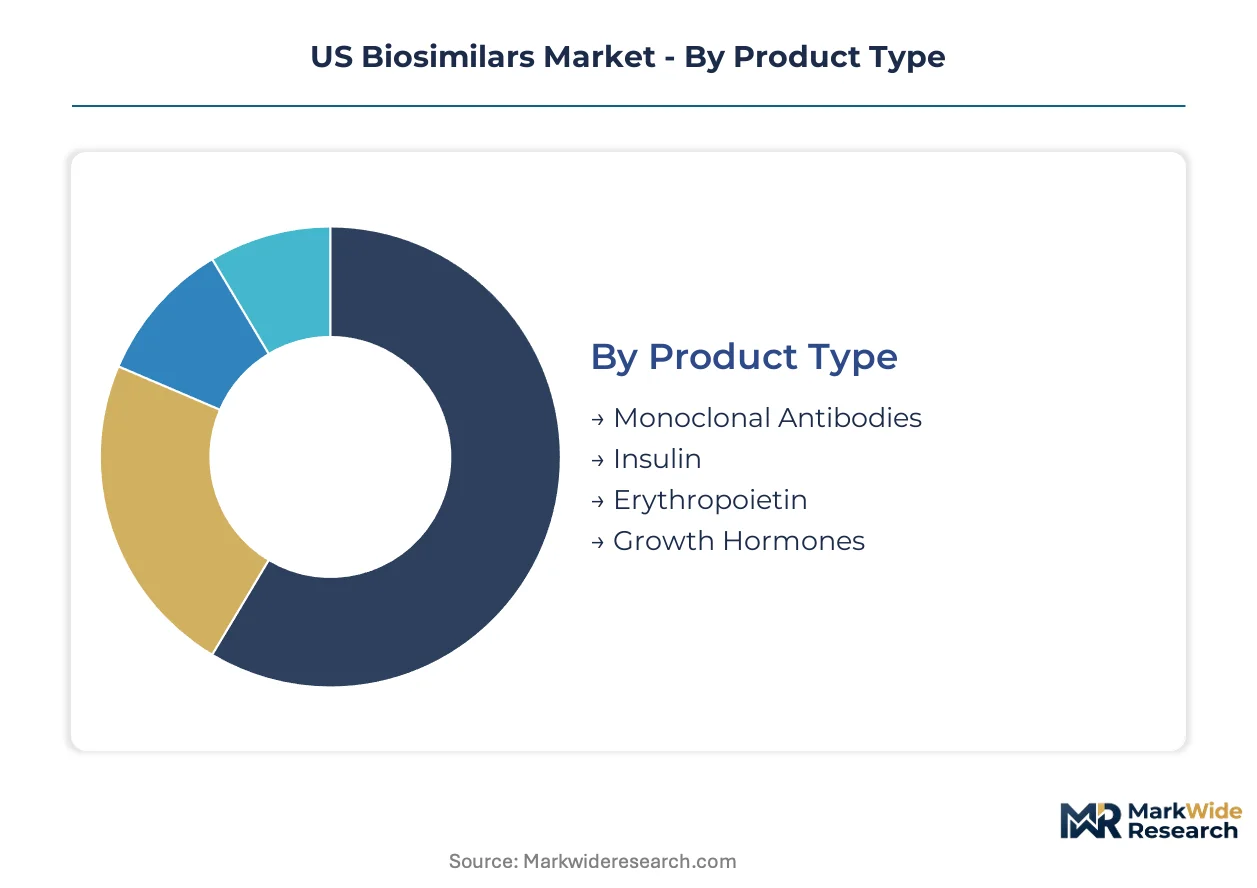
Segmentation in the US biosimilars market determines which products qualify for automatic substitution and which require prescriber consultation. FDA pathway designations and state pharmacy board rules create distinct commercial zones that manufacturers must navigate separately.
Product Type:
Certification burden varies sharply across molecule classes, with monoclonal antibodies requiring the most extensive immunogenicity testing while insulin products face additional USP monograph compliance.
- Monoclonal Antibodies:Complex glycosylated proteins targeting specific antigens in oncology and autoimmune applications. Demand concentrates in Medicare Advantage infusion centers across Florida and Texas as payers mandate pre-authorization switches for rituximab and trastuzumab alternatives. Analytical similarity thresholds for Fc receptor binding extend FDA review timelines.
- Insulin:Peptide hormones manufactured through recombinant DNA technology in microbial expression systems. Concentrated demand from 340B-eligible entities in rural Mississippi and Alabama seeking margin capture on long-acting analogs. USP General Chapter <905> uniformity testing adds compounding pharmacy compliance layers.
- Erythropoietin:Glycoprotein stimulating red blood cell production in dialysis populations. CMS bundled payment rules for end-stage renal disease create procurement concentration in DaVita and Fresenius clinic networks.
- Growth Hormones:Polypeptide therapies for pediatric endocrinology and adult deficiency. Medicaid formulary restrictions in California and New York limit automatic substitution despite FDA approval.
Leading the category by volume: Monoclonal Antibodies. Growing fastest: Insulin.
End User:
Procurement authority determines substitution speed, with institutions possessing pharmacy and therapeutics committees moving faster than retail channels requiring individual prescriber consent.
- Hospitals:Integrated delivery networks with centralized formularies and oncology pharmacy directors. Premier and Vizient GPO contracts in California and Texas systems now mandate biosimilar minimum volume commitments.
- Specialty Clinics:Rheumatology and gastroenterology practices with in-office infusion capabilities. Concentrated in Medicare-served populations across Arizona and Nevada where prior authorization automation accelerates switching.
- Retail Pharmacies:Chain and independent dispensers handling self-administered products. State-level substitution laws in Florida and Ohio permit pharmacist-level interchange without prescriber consultation for designated interchangeable products.
- Online Pharmacies:Mail-order and specialty pharmacy platforms serving chronic disease management. 340B contract pharmacy arrangements in rural expansion areas create margin capture opportunities.
Highest procurement authority: Hospitals. Fastest channel expansion: Specialty Clinics.
Application:
Clinical setting determines reimbursement mechanics, with infused therapies in hospital outpatient departments operating under separate CMS payment methodologies than self-injected products in pharmacy benefit management.
- Oncology:Supportive care and cytotoxic biosimilars in infusion center settings. IRA Medicare price negotiation provisions accelerate hospital procurement shifts toward lower-cost alternatives in community oncology practices across Pennsylvania and Ohio.
- Autoimmune Disorders:Rheumatoid arthritis, psoriasis, and inflammatory bowel disease therapies. Step therapy protocols in Medicare Advantage plans in Michigan and Illinois mandate biosimilar trial before reference product authorization.
- Infectious Diseases:Limited pipeline concentrated in hepatitis and HIV supportive care. Medicaid managed care restrictions in Georgia and North Carolina slow formulary adoption.
- Diabetes Management:Insulin and GLP-1 biosimilar development. CMS insulin cost-sharing caps create direct-to-consumer price sensitivity in Medicare Part D plans.
Deepest formulary penetration: Oncology. Steepest expansion trajectory: Autoimmune Disorders.
Regulatory Pathway:
Submission type dictates evidentiary requirements and approval economics, with abbreviated pathways leveraging reference product data to compress development costs and timelines.
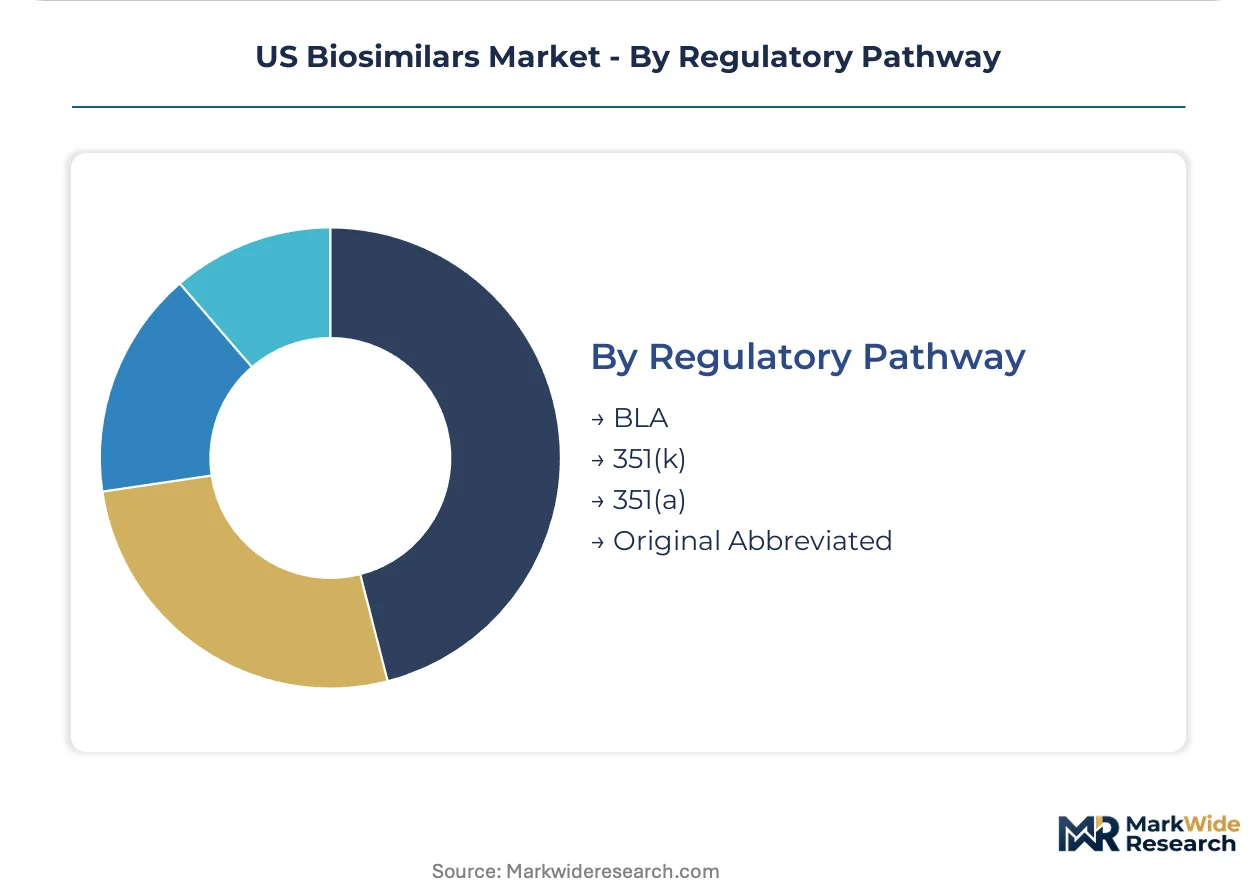
- 351(k):Abbreviated biosimilar pathway permitting reliance on reference product safety and efficacy data. FDA interchangeability designations enable automatic substitution at pharmacy level without prescriber consultation.
- BLA:Full biologics license application for novel biologics or when reference product data is unavailable. Required for first-in-class molecules or when analytical similarity cannot be established.
- 351(a):Original biologics pathway for pioneer products. Originators extend exclusivity through manufacturing process patents and inter partes review proceedings.
- Original Abbreviated:Legacy pathway for certain protein products grandfathered under specific statutory provisions. Limited applicability in current development environment.
Dominant submission route: 351(k). Gaining regulatory clarity: Interchangeability standards under FDA draft guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US biosimilar production concentrates in contract manufacturing clusters while consumption spreads across Medicare-served populations in diverse state markets. Hospital procurement decisions in high-volume states drive national pricing benchmarks.
California
Integrated delivery networks in Los Angeles and San Francisco Bay Area operate under Medi-Cal managed care expansion, accelerating biosimilar formulary adoption in oncology infusion centers. Kaiser Permanente's centralized pharmacy and therapeutics committees mandate pre-authorization switches for rituximab and trastuzumab alternatives. The state's 340B program expansion in rural Central Valley counties creates margin capture opportunities for eligible entities.
Texas
Medicare Advantage penetration in Houston and Dallas-Fort Worth metroplexes generates concentrated demand for autoimmune disorder therapies with step therapy protocols. The Texas State Board of Pharmacy permits automatic substitution for FDA-designated interchangeable products without prescriber consultation. MD Anderson Cancer Center's procurement decisions influence pricing benchmarks across Southwest hospital systems.
Florida
Retiree population density in Miami-Dade and Broward counties drives oncology biosimilar volume in hospital outpatient departments. Florida's pharmacy substitution laws enable pharmacist-level interchange for self-administered products in retail channels. Tampa Bay health systems participate in Premier GPO contracts specifying biosimilar minimum volume commitments.
Pennsylvania
Community oncology practices in Philadelphia and Pittsburgh corridors respond to IRA Medicare price negotiation provisions with accelerated procurement shifts. The state's Medicaid managed care organizations mandate biosimilar trial before reference product authorization for erythropoietin therapies. University of Pennsylvania Health System's formulary decisions anchor purchasing patterns across Mid-Atlantic networks.
Ohio
Cleveland Clinic and Ohio State University Wexner Medical Center anchor hospital procurement concentration in the Midwest. The state's pharmacy board regulations require prescriber notification for automatic substitution, creating documentation requirements that slow retail channel adoption. Cincinnati-based specialty clinics manage mixed-payer rheumatology populations with prior authorization automation.
US Biosimilars Market Vendor Landscape
Top-tier vendors anchor the reference biologic originator segment, while mid-tier developers exploit 351(k) pathway economics through contract manufacturing partnerships. Market structure reflects tiered specialization across molecule complexity classes, with monoclonal antibody developers commanding premium analytical testing investments. Two strategic archetypes dominate: vertically integrated biologics manufacturers leveraging existing infrastructure, and pure-play biosimilar specialists competing on price with European regulatory credentials. Dominant competitive moves include capacity expansion in single-use bioreactor facilities and strategic partnerships with hospital purchasing cooperatives.
Within the integrated manufacturer tier, Amgen Inc. and Pfizer Inc. occupy positions that exemplify backward control over active pharmaceutical ingredient supply and manufacturing reliability for complex molecules. Samsung Bioepis sits within the specialist tier, representing aggressive price competition maintained through European regulatory credentials that ease FDA pathway navigation. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning in the US biosimilar landscape.
| Leading Market Players |
|---|
| Amgen Inc. |
| Pfizer Inc. |
| Sandoz |
| Novartis AG |
| Celltrion Inc. |
| Viatris Inc. |
| Samsung Bioepis |
| Coherus BioSciences |
| Samsung Biologics Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Interchangeability certification divergence between FDA-designated and non-designated biosimilars manifests in hospital formulary premiums for automatic substitution authority while bioreactor capacity clustering in Massachusetts and North Carolina shapes regional supply availability. CMS reimbursement parity rules compress price spreads between tiers, yet 340B-eligible entities capture enhanced margins through procurement concentration.
Pricing Analysis
Margin tightening in non-interchangeable monoclonal antibody tiers reflects originator litigation delays and extended FDA review timelines for complex glycosylated proteins. Three-tier pricing structure across premium interchangeable, standard biosimilar, and economy 340B contract levels dominates hospital procurement. Pricing pressure intensifies in insulin segments as CMS cost-sharing caps cascade into direct-to-consumer channels. Medicare Advantage plans exhibit highest price sensitivity; integrated delivery networks with captive pharmacy operations demonstrate lowest sensitivity due to formulary control.
Supply Chain Analysis
FDA current Good Manufacturing Practice qualification gates concentrate mammalian cell line production in Massachusetts, North Carolina, and Puerto Rico contract manufacturing clusters. Active pharmaceutical ingredient supply draws from Swiss and Irish fermentation facilities, while single-use bioreactor systems source from German and US specialty equipment vendors. Single-source vulnerability pervades high-complexity monoclonal antibody capacity. Distribution runs through Premier and Vizient group purchasing organization contracts into hospital central pharmacy repositories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing platform adoption is displacing stainless-steel batch processes, creating capital reallocation imperatives across incumbent and entrant manufacturer archetypes.
For Market Incumbents: Anchor formulary position through backward integration into single-use bioreactor capacity expansion in Research Triangle Park corridors. Defend against Samsung Bioepis price aggression by securing interchangeable designations for rituxumab and trastuzumab portfolios before reference product patent cliffs accelerate. Prioritize 340B contract pharmacy network density to capture margin in rural expansion areas. For New Entrants and Emerging Players: The price-point gap between premium interchangeable ophthalmology biosimilars and economy supportive care molecules creates entry viability for ranibizumab and aflibercept developers. Target retina therapy segments with limited follow-on competition and accelerated FDA review timelines under draft interchangeability guidance. Pursue hospital purchasing cooperative partnerships over retail pharmacy distribution to bypass state-by-state substitution heterogeneity. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap developers with European regulatory credentials and 351(k) approval track records. Five-to-ten year viability hinges on bioreactor capacity access rather than molecule pipeline depth. Monitor FDA draft guidance finalization on analytical similarity thresholds as inflection indicator for interchangeability petition success rates.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Single-use bioreactor deployment in Puget Sound corridors absorbs fixed-cost depreciation while enabling rapid product switches. |
| Regulatory Approval Pathway | FDA interchangeability designation under 351(k) pathway unlocks automatic substitution authority in Medicaid programs. |
| Hospital System Partnership | Premier and Vizient GPO contracts with minimum volume commitments displace individual hospital negotiations in California and Texas. |
| Pipeline Diversification | Ophthalmology biosimilar development addresses ranibizumab and aflibercept white space with limited incumbent competition. |
| Backward Integration | In-house active pharmaceutical ingredient production insulates against Swiss and Irish fermentation facility concentration risk. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with formulary directors, regulatory affairs leads, hospital procurement managers, and payer access specialists provided qualitative calibration. FDA 351(k) submission databases, CMS Medicare reimbursement files, ClinicalTrials.gov records, and group purchasing organization contract disclosures supplied quantitative foundations. Bottom-up patient population modeling and top-down expenditure flow analysis triangulated market size estimates.
Granularity-level modeling operated at molecule class, regulatory pathway designation, end-user channel, and state Medicaid program cluster dimensions across the analysis window. CAGRs derived from patient volume projections, price trajectory assumptions, and substitution elasticity parameters. Immunogenicity testing cost curves and bioreactor capacity utilization rates informed supply-side constraints throughout the forecast period.
Inputs from FDA guidance documents and state pharmacy board regulations were available through the study window; gaps in real-world switching study data introduce uncertainty bands around interchangeability adoption curves. Forecasts reflect documented assumptions regarding IRA Medicare price negotiation implementation pace and originator litigation settlement patterns. A model refresh is warranted upon material change in FDA analytical similarity threshold finalization or CMS reimbursement parity rule modification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Dasatinib Market
Biosimilars
Global Biosimilars Market
Biosimilars
Imatinib Drug Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Global Biosimilar Monoclonal Antibodies (Mabs) Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Europe Biosimilars Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Etanercept Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Immunology Biosimilars Market
Biosimilars
Remicade Biosimilar Market