
 Biotech API Manufacturing Services Market | 2026-2036
Biotech API Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Biotech API Manufacturing Services Market Outlook
Single-source reliance on captive biologics manufacturing is shifting toward multi-source outsourced partnerships across the biopharmaceutical value chain. Lonza Group Ltd. leverages its Swiss and US-based mammalian cell culture infrastructure to anchor high-complexity monoclonal antibody supply for global innovators. WuXi AppTec Co., Ltd. competes through integrated discovery-to-commercialization platforms spanning China and North America. Catalent, Inc. specializes in fill-finish and viral vector manufacturing, extending service breadth beyond traditional API production.
Biotech API manufacturing services encompass contract production of active pharmaceutical ingredients derived from living organisms, requiring mammalian or microbial cell culture systems operating under controlled temperature, pH, and dissolved oxygen parameters to ensure glycosylation patterns and protein folding critical for therapeutic efficacy. Monoclonal antibodies occupy the dominant product-type position due to their established oncology and autoimmune applications, while recombinant proteins represent the fastest-expanding category as novel biologic modalities gain clinical traction. Chromatography and filtration technologies command disproportionate capital allocation because downstream purification determines yield, impurity profiles, and regulatory compliance for commercial release.
FDA's Current Good Manufacturing Practice enforcement and EMA's MDR-aligned quality system requirements compel contract manufacturers to maintain redundant quality units, validated cleanroom suites, and extensive batch documentation. China's NMPA has tightened biologics manufacturing licensing through revised GMP Annexes, raising barriers for new market entrants while favoring established players with prior inspection history. Stakeholders must weigh geographic regulatory divergence against single-site efficiency when siting new capacity or qualifying secondary suppliers.
Market Dynamics
The FDA's Quality by Design framework compels contract manufacturers to front-load process validation, reshaping capital allocation toward continuous manufacturing platforms and real-time release testing capabilities.
Growth Catalysts
- Oncology Pipeline Expansion:The surge of bispecific antibodies and antibody-drug conjugates in clinical development drives demand for mammalian cell culture capacity with specialized glycoengineering capabilities.
- EMA's MDR Alignment:Stricter quality system requirements for biosimilar comparability studies push originator and generic sponsors toward audited contract manufacturing partners with established regulatory track records.
- Continuous Processing Technology:Perfusion bioreactor adoption reduces facility footprint and cost-per-gram for high-volume monoclonal antibodies, accelerating platform standardization across the industry.
Market Restraints
- Single-Use Component Volatility:Supply concentration for bioprocess bags and tubing in limited polymer resin grades creates input cost instability and qualification delays.
- Swiss and US Corridor Saturation:Premium manufacturing capacity clusters in Basel and Boston face 18-24 month lead times for new project onboarding, constraining sponsor flexibility.
- Chromatography Resin Lead Times:Protein A and mixed-mode resin supply bottlenecks extend downstream process development timelines and campaign start dates.
Strategic Opportunities
- China's NMPA Streamlined Pathways:Revised biologics licensing procedures for innovative therapies attract foreign sponsor investment in domestic contract manufacturing partnerships.
- Cell and Gene Therapy Convergence:Viral vector production expertise developed for gene therapies transfers to mRNA vaccine manufacturing, opening cross-platform service expansion.
- Digital Twin Implementation:Process simulation software integration with physical manufacturing trains enables remote tech transfer and reduces on-site validation requirements.
Industry Challenges
- Process Analytical Technology Talent Scarcity:Shortages of engineers trained in multivariate data analysis and chemometric modeling delay continuous manufacturing deployments.
- Dual-Site Qualification Burden:FDA and EMA requirements for redundant manufacturing sources force sponsors to validate secondary suppliers, doubling documentation and audit costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotech API Manufacturing Services Market |
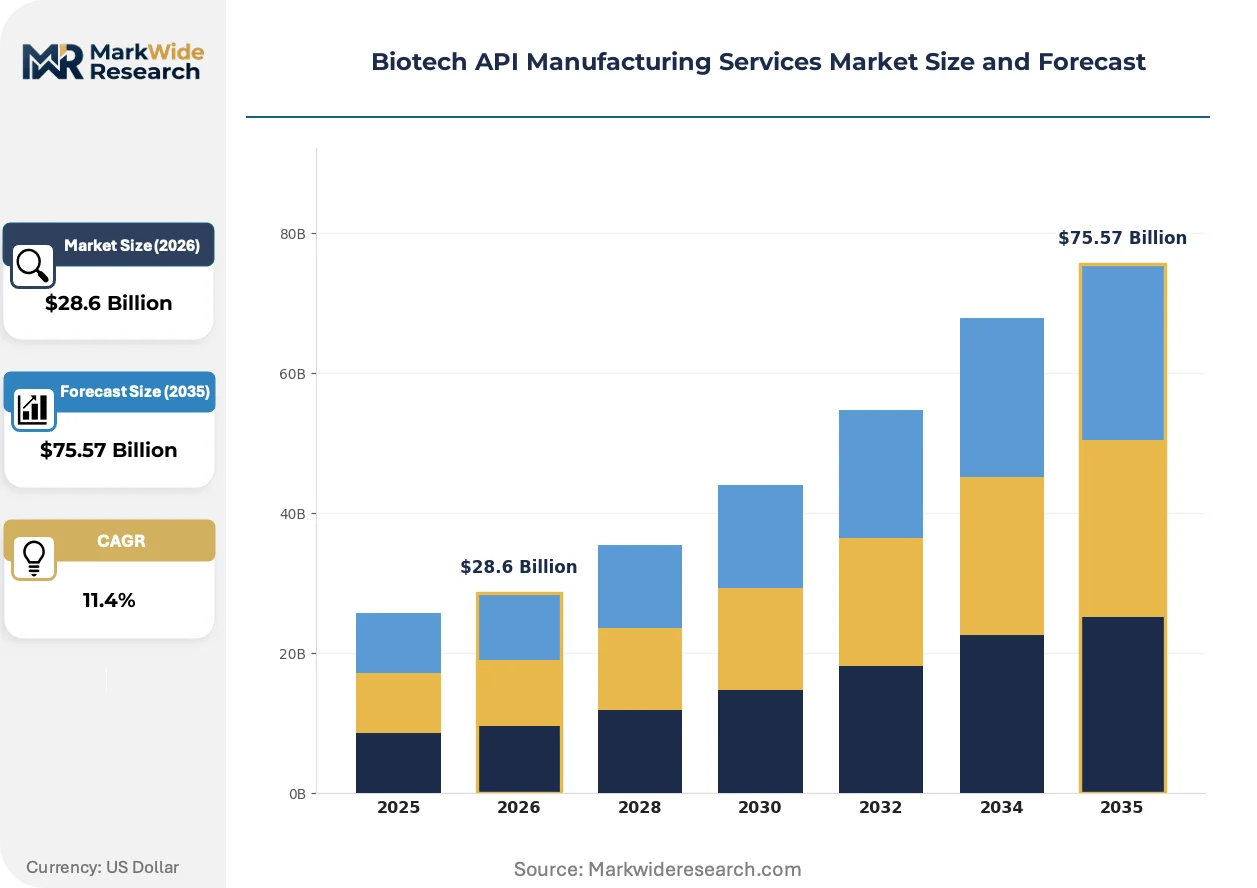
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Antigens, Recombinant Proteins Technology: Fermentation, Cell Culture, Filtration, Chromatography Application: Oncology, Infectious Diseases, Autoimmune Disorders, Cardiovascular Diseases Client Type: Pharmaceutical Companies, Biotech Firms, Research Organizations, Academic Institutions |
| Companies Covered | Lonza Group Ltd., WuXi AppTec Co., Ltd., Boehringer Ingelheim Biopharmaceuticals GmbH, CordenPharma International, Sterling Pharma Solutions, AbbVie, Inc., Hikal Ltd., FUJIFILM Diosynth Biotechnologies, Catalent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotech API Manufacturing Services Market Strategic Shifts
Biotech API manufacturing is pivoting from batch-oriented legacy platforms toward integrated continuous processing, with digital infrastructure and regulatory science advancing in parallel to enable real-time quality assurance.
Single-use bioreactor technology is consolidating upstream production economics across mammalian cell culture operations. Mid-cap biopharmaceutical developers now specify disposable systems for Phase III campaigns, bypassing stainless steel validation timelines. This shift is consolidating vendor relationships around integrated equipment-and-consumables suppliers capable of global service networks.
EMA's evolving biosimilar immunogenicity guidelines now require extended characterization of post-translational modifications for interchangeability designation. Contract manufacturers must invest in mass spectrometry and glycan mapping capabilities to support sponsor submissions. High-complexity biosimilar programs targeting the European market face 12-18 month analytical development extensions to meet these standards.
Biopharmaceutical procurement teams now mandate outcome-based manufacturing agreements with penalty clauses for yield shortfalls and timeline overruns. Large-cap sponsors unbundle fill-finish from drug substance contracts to optimize logistics and release timing. This restructuring concentrates most visibly in the United States, where integrated delivery networks negotiate direct-to-site distribution from contract manufacturing organizations.
Biotech API Manufacturing Services Market Segmentation
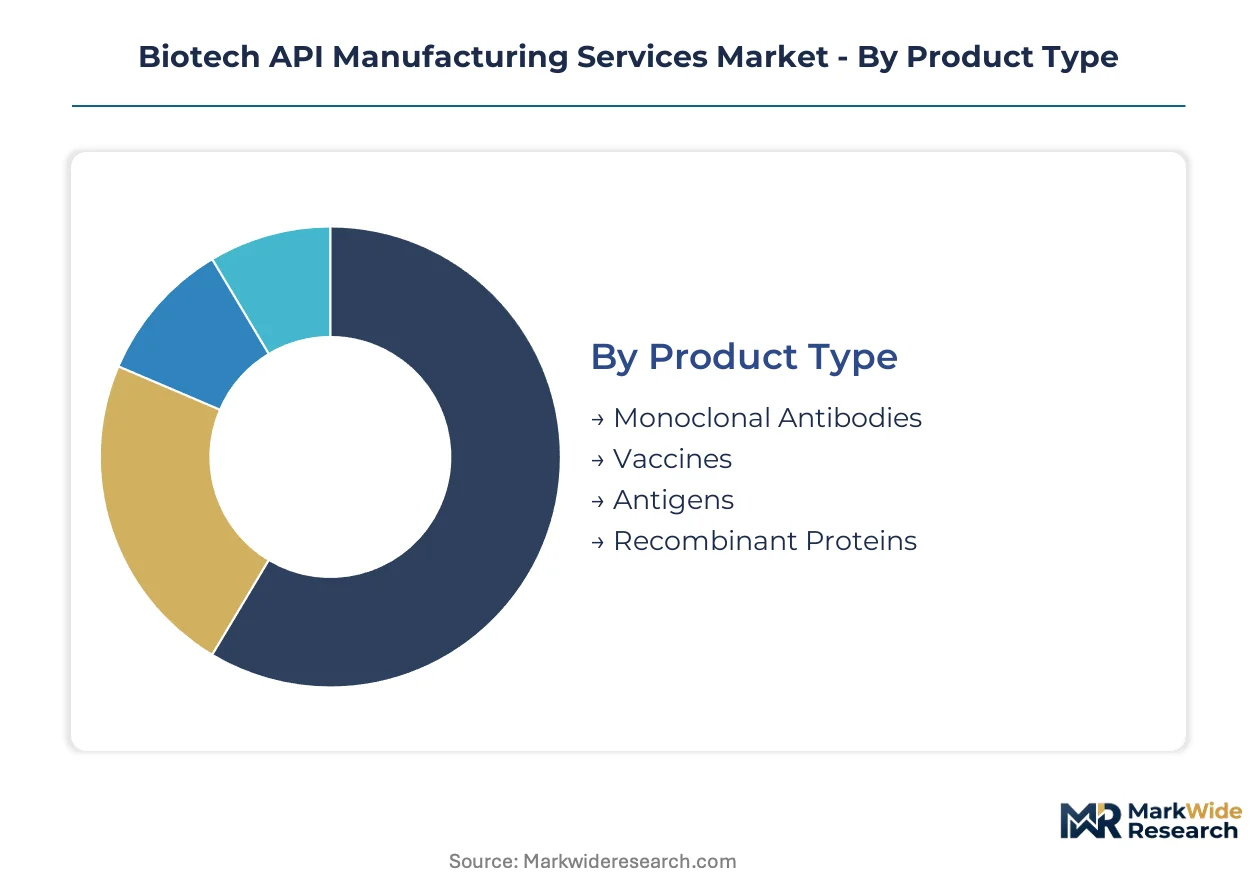
Biotech API manufacturing services fragment across four dimensions that determine facility design, regulatory pathways, and contract economics. Each segmentation axis carries distinct capital requirements, margin profiles, and client relationship dynamics that shape competitive positioning.
Product Type:
Mammalian cell culture infrastructure demands the steepest upfront investment, with stainless steel bioreactor trains and downstream purification suites requiring validated cleanroom environments.
- Monoclonal Antibodies:These glycoproteins require mammalian expression systems to achieve proper folding and glycosylation patterns essential for therapeutic efficacy. Demand concentrates in the United States and Switzerland, where FDA and Swissmedic inspection histories anchor sponsor confidence for oncology and autoimmune indications.
- Vaccines:Viral and subunit vaccines span microbial fermentation to embryonated egg production, with adjuvant formulation adding complexity. Egg-based influenza manufacturing in the United States maintains entrenched capacity, while recombinant platforms in China scale through NMPA-aligned facilities.
- Antigens:Purified protein immunogens for diagnostic and therapeutic vaccines deploy bacterial or yeast expression systems with lower capital barriers than mammalian platforms.
- Recombinant Proteins:Enzymes, cytokines, and growth factors represent the fastest-climbing category, with novel biologic modalities in metabolic and rare disease pipelines driving microbial and cell culture capacity expansion.
Most installed capacity flows through Monoclonal Antibodies. Expansion is steepest in Recombinant Proteins.
Technology:
Downstream purification technologies command disproportionate capital allocation relative to their physical footprint, with resin and membrane costs driving per-batch economics.
- Fermentation:Microbial systems using E. coli or yeast achieve higher cell densities and faster doubling times than mammalian alternatives, with stainless steel tanks dominating high-volume antibiotic and insulin precursor production.
- Cell Culture:Mammalian platforms anchor complex glycoprotein manufacturing, with perfusion bioreactor adoption reducing facility footprint and media consumption for United States-based monoclonal antibody campaigns.
- Filtration:Tangential flow and depth filtration operations determine viral clearance validation and endotoxin removal, with single-use membrane technologies shortening campaign changeover timelines.
- Chromatography:Protein A affinity and mixed-mode resin systems represent the highest-margin technology tier, with resin lead times and column packing expertise constraining available manufacturing slots across Switzerland and United States corridors.
Cell Culture anchors the majority of revenue-generating campaigns. Chromatography claims the steepest margin expansion trajectory.
Application:
Oncology applications concentrate manufacturing demand in high-complexity modalities, with checkpoint inhibitors and antibody-drug conjugates requiring specialized conjugation and handling capabilities.
- Oncology:Bispecific antibodies and CAR-T cell support materials drive demand for flexible multi-product facilities with potent compound containment infrastructure, particularly in Massachusetts and California biotech clusters.
- Infectious Diseases:Pandemic preparedness funding and seasonal influenza manufacturing sustain dedicated capacity, with mRNA platform investments creating cross-application viral vector expertise.
- Autoimmune Disorders:Established tumor necrosis factor and interleukin inhibitor franchises maintain steady fill-finish demand, with biosimilar competition pressuring cost-per-gram targets.
- Cardiovascular Diseases:Recombinant enzymes and anticoagulants occupy mature manufacturing platforms with standardized process parameters and well-characterized impurity profiles.
Oncology commands the largest share of active project pipelines. Infectious Diseases shows the most volatile capacity utilization patterns.
Client Type:
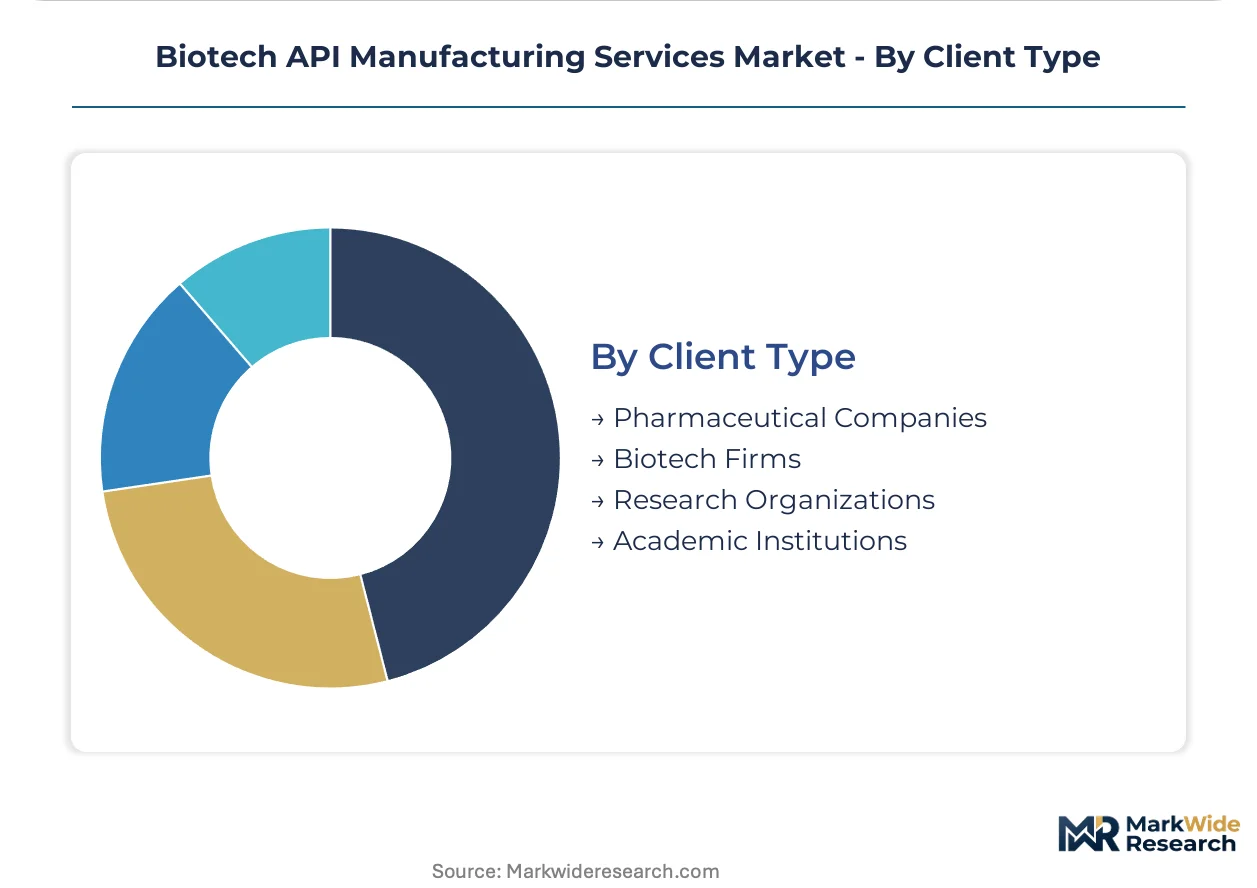
Pharmaceutical companies bring scale and multi-year commitments, while biotech firms demand flexibility and accelerated timelines that reshape facility scheduling economics.
- Pharmaceutical Companies:Large-cap sponsors unbundle drug substance and fill-finish contracts to optimize logistics, with direct-to-site distribution requirements reshaping United States contract manufacturing organization relationships.
- Biotech Firms:Venture-backed developers prioritize speed-to-IND and speed-to-Phase-I, with single-use technology adoption enabling rapid campaign initiation without stainless steel validation burdens.
- Research Organizations:Non-profit and government entities fund early-stage process development, with technology transfer requirements to commercial partners creating downstream revenue pipelines.
- Academic Institutions:University-affiliated manufacturing facilities support investigator-initiated trials and rare disease programs with limited commercial volumes but high scientific complexity.
Pharmaceutical Companies anchor long-term capacity commitments. Biotech Firms generate the highest project velocity and platform switching rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor anchors mammalian cell culture capacity expansion, drawing venture capital and pharmaceutical sponsor investment into Massachusetts-based contract manufacturing infrastructure. FDA inspection histories and proximity to clinical trial networks reinforce sponsor preference for United States-based production of oncology biologics.
United States
Checkpoint inhibitor and antibody-drug conjugate pipelines drive demand for multi-product facilities with potent compound containment. FDA's Quality by Design framework mandates front-loaded process validation, extending facility qualification timelines. The Greater Boston cluster concentrates perfusion bioreactor investments from established contract manufacturers seeking to reduce cost-per-gram for high-volume monoclonal antibodies.
Switzerland
Specialized glycoengineering capabilities for bispecific antibodies attract European sponsor programs requiring Swissmedic-aligned quality systems. EMA's evolving biosimilar immunogenicity guidelines extend analytical development timelines for interchangeability designation. The Basel corridor faces 18-24 month project onboarding lead times as capacity saturation constrains sponsor flexibility for new campaign initiation.
China
NMPA's streamlined biologics licensing pathways for innovative therapies draw foreign sponsor investment into domestic contract manufacturing partnerships. Revised GMP Annexes raise barriers for new entrants while favoring established players with prior inspection history. The Yangtze River Delta scales recombinant protein capacity as metabolic and rare disease pipelines accelerate microbial and cell culture expansion.
Germany
EMA-aligned quality system requirements for biosimilar comparability studies push originator and generic sponsors toward audited contract partners. Continuous processing technology adoption reduces facility footprint for high-volume campaigns. The Munich-Frankfurt corridor concentrates viral vector production expertise transferable to mRNA vaccine manufacturing platforms.
India
CDSCO's tightened biologics manufacturing licensing through revised GMP standards elevates quality expectations for export-oriented capacity. Cost-competitive microbial fermentation infrastructure supports insulin precursor and enzyme production for global pharmaceutical sponsors. The Hyderabad-Bangalore corridor attracts technology transfer partnerships from Western sponsors seeking secondary supply qualification.
Biotech API Manufacturing Services Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cell and gene therapy specialization and digital twin implementation. The vendor base stratifies across three maturity tiers: integrated discovery-to-commercialization platforms, mammalian cell culture specialists, and fill-finish service providers. Swiss and United States-based incumbents anchor high-complexity monoclonal antibody supply through validated cleanroom infrastructure. Competitive dynamics concentrate on capacity expansion in China, strategic partnerships for viral vector expertise, and technology licensing for continuous processing platforms.
Within the integrated platform tier, Lonza Group Ltd. and WuXi AppTec Co., Ltd. exemplify divergent geographic strategies for sponsor proximity. Lonza's Swiss and United States-based infrastructure anchors European and North American pharmaceutical relationships through established regulatory track records. WuXi AppTec's China-North American dual presence competes through speed-to-IND acceleration for venture-backed developers. Catalent, Inc. occupies a distinct position in fill-finish and viral vector manufacturing, extending service breadth beyond traditional drug substance production into integrated delivery network distribution.
| Leading Market Players |
|---|
| Lonza Group Ltd. |
| WuXi AppTec Co., Ltd. |
| Boehringer Ingelheim Biopharmaceuticals GmbH |
| CordenPharma International |
| Sterling Pharma Solutions |
| AbbVie, Inc. |
| Hikal Ltd. |
| FUJIFILM Diosynth Biotechnologies |
| Catalent, Inc. |
| Others |
Value Chain & Pricing Dynamics
Protein A resin pricing indices cascade through biotech API manufacturing tiers, with chromatography consumable costs compressing margins for standard-tier contract manufacturers while premium Swiss and United States facilities pass through qualified resin premiums to oncology sponsors demanding validated supply chains.
Pricing Analysis
Input-cost pass-through dominates contract economics, with single-use bioreactor bag and tubing resin grades driving per-campaign cost variability. Pricing stratifies across FDA-inspected premium tiers, EMA-aligned standard tiers, and emerging-economy economy tiers based on regulatory audit history and geographic proximity to sponsor R&D hubs. Pricing pressure stems from sponsor unbundling of drug substance and fill-finish contracts, forcing drug substance manufacturers to absorb logistics coordination costs. Biotech firms exhibit highest price sensitivity, prioritizing speed-to-IND over per-gram economics, while pharmaceutical companies accept premium pricing for redundant quality units and established inspection histories.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA compel sponsors to qualify secondary suppliers, fragmenting procurement across Switzerland, the United States, and China for mammalian cell culture capacity. Raw material dependencies center on protein A and mixed-mode chromatography resins, single-use polymer films, and chemically defined cell culture media. Single-source vulnerability for specialized resin grades creates campaign start delays when primary suppliers face allocation constraints. Distribution runs through direct-to-site models from contract manufacturing organizations to integrated delivery networks, bypassing traditional wholesale channels for temperature-controlled biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biotech API manufacturing services market compounds steadily as oncology pipeline expansion sustains capacity absorption across mammalian cell culture infrastructure, with bispecific antibodies and antibody-drug conjugates driving multi-year offtake commitments.
For Market Incumbents: Anticipate sponsor pressure for continuous processing technology adoption by securing perfusion bioreactor platforms and process analytical technology talent pools ahead of competitor qualification. Defensive consolidation into viral vector manufacturing expertise captures cell and gene therapy convergence demand, while backward integration into chromatography resin supply buffers margin compression from consumable cost volatility. For New Entrants and Emerging Players: Capture NMPA-aligned manufacturing partnerships in China's Yangtze River Delta, where streamlined biologics licensing for innovative therapies attracts foreign sponsor investment without incumbent inspection history requirements. White-space availability concentrates in microbial fermentation capacity for recombinant proteins, with metabolic and rare disease pipelines outpacing installed supply. Go-to-market positioning through integrated discovery-to-commercialization platforms accelerates venture-backed developer capture. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale mammalian cell culture specialists possessing Swissmedic or FDA inspection histories but sub-scale geographic footprints, as sponsor dual-sourcing mandates inflate acquisition premiums for qualified secondary supply. Long-term viability hinges on continuous processing technology deployment and digital twin implementation capabilities. The signal to watch is perfusion bioreactor adoption rates across sponsor RFPs, indicating platform standardization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Technology Deployment | Perfusion bioreactor adoption reduces facility footprint and cost-per-gram for high-volume monoclonal antibodies in United States corridors. |
| Regulatory Inspection History Accumulation | FDA and Swissmedic audit records anchor sponsor confidence and command pricing premiums for oncology biologics manufacturing. |
| Chromatography Resin Backward Integration | In-house protein A supply buffers margin compression from resin lead times and allocation constraints across campaigns. |
| Viral Vector Manufacturing Scale-Up | Gene therapy expertise transfers to mRNA vaccine platforms, opening cross-modal service expansion for fill-finish providers. |
| Digital Twin Implementation | Process simulation software enables remote tech transfer and reduces on-site validation requirements for sponsor campaigns. |
Study Parameters
Coverage spans the United States, Switzerland, China, Germany, and India, with primary inputs from each market's contract manufacturing executives, regulatory affairs leads, sponsor procurement managers, and quality unit directors. Secondary validation draws from FDA filings, EMA submissions, NMPA biologics licensing records, and CDSCO GMP inspection reports. Bottom-up capacity utilization modeling triangulates against top-down sponsor pipeline expenditure analysis.
Granularity-level modeling operates at product-type, technology, application, and client-type segmentation dimensions, with additional disaggregation by regional regulatory cluster and manufacturing platform maturity. CAGRs derive from capacity expansion announcements, sponsor RFP volume trends, and inspection history accumulation rates across the projection horizon. Forecast inputs incorporate perfusion bioreactor adoption curves and chromatography resin supply allocation patterns.
Regulatory timeline acceleration, single-use component supply disruptions, and sponsor pipeline failure rates are the dominant revision risks to modeled capacity absorption and pricing trajectories. Deviation in FDA Quality by Design enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Stable Cell Line Development Market