
 BRAF Kinase Inhibitors Market | 2026-2036
BRAF Kinase Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
BRAF Kinase Inhibitors Market Analysis
Oncology centers is bifurcating from traditional hospital infusion suites toward outpatient precision medicine hubs. F. Hoffmann-La Roche Ltd. leverages its companion diagnostic ecosystem to anchor combination therapy positioning. Novartis AG sustains broad geographic reach through established targeted therapy portfolios. Pfizer Inc. differentiates via vertically integrated clinical trial networks spanning multiple BRAF-mutant indications.
BRAF kinase inhibitors are small-molecule compounds engineered to selectively block mutated BRAF V600E/K kinase activity, typically formulated as oral capsules with defined bioavailability profiles and hepatic metabolism pathways; these agents halt aberrant MAPK signaling in tumor cells. Encorafenib occupies the fastest-expanding position within the product type dimension as clinicians prioritize combination regimens with MEK inhibitors. The melanoma therapy area retains the largest patient volume base, though colorectal cancer applications are gaining protocol inclusion across major cancer centers. Oral administration dominates utilization patterns due to patient convenience and cost structures, while intravenous formats persist in research laboratory settings for pharmacokinetic studies.
FDA oncology center of excellence review standards, EMA's MDR compliance requirements for companion diagnostics, and Japan PMDA sakigake designation frameworks collectively shape approval timelines and reimbursement thresholds for BRAF-targeted therapies. These regulatory architectures determine which manufacturers secure priority review vouchers and accelerated market entry pathways. Stakeholders must monitor evolving combination therapy trial readouts and biomarker-driven label expansions to anticipate shifts in prescriber preference and payer coverage policies.
Market Dynamics
Combination therapy protocols are compressing monotherapy utilization as oncology centers prioritize BRAF-MEK inhibitor pairings for durable response rates. This structural pivot toward synergistic regimens is reshaping clinical trial design, reimbursement negotiations, and manufacturing capacity allocation across the therapeutic landscape.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Accelerated review pathways compress development timelines for novel combination candidates. Manufacturers secure priority vouchers that expedite commercialization of dual-target regimens.
- Companion Diagnostic Integration:PCR-based BRAF V600E/K testing platforms enable patient stratification at the point of diagnosis. Pathology laboratories embed molecular screening into standard melanoma workups.
- Japan PMDA Sakigake Framework:Early approval mechanisms for innovative oncology products shorten market access delays. Domestic manufacturers leverage this pathway for combination therapy submissions.
Market Restraints
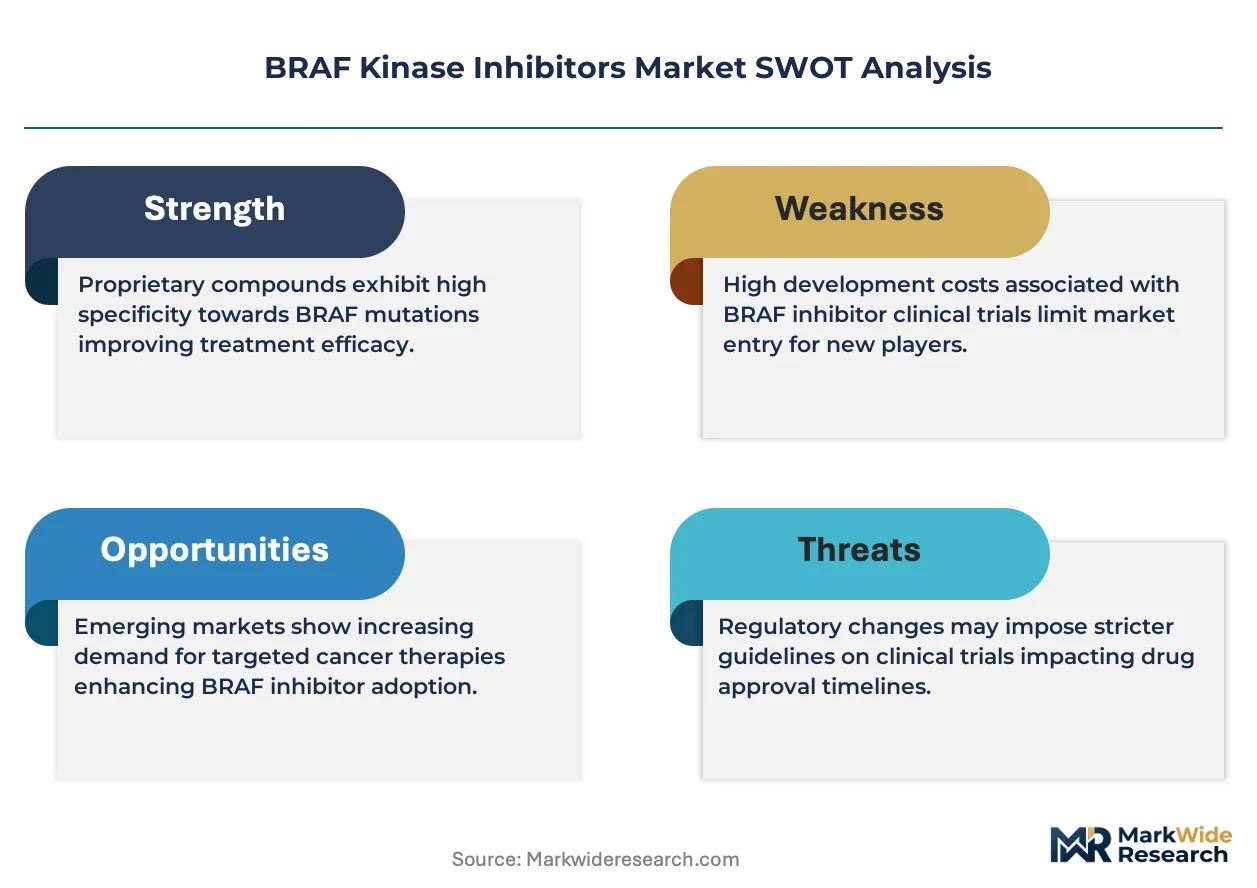
- API Supply Concentration:Active pharmaceutical ingredient production clusters in select Asian contract manufacturing organizations. Single-source dependencies create vulnerability to geopolitical trade disruptions.
- EMA MDR Compliance Burden:In vitro diagnostic regulation revisions impose documentation requirements on companion test developers. Smaller diagnostic firms face resource constraints for technical file preparation.
- Acquired Resistance Mechanisms:Secondary NRAS and MEK mutations emerge in treated patient populations. Clinicians cycle through limited salvage options as disease progression accelerates.
Strategic Opportunities
- Colorectal Cancer Protocol Expansion:BRAF V600E-mutant metastatic colorectal indications show emerging efficacy signals. Academic medical centers initiate basket trial enrollment for non-melanoma solid tumors.
- Real-World Evidence Generation:Flatiron Health and similar oncology data platforms enable post-marketing outcome tracking. Payers accept RWE submissions for formulary positioning of combination therapies.
- Outpatient Infusion Center Networks:Community oncology practices expand oral oncolytic dispensing capabilities. Patients bypass hospital-based pharmacy queues for same-day treatment initiation.
Industry Challenges
- Biomarker Testing Standardization:Discordant results between tissue-based and liquid biopsy platforms complicate treatment decisions. Pathology societies struggle to harmonize assay validation criteria.
- Cross-Border Reimbursement Fragmentation:National health technology assessment bodies apply divergent cost-effectiveness thresholds. Manufacturers negotiate parallel value demonstration frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BRAF Kinase Inhibitors Market |
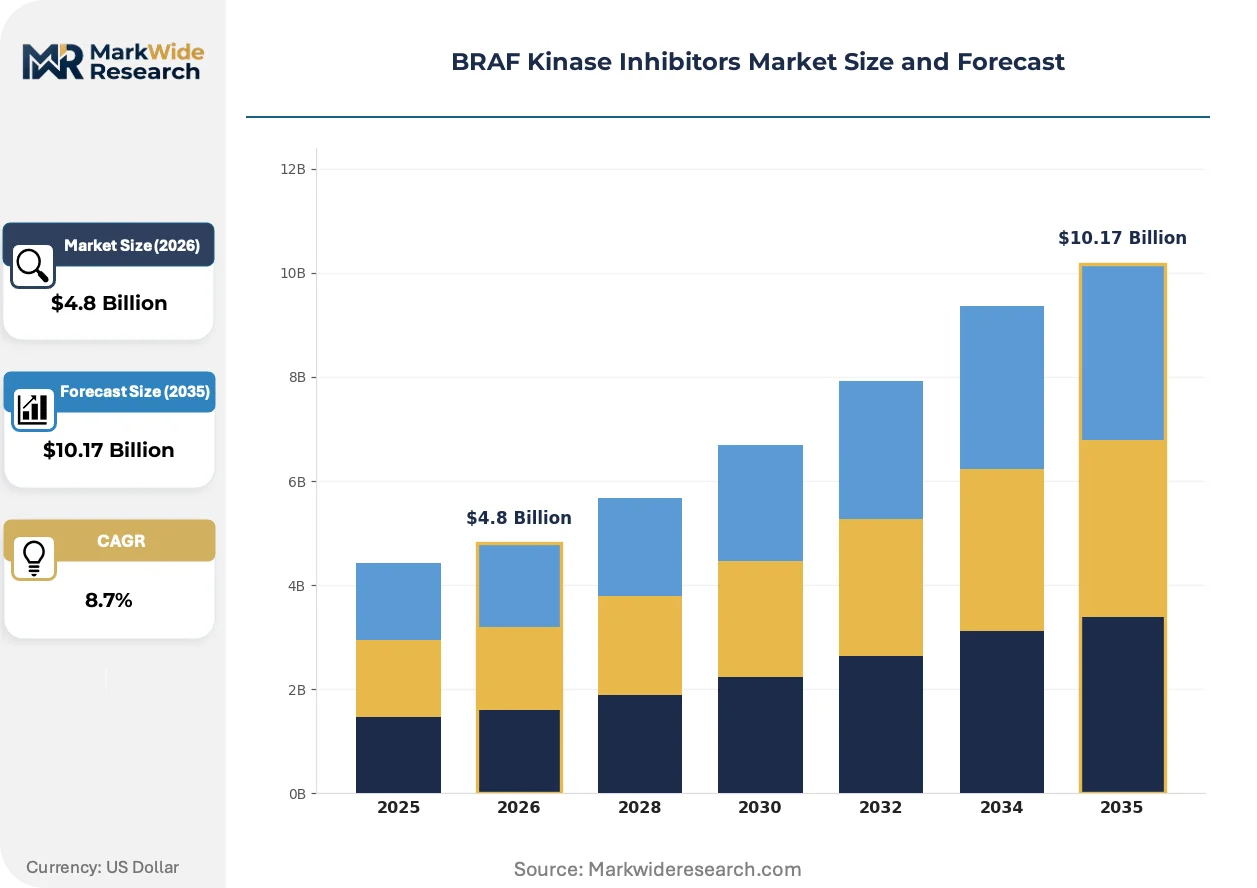
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dabrafenib, Vemurafenib, Encorafenib, Others Therapy Area: Melanoma, Colorectal Cancer, Lung Cancer, Others Administration Route: Oral, Intravenous, Subcutaneous, Others End User: Hospitals, Oncology Centers, Homecare Settings, Research Laboratories |
| Companies Covered | F. Hoffmann-La Roche Ltd., Novartis AG, Pfizer Inc., Bayer AG, BeiGene Ltd., Ono Pharmaceutical Co. Ltd., Asana BioSciences LLC, Jazz Pharmaceuticals Plc, GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BRAF Kinase Inhibitors Market Emerging Trajectories
Next-generation sequencing platforms are compressing diagnostic turnaround times while expanding detectable mutation spectra. These technical advances enable earlier intervention windows and more precise patient-treatment matching across oncology networks.
Third-generation BRAF inhibitors with paradox-breaking mechanisms are bifurcating from first-generation ATP-competitive scaffolds. Memorial Sloan Kettering and similar comprehensive cancer centers prioritize these agents for patients with prior progression on standard combinations. The technology is bifurcating clinical trial enrollment criteria toward more molecularly homogeneous cohorts.
EMA's Medical Device Regulation (MDR) implementation is elevating companion diagnostic quality management requirements. In vitro diagnostic manufacturers face notified body capacity constraints for conformity assessments. Class C diagnostic devices for BRAF mutation detection encounter extended certification timelines across European markets.
Specialty pharmacy distribution is displacing traditional hospital outpatient dispensing for oral kinase inhibitors. CVS Specialty and AllianceRx Walgreens Prime capture patient volumes through hub-and-spoke models with integrated adherence monitoring. Germany and Japan exhibit the most pronounced channel migration as reimbursement pathways accommodate home delivery logistics.
BRAF Kinase Inhibitors Market Segmentation
BRAF kinase inhibitor prescribing patterns diverge sharply across molecular profiles, care settings, and administration logistics. Manufacturers align portfolio investments with these fault lines to capture volume in melanoma while building optionality in emerging solid tumor indications.
Product Type:
Substitution pressure concentrates on first-generation ATP-competitive inhibitors as combination protocols favor next-generation scaffolds with improved paradox-breaking properties.
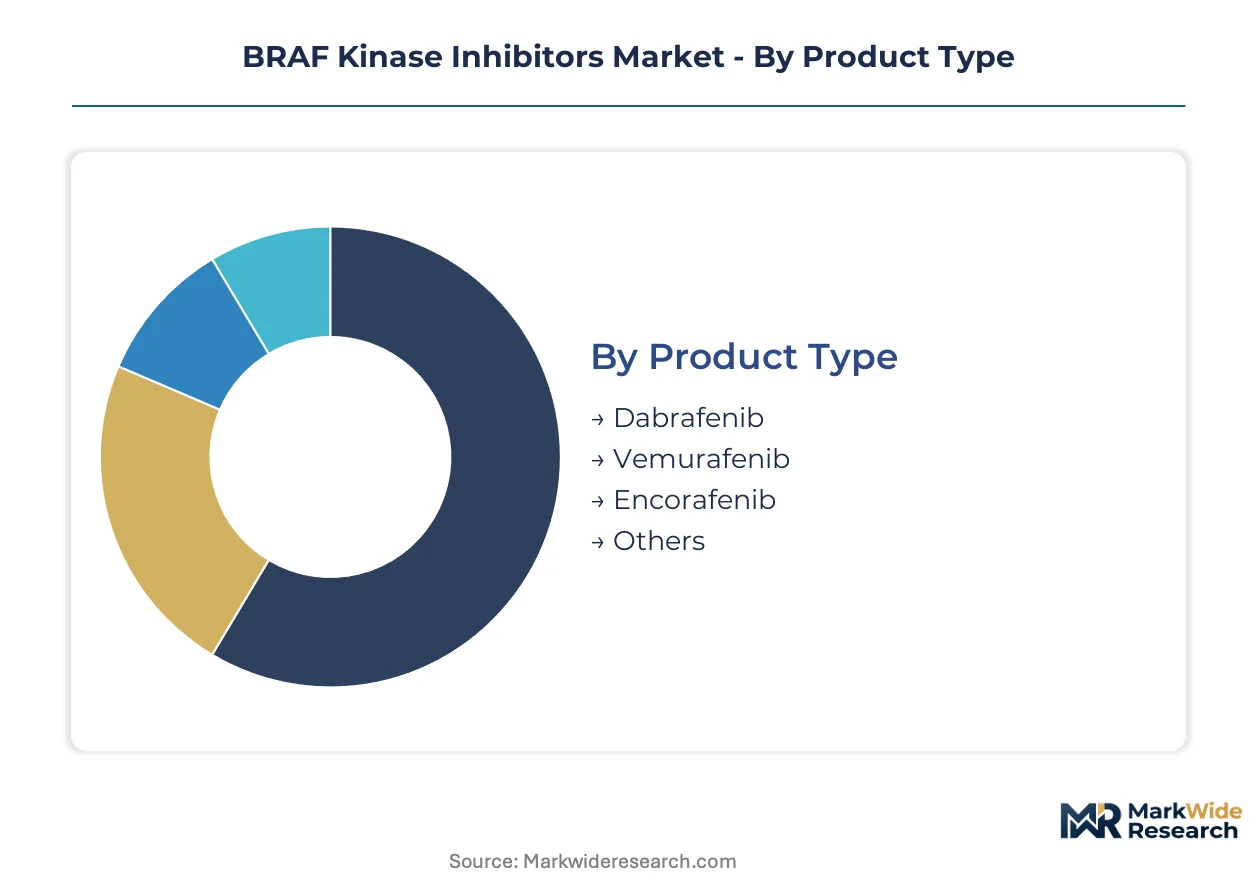
- Dabrafenib:A selective ATP-competitive BRAF V600E inhibitor formulated as oral capsules with established hepatic metabolism via CYP3A4 enzymes. Demand clusters in United States academic medical centers running combination trials with trametinib for adjuvant melanoma protocols.
- Encorafenib:A third-generation inhibitor engineered for extended target residence time and reduced paradoxical activation of wild-type BRAF. Germany's university hospitals prioritize this agent for BRAF-MEK pairing protocols in metastatic colorectal cancer.
- Vemurafenib:First-in-class BRAF inhibitor with documented efficacy in V600E-mutant melanoma.
- Others:Investigational compounds and biosimilar candidates in Phase II development pipelines.
Dabrafenib anchors the volume base while Encorafenib gains share at the steepest rate.
Therapy Area:
Cost tier stratification separates curative-intent melanoma regimens from palliative applications in refractory colorectal populations.
- Melanoma:Adjuvant and metastatic treatment protocols drive the largest patient volume with established reimbursement pathways across commercial and government payers.
- Colorectal Cancer:BRAF V600E-mutant metastatic indications demonstrate emerging efficacy signals in Japan's basket trial networks.
- Lung Cancer:Non-small cell lung cancer applications remain investigational with limited protocol inclusion.
- Others:Thyroid, hairy cell leukemia, and histiocytic disorder applications in early clinical exploration.
Melanoma commands the revenue concentration while Colorectal Cancer applications expand most quickly through protocol inclusion.
Administration Route:
Patient convenience preferences and pharmacy benefit structures are displacing hospital-based infusion models toward ambulatory oral dispensing.
- Oral:Capsule and tablet formulations dominate commercial utilization with bioavailability profiles supporting once-daily or twice-daily dosing schedules.
- Intravenous:Research laboratory applications persist for pharmacokinetic studies and bioequivalence assessments.
- Subcutaneous:Limited development activity for depot formulations in early-stage pipelines.
- Others:Transdermal and inhalation delivery mechanisms in preclinical investigation.
Oral administration captures the patient volume base while Intravenous formats retain specialized research demand.
End User:
Site-of-care migration is bifurcating dispensing authority between integrated delivery networks and independent community oncology practices.
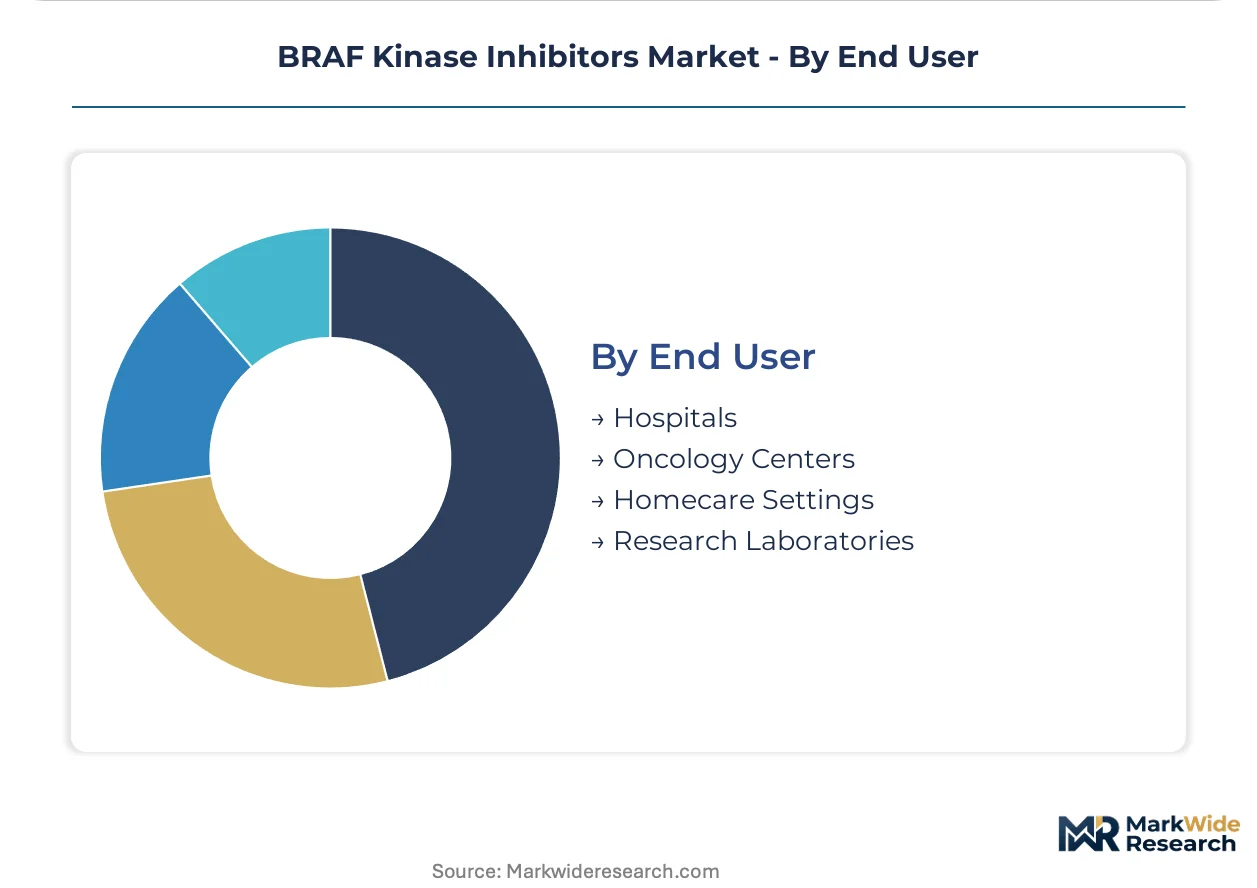
- Oncology Centers:Outpatient precision medicine hubs concentrate BRAF-mutant patient volumes with embedded molecular tumor boards and rapid turnaround testing.
- Hospitals:Academic medical centers retain complex case referrals and clinical trial enrollment for combination regimens.
- Homecare Settings:Specialty pharmacy networks enable direct-to-patient delivery with remote adherence monitoring.
- Research Laboratories:Contract research organizations and academic cores handle biomarker validation and resistance mechanism studies.
Oncology Centers anchor the prescription volume base while Homecare Settings climb the fastest as reimbursement accommodates remote dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and precision oncology hubs concentrate purchasing authority for BRAF-targeted therapies across major pharmaceutical markets. Reimbursement pathways and companion diagnostic infrastructure determine commercial penetration rates in each geography.
United States
Memorial Sloan Kettering and MD Anderson anchor combination therapy adoption for metastatic melanoma protocols. FDA breakthrough therapy designations compress review timelines for novel BRAF-MEK regimens. The Boston-Cambridge corridor concentrates biomarker testing infrastructure with embedded molecular tumor boards.
Germany
University hospitals in Munich and Heidelberg prioritize encorafenib-based pairings for colorectal cancer applications. EMA accelerated assessment procedures streamline market access for combination submissions. The Rhine-Ruhr metropolitan region hosts centralized pathology laboratories with PCR-based BRAF screening capabilities.
Japan
National Cancer Center hospitals in Tokyo and Osaka drive protocol inclusion for non-melanoma solid tumors. PMDA sakigake designation frameworks shorten approval delays for innovative oncology products. The Kansai region concentrates pharmaceutical manufacturing with integrated active ingredient synthesis capabilities.
United Kingdom
The Royal Marsden and Christie NHS Foundation Trusts coordinate adjuvant melanoma trials with real-world evidence collection. NICE technology appraisals apply quality-adjusted life year thresholds for combination therapy reimbursement. The Cambridge-Oxford-London golden triangle anchors precision medicine research consortia.
Switzerland
University Hospital Zurich and Lausanne University Hospital participate in multinational basket trials for rare BRAF-mutant indications. Swissmedic maintains alignment with EMA centralized procedures while offering national scientific advice pathways. The Basel biotech cluster hosts companion diagnostic developers with integrated pharmaceutical partnerships.
BRAF Kinase Inhibitors Market Vendor Landscape
Player mix skews toward integrated pharmaceutical conglomerates with companion diagnostic ecosystems and targeted therapy portfolios. Market structure concentrates around three to five established oncology franchises with vertically integrated clinical trial networks. Strategic archetypes include precision medicine platform builders, geographic reach maximizers, and combination regimen specialists. Dominant competitive moves encompass companion diagnostic partnerships and label expansion through biomarker-driven trial designs.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd., Novartis AG, and Pfizer Inc. occupy positions defined by diagnostic-therapy bundling capabilities and multi-indication clinical infrastructure. Roche represents the archetype of companion diagnostic anchoring. Novartis exemplifies broad geographic reach through established targeted therapy distribution. Pfizer sits within the vertically integrated trial network segment spanning multiple BRAF-mutant indications.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Novartis AG |
| Pfizer Inc. |
| Bayer AG |
| BeiGene Ltd. |
| Ono Pharmaceutical Co. Ltd. |
| Asana BioSciences LLC |
| Jazz Pharmaceuticals Plc |
| GlaxoSmithKline plc |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient batch economics in BRAF kinase inhibitor manufacturing concentrate production scale advantages among Asian contract manufacturing organizations, compressing unit costs for high-volume oral formulations while establishing price floors for specialized combination therapies that resist commoditization.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to raw material benchmarks and regulatory compliance cost escalators. Three-tier pricing structure across premium combination regimens, standard monotherapy, and economy-tier biosimilar candidates differentiates by clinical trial data depth and companion diagnostic bundling. Pricing pressure stems from payer formulary restrictions demanding outcome-based contracting for BRAF-MEK pairings. Community oncology practices exhibit highest price sensitivity due to thin dispensing margins, while academic medical centers prioritize efficacy data over acquisition cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate oral kinase inhibitor distribution through specialty pharmacy networks, though strategic stockpiling persists for clinical trial comparator arms and named-patient programs. API synthesis clusters in India, China, and South Korea with downstream formulation and packaging in Germany and the United States. Key inputs include pyridine derivatives, fluorinated intermediates, and high-purity solvents subject to environmental regulatory restrictions. Single-source dependencies for critical intermediates create vulnerability to export license delays. Distribution runs through hub-and-spoke specialty pharmacy models with integrated cold-chain logistics for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic platform economics are reshaping competitive positioning as therapy-diagnostic bundling becomes the default commercial architecture, with interoperability between PCR-based testing and electronic health record systems determining prescriber workflow integration.
For Market Incumbents: Consolidate companion diagnostic partnerships to lock in testing channel control before emerging players secure pathology laboratory relationships. Deepen backward integration into API synthesis for encorafenib-class scaffolds to insulate margin structures from Asian contract manufacturing pricing volatility. Priority defensive moves include securing FDA breakthrough therapy designations for next-generation paradox-breaking inhibitors and embedding molecular tumor board software into integrated delivery network workflows. For New Entrants and Emerging Players: Post-treatment resistance monitoring services represent the most penetrable white-space segment where incumbents under-serve with liquid biopsy platforms for NRAS and MEK mutation tracking. Target community oncology practices in the United States Sun Belt and German ambulatory care networks with oral dispensing capabilities. Go-to-market angle centers on remote patient adherence monitoring through smartphone-connected pill dispensers with real-time data feeds to payers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision medicine platform builders with companion diagnostic recurring test volumes and therapy royalty streams. Five-to-ten year viability favors acquisition targets possessing vertically integrated clinical trial networks spanning melanoma and colorectal cancer indications. Signal to watch is EMA MDR certification timelines for Class C diagnostic devices, as notified body capacity constraints create acquisition windows for CE-mark-ready testing platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | Roche's embedded testing ecosystem anchors prescriber workflow integration for combination regimens. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses review timelines for novel BRAF-MEK candidates. |
| Manufacturing Scale-Up | Encorafenib API capacity expansion in Basel cluster supports colorectal cancer protocol inclusion. |
| Pipeline Diversification | Basket trial enrollment for thyroid and histiocytic disorders extends addressable patient populations. |
| Reimbursement Strategy | NICE technology appraisals in United Kingdom establish quality-adjusted life year benchmarks for payer negotiations. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions shaping this analysis. Primary interviews across pharmaceutical manufacturers, diagnostic developers, and integrated delivery networks combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down revenue triangulation anchored market size estimates across the analysis window.
Segmentation dimensions modeled include product generation tier, therapy area indication, administration route, end-user site of care, and regional regulatory cluster. CAGRs were derived from treatment protocol adoption curves, biomarker testing penetration rates, and reimbursement pathway expansion timelines. Forecast inputs incorporated combination therapy trial readouts, companion diagnostic regulatory certification schedules, and prescriber preference shifts toward outpatient precision medicine hubs.
Underlying assumptions cover FDA and EMA approval trajectory continuity, with deviation risk concentrated in biomarker testing standardization delays and cross-border reimbursement fragmentation. Forecasts reflect these documented assumptions with sensitivity analysis for acquired resistance mechanism emergence and third-generation inhibitor clinical trial outcomes. Revision becomes warranted when PMDA sakigake designation thresholds or EMA MDR notified body capacity constraints cross material disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Global Bioengineered Protein Drugs Market
Biopharmaceuticals
Drug Resistant Pulmonary Tuberculosis Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market