
 Large Macrolide Drugs Market | 2026-2036
Large Macrolide Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Large Macrolide Drugs Market Analytics
Semisynthetic erythromycin derivatives are decoupling from legacy fermentation economics as enzymatic catalysis replaces classical chemical modification. Pfizer Inc leverages captive fermentation capacity to anchor its cost position in clarithromycin supply. Teva Pharmaceutical Industries Ltd competes through backward integration into active pharmaceutical ingredient production. Sun Pharmaceutical Industries Ltd dominates injectable macrolide exports from its Indian manufacturing base.
Large macrolide drugs comprise 14- to 16-membered lactone-ring antibiotics synthesized via Streptomyces fermentation or semisynthetic modification, with azithromycin incorporating a methyl-substituted nitrogen in the macrolide ring to enhance gastric acid stability and tissue half-life. These agents function primarily through 50S ribosomal subunit binding to inhibit bacterial protein synthesis across gram-positive and atypical pathogens. Oral delivery mode leads volume consumption due to outpatient respiratory infection prescribing patterns, while injectable formulations command premium positioning in hospital sepsis protocols. Respiratory infection therapy anchors revenue concentration, though sexually transmitted infection protocols represent the fastest-expanding indication as dual-therapy gonorrhea guidelines evolve.
FDA bioequivalence standards shape generic azithromycin market access timelines, while EMA's revised antibiotic environmental risk assessment guidelines are elevating manufacturing discharge compliance costs. India's CDSCO accelerated approval pathways for anti-infectives are compressing entry timelines for domestic manufacturers. Stakeholders must monitor evolving WHO essential medicines list revisions and national stewardship program rollouts to anticipate demand trajectory shifts.
Market Dynamics
Enzymatic catalysis is severing semisynthetic macrolide production from legacy fermentation economics, compressing batch times and raw material intensity while reshaping manufacturer cost structures and competitive positioning.
Growth Catalysts
- CDSCO Accelerated Approvals:India's streamlined pathways for anti-infectives are compressing domestic manufacturer entry timelines and expanding hospital formulary access.
- Dual-Therapy Gonorrhea Protocols:Evolving WHO sexually transmitted infection guidelines are expanding macrolide indication scope beyond respiratory applications.
- Hospital Sepsis Protocols:Injectable azithromycin demand is accelerating across tertiary care centers in Brazil, Mexico, and South Africa.
Market Restraints
- Streptomyces Fermentation Concentration:Active pharmaceutical ingredient supply clusters in Indian and Chinese fermentation facilities create geographic vulnerability.
- EMA Environmental Risk Assessment:Revised antibiotic manufacturing discharge guidelines are elevating compliance costs for European production sites.
- Fluoroquinolone Substitution:Respiratory infection prescribing protocols in some markets retain competing antibiotic classes as first-line alternatives.
Strategic Opportunities
- Southeast Asia Hospital Procurement:Oral azithromycin volume demand is expanding in Indonesia, Vietnam, and Philippines outpatient networks.
- FDA Generic Bioequivalence Pathways:Streamlined abbreviated new drug application standards are reducing generic manufacturer market access friction.
- Enzyme-Assisted Semisynthesis:Biocatalytic modification platforms are converging with continuous flow chemistry to enable novel derivative development.
Industry Challenges
- Stewardship Program Compliance:National antibiotic resistance action plans in multiple jurisdictions are restricting promotional activity and volume incentives.
- Fermentation Scale-Up Expertise:Industrial microbiology talent scarcity is constraining capacity expansion at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Large Macrolide Drugs Market |
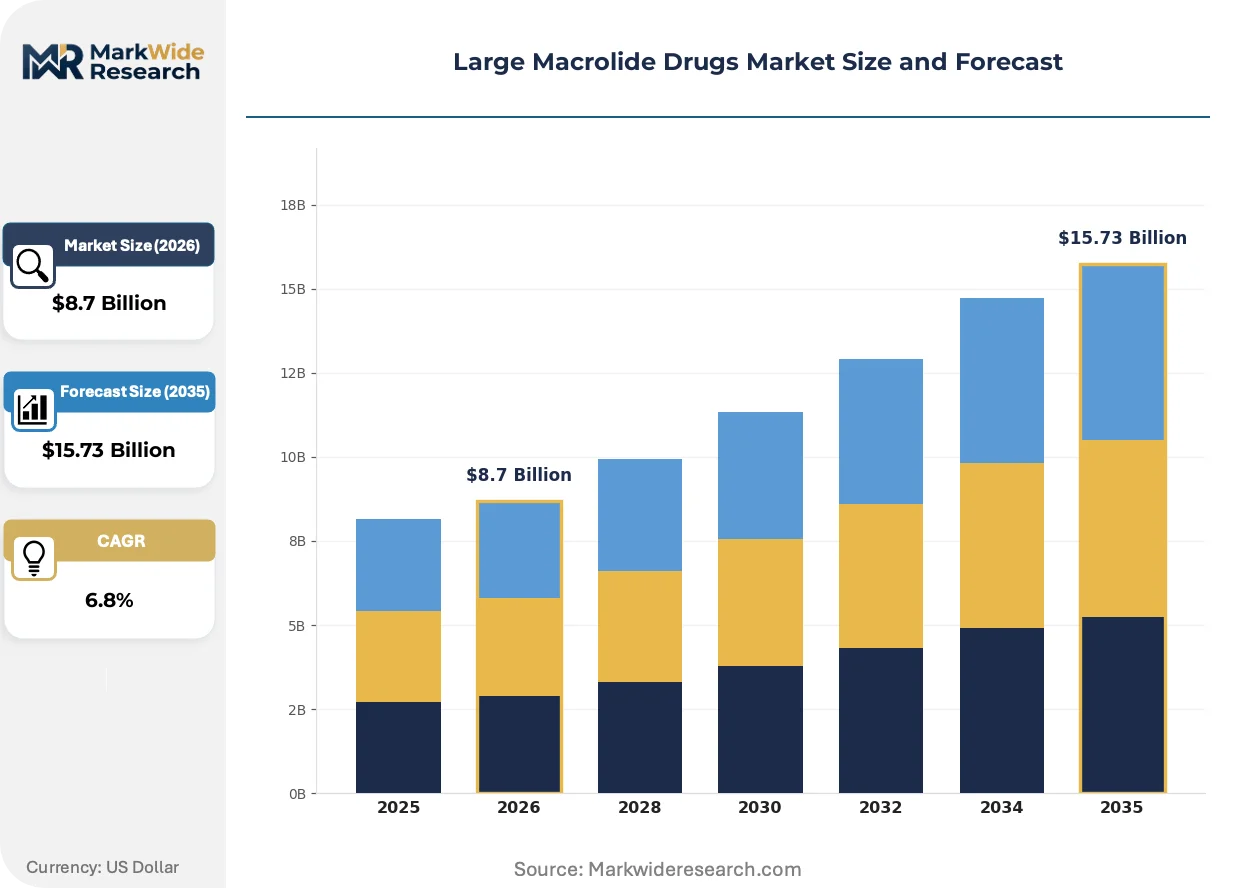
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythromycin, Azithromycin, Clarithromycin, Roxithromycin Therapy Area: Respiratory Infections, Skin Infections, Ear Infections, Sexually Transmitted Infections Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Hospitals, Clinics, Homecare, Pharmaceutical Companies |
| Companies Covered | Pfizer Inc, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., AbbVie Inc., Novartis AG, GlaxoSmithKline plc, Sun Pharmaceutical Industries Ltd., Sandoz International GmbH, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Large Macrolide Drugs Market Evolving Landscape
Biocatalytic manufacturing platforms are actively displacing classical chemical modification routes, while regulatory environmental standards tighten and hospital procurement models concentrate buying power across emerging markets.
Continuous enzymatic catalysis is consolidating semisynthetic macrolide production economics by replacing multi-step chemical modification with single-vessel biocatalytic transformations. Contract development and manufacturing organizations serving generic pharmaceutical clients are adopting these platforms at accelerated pace. The technology is consolidating competitive advantage toward manufacturers with in-house enzyme engineering capabilities and captive fermentation infrastructure.
EMA's revised antibiotic environmental risk assessment guidelines are mandating enhanced manufacturing discharge monitoring and treatment infrastructure. European production facilities face elevated capital requirements for compliance with aquatic toxicity thresholds. Injectable macrolide manufacturing sites in Germany and Italy are responding with closed-loop water systems and advanced oxidation process installations.
Hospital group purchasing organizations are centralizing antibiotic procurement decisions across multi-facility networks in India and Southeast Asia. Regional distributor relationships are being displaced by direct manufacturer contracts with consolidated tender platforms. This concentration is most visible in Maharashtra and Karnataka state hospital systems, where centralized pharmacy committees now control formulary placement for respiratory infection protocols.
Large Macrolide Drugs Market Segmentation
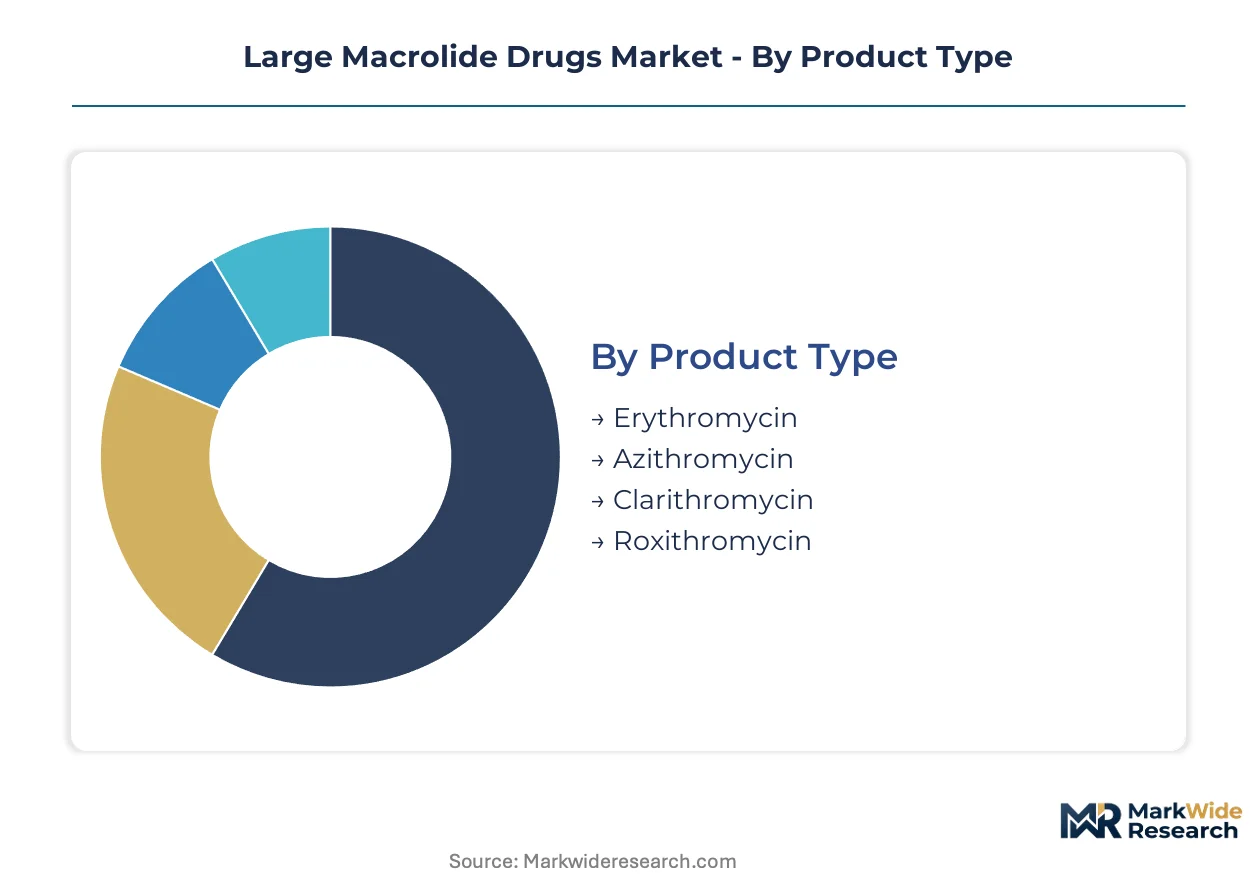
Large macrolide drugs fragment across four structural dimensions that determine manufacturing investment intensity, regulatory pathway complexity, and margin capture potential. Each segmentation axis reveals distinct competitive dynamics between fermentation-based incumbents and biocatalytic challengers.
Product Type:
Capital intensity varies sharply across this category, with fermentation scale-up requirements and semisynthetic modification complexity driving facility investment thresholds.
- Azithromycin:A methyl-substituted 15-membered macrolide engineered for gastric acid stability and extended tissue half-life. Hospital procurement in Maharashtra and Karnataka state systems is compressing distributor margins while accelerating volume concentration toward manufacturers with captive fermentation infrastructure.
- Erythromycin:The foundational 14-membered macrolide produced via Streptomyces fermentation with classical chemical modification. Demand is softening in developed markets as resistance profiles and gastrointestinal tolerability concerns shift prescribing toward semisynthetic derivatives.
- Clarithromycin:A 6-O-methylerythromycin derivative with enhanced acid stability. Pfizer's captive fermentation capacity anchors supply security for this segment.
- Roxithromycin:A semisynthetic derivative with modified pharmacokinetic properties. Teva Pharmaceutical Industries Ltd competes through backward integration into active pharmaceutical ingredient production for this compound.
Most installed capacity flows through azithromycin. Expansion is steepest in clarithromycin as hospital sepsis protocols drive injectable demand.
Therapy Area:
Application-specific regulatory requirements and reimbursement dynamics create divergent margin profiles across clinical indications.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis protocols anchor volume consumption. Brazil, Mexico, and South Africa concentrate outpatient prescribing for this indication, with oral azithromycin dominating first-line therapy.
- Sexually Transmitted Infections:Dual-therapy gonorrhea guidelines from WHO are expanding indication scope beyond traditional respiratory applications. This segment is gaining share fastest as resistance surveillance reshapes protocol recommendations.
- Skin Infections:Erysipelas and impetigo protocols utilize macrolides as penicillin alternatives. Demand concentrates in dermatology clinics and emergency departments.
- Ear Infections:Pediatric otitis media represents a volume-stable but price-sensitive segment with strong generic substitution pressure.
Respiratory infections retain the largest patient population base. Sexually transmitted infection protocols are climbing the fastest as guideline evolution accelerates.
Delivery Mode:
Manufacturing complexity and sterility assurance requirements stratify competitive positioning across administration routes.
- Oral:Tablet and suspension formulations lead volume consumption due to outpatient respiratory infection prescribing patterns. Southeast Asia hospital procurement expansion in Indonesia, Vietnam, and Philippines is driving tender concentration.
- Injectable:Intravenous formulations command premium positioning in hospital sepsis protocols across tertiary care centers. Sun Pharmaceutical Industries Ltd dominates exports from Indian manufacturing bases for this high-margin segment.
- Topical:Dermatological preparations serve localized skin infection therapy with limited systemic exposure. Regulatory bioequivalence standards from FDA shape generic market access timelines.
- Inhalation:Aerosolized macrolide delivery for chronic respiratory conditions represents an emerging modality with specialized device compatibility requirements.
Oral delivery channels the majority of unit volume. Injectable formats deliver the steepest margin expansion as hospital procurement consolidates.
End User:
Customer-type concentration patterns determine pricing leverage and contract structure complexity across the value chain.
- Hospitals:Tertiary care centers and multi-facility networks centralize antibiotic procurement through group purchasing organizations. CDSCO accelerated approval pathways are compressing domestic manufacturer entry timelines for hospital formulary access in India.
- Clinics:Outpatient facilities drive oral macrolide volume with prescription patterns shaped by regional resistance surveillance data.
- Homecare:Post-discharge oral therapy and long-term prophylaxis represent a growing channel as hospital length-of-stay contracts.
- Pharmaceutical Companies:Active pharmaceutical ingredient supply and contract manufacturing relationships serve as a demand source for fermentation and biocatalytic production capacity.
Hospital procurement absorbs the largest share of high-value injectable volume. Homecare channels are expanding most quickly as oral therapy protocols shift treatment location.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian fermentation clusters anchor API supply security for large macrolide drugs. Hospital procurement centralization and regulatory acceleration are reshaping demand geography across five critical markets.
United States
FDA generic bioequivalence pathways compress market access timelines for azithromycin manufacturers. The agency's abbreviated new drug application standards reduce entry friction for domestic and foreign suppliers alike. Injectable macrolide demand concentrates in tertiary care centers across Texas, Florida, and California hospital systems.
India
CDSCO accelerated approval pathways for anti-infectives expand hospital formulary access for domestic manufacturers. Maharashtra and Karnataka state health systems centralize procurement through pharmacy committees controlling respiratory infection protocols. Sun Pharmaceutical Industries Ltd dominates injectable exports from fermentation facilities in Gujarat and Maharashtra.
Germany
EMA environmental risk assessment guidelines mandate enhanced discharge monitoring for antibiotic manufacturing sites. Production facilities in Bavaria and North Rhine-Westphalia deploy closed-loop water systems and advanced oxidation processes. Injectable clarithromycin supply serves hospital sepsis protocols across Berlin, Munich, and Hamburg tertiary networks.
Brazil
ANVISA regulatory frameworks shape generic macrolide registration timelines for respiratory infection therapy. Outpatient prescribing concentrates in São Paulo, Rio de Janeiro, and Minas Gerais state health systems. Hospital sepsis protocols in southeastern tertiary centers drive injectable azithromycin procurement expansion.
China
NMPA drug approval reforms streamline anti-infective market access for domestic fermentation-based manufacturers. Streptomyces fermentation capacity clusters in Jiangsu and Shandong provinces supply global API demand. Environmental compliance upgrades at Zhejiang production sites respond to MEE discharge standards tightening.
Large Macrolide Drugs Market Competitive Landscape
Global majors compete with regional champions across fermentation capacity and semisynthetic modification expertise. Market structure tilts toward consolidated supply among captives with backward integration into active pharmaceutical ingredient production. Three archetypes dominate: fermentation-anchored incumbents, biocatalytic challengers, and contract manufacturing specialists. Capacity expansion and enzyme engineering licensing represent the dominant competitive moves reshaping cost positions.
Among fermentation-anchored pharmaceutical manufacturers, Pfizer Inc and Sun Pharmaceutical Industries Ltd exemplify the captive capacity archetype. Teva Pharmaceutical Industries Ltd occupies a position representing backward integration into API production for semisynthetic derivatives. These three companies anchor the competitive structure through control over manufacturing infrastructure rather than portfolio breadth alone.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Sun Pharmaceutical Industries Ltd. |
| Sandoz International GmbH |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
Hospital procurement centralization across Maharashtra and Karnataka state health systems is compressing distributor margins and forcing manufacturers toward direct tender participation, which stratifies pricing power around captive fermentation capacity and enzymatic catalysis adoption.
Pricing Analysis
Input-cost pass-through from Streptomyces fermentation substrates and enzyme engineering investments shapes contract structures. Three-tier pricing separates originator-grade clarithromycin from standard generic azithromycin and economy erythromycin, with FDA bioequivalence tiering as the primary differentiation driver. Pricing pressure stems from Indian and Southeast Asian tender concentration, which intensifies volume-scale competition. Hospital group purchasing organizations exhibit highest price sensitivity, while injectable sepsis protocol buyers accept premium positioning for supply security.
Supply Chain Analysis
Dual-sourcing requirements from European and North American hospital systems mandate API qualification across at least two fermentation bases. Supply concentrates in Indian and Chinese Streptomyces facilities, with Jiangsu and Gujarat clusters anchoring global API output. Raw material dependencies include corn steep liquor, soybean meal, and specialized enzyme preparations. Single-source vulnerability persists where biocatalytic expertise concentrates at mid-tier manufacturers. Distribution runs through regional tender platforms and direct manufacturer contracts, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in large macrolide drugs rest on enzymatic catalysis cost-down trajectories and injectable premium-tier demand from hospital sepsis protocols.
For Market Incumbents: Extend fermentation capacity utilization into contract manufacturing services for biocatalytic challengers lacking captive infrastructure. Secure enzyme engineering licensing agreements to defend cost positions against continuous-flow chemistry entrants. Anchor supply security through backward integration into Indian API clusters facing environmental compliance upgrades. For New Entrants and Emerging Players: Launch via direct tender platform participation in Indonesia, Vietnam, and Philippines outpatient networks where hospital procurement centralization creates formulary access openings. Target sexually transmitted infection protocol expansion as the fastest-climbing indication with less entrenched incumbent presence. Pursue CDSCO accelerated approval pathways to compress domestic Indian market entry timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with biocatalytic technology licensors and mid-tier Indian manufacturers with fermenter assets but underutilized enzyme engineering capabilities. Five-to-ten-year viability favors positions combining captive fermentation with environmental compliance infrastructure ahead of EMA discharge standard tightening. Watch WHO essential medicines list revisions for gonorrhea dual-therapy guideline shifts as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme Engineering Licensing | Biocatalytic platforms from specialized CROs displace classical chemical modification for semisynthetic derivatives. |
| CDSCO Accelerated Approval | Streamlined anti-infective pathways compress domestic manufacturer entry timelines for hospital formulary access. |
| Continuous Flow Chemistry Integration | Single-vessel transformations reduce batch times and raw material intensity in clarithromycin production. |
| Closed-Loop Water Systems | Advanced oxidation processes at European sites respond to EMA aquatic toxicity discharge thresholds. |
| Direct Tender Platform Contracts | Manufacturer relationships with Maharashtra and Karnataka pharmacy committees displace regional distributors. |
Research Methodology
Direct dialogue with fermentation operations directors, hospital procurement managers, regulatory affairs leads at CDSCO and FDA, and contract manufacturing organization executives grounded qualitative findings. Secondary validation drew from FDA ANDA filings, EMA environmental risk assessment guidelines, Indian state health department tender records, and WHO essential medicines list documentation. Bottom-up patient-volume modeling and top-down API production capacity estimates were triangulated against hospital formulary placement data.
Bottom-up demand modeling tracked respiratory infection prescribing volumes, sexually transmitted infection protocol adoption curves, and sepsis protocol penetration across tertiary care networks. Top-down supply assessment mapped fermentation capacity at Indian and Chinese facilities against enzymatic catalysis adoption rates. Segmentation dimensions included product type, therapy area, delivery mode, and end-user concentration patterns. CAGRs were derived from volume-price elasticity modeling and regulatory pathway timeline compression effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated antibiotic stewardship program rollouts or sudden fermentation substrate cost shocks. Forecasts reflect documented assumptions regarding CDSCO approval velocity, EMA environmental compliance cost trajectories, and hospital procurement centralization momentum. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Penicillin G Acylase Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Spectinomycin Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
Octreotide Market