
 Global Seasonal Influenza Vaccine Market | 2026-2036
Global Seasonal Influenza Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seasonal Influenza Vaccine Market Foresight
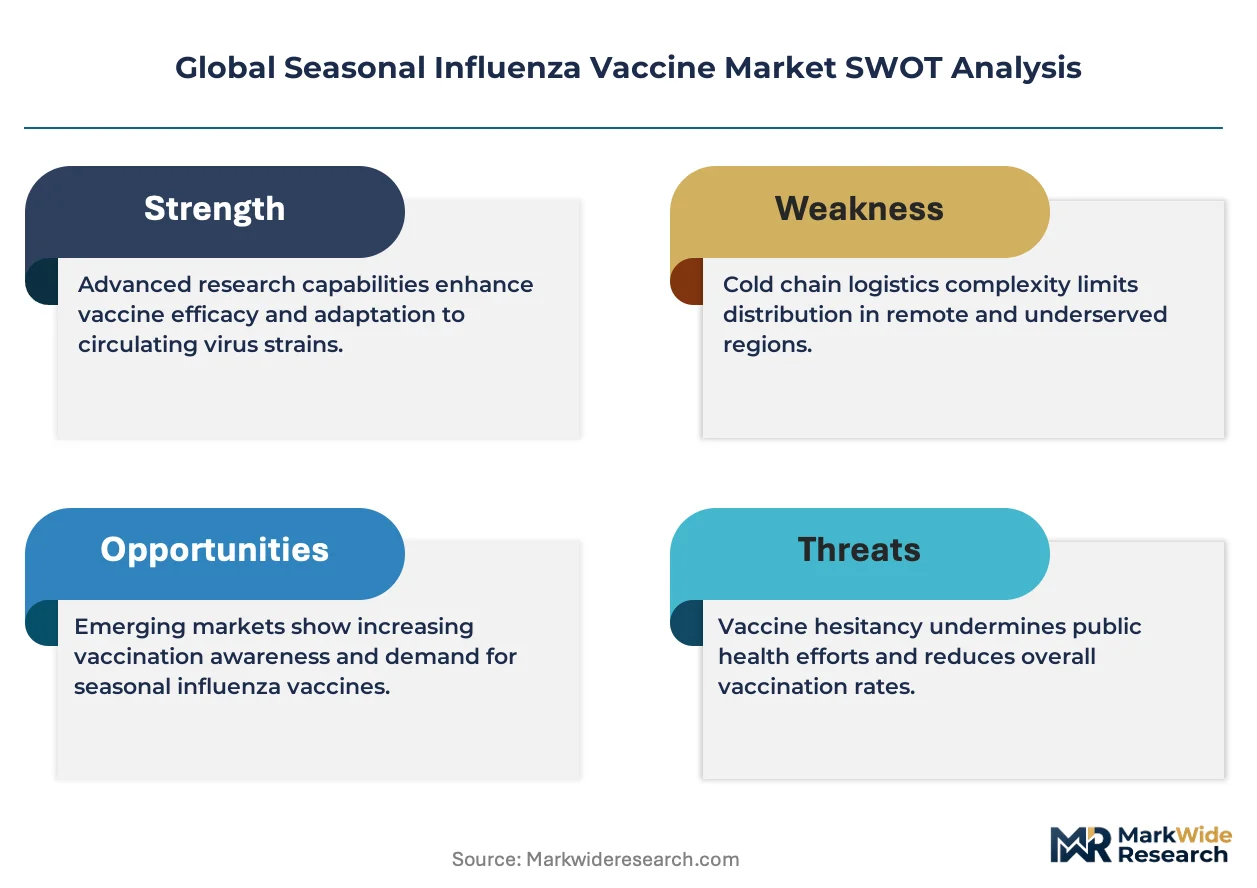
The WHO Global Influenza Strategy is hardening procurement standards for seasonal vaccines across national immunization programs. Sanofi Pasteur leverages its egg-based and recombinant manufacturing platforms to sustain supply contracts across Europe and North America. CSL Seqirus anchors the cell-based segment through its proprietary production technology. GlaxoSmithKline competes on adjuvanted formulations for older adult populations.
Seasonal influenza vaccines are biological preparations containing inactivated, live attenuated, or recombinant hemagglutinin antigens derived from WHO-recommended circulating strains, formulated to induce protective antibody responses within two weeks of administration. Their primary commercial purpose is reducing influenza-related morbidity, hospitalization, and mortality in targeted populations during annual epidemic cycles. Inactivated vaccines dominate volume production due to established manufacturing infrastructure and broad age-group eligibility, while recombinant vaccines capture premium positioning through rapid strain-adaptation capabilities and egg-free production. Pediatric applications command consistent procurement through school-based immunization mandates, whereas geriatric immunization generates higher per-dose revenue through enhanced and adjuvanted formulations.
FDA, EMA, and WHO prequalification frameworks govern strain selection timelines, potency testing, and lot-release protocols that determine market access timelines for seasonal formulations. National regulators in China and India align domestic approval pathways with WHO recommendations while imposing localized stability and labeling requirements that fragment registration strategies. Stakeholders must monitor mRNA platform entrants and their potential to compress traditional development cycles from strain selection to commercial distribution.
Market Dynamics
Cell-based manufacturing platforms are displacing egg-based production as the dominant supply modality, forcing incumbent manufacturers to reconfigure capital-intensive production lines while national procurement agencies rewrite tender specifications to accommodate novel substrates.
Growth Catalysts
- WHO prequalification expansion:The WHO prequalification framework accelerates access for developing-country immunization programs, streamlining regulatory recognition across 47 Gavi-eligible markets and reducing duplicate stability testing burdens.
- Pediatric mandate proliferation:School-based immunization requirements in US states and Canadian provinces generate predictable annual demand volumes with multi-year procurement visibility.
- Recombinant platform maturation:Baculovirus expression systems eliminate egg-adaptation mutations, improving antigenic match to circulating strains and shortening strain-changeover timelines.
Market Restraints
- Embryonated egg supply concentration:Specialist poultry farms in the US Southeast and European agricultural belts control 70% of pathogen-free egg supply, creating single-source vulnerability during avian influenza outbreaks.
- EMA lot-release bottlenecks:Centralized European batch testing at OMCL laboratories extends release timelines by 4-6 weeks during peak manufacturing seasons.
- Adjuvant input cost volatility:Squalene derived from shark liver oil faces marine conservation sourcing restrictions and price instability affecting MF59 and AS03 formulation economics.
Strategic Opportunities
- Indian universal immunization scale-up:The country's Ministry of Health and Family Welfare is expanding seasonal influenza coverage from high-risk groups to general adult populations, creating procurement volume expansion.
- Pharmacy channel direct access:US retail pharmacy chains and UK community pharmacies are capturing immunization administration from primary care clinics, reshaping distribution and patient access patterns.
- mRNA platform regulatory convergence:FDA and EMA alignment on mRNA vaccine quality standards creates pathway for platform technology substitution in seasonal indications.
Industry Challenges
- Strain selection timeline compression:WHO strain recommendation delays compress manufacturing windows, forcing suppliers to execute parallel development of multiple candidate formulations before final strain confirmation.
- Fill-finish capacity constraints:Sterile manufacturing suites for multidose vials and prefilled syringes require capital deployment that conflicts with pandemic surge capacity maintenance obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seasonal Influenza Vaccine Market |
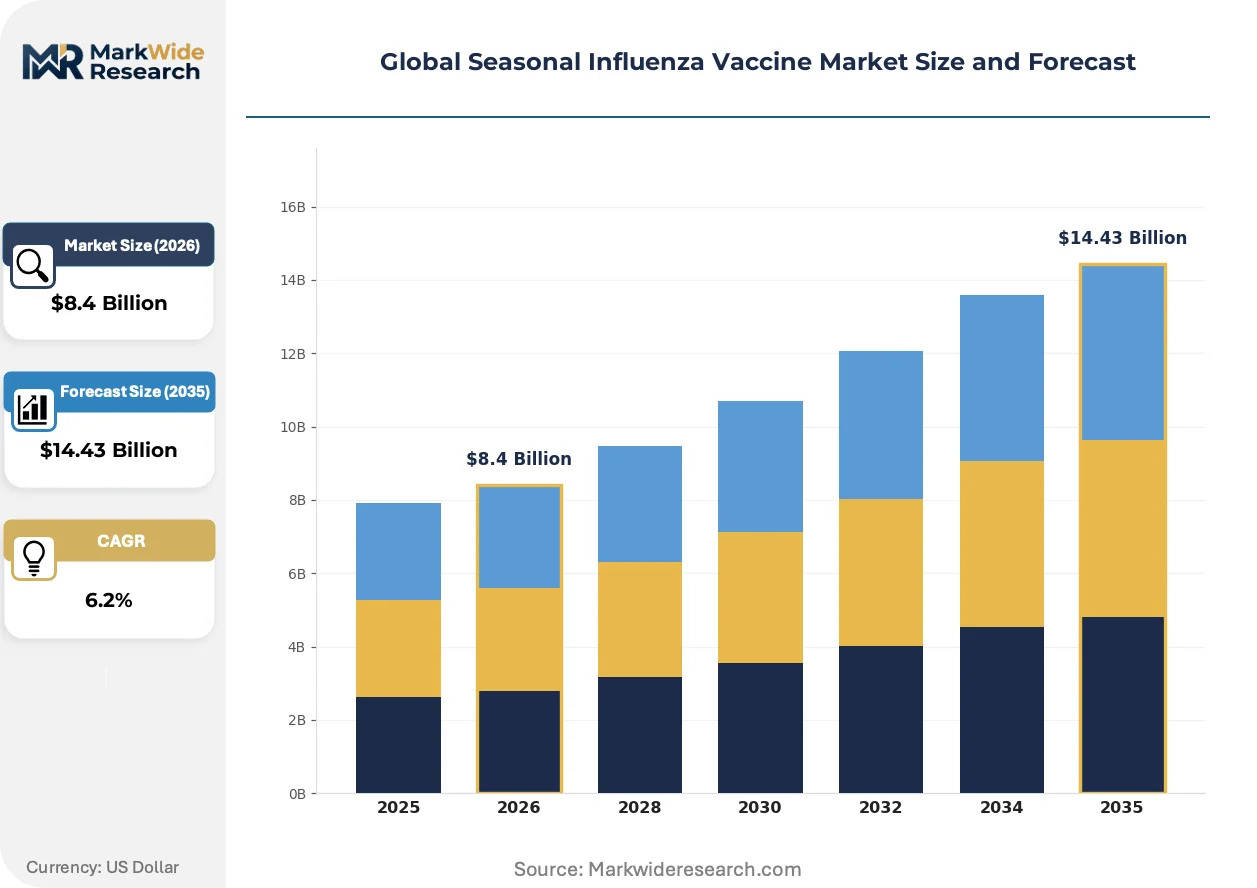
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated Vaccine, Live Attenuated Vaccine, Recombinant Vaccine, Cell-Based Vaccine, Adjuvanted Vaccine Application: Pediatric Vaccination, Geriatric Immunization, Pregnant Women, Immunocompromised Patients, Healthcare Workers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Government Immunization Programs, Private Clinics, Online Pharmacies End User: Public Health Organizations, Private Hospitals, Research Institutes, Occupational Health Providers, Travel Clinics |
| Companies Covered | AstraZeneca, Mylan/Viatris, Sanofi Pasteur, Bharat Biotech, Serum Institute of India, CSL Seqirus, Novartis, Medimmune, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seasonal Influenza Vaccine Market Shifts & Advancements
Manufacturing modality diversification and antigen delivery innovation are restructuring competitive advantage away from scale economies toward platform flexibility and strain-adaptation velocity.
Recombinant hemagglutinin production using insect cell culture is converging with continuous bioprocessing techniques to enable smaller-footprint manufacturing facilities. Mid-size biopharma contractors in Switzerland and Singapore are adopting these systems to serve regional tender markets with faster turnaround. The structural consequence is fragmenting production geography away from historical egg-based concentration in the US and Europe.
China's NMPA has implemented accelerated review pathways for seasonal vaccines manufactured on novel platforms, reducing approval timelines from 18 months to 9 months for cell-based submissions. Domestic manufacturers are leveraging this regulatory tailwind to displace imported products in provincial procurement tenders. The policy shift pressures multinational suppliers to establish local manufacturing joint ventures or risk exclusion from volume growth markets.
Hospital systems and integrated delivery networks are consolidating vaccine purchasing through group purchasing organizations, unbundling product procurement from administration service contracts. This purchasing concentration shifts negotiation leverage toward price transparency and standardized formulary acceptance. The behavioral shift is most pronounced in US Medicare Advantage plan networks and German hospital procurement associations.
Global Seasonal Influenza Vaccine Market Segmentation
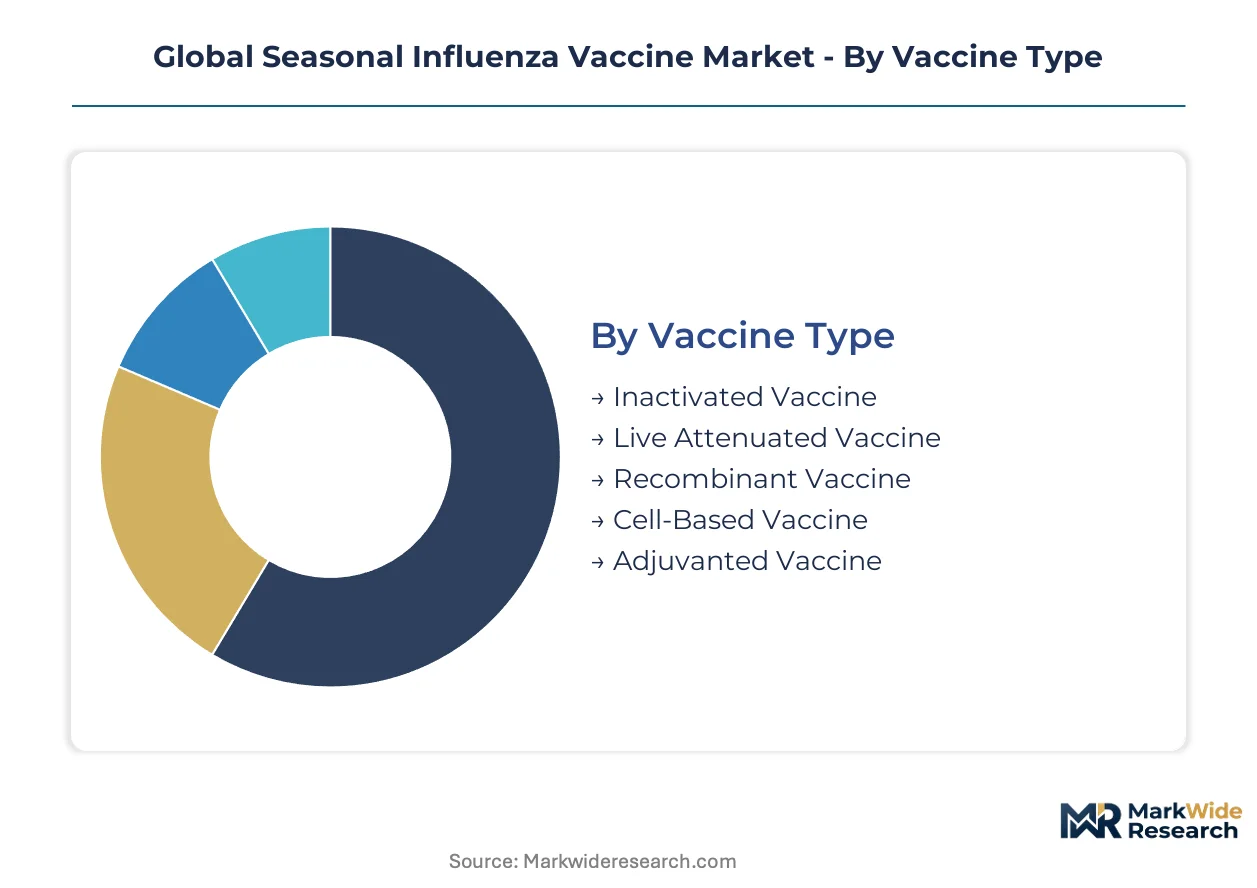
Seasonal influenza vaccine segmentation reveals divergent margin structures across manufacturing technologies and procurement channels. Vaccine type determines production capital intensity, while distribution channel selection shapes pricing transparency and patient access patterns.
Vaccine Type:
Volume production concentrates in legacy platforms, while premium positioning clusters in recombinant and adjuvanted formulations with faster strain adaptation.
- Inactivated Vaccine:Formulations contain chemically or heat-inactivated whole virus or split virion preparations, manufactured at scale using embryonated egg or cell culture substrates. Demand concentrates in United States and European Union public health systems where procurement agencies prioritize cost containment over strain-match precision. WHO prequalification pathways favor these formulations for Gavi-eligible markets.
- Recombinant Vaccine:Baculovirus expression systems produce purified hemagglutinin proteins without egg-adaptation mutations, enabling faster strain-changeover timelines. Demand is concentrating in Germany, Switzerland, and United Kingdom where hospital procurement associations accept premium pricing for improved antigenic match.
- Live Attenuated Vaccine:Intranasal formulations containing temperature-sensitive attenuated virus strains, restricted to non-pregnant populations aged 2-49 years.
- Cell-Based Vaccine:Mammalian cell culture production eliminates egg supply dependencies, with CSL Seqirus and domestic Chinese manufacturers scaling capacity.
- Adjuvanted Vaccine:MF59 or AS03 formulations enhance immunogenicity in older adults, commanding per-dose premiums in Japan and Italy.
Mature deployment sits with inactivated vaccines across mass immunization programs. Newer deployment is concentrated in recombinant and cell-based platforms where supply chain resilience commands procurement priority.
Application:
Pediatric mandates generate predictable volume, while geriatric applications sustain margin through enhanced formulation requirements.
- Pediatric Vaccination:School-based immunization programs in US states, Canadian provinces, and Australian territories generate multi-year procurement contracts with standardized dosing schedules. Demand is concentrating in California, Ontario, and New South Wales where state-level mandates expand age-eligible populations annually.
- Geriatric Immunization:Adults aged 65+ require higher antigen dose or adjuvanted formulations to overcome immunosenescence, with reimbursement rates exceeding standard adult vaccines. Demand concentrates in Japan, Germany, and Florida where aging demographics and Medicare Advantage plan structures align.
- Pregnant Women:Maternal immunization programs in United Kingdom, Australia, and Brazil prioritize second-trimester administration for transplacental antibody transfer.
- Immunocompromised Patients:Inactivated formulations predominate for oncology and transplant populations under specialist supervision in tertiary hospitals.
- Healthcare Workers:Occupational health mandates in National Health Service trusts and US hospital systems drive institutional procurement.
Pediatric applications anchor volume procurement through government tenders. Geriatric immunization is expanding most quickly as national programs lower age thresholds for enhanced formulations.
Distribution Channel:
Channel selection determines patient access friction and reimbursement pathway complexity.
- Hospital Pharmacies:Integrated delivery networks in United States and German hospital associations consolidate purchasing through group purchasing organizations, unbundling product from administration services.
- Retail Pharmacies:CVS, Walgreens, and Boots capture immunization administration from primary care, reshaping United States and United Kingdom access patterns with same-day availability.
- Government Immunization Programs:Centralized procurement in India, Brazil, and Mexico distributes through public health clinics with price-controlled tenders.
- Private Clinics:Occupational health providers and travel medicine specialists serve corporate clients and pre-travel populations in Singapore and United Arab Emirates.
- Online Pharmacies:Appointment scheduling and home delivery emerging in South Korea and Netherlands with cold-chain logistics partnerships.
Hospital pharmacies retain institutional contract concentration. Retail pharmacy channels are gaining share fastest as scope-of-practice expansions enable pharmacist administration.
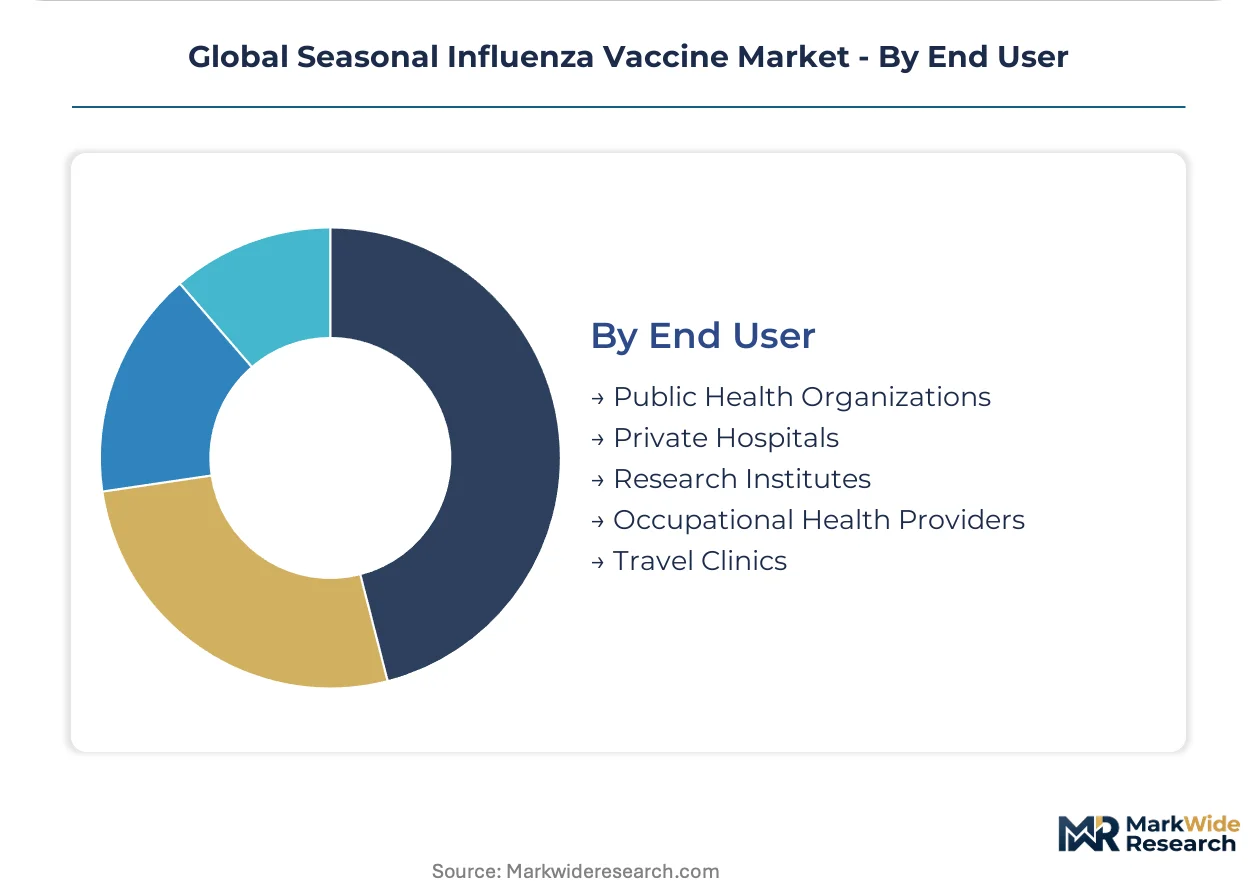
End User:
Procurement sophistication varies sharply between public health systems and private provider networks.
- Public Health Organizations:CDC, Public Health England, and state health departments in India execute centralized tenders with multi-year volume commitments and stringent cold-chain requirements.
- Private Hospitals:US Medicare Advantage networks and German private hospital chains negotiate formulary placement with price transparency mandates.
- Research Institutes:Phase III trial sponsors and immunogenicity study coordinators in academic medical centers.
- Occupational Health Providers:Corporate wellness vendors serving manufacturing and logistics workforces in Mexico and Poland.
- Travel Clinics:Specialist providers in London, Dubai, and Bangkok serving pre-departure populations with Southern Hemisphere formulation access.
Public health organizations anchor procurement volume through national immunization programs. Private hospitals represent the steepest expansion trajectory as integrated networks consolidate purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swiftwater, Pennsylvania anchors the world's largest egg-based influenza vaccine manufacturing corridor, with production clusters extending through North Carolina and into the European agricultural belts of Limburg and the Cotswolds.
United States
Pediatric mandate proliferation across California, New York, and Texas drives predictable procurement volumes through school-based programs. FDA lot-release protocols and CDC strain selection timelines compress manufacturing windows, forcing suppliers to maintain parallel formulation development. The Southeast poultry belt supplies embryonated eggs to Swiftwater and Holly Springs facilities, creating geographic concentration of pathogen-free substrate production.
Germany
Geriatric immunization programs in Bavaria and North Rhine-Westphalia prioritize adjuvanted formulations for adults aged 60 and above. EMA centralized batch testing at OMCL laboratories extends release timelines, though German hospital procurement associations accept premium pricing for improved strain-match precision. The Marburg biopharma corridor hosts cell-based manufacturing investments displacing legacy egg-dependent capacity.
China
NMPA accelerated review pathways reduced approval timelines for cell-based submissions, enabling domestic manufacturers to capture provincial tender volumes. The Yangtze River Delta concentration of biopharma facilities in Shanghai and Suzhou scales mammalian cell culture production. Beijing-Tianjin-Hebei immunization infrastructure expansion targets general adult populations beyond historical high-risk group focus.
India
The Ministry of Health and Family Welfare expands seasonal influenza coverage from high-risk groups to general adult populations, creating procurement volume expansion through public health clinics. CDSCO aligns domestic approval pathways with WHO recommendations while imposing localized stability requirements. Pune and Hyderabad manufacturing clusters supply recombinant and inactivated formulations to Gavi-eligible markets through prequalification pathways.
United Kingdom
NHS England maternal immunization programs prioritize second-trimester administration for transplacental antibody transfer, with procurement concentrated through Public Health England centralized tenders. Community pharmacy scope-of-practice expansions enable Boots and independent chains to capture immunization administration from primary care. The Liverpool vaccine manufacturing zone supports fill-finish capacity for multidose vial distribution.
Global Seasonal Influenza Vaccine Market Competitive Landscape
The competitive structure tilts toward diversified platform operators with egg-based, cell-based, and recombinant manufacturing capabilities. Consolidation pressure concentrates procurement authority through group purchasing organizations and national immunization programs, reducing vendor counts in major tenders. Three archetypes dominate: legacy egg-based manufacturers defending scale positions, cell-based specialists capturing premium procurement specifications, and recombinant platform operators exploiting strain-adaptation velocity. Competitive moves center on manufacturing modality diversification and geographic joint ventures to secure local market access.
Among diversified multinational vaccine manufacturers, Sanofi Pasteur, GlaxoSmithKline, and CSL Seqirus occupy positions spanning multiple technology platforms and procurement channels. Sanofi Pasteur exemplifies the legacy-integrated archetype with established egg-based infrastructure supplemented by recombinant capabilities. GlaxoSmithKline represents adjuvanted formulation specialization targeting geriatric premium segments. CSL Seqirus anchors the cell-based manufacturing transition, with proprietary production technology displacing substrate-dependent alternatives in tender specifications. Serum Institute of India and Bharat Biotech sit within the emerging-market supply archetype, leveraging WHO prequalification and domestic regulatory tailwinds to capture volume growth in Gavi-eligible and provincial procurement markets.
| Leading Market Players |
|---|
| AstraZeneca |
| Mylan/Viatris |
| Sanofi Pasteur |
| Bharat Biotech |
| Serum Institute of India |
| CSL Seqirus |
| Novartis |
| Medimmune |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Squalene derived from shark liver oil feeds into MF59 and AS03 adjuvant formulations, cascading through three-tier pricing structures that separate premium geriatric doses from standard adult vaccines and economy pediatric tenders across European and Asian procurement systems.
Pricing Analysis
Value-based pricing anchors on immunogenicity outcomes in older adult populations, with adjuvanted formulations commanding premiums over standard doses in Japan and Italy. Three-tier pricing structure across premium, standard, and economy levels reflects strain-match precision, manufacturing substrate, and bundled cold-chain service tiers. Cost compression in economy pediatric tenders is intensifying because WHO prequalification pathways prioritize cost containment over antigenic fidelity. Public health organizations in Gavi-eligible markets exhibit highest price sensitivity, while German hospital procurement associations accept premiums for improved strain-match precision.
Supply Chain Analysis
Single-source vulnerability sits with specialist poultry farms in the US Southeast controlling pathogen-free embryonated egg supply for egg-based manufacturing platforms. Manufacturing concentration spans the United States, China, and India, with fill-finish capacity anchored in Switzerland and Singapore for regional tender markets. Raw material dependencies encompass embryonated eggs, squalene adjuvants, and mammalian cell culture media. Tariff exposure on imported adjuvant inputs threatens formulation economics. Distribution runs through government immunization programs, retail pharmacy chains, and hospital group purchasing organizations with divergent cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fill-finish capacity constraints prop pricing power for manufacturers with sterile multidose vial and prefilled syringe capabilities, as national procurement agencies compete for limited manufacturing slots during compressed strain-selection windows.
For Market Incumbents: To counter mRNA platform entrants compressing traditional development cycles, incumbent manufacturers should accelerate cell-based manufacturing investments in the Marburg biopharma corridor and secure backward integration into pathogen-free egg supply through captive poultry farm partnerships. Certification investment in NMPA accelerated review pathways protects market access in China's provincial tender expansion. For New Entrants and Emerging Players: Direct-to-pharmacy digital scheduling platforms offer the lowest-friction route into immunization administration markets, bypassing entrenched hospital procurement networks. White-space targets include online pharmacy appointment systems in South Korea and Netherlands, plus regional fill-finish contracting for mid-size biopharma in Switzerland. Community pharmacy scope-of-practice expansions in the United Kingdom present the most penetrable channel for platform entrants without established tender relationships. For Investors and Strategic Acquirers: WHO prequalification expansion announcements are the leading indicator that procurement volume will concentrate in Gavi-eligible markets, signaling acquisition timing for emerging-market supply archetypes. Long-term viability over the next decade rests on manufacturing modality diversification across egg-based, cell-based, and recombinant platforms. Target acquisition profiles center on cell-based specialists with proprietary production technology and established provincial tender relationships in China and India.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Based Manufacturing Scale-Up | CSL Seqirus and domestic Chinese manufacturers expand mammalian cell culture capacity to displace egg-dependent supply. |
| Regulatory Approval Pathway Investment | NMPA accelerated review timelines reduce approval windows from 18 months to 9 months for novel platform submissions. |
| Backward Integration into Adjuvant Supply | Shark liver oil sourcing constraints force manufacturers to secure captive squalene supply for MF59 formulation stability. |
| Pharmacy Channel Partnership | CVS, Walgreens, and Boots capture immunization administration from primary care with same-day availability expansion. |
| Geographic Manufacturing Joint Venture | Multinational suppliers establish local production in Yangtze River Delta to meet NMPA localization requirements for tender access. |
Research Methodology
Independent corroboration across regulatory affairs leads at EMA and FDA, formulary directors at German hospital procurement associations, and manufacturing executives at cell-based production facilities underwrites the qualitative findings in this study. Primary interviews with vaccine development executives, national immunization program managers, and GPO contracts managers combined with secondary validation from FDA lot-release databases, WHO prequalification listings, EMA centralized batch testing records, and provincial tender documents in China and India. Bottom-up demand modeling across pediatric mandate states and top-down supply capacity assessments triangulate volume estimates.
Comparable historical periods spanning pre-pandemic, pandemic surge, and post-pandemic normalization phases anchored the forecast window across the analysis window. The analytical framework models segmentation across vaccine type, application population, distribution channel, and regional regulatory cluster. CAGRs derive from exponential growth curve fitting against historical procurement volumes. Industry-specific forecast inputs include strain-selection timeline compression effects and fill-finish capacity utilization rates at sterile manufacturing suites.
Inputs from EMA OMCL batch testing records and WHO prequalification pathway documentation were available through the study window; gaps in real-time provincial tender award data from China introduce uncertainty bands around market share projections. Deviation in avian influenza outbreak severity affecting pathogen-free egg supply would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Drug-Induced Immune Hemolytic Anemia Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Plasma Protein System Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Oseltamivir Market