
 Bioequivalence Studies Market | 2026-2036
Bioequivalence Studies Market Size, Share, and Industry Trends Forecast 2026-2036
Bioequivalence Studies Market Intelligence
Good manufacturing practice certification upgrades are reorganizing competitive dynamics among contract research organizations serving generic drug developers. IQVIA leverages its integrated clinical and commercial data infrastructure to anchor large-scale bioequivalence programs across multiple geographies. Charles River Laboratories sustains specialized laboratory capacity for complex formulation analytics. Veeda Clinical Research dominates early-phase volunteer recruitment and bioanalytical execution in South Asia.
Bioequivalence studies are controlled clinical trials that measure the rate and extent of active pharmaceutical ingredient absorption from a test formulation against a reference listed drug, typically requiring 24-48 hour pharmacokinetic blood sampling profiles with bioanalytical validation at lower limits of quantification of 1-5 ng/mL. Their primary purpose is to demonstrate therapeutic equivalence for abbreviated regulatory approvals, enabling generic substitution without repeating full clinical efficacy trials. Pharmacokinetic studies lead volume demand due to universal regulatory acceptance across FDA, EMA, and WHO pathways, while clinical endpoint studies command premium pricing for locally acting products where plasma levels prove insufficient. Oncology and neurology therapeutic areas are expanding fastest as complex generic pipelines target high-value specialty medicines with narrow therapeutic indices.
FDA bioequivalence guidance, EMA reflection papers, and WHO prequalification standards collectively shape study design requirements, analytical method stringency, and inspection readiness for contract research organizations worldwide. India's CDSCO and the US FDA conduct mutual recognition assessments that determine which bioequivalence data packages transfer across jurisdictions. Stakeholders must monitor evolving guidance on immunogenicity, adaptive trial designs, and biowaivers as regulators refine equivalence criteria for biosimilars and complex generics.
Market Dynamics
Pharmacokinetic sampling automation is compressing study timelines and forcing contract research organizations to restructure their bioanalytical laboratory footprints to maintain throughput margins.
Growth Catalysts
- CDSCO abbreviated approval pathways:India's streamlined generic drug review processes accelerate sponsor timelines for multinational pharmaceutical companies seeking dual US-India filings.
- Complex generic injectables:High-value parenteral formulations require specialized bioequivalence designs with extended sampling windows, expanding serviceable addressable market for advanced CRO capabilities.
- WHO prequalification standards:Emerging market access requirements for essential medicines drive demand for internationally compliant study documentation and inspection-ready quality systems.
Market Restraints
- Reference listed drug sourcing:Supply chain concentration for originator comparator products in North America creates procurement bottlenecks and pricing volatility for study sponsors.
- Skilled bioanalytical chemist scarcity:Specialized LC-MS/MS method development expertise concentrates in established pharmaceutical clusters, constraining laboratory expansion in secondary markets.
- FDA immunogenicity guidance evolution:Uncertainty around biosimilar equivalence criteria for protein products extends protocol development timelines and increases regulatory risk for development programs.
Strategic Opportunities
- Brazil's ANVISA harmonization:Alignment with ICH bioequivalence guidelines creates transferable data packages for Latin American market access without redundant clinical work.
- Adaptive trial designs:Bayesian pharmacokinetic modeling enables real-time sample size adjustment, reducing volunteer recruitment burden and accelerating database lock.
- Ophthalmic local delivery:Clinical endpoint studies for topical formulations command premium pricing where traditional plasma-based bioequivalence proves insufficient.
Industry Challenges
- Volunteer recruitment saturation:Healthy subject pool depletion in high-volume Indian metropolitan centers extends screening timelines and inflates per-subject costs.
- Legacy bioanalytical platform migration:Transitioning from triple quadrupole to high-resolution mass spectrometry demands capital-intensive equipment upgrades and revalidation of established methods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioequivalence Studies Market |
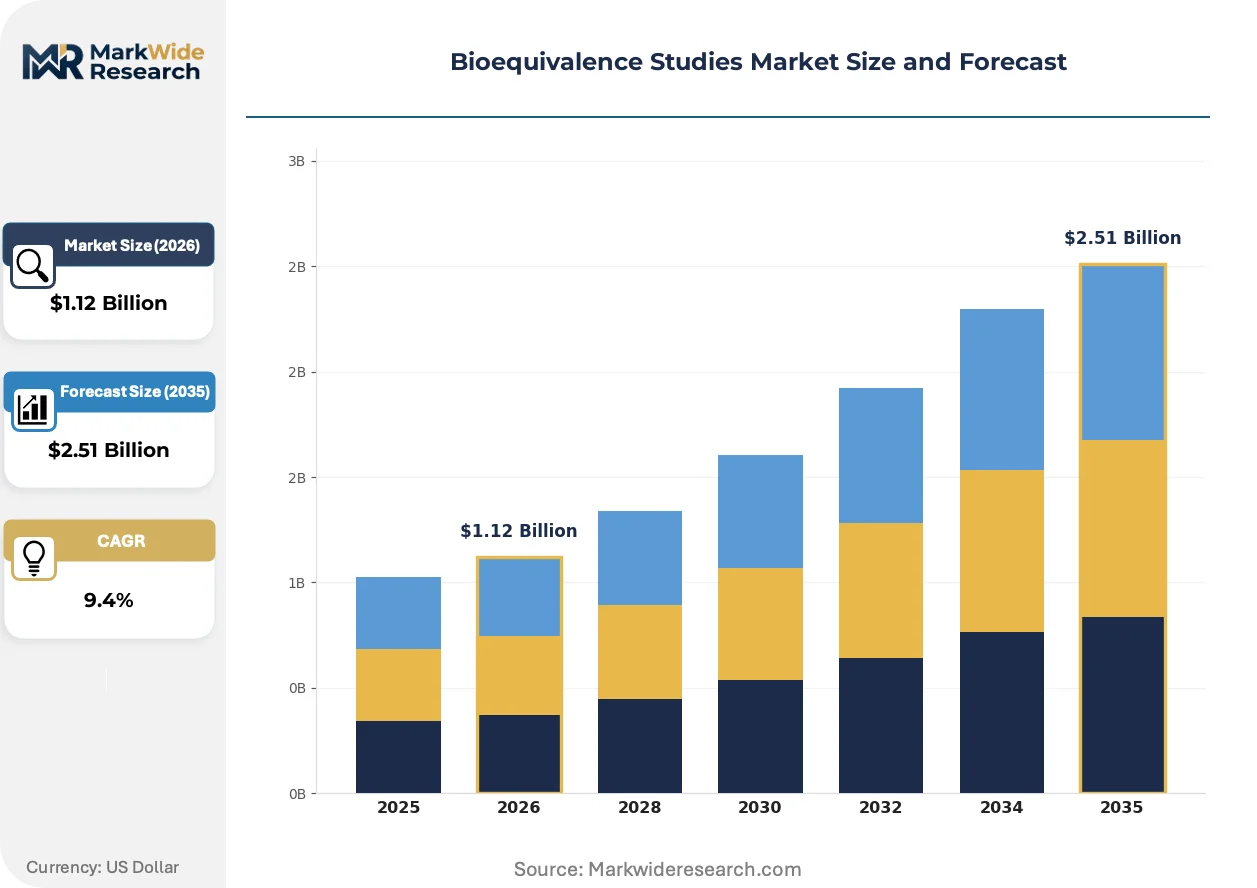
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Study Type: Single Dose, Multiple Dose, Pharmacokinetic, Clinical Therapeutic Area: Cardiovascular, Oncology, Neurology, Infectious Diseases Regulatory Agency: FDA, EMA, WHO, TGA Formulation Type: Tablet, Capsule, Injectable, Oral Solution |
| Companies Covered | ICON plc, ProRelix Services LLP, IQVIA, Synova Health, KYMOS Group, Charles River Laboratories, Veeda Clinical Research, CliniExperts, Labcorp Drug Development, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioequivalence Studies Market Strategic Shifts & Innovations
Digital biomarker integration and decentralized clinical trial infrastructure are reconfiguring how pharmacokinetic data is captured, shifting competitive advantage toward technology-enabled CRO platforms.
Microsampling devices using volumetric absorptive matrices are decomposing traditional venous blood collection protocols. Generic sponsors in oncology therapeutic areas are adopting capillary sampling for pediatric and geriatric populations where serial draws prove prohibitive. This technology is decomposing the 24-hour inpatient confinement model that has dominated bioequivalence execution for three decades.
EMA reflection papers on bioanalytical method validation are tightening acceptance criteria for incurred sample reproducibility. European contract laboratories are investing in automated sample handling systems to reduce human error in high-throughput environments. Complex generic developers targeting EMA centralized procedures face heightened scrutiny on chromatographic peak integration consistency.
Sponsor procurement teams are consolidating bioequivalence vendor rosters to capture volume discounts and simplify audit burden. Mid-size generic manufacturers are displacing fragmented regional CRO relationships with preferred provider agreements spanning multiple study phases. This concentration is most visible among US-based sponsors outsourcing to Indian full-service organizations with integrated bioanalytical and clinical capabilities.
Bioequivalence Studies Market Segmentation
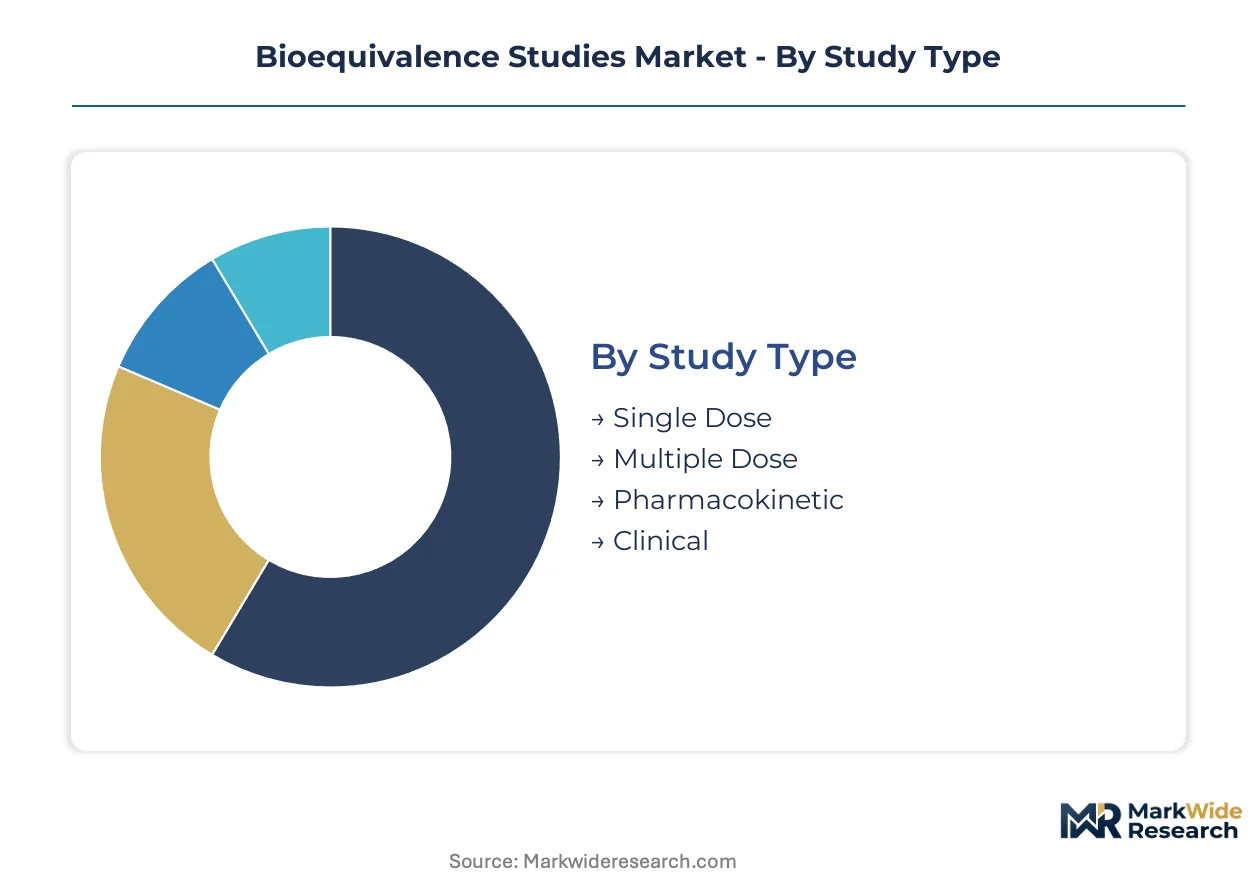
Segmentation in bioequivalence studies determines protocol complexity, regulatory pathway selection, and pricing structures for contract research organizations. Study design choices cascade through volunteer recruitment requirements, bioanalytical method validation scope, and inspection readiness preparation.
Study Type:
FDA, EMA, and WHO guidance documents prescribe distinct sampling schedules and statistical criteria for each study design category.
- Pharmacokinetic:Blood concentration-time profiles with 24-48 hour sampling windows constitute the regulatory standard for systemic absorption demonstration. FDA and EMA accept these studies universally for orally administered products, concentrating demand among generic tablet and capsule developers seeking abbreviated approvals.
- Clinical:Comparative clinical endpoint trials substitute for pharmacokinetic approaches where plasma levels fail to predict therapeutic effect, such as locally acting inhalers or topical dermatological products. Complex generic sponsors in ophthalmic and nasal delivery segments drive premium pricing for these specialized designs.
- Single Dose:One-time administration with washout periods dominates bioequivalence execution for immediate-release formulations.
- Multiple Dose:Steady-state assessment protocols apply to extended-release products and drugs with nonlinear pharmacokinetics.
Established volume favors Pharmacokinetic studies; emerging adoption favors Clinical designs.
Therapeutic Area:
Patient population characteristics and safety monitoring intensity differentiate cost structures across therapeutic segments.
- Oncology:Narrow therapeutic indices for cytotoxic agents demand expanded sampling protocols and specialized bioanalytical sensitivity. CDSCO and FDA reviewers impose stringent equivalence margins for anticancer generics, extending study timelines and expanding addressable service revenue for specialized CROs.
- Neurology:Central nervous system penetrant drugs require cerebrospinal fluid sampling or specialized population pharmacokinetic modeling. Generic developers targeting antiepileptic and antipsychotic markets invest in adaptive trial designs to manage recruitment challenges for controlled-substance protocols.
- Cardiovascular:Large volunteer pools and established reference standards streamline execution for antihypertensive and anticoagulant generics.
- Infectious Diseases:Antiretroviral and antibiotic bioequivalence supports WHO prequalification programs for emerging market access.
Cardiovascular studies deliver volume scale; Neurology applications command margin premiums.
Regulatory Agency:
Jurisdiction-specific documentation standards and inspection protocols shape CRO capability investments.
- FDA:Abbreviated New Drug Application requirements encompass bioanalytical method validation, clinical protocol adherence, and current Good Manufacturing Practice compliance for reference product handling. US-based sponsors and Indian exporters targeting the American market prioritize FDA inspection history in vendor selection.
- EMA:Centralized procedure submissions demand adherence to reflection papers on bioanalytical method validation and incurred sample reproducibility. European contract laboratories invest in automated sample handling to meet tightened chromatographic peak integration scrutiny.
- WHO:Prequalification standards enable emerging market access for essential medicines through unified technical documentation.
- TGA:Australian regulatory alignment with ICH guidelines facilitates data package transferability for Asia-Pacific registrations.
FDA submissions anchor commercial scale; EMA procedures drive quality system investments.
Formulation Type:
Manufacturing complexity and analytical method development burden segment service pricing tiers.
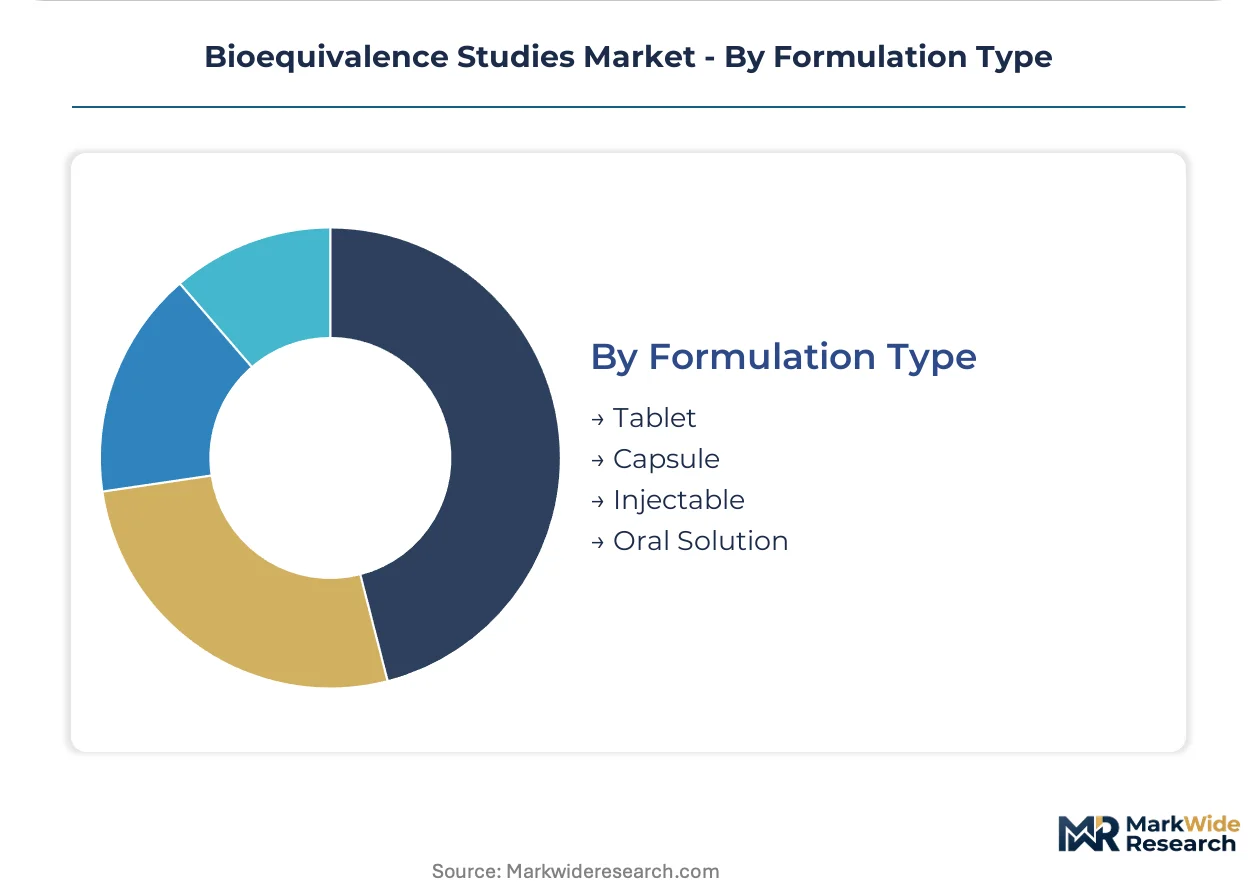
- Injectable:Parenteral formulations require sterile manufacturing demonstration, endotoxin testing integration, and specialized pharmacokinetic sampling for biologics and complex generics. High-value biosimilar developers in oncology and autoimmune therapeutic areas commission extended sampling windows and immunogenicity assessments.
- Capsule:Modified-release pellet technologies and lipid-based formulations demand dissolution profile matching beyond traditional bioequivalence metrics. Generic sponsors targeting niche oral delivery segments invest in physiologically based pharmacokinetic modeling to justify biowaivers.
- Tablet:Immediate-release solid oral dosage forms constitute the execution volume base for high-throughput CRO operations.
- Oral Solution:Liquid formulations for pediatric and geriatric populations require taste-masking and stability validation alongside pharmacokinetic assessment.
Tablet studies concentrate execution volume; Injectable formats expand fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research organizations cluster where generic drug sponsors concentrate regulatory submissions and where volunteer recruitment pools scale efficiently. India and the United States anchor execution volume, while European laboratories specialize in complex formulation analytics for EMA centralized procedures.
United States
FDA abbreviated new drug applications drive sponsor demand for inspection-ready bioanalytical capacity. The agency's bioequivalence guidance on immunogenicity and adaptive designs shapes protocol development timelines. Greater Boston and Research Triangle Park host specialized CROs serving oncology and neurology generic developers.
India
CDSCO streamlined approval pathways attract multinational sponsors seeking dual US-India filing strategies. The regulator's mutual recognition assessments with FDA determine data package transferability. Ahmedabad and Hyderabad dominate volunteer recruitment and bioanalytical execution for high-throughput pharmacokinetic studies.
Germany
EMA reflection papers on bioanalytical method validation tighten chromatographic scrutiny for centralized procedure submissions. The country's national pharmaceutical regulator enforces incurred sample reproducibility standards. Munich and Berlin laboratories invest in automated sample handling for complex generic developers.
Switzerland
Swissmedic alignment with ICH guidelines facilitates data package acceptance across European and emerging markets. The regulator's inspection protocols emphasize current Good Manufacturing Practice compliance for reference product handling. Basel anchors bioanalytical specialization for narrow therapeutic index formulations.
Brazil
ANVISA harmonization with ICH bioequivalence guidelines creates transferable data pathways for Latin American market access. The regulator's abbreviated approval processes reduce redundant clinical work for regional generic sponsors. São Paulo concentrates contract laboratory capacity serving multinational pharmaceutical exporters.
Bioequivalence Studies Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the bioequivalence services market. Integrated clinical research organizations with end-to-end capabilities command premium positioning for complex generic programs, while specialized bioanalytical laboratories compete on throughput and price efficiency for standard pharmacokinetic studies. Three archetypes dominate: full-service global CROs, regional execution specialists with integrated bioanalytical capacity, and niche method development laboratories. Consolidation through strategic acquisitions and preferred provider agreement expansion represent the primary competitive vectors reshaping vendor relationships.
Among full-service global CROs, IQVIA leverages integrated clinical and commercial data infrastructure across multiple geographies, while Charles River Laboratories sustains specialized laboratory capacity for complex formulation analytics. Veeda Clinical Research exemplifies the regional execution specialist archetype, dominating early-phase volunteer recruitment and bioanalytical execution in South Asia.
| Leading Market Players |
|---|
| ICON plc |
| ProRelix Services LLP |
| IQVIA |
| Synova Health |
| KYMOS Group |
| Charles River Laboratories |
| Veeda Clinical Research |
| CliniExperts |
| Labcorp Drug Development |
| Others |
Cost & Logistics Intelligence
High-throughput bioanalytical capacity utilization in Indian metropolitan clusters compresses per-study cost floors while concentrating pricing power among full-service contract research organizations with integrated clinical and laboratory infrastructure. This scale dynamic simultaneously depresses margins for standalone bioanalytical laboratories and elevates premium capture for specialized providers serving complex generic injectables and ophthalmic segments.
Pricing Analysis
FDA bioequivalence guidance dictates the pricing tier structure across pharmacokinetic and clinical endpoint study designs. Three-tier pricing structure across premium, standard, and economy levels separates complex formulation analytics from high-volume tablet studies and commodity bioanalytical services. Cost compression in standard pharmacokinetic execution is intensifying because volunteer recruitment saturation in Ahmedabad and Hyderabad inflates per-subject costs. Mid-size generic manufacturers exhibit highest price sensitivity, while multinational sponsors prioritize FDA inspection history over marginal cost savings.
Supply Chain Analysis
Reference listed drug inventory lead times from North American originator manufacturers routinely extend study initiation timelines by 8-16 weeks. Supply concentrates in the United States, India, and Germany for comparator product sourcing, bioanalytical reagents, and specialized LC-MS/MS equipment respectively. The supply chain draws from single-source vulnerability for certified reference standards and immunogenicity assay kits. Distribution runs through sponsor-procurement teams consolidating vendor rosters into preferred provider agreements with integrated Indian full-service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioequivalence services market is recovering from pandemic-induced study delays as sponsor pipelines refill with complex generic submissions targeting FDA abbreviated new drug application pathways.
For Market Incumbents: Shield specialized laboratory capacity in complex formulation analytics from price erosion by embedding method development scientists directly into sponsor regulatory strategy teams. Anchor inspection-ready quality systems as the priority lever against emerging mid-size CROs lacking FDA establishment inspection history. Defend against volunteer recruitment saturation by securing exclusive site agreements with high-volume Indian clinical pharmacology units. For New Entrants and Emerging Players: Anchor in ophthalmic and nasal delivery clinical endpoint studies where plasma-based bioequivalence proves insufficient and incumbent capacity concentrates in legacy pharmacokinetic execution. Brazil's ANVISA harmonization with ICH guidelines creates the most penetrable geography for transferable data packages without redundant clinical work. Pursue white-label bioanalytical partnerships with established Indian CROs to bypass capital-intensive LC-MS/MS platform investments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional execution specialists with integrated bioanalytical and clinical capabilities serving multinational sponsor preferred provider agreements. Long-term viability across the projection horizon hinges on adaptive trial design technology adoption and microsampling device integration. Monitor FDA immunogenicity guidance evolution as the primary signal for biosimilar equivalence criteria stabilization.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Design Adoption | Bayesian pharmacokinetic modeling reduces volunteer recruitment burden and accelerates database lock timelines. |
| Microsampling Technology Integration | Volumetric absorptive matrices decompose traditional 24-hour inpatient confinement models for pediatric populations. |
| Preferred Provider Agreement Expansion | Consolidated vendor rosters capture volume discounts and simplify audit burden for sponsor procurement teams. |
| Complex Generic Capability Buildout | Specialized capacity for injectables and ophthalmic products commands premium pricing in narrow therapeutic index segments. |
| CDSCO-FDA Mutual Recognition Leverage | Dual filing strategies accelerate sponsor timelines through streamlined Indian abbreviated approval pathways. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bioanalytical laboratory directors, regulatory affairs leads at generic pharmaceutical sponsors, clinical pharmacology unit managers, and CDSCO inspection readiness consultants. Secondary validation drew from FDA bioequivalence guidance documents, EMA reflection papers on method validation, WHO prequalification standards, ClinicalTrials.gov protocol registrations, and CDSCO abbreviated approval pathway circulars. Bottom-up study volume estimates triangulated against top-down CRO revenue segmentation across the analysis window.
Across the modeling period, forecast outputs reflect segment-level CAGRs derived from sponsor pipeline analysis by therapeutic area and formulation complexity. Segmentation dimensions include study type, therapeutic area, regulatory agency jurisdiction, and formulation type. Study volume projections incorporated generic drug approval trends, reference listed drug patent expiry schedules, and emerging market access requirements for WHO prequalification.
Decision-makers should treat outputs as directional under assumptions of stable FDA-CDSCO mutual recognition and continued complex generic pipeline expansion; material deviation in immunogenicity guidance or reference product sourcing disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Biologic Response Modifiers Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Targeted Protein Degradation Market