
 Norethisterone Enanthate API Market | 2026-2036
Norethisterone Enanthate API Market Size, Share, and Industry Trends Forecast 2026-2036
Norethisterone Enanthate API Market Insights
Project finance for dedicated steroid hormone manufacturing facilities is rewriting competitive entry thresholds in norethisterone enanthate API production. Bayer AG leverages backward integration into key starting material synthesis to protect margin structures. Symbiotec Pharmalab anchors its position through specialized hormone API manufacturing infrastructure in India. Zhejiang Xianju Pharmaceutical Co., Ltd. dominates bulk volume supply through scaled fermentation and chemical conversion capabilities.
Norethisterone enanthate is a synthetic progestin ester formulated as an intramuscular injectable with a typical duration of action extending eight to twelve weeks, manufactured through multi-step organic synthesis from estrone or diosgenin precursors. The application dimension shows hormonal contraception commanding the largest volume share while cancer treatment applications sustain premium pricing due to smaller batch requirements and tighter purity specifications. Bulk packaging formats occupy the production-weighted center of gravity, though vial and ampoule presentations capture higher unit economics through closer integration with finished dosage form operations.
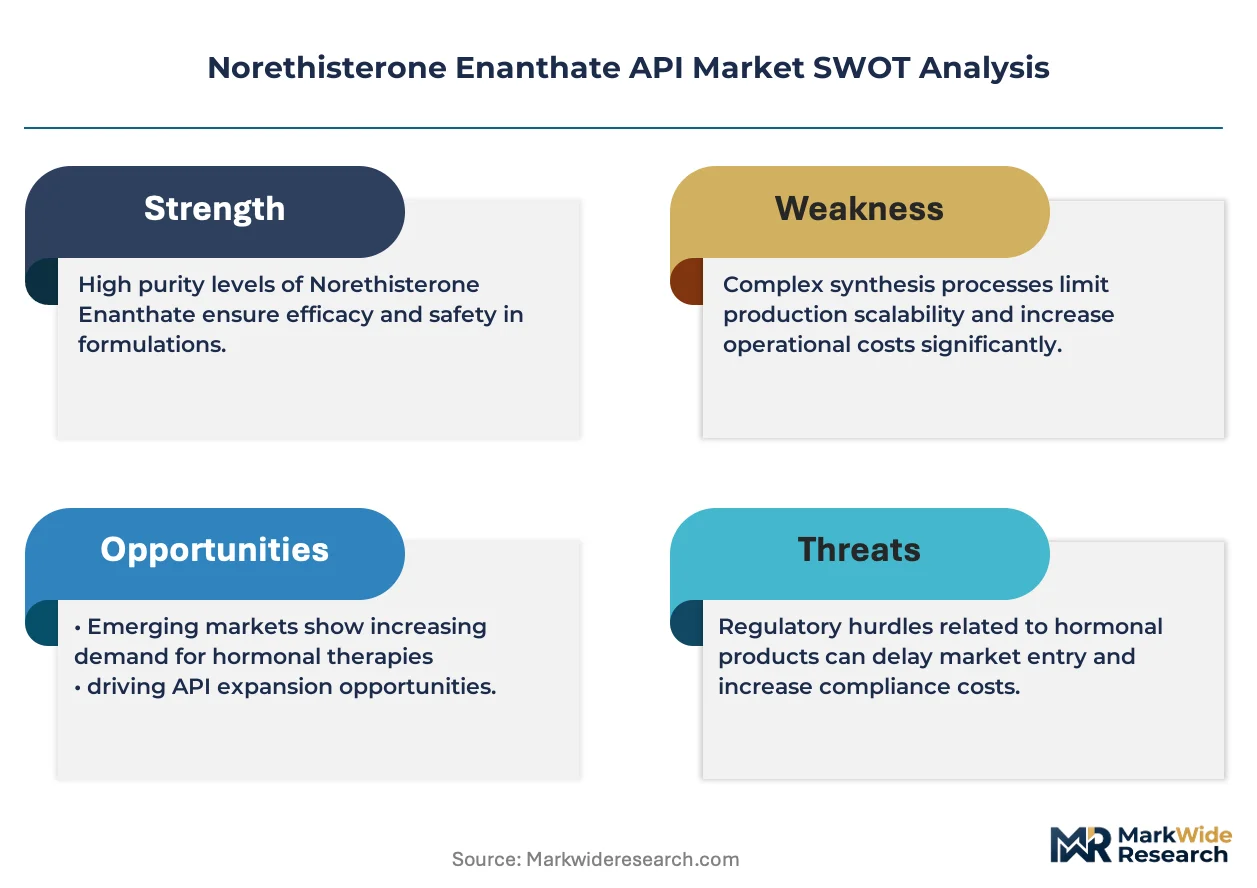
The US FDA and EMA enforce stringent ICH Q7 guidelines for API manufacturing, with India's CDSCO aligning domestic good manufacturing practice standards to facilitate export market access. China's NMPA maintains separate registration pathways for hormone APIs that limit market entry velocity for non-domestic producers. Stakeholders must monitor evolving environmental compliance costs around steroid synthesis waste streams as regulatory scrutiny intensifies across manufacturing jurisdictions.
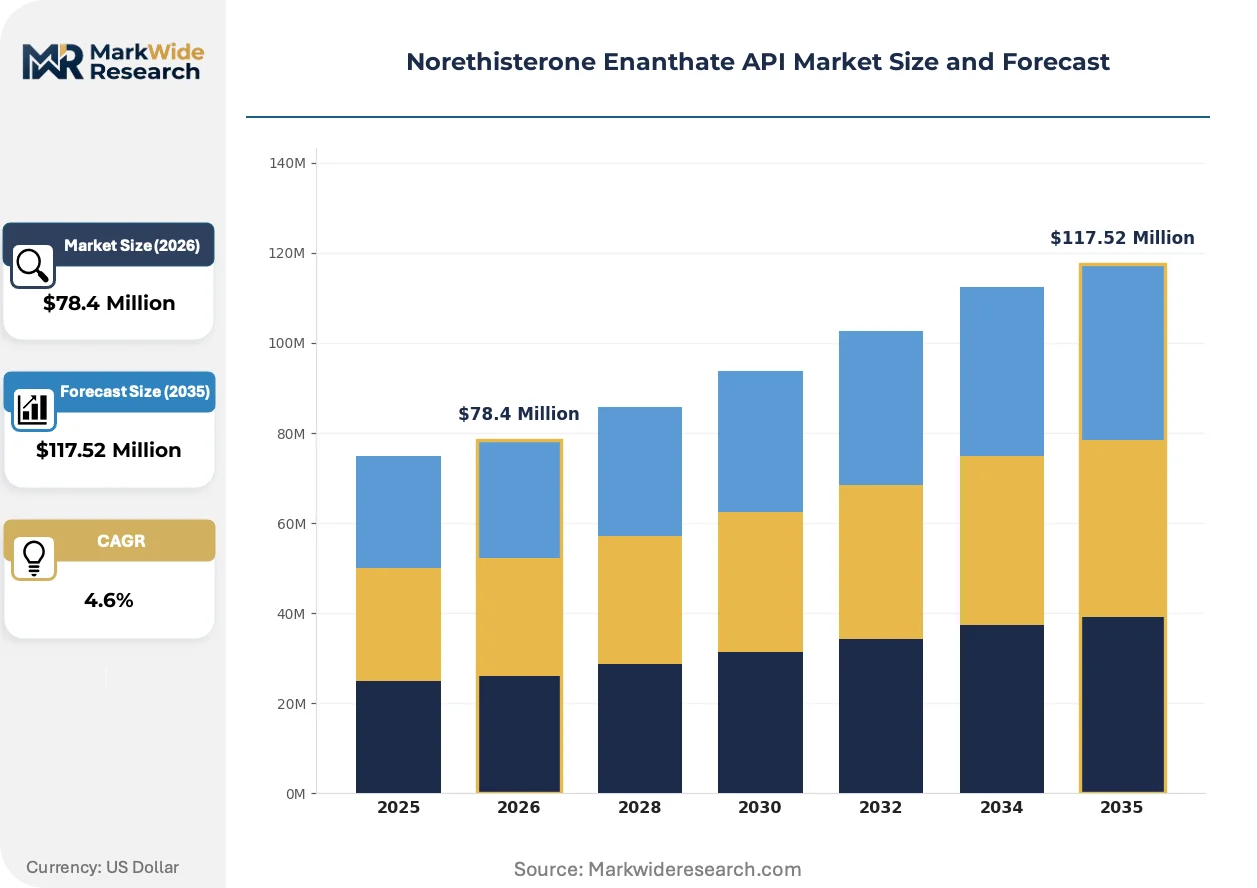
Market Dynamics
Contract manufacturing concentration is restructuring competitive access to norethisterone enanthate API supply, as public health procurement programs consolidate volume commitments among fewer qualified steroid hormone manufacturers capable of meeting ICH Q7 compliance.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredients are lowering capital recovery timelines for domestic hormone synthesis facilities. Domestic manufacturers are expanding fermentation capacity to capture export contract volumes.
- Injectable contraceptive programs:UNFPA and national family planning initiatives in sub-Saharan Africa and South Asia are generating predictable offtake agreements for long-acting progestin esters. These programs favor suppliers with WHO prequalification status.
- Biocatalytic conversion:Engineered enzyme platforms for steroid backbone modification are reducing solvent waste and yield loss in diosgenin-to-progestin synthesis. Early adopters are achieving cost parity with traditional chemical routes at commercial scale.
Market Restraints
- Starting material concentration:Diosgenin supply depends on Mexican yam cultivation and Chinese diosgenin extraction infrastructure. Weather volatility and agricultural commodity pricing transmit directly to API cost structures.
- EMA/FDA inspection intensity:Heightened surveillance of steroid hormone manufacturing sites in India and China is extending approval timelines for new suppliers. Regulatory resource constraints are creating multi-year entry barriers.
- Oral contraceptive substitution:Daily oral progestin formulations retain preference in private-pay markets with established distribution. Injectable uptake remains concentrated in public sector channels with limited pricing power.
Strategic Opportunities
- Brazilian ANVISA alignment:Latin America's largest pharmaceutical market is harmonizing GMP standards with PIC/S guidelines. Qualified suppliers can leverage existing FDA or EMA dossiers for accelerated market entry.
- Oncology applications:Endometrial cancer and breast cancer palliative protocols are generating demand for smaller-batch, higher-purity norethisterone enanthate. These indications command pricing premiums over contraceptive grades.
- Continuous flow chemistry:Modular reactor systems for hazardous steroid intermediate synthesis are enabling distributed manufacturing footprints. Technology licensors are partnering with regional API producers to bypass centralized production economics.
Industry Challenges
- Steroid synthesis expertise scarcity:Experienced process chemists capable of managing multi-step organic transformations with chiral center control are concentrated at legacy manufacturers. Training pipelines have not kept pace with facility expansion.
- Environmental compliance capex:Wastewater treatment and solvent recovery infrastructure for steroid synthesis waste streams requires substantial capital allocation. India's Central Pollution Control Board is tightening discharge standards for hormone API clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norethisterone Enanthate API Market |
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $117.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringe, Vial, Ampoule, Bulk Application: Hormonal Contraception, Endometriosis, Cancer Treatment, Hormone Replacement End User: Pharmacies, Hospitals, Research Laboratories, Clinics Packaging Type: Plastic, Glass, Blister Packs, Others |
| Companies Covered | Bayer AG, Sanofi S.A., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Amber Lifesciences, Symbiotec Pharmalab, Coral Drugs Private Limited, Zhejiang Xianju Pharmaceutical Co., Ltd., Lupin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norethisterone Enanthate API Market Trends and Innovations
Process intensification and regulatory harmonization are compressing manufacturing economics for norethisterone enanthate, while procurement consolidation is reshaping how volume commitments translate to capacity planning.
Biocatalytic steroid modification using engineered cytochrome P450 enzymes and ketoreductases is replacing traditional chromium-mediated oxidation steps in progestin synthesis. European contract manufacturers are piloting these routes to reduce hazardous waste generation and simplify EMA environmental risk assessments. The technology is rendering obsolete legacy chemical process trains that required extensive solvent recovery infrastructure and generated chromium-containing effluent.
EMA's revised guideline on genotoxic impurities in pharmaceuticals is tightening acceptable limits for residual solvents and process-related contaminants in steroid APIs. Manufacturers are validating alternative purification sequences and investing in analytical capability upgrades. Hormone API specialists with existing mass spectrometry infrastructure are adapting fastest, while smaller producers face six-to-twelve month compliance timelines.
Public health procurement bodies are consolidating annual contraceptive tenders into multi-year framework agreements with pre-qualified suppliers. UNFPA and national family planning programs are shifting from spot purchasing to three-to-five year offtake commitments with volume guarantees. This concentration is most visible in sub-Saharan Africa, where country-level pooling mechanisms are reducing supplier count from fifteen to five per regional tender.
Norethisterone Enanthate API Market Segmentation
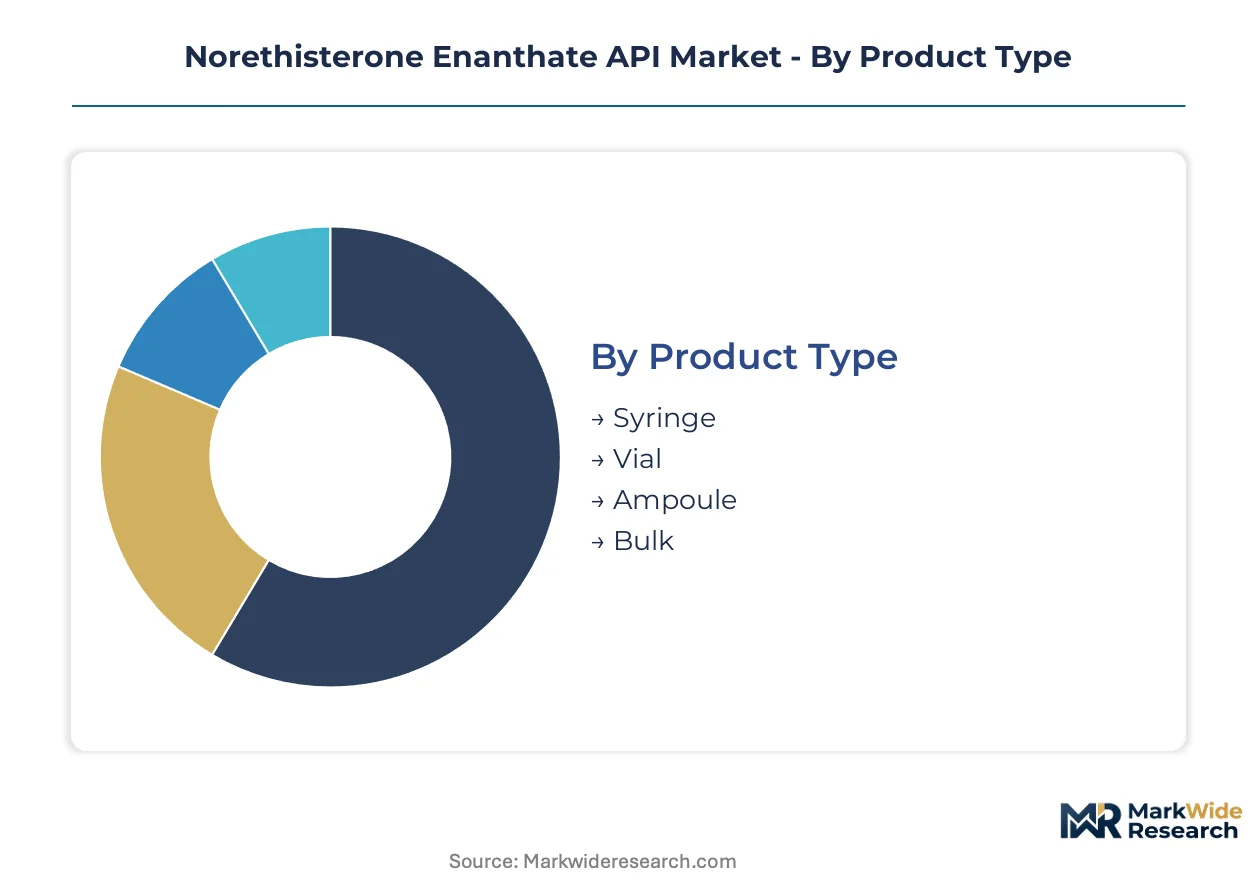
Norethisterone enanthate API demand fragments across packaging formats, therapeutic applications, and procurement channels. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape supplier priorities.
Product Type:
Volume concentration across presentation formats determines integration depth with finished dosage manufacturing.
- Bulk:Unformulated active pharmaceutical ingredient shipped in kilogram-scale containers to contract manufacturers. Public health procurement programs in sub-Saharan Africa and South Asia anchor predictable offtake volumes for qualified steroid hormone suppliers.
- Vial:Sterile solution in multi-dose glass containers requiring aseptic filling capability. European and North American formulation clients concentrate demand here, driven by CDMO integration and ICH Q7 compliance requirements.
- Syringe:Pre-filled presentation eliminating reconstitution steps at point of care. WHO prequalification status accelerates tender access for injectable contraceptive programs.
- Ampoule:Single-unit glass containment for immediate use. Hospital procurement in Latin America and Southeast Asia sustains niche volume.
Bulk commands the established base. The steepest expansion runs through vial presentations.
Application:
Therapeutic indication splits the market between high-volume contraceptive supply and precision oncology manufacturing.
- Hormonal Contraception:Intramuscular depot formulation delivering eight to twelve weeks of progestin activity. UNFPA framework agreements and national family planning initiatives in India, Nigeria, and Indonesia generate recurring multi-year tenders.
- Cancer Treatment:Palliative protocols for endometrial and breast cancer requiring tighter purity specifications and smaller batch sizes. EMA genotoxic impurity guidelines enforce premium analytical overhead.
- Endometriosis:Off-label and approved progestin suppression of ectopic tissue growth. Specialist gynecology practices in Germany, France, and Japan sustain demand.
- Hormone Replacement:Menopausal symptom management with combined estrogen-progestin regimens. Compounding pharmacies in the US and Australia capture fragmented prescription volume.
Hormonal contraception anchors volume scale. Cancer treatment delivers the steepest margin expansion.
End User:
Channel structure determines pricing power and inventory commitment patterns across the value chain.
- Hospitals:Inpatient and outpatient departments managing injectable administration directly. Government procurement bodies in Brazil, Mexico, and South Africa consolidate purchasing through national tender systems.
- Pharmacies:Retail and institutional dispensers serving prescription and over-the-counter channels. India's Jan Aushadhi generic program and similar initiatives compress margins while expanding volume access.
- Clinics:Primary care and reproductive health facilities with limited cold chain infrastructure. Sub-Saharan African public health networks favor long-acting formulations reducing visit frequency.
- Research Laboratories:Preclinical and clinical trial material supply with stringent documentation requirements. Academic medical centers in the US, UK, and Japan source through specialized chemical distributors.
Hospitals dominate institutional procurement. Clinics are climbing fastest on public program expansion.
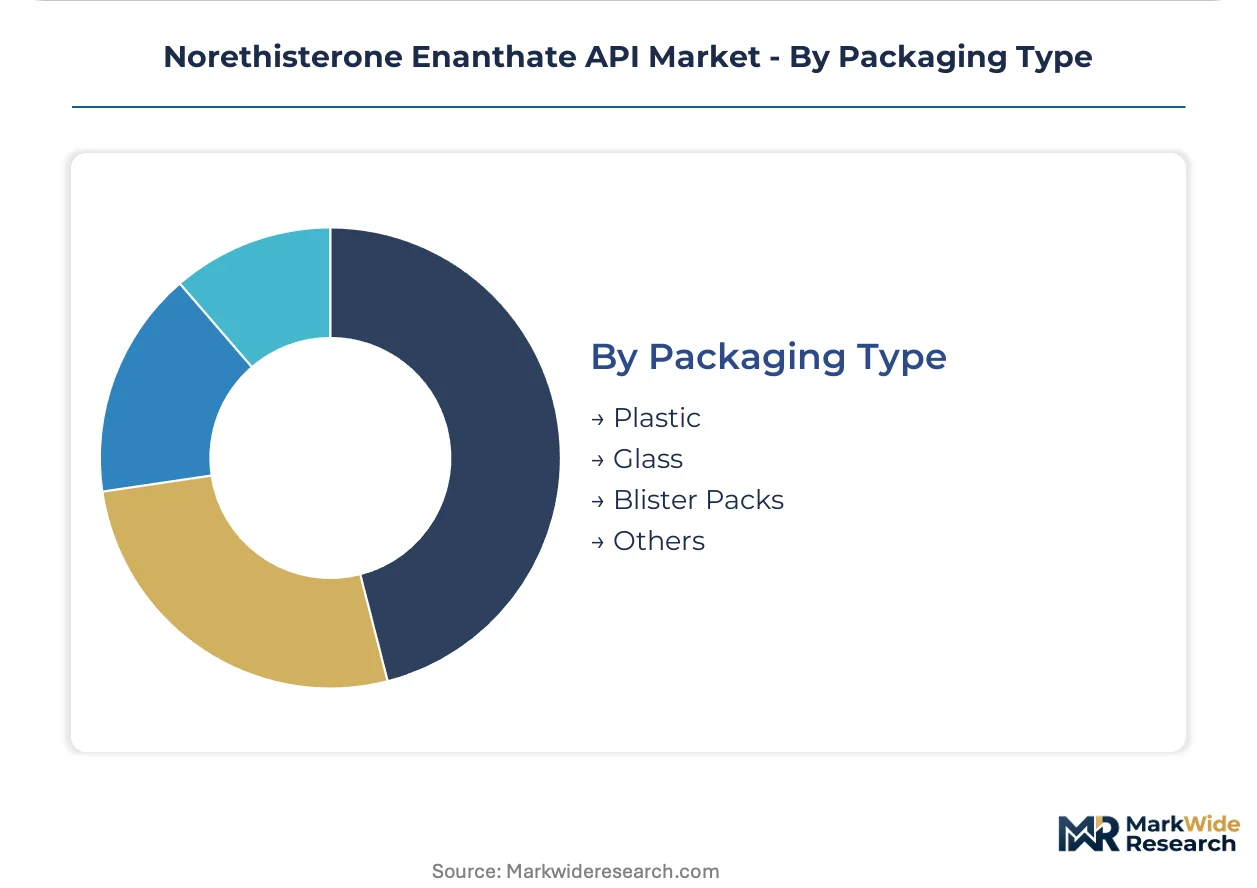
Packaging Type:
Material selection balances cost, barrier properties, and environmental compliance across distribution geographies.
- Glass:Borosilicate and treated soda-lime containers with established USP and EP compatibility. European EMA filings and US FDA drug master files reference glass primary packaging as the default standard.
- Plastic:Cyclic olefin polymer and polypropylene alternatives for weight reduction and breakage resistance. India's CDSCO is expanding acceptable plastic packaging pathways for domestic and export markets.
- Blister Packs:Unit-dose aluminum and polymer laminates for oral co-formulations. Limited relevance for injectable norethisterone enanthate but present in combination product portfolios.
- Others:Specialized containment including aluminum canisters and composite materials for temperature-sensitive logistics. Cold chain distributors in Australia and Canada pilot these formats for remote delivery.
Glass retains the specification base. Plastic formats are gaining share fastest on logistics cost pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for active pharmaceutical ingredients is redirecting capital toward domestic steroid hormone synthesis capacity. Government-backed fermentation infrastructure in Hyderabad and Ahmedabad is expanding export contract volumes. European and North American formulation clients are consolidating procurement through qualified Indian suppliers.
India
UNFPA framework agreements and national family planning tenders from Nigeria and Indonesia are driving bulk API offtake from Indian manufacturers. The CDSCO aligns domestic GMP standards with ICH Q7 guidelines to facilitate export market access. Hyderabad's API manufacturing cluster hosts specialized hormone synthesis facilities expanding fermentation capacity under PLI incentives.
China
Zhejiang province's chemical conversion infrastructure anchors global diosgenin-to-progestin processing volumes. The NMPA maintains separate registration pathways for hormone APIs that limit market entry velocity for non-domestic producers. Xianju county's pharmaceutical industrial zone concentrates scaled steroid backbone modification operations serving European contract manufacturers.
Germany
EMA genotoxic impurity guidelines are tightening acceptable limits for residual solvents in steroid APIs imported from Asia. Bayer AG leverages backward integration into key starting material synthesis to protect margin structures. Leverkusen's integrated chemical-pharmaceutical complex maintains captive production of estrone precursors for progestin ester manufacturing.
United States
FDA inspection intensity is extending approval timelines for new steroid hormone suppliers from India and China. Compounding pharmacies in Texas and Florida capture fragmented prescription volume for hormone replacement applications. The FDA's drug master file system favors established suppliers with existing ICH Q7 compliance documentation.
Brazil
ANVISA is harmonizing GMP standards with PIC/S guidelines to accelerate qualified supplier market entry. Government procurement bodies in São Paulo and Rio de Janeiro consolidate injectable contraceptive purchasing through national tender systems. The São Paulo state pharmaceutical corridor is attracting technology licensing partnerships for modular steroid synthesis reactor systems.
Norethisterone Enanthate API Market Competitive Landscape
Channel-controlling players compete with product-specialist players across contract manufacturing and captive supply segments. The vendor base concentrates among qualified steroid hormone manufacturers capable of meeting ICH Q7 compliance for public health procurement. Three archetypes dominate: integrated pharmaceutical conglomerates with backward synthesis control, specialized API manufacturers with dedicated hormone infrastructure, and scaled chemical converters with fermentation-to-esterification capabilities. Competitive moves center on multi-year offtake agreements with UNFPA and national family planning programs, plus biocatalytic technology licensing to reduce environmental compliance costs.
Among European integrated pharmaceutical conglomerates, Bayer AG exemplifies backward integration archetypes through captive starting material production. Symbiotec Pharmalab and Zhejiang Xianju Pharmaceutical Co., Ltd. occupy positions on opposite ends of the specialist spectrum—one representing dedicated hormone API manufacturing infrastructure, the other embodying scaled fermentation and chemical conversion capabilities. These three anchors illustrate how competitive positioning fragments across integration depth, regulatory qualification status, and production scale rather than consolidating around uniform business models.
| Leading Market Players |
|---|
| Bayer AG |
| Sanofi S.A. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Amber Lifesciences |
| Symbiotec Pharmalab |
| Coral Drugs Private Limited |
| Zhejiang Xianju Pharmaceutical Co., Ltd. |
| Lupin Ltd. |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-Jawaharlal Nehru Port freight corridor shapes cost dynamics across norethisterone enanthate API trade, concentrating supply-side power among ICH Q7-qualified Indian manufacturers while downstream price differentiation splits WHO-prequalified bulk supply from premium vial presentations serving European formulation clients.
Pricing Analysis
Certification level (ICH Q7/WHO-prequalified versus standard GMP) creates the primary spread between contraceptive-grade bulk and oncology-grade vial supply. Contract-based long-term offtake agreements with UNFPA anchor volume pricing for qualified suppliers, while spot procurement for research-grade material commands substantial premiums. Pricing pressure stems from India's PLI scheme accelerating domestic fermentation capacity expansion and compressing capital recovery timelines. Public health procurement bodies exhibit highest price sensitivity through consolidated multi-year tenders, whereas cancer treatment applications show lowest sensitivity due to stringent purity specifications and limited qualified supplier pools.
Supply Chain Analysis
Export-control restrictions on dual-use bioprocessing equipment limit technology transfer into steroid synthesis facilities outside established manufacturing clusters. Supply concentrates in India, China, and Germany, with Zhejiang province anchoring diosgenin extraction and Hyderabad hosting specialized hormone API fermentation. Raw material flows depend on Mexican yam cultivation, Chinese chemical conversion infrastructure, and Indian fermentation capacity. Single-source vulnerability around diosgenin supply creates structural exposure to agricultural commodity volatility. Distribution runs through contract manufacturing arrangements serving European and North American formulation clients, with public health procurement bodies consolidating volume through qualified supplier frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The norethisterone enanthate API market rewards specialized process chemistry capabilities that resist rapid replication, with experienced steroid synthesis expertise concentrated at legacy manufacturers and training pipelines failing to match facility expansion rates.
For Market Incumbents: Pre-empt emerging biocatalytic technology adoption by licensing engineered enzyme platforms before cost parity with traditional chemical routes erodes established process advantages. Defend margin structures through backward integration into estrone precursor synthesis, mirroring Bayer AG's captive starting material production at Leverkusen. Prioritize WHO prequalification maintenance against tightening EMA genotoxic impurity guidelines that threaten smaller competitors with six-to-twelve month compliance timelines. For New Entrants and Emerging Players: Pursue Brazilian ANVISA alignment as Latin America's largest pharmaceutical market harmonizes with PIC/S guidelines, enabling accelerated entry through existing FDA or EMA dossier leverage. Target oncology applications for endometrial and breast cancer palliative protocols, where smaller-batch requirements and tighter purity specifications sustain premium pricing above commoditized contraceptive grades. Secure technology licensing partnerships for modular continuous flow chemistry reactor systems to bypass centralized production economics and establish distributed manufacturing footprints. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized API manufacturers with dedicated hormone synthesis infrastructure over diversified chemical converters lacking regulatory qualification depth. Long-term viability rests on multi-year offtake agreement visibility with UNFPA and national family planning programs rather than spot market exposure. Acquisition targets should demonstrate existing ICH Q7 compliance documentation and WHO prequalification status. The signal to watch is India's Central Pollution Control Board enforcement intensity around wastewater discharge standards, which may force consolidation among undercapitalized competitors facing environmental compliance capex burdens.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Investment | Accelerates tender access for UNFPA framework agreements in sub-Saharan Africa. |
| Biocatalytic Technology Licensing | Reduces chromium-containing effluent generation and simplifies EMA environmental risk assessments. |
| Backward Integration into Precursors | Protects margin structures against diosgenin commodity volatility from Mexican yam supply. |
| Continuous Flow Chemistry Partnership | Enables distributed manufacturing footprints bypassing centralized production economics. |
| ANVISA Regulatory Alignment | Leverages existing FDA or EMA dossiers for accelerated Brazilian market entry. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with steroid synthesis process chemists, CDSCO regulatory affairs leads, UNFPA procurement officers, and European contract manufacturing executives; and secondary validation through FDA drug master files, EMA submissions, Indian PLI scheme disclosures, and WHO prequalification records. Bottom-up capacity assessments at Hyderabad and Zhejiang manufacturing clusters were triangulated against top-down public health procurement volume commitments.
Forecast inputs incorporated hormonal contraceptive tender volumes, oncology application purity premiums, and biocatalytic technology adoption curves across the projection horizon. Segmentation dimensions modeled include packaging format, therapeutic indication, procurement channel, and regional regulatory cluster. CAGRs were derived from supply-side capacity expansion timelines and demand-side offtake agreement visibility, with particular weighting toward India's PLI scheme implementation pace and UNFPA framework agreement renewal patterns.
Sensitivities concentrate around diosgenin supply disruptions from Mexican yam cultivation volatility, EMA inspection intensity extending Indian supplier approval timelines, and biocatalytic route cost parity achievement accelerating technology displacement. Material shifts in starting material availability or genotoxic impurity guideline stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Pegylated Protein Therapeutics Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Tetracycline Market
Biopharmaceuticals
Global Topical Antibiotics Market