
 Antibacterial Drugs Market | 2026-2036
Antibacterial Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antibacterial Drugs Market Analysis
Hospital infection control is repositioning antibacterial drug procurement toward narrow-spectrum agents with resistance-sparing profiles. Pfizer Inc. leverages its established hospital formulary relationships to sustain cephalosporin and penicillin franchise volumes across integrated delivery networks. Merck & Co., Inc. anchors its position through carbapenem manufacturing scale and anti-infective R&D intensity. GlaxoSmithKline plc differentiates via geographic dominance in respiratory infection therapy areas across European and emerging markets.
Antibacterial drugs are chemical or biological agents that inhibit bacterial cell wall synthesis, protein production, or DNA replication, typically administered at dosages calibrated to minimum inhibitory concentration thresholds against target pathogens. These agents serve the primary commercial purpose of treating or preventing bacterial infections across acute, chronic, and prophylactic clinical scenarios. Cephalosporins and penicillins occupy mature margin pools with stable hospital contracting, while glycopeptides command premium positioning against methicillin-resistant Staphylococcus aureus. Hospital infections represent the dominant therapy area by revenue commitment, though skin infections and urinary tract infections generate higher prescription volumes in outpatient and long-term care channels.
The FDA's Qualified Infectious Disease Product program and EMA's priority medicines pathway shape clinical trial investment and accelerated review timelines for novel antibacterial mechanisms. EPA and national pharmaceutical regulators enforce environmental discharge limits on antibiotic manufacturing effluent, raising compliance costs for active pharmaceutical ingredient producers. Stakeholders must monitor resistance surveillance data from WHO and national health agencies to align pipeline priorities with evolving pathogen threat profiles.
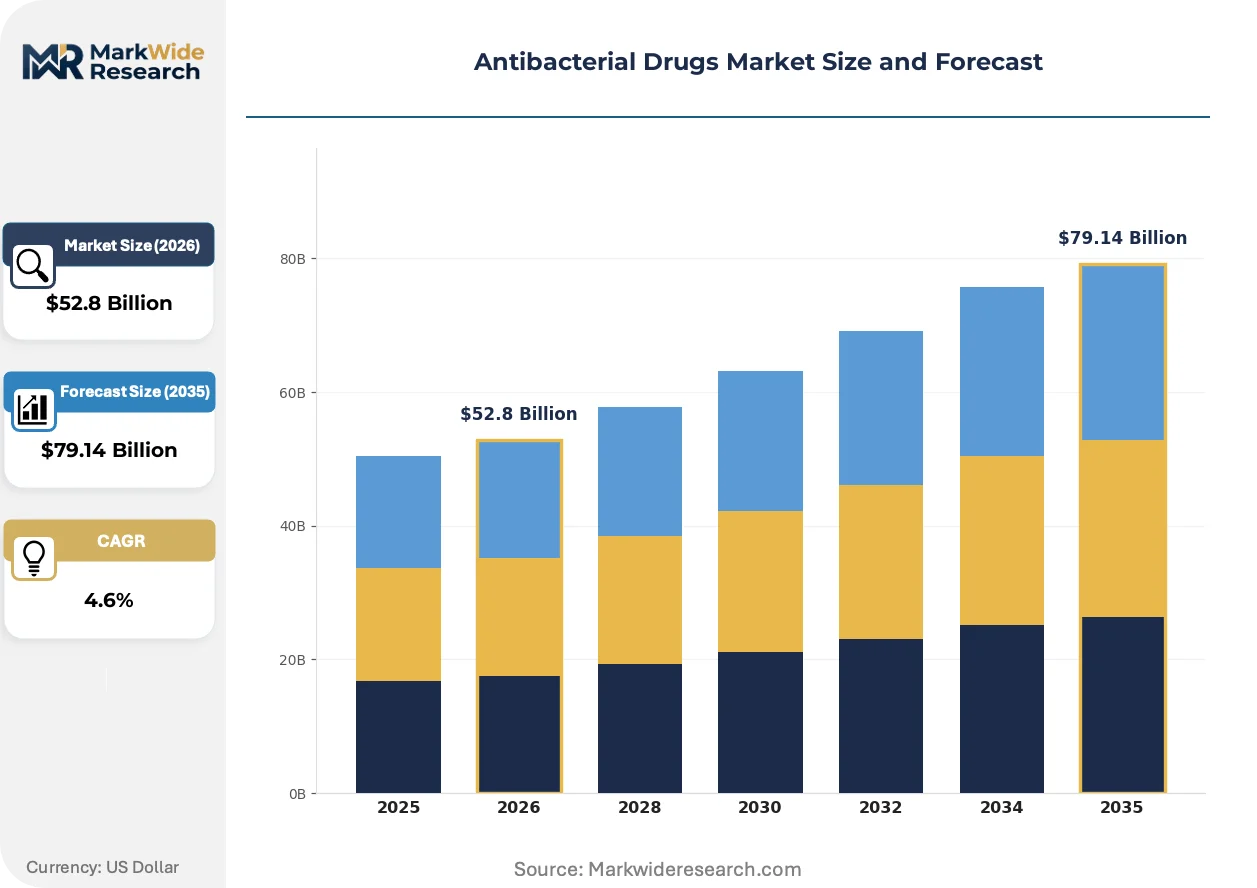
Market Dynamics
Antimicrobial stewardship mandates are compressing broad-spectrum prescribing volumes while accelerating narrow-spectrum development investment across hospital systems and outpatient networks.
Growth Catalysts
- Hospital-Acquired Infection Protocols:Acute care networks in the United States are intensifying formulary restrictions that favor resistance-sparing agents. These protocols drive procurement toward agents with documented efficacy against multidrug-resistant pathogens.
- EMA Priority Medicines Pathway:Accelerated regulatory review timelines in Europe compress development cycles for novel antibacterial mechanisms. Developers gain faster market access for qualified infectious disease products targeting unmet resistance profiles.
- Carbapenem Manufacturing Scale:Production concentration among specialized active pharmaceutical ingredient facilities enables cost-efficient supply of last-resort antibiotics. This capacity anchors hospital contracting for severe infection therapy areas.
Market Restraints
- API Supply Concentration:Bulk antibiotic manufacturing concentrates in Chinese and Indian chemical synthesis clusters. Geographic concentration creates vulnerability to environmental compliance actions or export restriction events.
- Reimbursement Compression:Payer formularies in Germany and France impose reference pricing that compresses margins on mature cephalosporin and penicillin franchises. Generic substitution further erodes branded volume retention.
- Environmental Discharge Limits:EPA effluent guidelines and EU Industrial Emissions Directive raise compliance costs for antibiotic manufacturing waste streams. Active pharmaceutical ingredient producers face capital-intensive wastewater treatment upgrades.
Strategic Opportunities
- Respiratory Infection Expansion:Outpatient respiratory therapy areas in Brazil and Mexico remain underpenetrated by narrow-spectrum agents. Local registration pathways enable first-mover positioning against community-acquired pneumonia pathogens.
- Pharmacokinetic Modeling Convergence:Integration of artificial intelligence with traditional minimum inhibitory concentration testing is compressing dose optimization timelines. This convergence enables personalized antibacterial regimens in critical care settings.
- Long-Term Care Channel Development:Urinary tract infection prophylaxis in United States nursing facilities represents an emerging prescription volume opportunity. Dedicated distribution partnerships with long-term care pharmacy networks enable formulary access.
Industry Challenges
- Clinical Microbiology Talent Scarcity:Specialized infectious disease pharmacologists and resistance surveillance specialists command premium compensation. Hospital systems and developers compete for limited expertise in pharmacokinetic-pharmacodynamic modeling.
- Legacy Manufacturing Integration:Sterile injectable capacity reconfiguration requires extended facility shutdowns and regulatory revalidation. Brownfield antibiotic production lines face compliance gaps against current good manufacturing practice standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibacterial Drugs Market |
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penicillins, Cephalosporins, Glycopeptides, Tetracyclines Therapy Area: Hospital Infections, Respiratory Infections, Skin Infections, Urinary Tract Infections End User: Hospitals, Clinics, Home Care Settings, Long-term Care Facilities Form: Tablets, Injections, Suspensions, Capsules |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Novartis AG, Johnson & Johnson Services LLC, Sanofi S.A., AstraZeneca plc, Bayer AG, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibacterial Drugs Market Emerging Trajectories
Beta-lactamase inhibitor combinations are displacing standalone beta-lactam regimens in hospital formularies, while regulatory frameworks and procurement models simultaneously reshape competitive positioning.
Next-generation beta-lactamase inhibitor combinations are consolidating market share within hospital anti-infective portfolios. These agents restore efficacy against extended-spectrum beta-lactamase-producing Enterobacteriaceae. Intensive care units and hematology-oncology wards are adopting them as first-line empiric therapy. This consolidation is compressing demand for traditional carbapenem-sparing strategies.
REACH authorization requirements for antibiotic manufacturing intermediates are tightening substance registration and environmental risk assessment obligations in Europe. Chemical suppliers must submit extended safety dossiers for active pharmaceutical ingredient precursors. Contract manufacturing organizations serving European markets are responding by consolidating supplier bases to qualified registrants with complete dossier portfolios.
Hospital purchasing cooperatives are centralizing antibacterial procurement decisions across integrated delivery networks in the United States. Individual facility autonomy is yielding to system-wide formulary standardization and volume commitment contracts. This concentration is most visible in the southeastern and midwestern states where multi-hospital systems dominate acute care capacity.
Antibacterial Drugs Market Segmentation
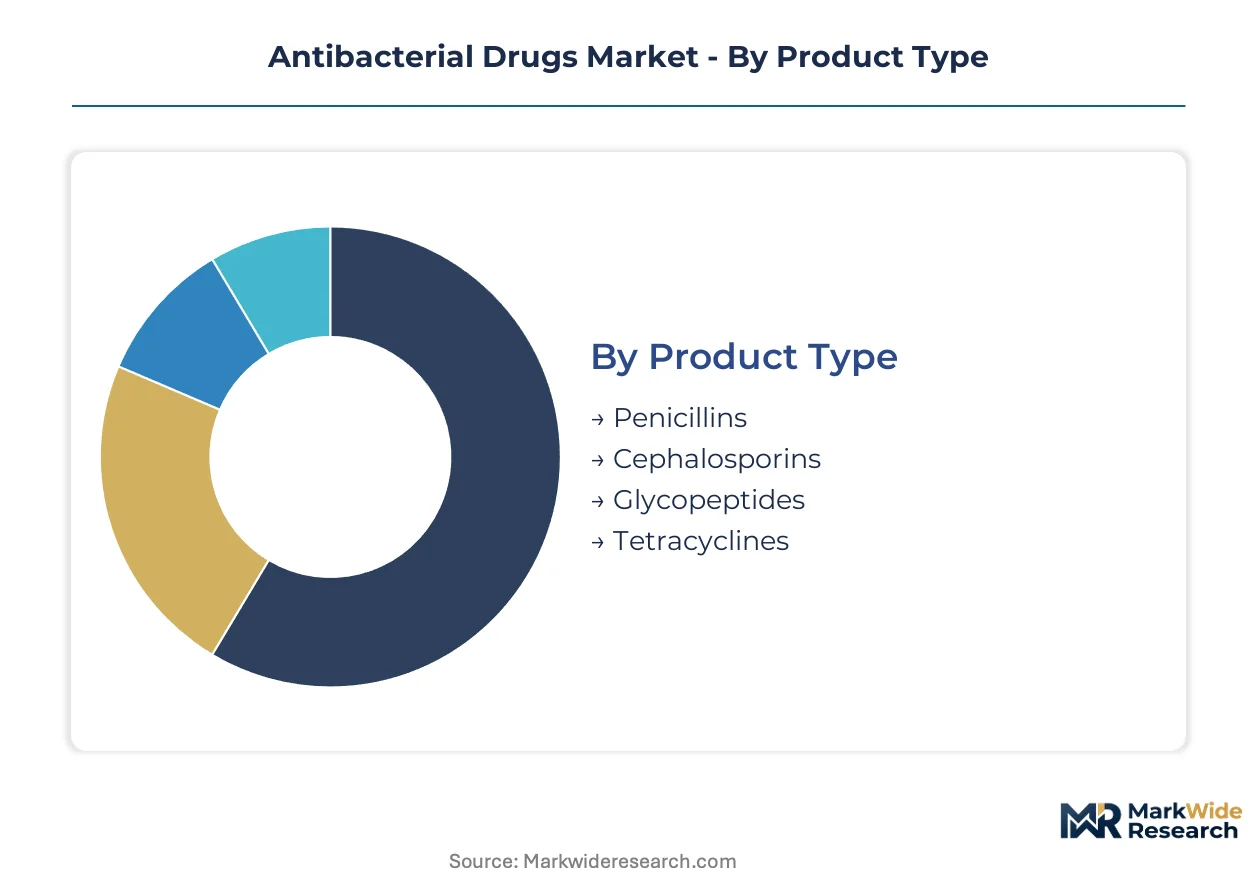
Antibacterial drug segmentation reveals how formulation chemistry, clinical setting, and route of administration intersect to determine procurement patterns. Manufacturers configure supply chains around the sterility requirements of injectable hospital products versus the scale economics of oral outpatient therapies.
Product Type:
The customization-vs-standardization spectrum runs from commodity beta-lactam fermentation products to precision-engineered glycopeptide semi-synthetics requiring specialized synthesis pathways.
- Penicillins:Natural and semi-synthetic beta-lactam agents derived from Penicillium fermentation, available in oral and parenteral forms. Demand concentrates in outpatient respiratory and skin infection channels across India and Brazil, where national essential medicines lists mandate bulk procurement. Volume leadership here reflects decades of manufacturing scale in Chinese and Indian active pharmaceutical ingredient clusters.
- Cephalosporins:Broad and extended-spectrum beta-lactams organized by generation-based potency against gram-negative pathogens. Hospital formularies in the United States and Germany anchor demand for third and fourth-generation injectable variants, driven by surgical prophylaxis protocols and empiric sepsis therapy.
- Glycopeptides:Large-molecule agents targeting methicillin-resistant Staphylococcus aureus through cell wall precursor binding. Intensive care units in tertiary hospitals command premium positioning.
- Tetracyclines:Protein synthesis inhibitors with revived interest for atypical respiratory pathogens and vector-borne diseases. Outpatient clinics sustain prescription volumes.
Most installed capacity flows through Cephalosporins. Expansion is steepest in Glycopeptides.
Therapy Area:
Margin structure varies sharply across acute versus chronic infection management, with hospital-acquired indications commanding price premiums over community-treated conditions.
- Hospital Infections:Nosocomial pneumonia, bloodstream infections, and surgical site infections requiring intravenous empiric therapy with broad-spectrum coverage. Demand clusters in United States integrated delivery networks and German university hospitals, where antimicrobial stewardship committees restrict formulary access to resistance-documented agents. Reimbursement through diagnosis-related group coding sustains higher per-dose economics than outpatient channels.
- Respiratory Infections:Community-acquired pneumonia, acute bacterial sinusitis, and chronic obstructive pulmonary disease exacerbations treated across outpatient and inpatient settings. European primary care networks and Brazilian public health clinics generate prescription volume for oral beta-lactams and macrolide alternatives.
- Skin Infections:Cellulitis, abscesses, and wound infections spanning outpatient dermatology and emergency department encounters. Long-term care facilities drive prophylactic demand.
- Urinary Tract Infections:Uncomplicated cystitis and complicated pyelonephritis treated predominantly in outpatient and long-term care settings. Generic substitution pressures dominate.
Revenue concentration sits with Hospital Infections. Volume expansion is fastest in Respiratory Infections.
End User:
Procurement authority concentrates differently across facility types, from centralized hospital purchasing cooperatives to fragmented home care pharmacy networks.
- Hospitals:Acute care institutions with centralized pharmacy and therapeutics committees controlling formulary access. Antimicrobial stewardship mandates in the United States and France reshape prescribing toward narrow-spectrum, resistance-sparing agents. Group purchasing organizations aggregate volume commitments across multi-hospital systems.
- Clinics:Outpatient facilities including primary care, urgent care, and specialty infectious disease practices. Retail pharmacy dispensing dominates reimbursement pathways.
- Home Care Settings:Outpatient parenteral antimicrobial therapy programs and self-administered oral regimens. United States home infusion providers coordinate with long-term care transitions.
- Long-term Care Facilities:Nursing homes and skilled nursing facilities managing recurrent urinary tract infections and skin colonization. Antibiotic stewardship requirements are intensifying.
Contracting leverage is strongest through Hospitals. Prescription volume growth is climbing fastest in Long-term Care Facilities.
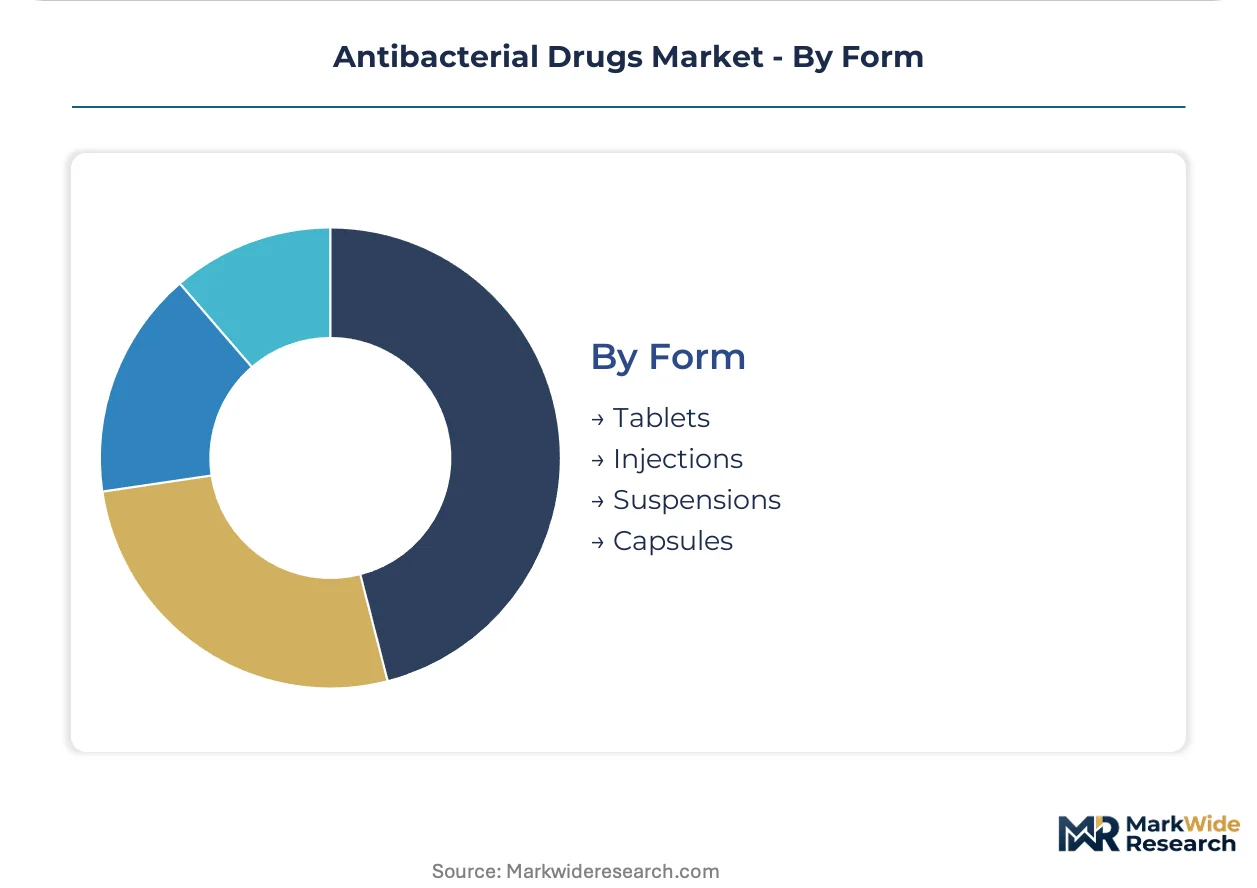
Form:
Manufacturing complexity and regulatory burden escalate from solid oral dosage forms to sterile injectable preparations requiring dedicated facility infrastructure.
- Tablets:Compressed solid dosage forms for oral administration, predominantly penicillin and tetracycline derivatives. Scale production in Indian formulation hubs supplies African and Southeast Asian tender markets. Bioequivalence requirements under FDA and EMA guidelines govern generic substitution.
- Injections:Sterile solutions and lyophilized powders for intravenous or intramuscular administration, encompassing cephalosporins, glycopeptides, and carbapenems. Hospital critical care units in Germany and the United States anchor demand for single-dose vials and premixed infusion bags.
- Suspensions:Liquid oral formulations for pediatric and geriatric patients with swallowing difficulties. Community pharmacies stock seasonal respiratory indications.
- Capsules:Gelatin or HPMC shells containing powder or granule fills, common for tetracyclines and amoxicillin combinations. Retail pharmacy distribution predominates.
Production asset intensity is highest in Injections. Market access expansion is proceeding most rapidly in Suspensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping active pharmaceutical ingredient sourcing as manufacturers relocate fermentation and chemical synthesis operations toward jurisdictions with streamlined environmental compliance pathways and lower wastewater treatment capital requirements.
United States
Hospital-acquired infection protocols drive formulary consolidation toward resistance-sparing agents across integrated delivery networks. FDA Qualified Infectious Disease Product designation accelerates novel antibiotic review timelines for developers targeting unmet resistance profiles. New Jersey and Massachusetts anchor sterile injectable manufacturing capacity for hospital-critical care segments.
Germany
EMA priority medicines pathway compresses development cycles for qualified infectious disease products entering European markets. Industrial emissions directives raise compliance costs for antibiotic manufacturing effluent, pushing API sourcing toward pre-qualified contract manufacturers. Bavaria and North Rhine-Westphalia concentrate fermentation-based beta-lactam production.
India
CDSCO streamlined approval pathways for generic penicillins and cephalosporins sustain export volume leadership into African and Southeast Asian tender markets. Production incentives under the PLI scheme for pharmaceuticals attract capital toward fermentation capacity expansion. Hyderabad and Ahmedabad clusters dominate bulk antibiotic API synthesis.
China
NMPA environmental discharge enforcement actions intermittently disrupt bulk cephalosporin and penicillin intermediate supply from concentrated chemical synthesis hubs. Dual carbon goals accelerate facility consolidation toward integrated manufacturers with captive wastewater treatment infrastructure. Shandong and Jiangsu provinces host the majority of fermentation-derived API capacity.
Brazil
ANVISA local registration pathways enable first-mover positioning for narrow-spectrum agents targeting community-acquired respiratory infections in underpenetrated outpatient channels. Public health clinic procurement through national essential medicines programs sustains volume demand for oral beta-lactams. São Paulo state anchors formulation and packaging operations for Latin American distribution.
Antibacterial Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital formulary concentration favoring established pharmaceutical houses while generic substitution pressures fragment outpatient and long-term care channels. The vendor base organizes around three strategic archetypes: integrated innovators with hospital contracting depth, fermentation-scale API suppliers with cost-position advantages, and regional formulation specialists serving tender markets. Competitive moves center on antimicrobial stewardship alignment and sterile injectable capacity reconfiguration.
Among integrated pharmaceutical houses, Pfizer Inc., Merck & Co., Inc., and GlaxoSmithKline plc occupy positions defined by hospital formulary relationships and geographic therapy area dominance. Pfizer anchors cephalosporin and penicillin franchise volumes through established integrated delivery network contracts. Merck exemplifies carbapenem manufacturing scale and anti-infective R&D intensity. GlaxoSmithKline represents geographic differentiation in respiratory infection therapy areas across European and emerging markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Johnson & Johnson Services LLC |
| Sanofi S.A. |
| AstraZeneca plc |
| Bayer AG |
| AbbVie Inc. |
| Others |
Supply Flow & Price Mechanics
Fermentation-to-synthesis manufacturing transitions in beta-lactam production are simultaneously compressing unit economics and concentrating active pharmaceutical ingredient supply among integrated Chinese and Indian facilities with captive wastewater treatment infrastructure. This dual shift reshapes how hospital purchasing cooperatives negotiate volume commitments against generic substitution pressures in outpatient channels.
Pricing Analysis
Hospital distributor margins anchor antibacterial drug pricing architecture across United States integrated delivery networks. Three-tier pricing structure across premium glycopeptides, standard cephalosporins, and economy penicillins reflects FDA QIDP certification status and resistance documentation depth. Cost compression in mature oral beta-lactam tiers intensifies as Indian CDSCO-approved generics flood African and Southeast Asian tender markets. Long-term care facilities exhibit highest price sensitivity due to Medicaid reimbursement ceilings, while tertiary hospital intensive care units accept premium positioning for last-resort carbapenems.
Supply Chain Analysis
Single-source vulnerability sits with Shandong and Jiangsu province fermentation hubs supplying bulk cephalosporin and penicillin intermediates to global formulation networks. Chinese NMPA environmental enforcement actions and Indian PLI scheme production incentives collectively shape API availability for hospital-critical care segments. Supply chain risk centers on MEE discharge compliance disruptions that trigger intermittent export restrictions. Distribution runs through hospital group purchasing organizations in the United States, regional tender authorities in Germany and France, and public health procurement systems in Brazil and Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The antibacterial drugs market functions as a regulatory compounder where FDA Qualified Infectious Disease Product designation and EMA priority medicines pathway accelerate development timelines and reshape competitive entry economics.
For Market Incumbents: Anchor hospital formulary position through antimicrobial stewardship committee alignment and resistance surveillance data partnerships. Defend against generic substitution by deepening backward integration into fermentation-based API production in Hyderabad and Ahmedabad clusters. Prioritize sterile injectable capacity reconfiguration in New Jersey and Massachusetts to meet current good manufacturing practice standards.
For New Entrants and Emerging Players: Launch via long-term care pharmacy network partnerships targeting urinary tract infection prophylaxis in United States nursing facilities. Exploit underpenetrated outpatient respiratory channels in Brazil and Mexico through ANVISA local registration pathways. Position narrow-spectrum agents against community-acquired pneumonia pathogens where stewardship mandates favor resistance-sparing profiles.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation specialists with captive environmental compliance infrastructure because NMPA discharge enforcement is consolidating Chinese API supply. Five-to-ten year viability hinges on pipeline positioning against WHO priority pathogen lists. Monitor EMA REACH authorization requirements for manufacturing intermediates as inflection indicator for European market access costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Stewardship Alignment | FDA QIDP designation accelerates hospital formulary access for novel resistance-sparing mechanisms. |
| Sterile Injectable Capacity Expansion | New Jersey and Massachusetts facilities anchor supply for United States critical care unit demand. |
| API Backward Integration | Hyderabad and Ahmedabad clusters reduce exposure to Chinese NMPA environmental enforcement disruptions. |
| Long-term Care Channel Development | United States nursing facility partnerships unlock prophylactic prescription volume for narrow-spectrum agents. |
| EMA Priority Medicines Pathway | Accelerated review timelines compress development cycles for novel beta-lactamase inhibitor combinations. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down active pharmaceutical ingredient production tracking forms the analytical core of this study. Primary interviews with infectious disease pharmacologists, hospital formulary directors, antimicrobial stewardship committee chairs, and long-term care pharmacy procurement managers combined with secondary validation from FDA QIDP filings, EMA priority medicines submissions, ClinicalTrials.gov protocol registries, and WHO resistance surveillance databases. Triangulation across these sources ensures segmentation outputs reflect actual prescribing pattern variation across acute care networks and outpatient channels.
Input-output matrices connect fermentation capacity utilization, environmental compliance cost structures, and hospital purchasing cooperative volume commitments to project segment-level revenue trajectories across the analysis window. Segmentation dimensions include product chemistry class, therapy area severity, end-user facility type, and regional regulatory cluster. CAGRs derive from minimum inhibitory concentration testing adoption curves and antimicrobial stewardship mandate implementation timelines. Forecast inputs incorporate CDSCO approval velocity for generic penicillins and NMPA discharge enforcement probability.
Several conditions sit outside the modeled scope, including pandemic-driven demand surges, novel resistance mechanism emergence, and radical manufacturing technology shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Latin America Insulin Pens Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Fenbendazole Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Targeted Protein Degradation Market