
 Difficult-To-Express Proteins Market | 2026-2036
Difficult-To-Express Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Difficult-To-Express Proteins Market Analysis
Capital-intensity divergence between mammalian cell culture specialists and microbial expression platform operators is redrawing competitive boundaries in protein manufacturing. Thermo Fisher Scientific leverages its integrated reagent-to-bioproduction infrastructure to anchor premium positioning across contract development workflows. Sino Biological competes through scaled recombinant protein libraries and aggressive capacity expansion in Asia-Pacific markets. Rentschler Biopharma specializes in complex glycoprotein manufacturing, occupying a defensible niche in mammalian expression for therapeutic-grade outputs.
Difficult-to-express proteins comprise recombinant, natural, fusion, and cytokine classes that resist conventional microbial or cell-based production due to toxicity, insolubility, or improper folding, typically requiring specialized chaperone co-expression, codon optimization, or cell-free synthesis to achieve functional yields for therapeutic and diagnostic applications. Recombinant proteins dominate current revenue flows given their centrality to biologic drug pipelines, while cell-free expression technologies represent the fastest-expanding segment as manufacturers seek to bypass cellular toxicity constraints. Vaccine development applications command elevated margins due to pandemic-preparedness contracting structures, whereas research-grade demand sustains volume throughput across academic and institutional buyers.
FDA biologic licensing requirements and EMA good manufacturing practice standards for host cell protein impurity profiles shape facility investment priorities and quality system architectures across production networks. China's NMPA has tightened biosimilar comparability guidelines, forcing foreign suppliers to demonstrate equivalence in glycosylation patterns and aggregation profiles for market access. ISO 13485 certification and WHO prequalification pathways further stratify supplier eligibility for diagnostic-grade protein contracts. Stakeholders must monitor regulatory convergence on host cell protein detection thresholds and emerging guidance on cell-free expression system characterization before committing to platform-scale capital deployment.
Market Dynamics
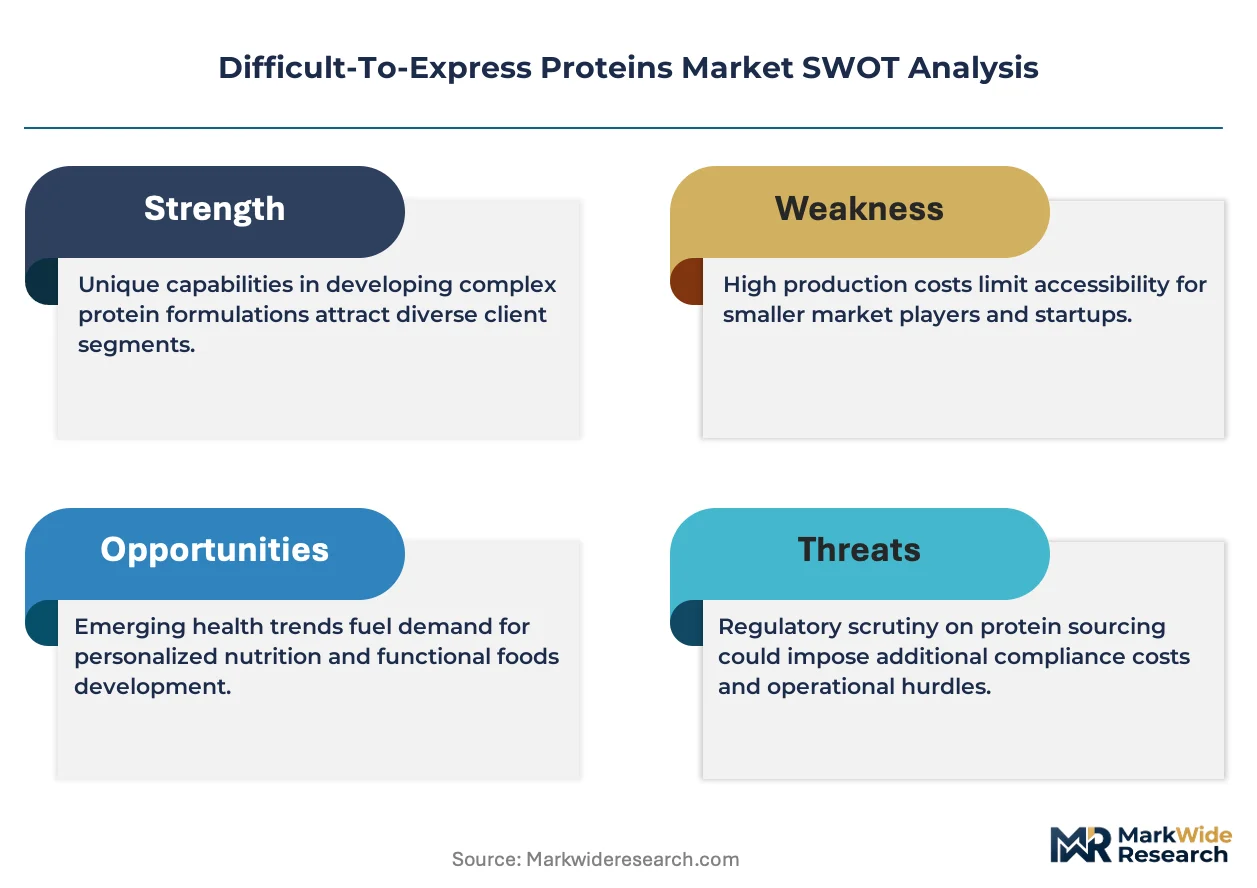
Cell-free expression systems are compressing production timelines for toxic membrane proteins, forcing legacy CHO cell infrastructure to reposition toward glycosylation-sensitive therapeutic outputs. This technology shift redistributes competitive advantage toward synthetic biology platform operators.
Growth Catalysts
- EMA GMP harmonization:Streamlined host cell protein impurity documentation accelerates multi-site manufacturing approvals across European contract development networks.
- Vaccine adjuvant protein demand:Pandemic preparedness contracting structures from national health agencies sustain elevated margin procurement for rapid-response production capacity.
- Continuous perfusion bioreactors:Chinese CDMO clusters in Suzhou and Shanghai deploy integrated upstream-downstream systems that halve residence time for aggregation-prone cytokines.
Market Restraints
- Proprietary media formulation costs:Serum-free chemically defined media constitute 35-45% of COGS for mammalian expression campaigns, with single-source suppliers dominating high-performance additive categories.
- Plasmid DNA supply chokepoints:GMP-grade plasmid production concentrates among three North American contract manufacturers, creating queue bottlenecks for cell-free system developers.
- Codon optimization IP thickets:Platform patents covering rare tRNA supplementation strategies fragment freedom-to-operate for microbial expression of cysteine-rich proteins.
Strategic Opportunities
- India CDMO scale-up:CDSCO's streamlined biosimilar pathway and PLI scheme incentives attract difficult-to-express protein investment toward Hyderabad-Bengaluru corridor facilities.
- AI-driven chaperone engineering:Machine learning prediction of solubility-enhancing fusion partners converges with automated yeast surface display screening to rescue previously intractable targets.
- Diagnostic OEM channel expansion:Lateral flow and ELISA kit manufacturers bypass distributor markups through direct technical partnerships with recombinant antigen suppliers.
Industry Challenges
- Process analytical technology integration:Real-time glycosylation monitoring via at-line mass spectrometry demands cross-functional teams combining bioprocess engineering with analytical chemistry expertise that remains scarce outside Boston-San Diego-Zurich clusters.
- ISO 13485 certification timelines:Diagnostic-grade protein suppliers face 14-18 month audit cycles for quality management system accreditation, delaying commercial launch of companion diagnostic co-development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Difficult-To-Express Proteins Market |
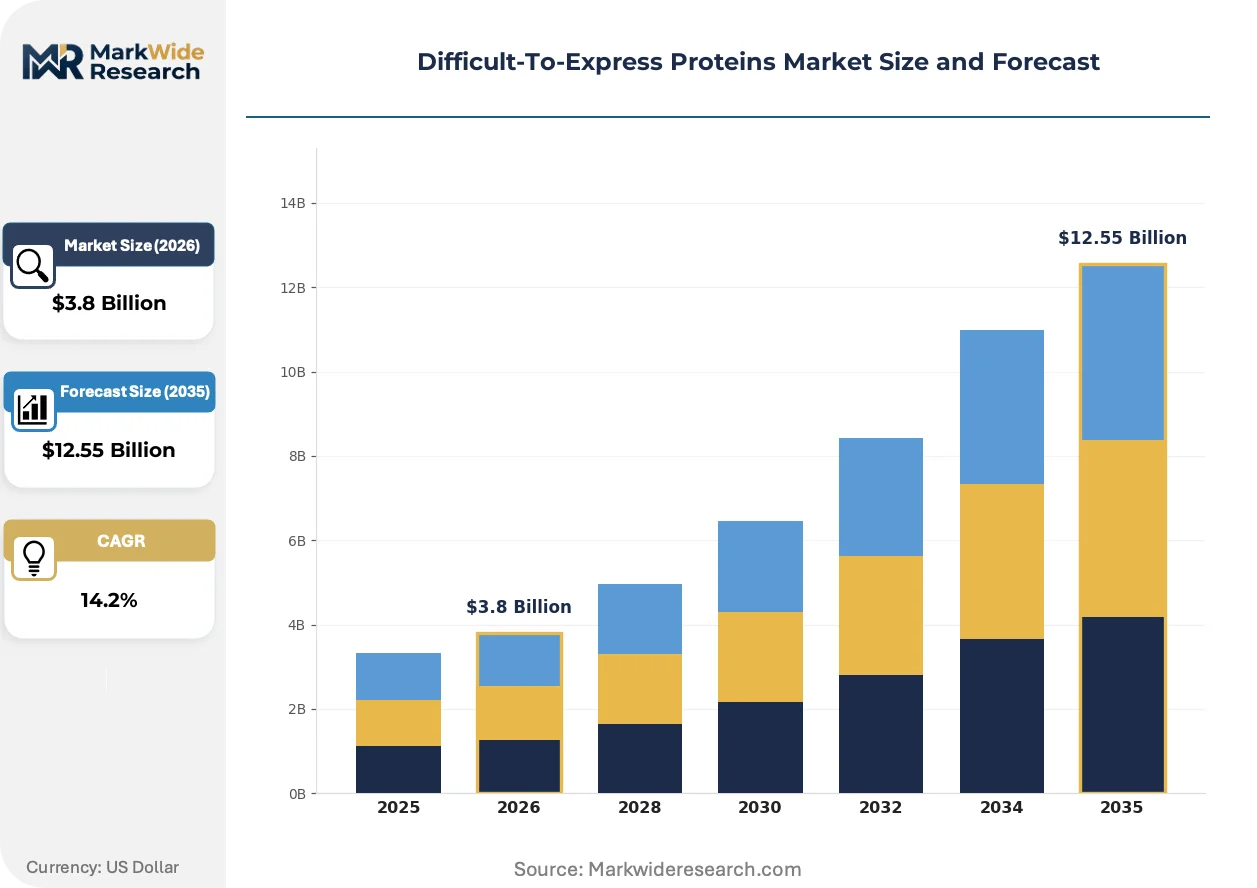
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Proteins, Natural Proteins, Fusion Proteins, Cytokines Applications: Therapeutics, Diagnostics, Research, Vaccine Development End User: Biopharmaceutical Companies, Academic Institutions, Research Laboratories, Contract Research Organizations Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation |
| Companies Covered | Sino Biological, Thermo Fisher Scientific, StressMarq Biosciences, Enzo Life Sciences, BioLegend, LifeSensors, Lucigen, Rentschler Biopharma, Novasep Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Difficult-To-Express Proteins Market Emerging Trajectories
Synthetic biology toolkits are collapsing the distinction between research-grade and GMP-ready expression platforms. Three developments dominate current investment patterns.
Cell-free protein synthesis utilizing E. coli or CHO lysate extracts is supplanting traditional fermentation for rapid prototyping of disulfide-bonded biologics. Biopharmaceutical discovery groups at Merck KGaA and contract research organizations adopt these systems for 48-hour antigen production cycles. The technology compresses early-stage candidate timelines from months to weeks, reallocating capital from cell line development toward downstream purification infrastructure.
China's NMPA tightened biosimilar comparability guidelines in 2023, mandating glycosylation pattern equivalence demonstrations for foreign supplier market access. The regulation forces European and North American manufacturers to establish local release testing partnerships or captive analytical facilities in Shanghai and Beijing. Mammalian expression specialists face the steepest compliance burden, as glycan microheterogeneity proves hardest to replicate across geographic production sites.
Academic consortia and mid-sized biotechs increasingly specify cell-free-derived proteins in CRISPR reagent procurement, bypassing traditional distributor networks for direct manufacturer relationships. The purchasing pattern concentrates volume among synthetic biology platform operators with demonstrated scale-up trajectories. This concentration is most visible in Cambridge, Massachusetts and Basel, where proximity to discovery biology clusters enables same-week technical troubleshooting and batch customization.
Difficult-To-Express Proteins Market Segmentation
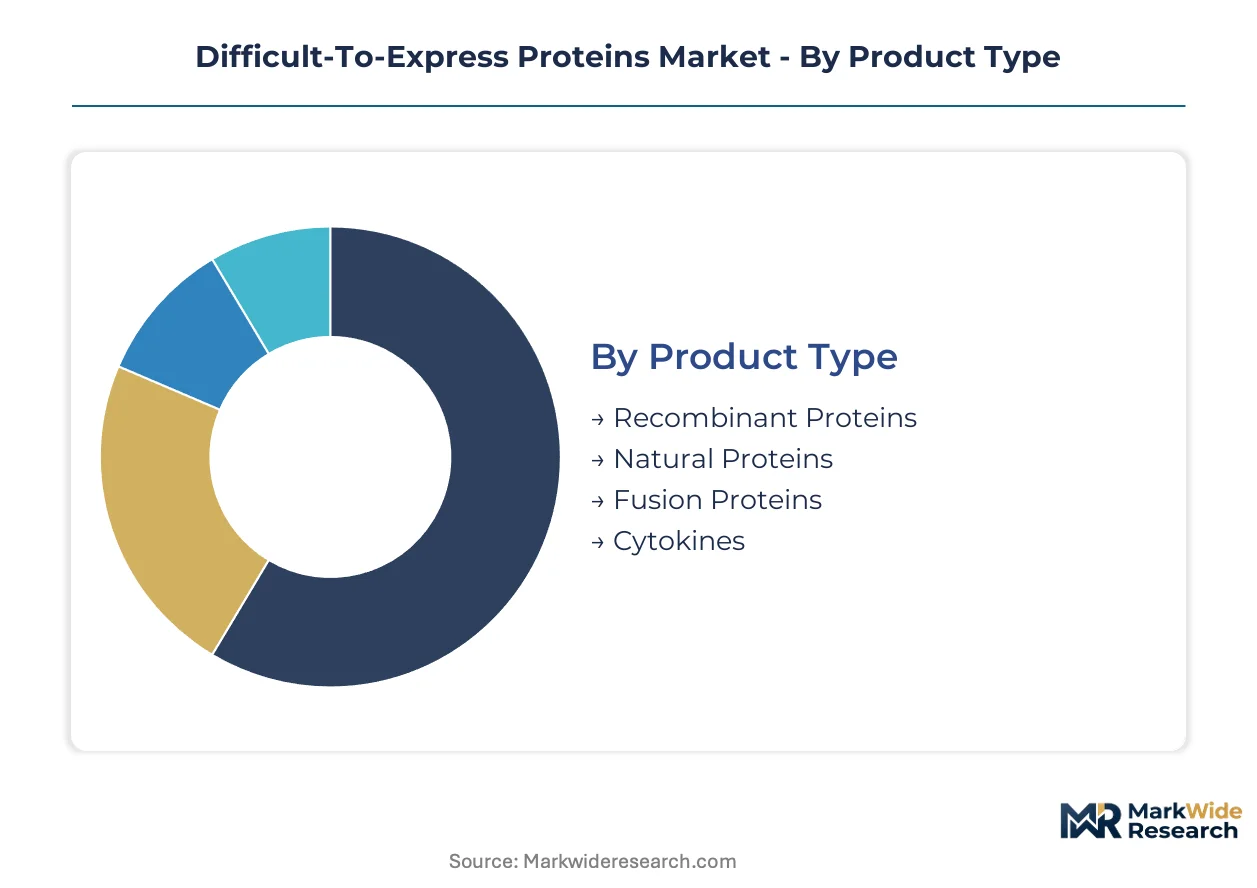
Segmentation in the difficult-to-express proteins market reveals distinct procurement patterns across therapeutic versus diagnostic applications. Channel structures diverge sharply between GMP-grade biologics sold through regulated supply agreements and research-grade materials distributed via e-commerce platforms.
Product Type:
Recombinant proteins flow predominantly through direct manufacturer relationships with biopharmaceutical companies, while natural proteins concentrate in diagnostic OEM channels requiring ISO 13485 certification.
- Recombinant Proteins:Engineered sequences produced in heterologous host systems enable precise control over post-translational modifications critical for therapeutic efficacy. Demand concentrates in the United States and Germany where monoclonal antibody developers require gram-scale GMP batches for clinical trials. FDA biologic licensing requirements enforce stringent host cell protein impurity documentation that elevates supplier qualification barriers.
- Natural Proteins:Native sequences extracted or purified from biological sources retain complex glycosylation patterns difficult to replicate recombinantly. Academic consortia in Basel and Cambridge, Massachusetts drive procurement for structural biology applications requiring authentic folding. Supply constraints around source tissue availability limit scale-up compared to recombinant alternatives.
- Fusion Proteins:Chimeric constructs combining functional domains from distinct protein classes extend serum half-life or enable targeted delivery.
- Cytokines:Signaling proteins requiring precise refolding protocols to maintain bioactivity; aggregation-prone variants demand specialized formulation expertise.
By volume, recombinant proteins lead. By growth pace, cytokines are expanding most quickly.
Applications:
Application segments stratify by margin structure, with vaccine development commanding premium pricing through pandemic preparedness contracting while research applications sustain volume through institutional procurement.
- Therapeutics:Protein-based biologics for disease treatment require GMP manufacturing with validated analytical methods for release testing. EMA GMP harmonization accelerates multi-site approvals across European contract development networks, reducing time-to-market for mammalian expression-derived antibodies. Batch failure costs exceed $500,000 for late-phase clinical material, concentrating demand among suppliers with demonstrated regulatory track records.
- Vaccine Development:Antigen production for prophylactic and therapeutic vaccines operates under national health agency rapid-response frameworks. Adjuvant protein procurement from BARDA and CEPI sustains elevated margins independent of commercial therapeutic pricing cycles. Cell-free expression systems are displacing traditional fermentation for emergency antigen prototyping.
- Diagnostics:Recombinant antigens and antibodies for immunoassay manufacturing; ISO 13485 certification gates supplier eligibility.
- Research:Non-GMP proteins for discovery biology; price sensitivity drives distributor-mediated procurement with lower switching costs.
Therapeutics generates the highest absolute revenue. Vaccine development shows the steepest expansion trajectory.
End User:
End user categories separate by technical support intensity, with biopharmaceutical companies demanding embedded application scientists while academic buyers prioritize catalog breadth and rapid fulfillment.
- Biopharmaceutical Companies:Integrated drug developers and emerging biotechs purchasing for internal pipeline manufacturing or external CDMO placement. Thermo Fisher Scientific and Sino Biological compete for multi-year supply agreements with dedicated account management. China's NMPA biosimilar comparability guidelines force foreign suppliers to establish local release testing partnerships.
- Contract Research Organizations:Service providers integrating protein production into broader discovery and development workflows; procurement emphasizes platform flexibility and timeline compression.
- Academic Institutions:University core facilities and individual laboratories; grant-funded purchasing concentrates in Massachusetts, California, and Oxford-Cambridge corridor.
- Research Laboratories:Government and private non-profit research centers; procurement patterns mirror academic buyers with additional emphasis on lot-to-lot consistency for longitudinal studies.
Biopharmaceutical companies dominate current spending. Contract research organizations are gaining share fastest.
Delivery Mode:
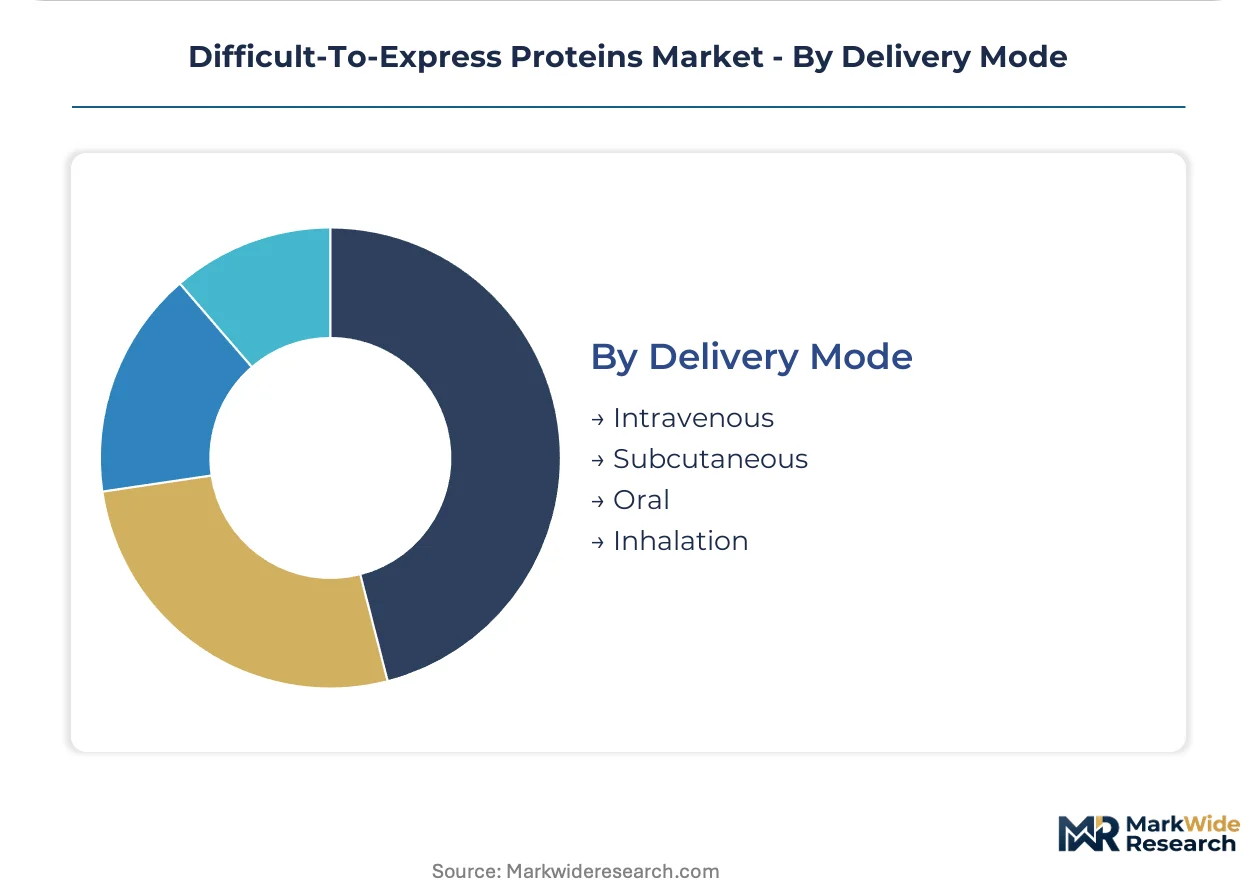
Delivery mode segmentation reflects formulation complexity gradients, with intravenous and subcutaneous routes requiring sterile injectable manufacturing capabilities that oral and inhalation formats bypass.
- Intravenous:Parenteral administration of high-dose biologics demands endotoxin-controlled manufacturing with validated sterile filtration. Concentrated protein solutions at 100+ mg/mL require viscosity-reducing formulation strategies. Suzhou and Shanghai CDMO clusters deploy continuous perfusion bioreactors that halve residence time for aggregation-prone candidates.
- Subcutaneous:Self-administered injection formats drive demand for high-concentration, low-volume formulations with reduced immunogenicity risk. Prefilled syringe and autoinjector compatibility constrains excipient selection and container closure system design.
- Oral:Non-invasive delivery limited to stable, non-degradable protein classes; permeation enhancers and enteric coatings add formulation complexity.
- Inhalation:Pulmonary delivery for local respiratory indications; aerosolization stability and deep lung deposition efficiency determine commercial viability.
Intravenous administration retains volume leadership. Subcutaneous formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland show the lowest price elasticity for GMP-grade glycoproteins, while academic purchasers in India and Brazil negotiate aggressively on research-grade catalog items. This demand-elasticity contrast shapes regional investment priorities and facility specifications.
United States
FDA biologic licensing requirements drive facility investment toward validated host cell protein detection systems. BARDA pandemic preparedness contracts sustain premium pricing for rapid-response antigen production capacity. The Boston-San Diego corridor concentrates mammalian expression specialists serving Phase III clinical trial material demand.
Germany
EMA GMP harmonization accelerates multi-site manufacturing approvals across contract development networks. The country's national pharmaceutical regulator enforces stringent comparability documentation for biosimilar glycosylation profiles. Heidelberg-Munich-Stuttgart industrial clusters deploy continuous perfusion systems for aggregation-prone cytokine manufacturing.
China
NMPA tightened biosimilar comparability guidelines force foreign suppliers to establish local release testing partnerships in Shanghai and Beijing. Suzhou and Shanghai CDMO clusters integrate upstream-downstream systems that compress residence times for difficult-to-express targets. Domestic biopharmaceutical companies expand captive mammalian cell culture capacity for monoclonal antibody pipelines.
India
CDSCO's streamlined biosimilar pathway and PLI scheme incentives attract contract manufacturing investment toward the Hyderabad-Bengaluru corridor. Price-sensitive academic procurement concentrates in Maharashtra and Karnataka state university systems. Local suppliers compete on research-grade recombinant protein catalog breadth rather than GMP certification depth.
Switzerland
Swissmedic therapeutic protein standards anchor premium positioning for glycosylation-sensitive biologics. Basel's discovery biology clusters specify cell-free-derived proteins in CRISPR reagent procurement, bypassing traditional distributor networks. The country's contract manufacturers specialize in complex glycoprotein release testing for European market access.
Difficult-To-Express Proteins Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated reagent-to-bioproduction infrastructure commanding premium positioning while scaled library operators compete on volume throughput. The vendor base separates into three strategic tiers: diversified life science conglomerates with captive supply chains, specialized mammalian expression service providers, and catalog-scale recombinant protein suppliers. Dominant competitive moves include geographic capacity expansion in Asia-Pacific markets and strategic partnerships for plasmid DNA supply security.
Among diversified platform operators, Thermo Fisher Scientific anchors integrated infrastructure positioning across contract development workflows. Sino Biological exemplifies scaled recombinant protein library competition with aggressive Asia-Pacific capacity expansion. Rentschler Biopharma occupies a defensible niche specialization in complex glycoprotein manufacturing for therapeutic-grade outputs.
| Leading Market Players |
|---|
| Sino Biological |
| Thermo Fisher Scientific |
| StressMarq Biosciences |
| Enzo Life Sciences |
| BioLegend |
| LifeSensors |
| Lucigen |
| Rentschler Biopharma |
| Novasep Holding |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with pandemic preparedness agencies lock in supply access for vaccine adjuvant proteins while anchoring price visibility through BARDA and CEPI procurement frameworks. These structures insulate premium-tier suppliers from spot-market volatility while forcing standard-grade producers into price competition on research catalog items.
Pricing Analysis
After-sales technical support contracts drive lifetime value for mammalian expression specialists serving Phase III clinical material demand. Three-tier pricing structure across premium GMP-grade, standard ISO-certified, and economy research-grade levels separates suppliers by regulatory documentation depth. Cost compression in standard-grade cytokine production intensifies as Chinese CDMO clusters deploy continuous perfusion systems. Academic purchasers in India and Brazil show highest price sensitivity, while German biopharmaceutical companies accept premium positioning for glycosylation-sensitive outputs.
Supply Chain Analysis
Inventory lead times for GMP-grade plasmid DNA extend 14-18 months due to concentration among North American contract manufacturers. Supply concentrates in the United States, China, and Germany where specialized fermentation capacity and analytical infrastructure cluster. Raw material dependencies center on serum-free chemically defined media formulations, rare tRNA supplementation reagents, and CHO cell line licenses. Single-source vulnerability in proprietary media additives creates queue bottlenecks for mammalian expression campaigns. Distribution runs through direct manufacturer relationships for GMP biologics and distributor-mediated channels for research-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The difficult-to-express proteins market is entering a cyclical recovery driven by pandemic preparedness agency restocking of rapid-response antigen production capacity. Contract manufacturing organizations with validated host cell protein detection systems are positioned to capture premium-tier procurement.
For Market Incumbents: Secure captive plasmid DNA supply through backward integration or strategic partnerships to eliminate queue bottlenecks threatening cell-free system scale-up. Add continuous perfusion capacity in Suzhou or Shanghai to defend margin position against Chinese CDMO clusters compressing residence times for aggregation-prone cytokines. For New Entrants and Emerging Players: ISO 13485 certification fast-tracks entry into diagnostic OEM channels where lateral flow and ELISA kit manufacturers seek direct technical partnerships. Target the India CDMO corridor around Hyderabad-Bengaluru where CDSCO's streamlined biosimilar pathway and PLI scheme incentives attract investment. Lead with AI-driven chaperone engineering capabilities to rescue previously intractable targets and differentiate from catalog-scale competitors. For Investors and Strategic Acquirers: Synthetic biology platform operators with demonstrated cell-free expression scale-up trajectories present asymmetric upside as academic consortia bypass traditional distributor networks. Monitor NMPA enforcement patterns on glycosylation pattern equivalence as the inflection signal for foreign supplier market access in China.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Free Expression Scale-Up | Compresses toxic membrane protein timelines from months to weeks for Merck KGaA discovery groups. |
| GMP Plasmid Supply Security | Eliminates North American contract manufacturer queue bottlenecks constraining system developers. |
| Continuous Perfusion Deployment | Halves residence time for aggregation-prone cytokines in Suzhou and Shanghai CDMO clusters. |
| ISO 13485 Certification Investment | Gates supplier eligibility for diagnostic-grade lateral flow and ELISA kit contracts. |
| AI-Driven Chaperone Engineering | Rescues previously intractable targets through machine learning prediction of solubility-enhancing fusion partners. |
Methodological Framework
Initial hypotheses were tested against primary input from bioprocess engineering directors, regulatory affairs leads at mammalian expression specialists, CDMO procurement managers, and academic core facility directors and refined through secondary validation. Sources included FDA biologic licensing filings, EMA GMP submission databases, NMPA biosimilar comparability guidelines, and WHO prequalification pathways. Bottom-up protein production volume estimates were triangulated against top-down biopharmaceutical pipeline expenditure analysis.
Variance-decomposition across product type, application, end user, and delivery mode segments shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level growth trajectory modeling incorporating cell-free expression technology adoption curves and pandemic preparedness contracting patterns. Industry-specific inputs included host cell protein impurity detection threshold evolution and glycosylation pattern equivalence demonstration requirements.
Decision-makers should treat outputs as directional under assumptions of sustained EMA-FDA regulatory convergence and continued NMPA enforcement intensity; material deviation in plasmid DNA supply availability or cell-free system characterization guidance would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Transient Protein Expression Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Mutation Generation Systems Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Synthetic Stem Cells Market