
 Middle East and Africa Biologics and Biosimilar Market | 2026-2036
Middle East and Africa Biologics and Biosimilar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biologics and Biosimilar Market Foresight
South Korean contract development and manufacturing organizations is expanding biologics production capacity serving Middle East and Africa markets. Samsung Biologics Co Ltd anchors large-scale mammalian cell culture output for regional supply. Celltrion Inc. leverages cost-efficient biosimilar manufacturing to compete across North African tenders. Pfizer Inc. sustains brand recognition among hospital formularies through established oncology portfolios.
Biologics and biosimilars comprise large-molecule therapeutics derived from living cells through recombinant DNA technology, microbial fermentation, or mammalian cell culture, with molecular weights typically exceeding 5,000 Daltons and structural complexity that precludes exact generic replication. These products treat autoimmune disorders, cancers, and chronic diseases by targeting specific cellular pathways rather than broad symptomatic relief. Monoclonal antibodies occupy the dominant revenue position due to established efficacy in oncology and immunology indications across Middle Eastern tertiary hospitals. Vaccines represent the fastest-expanding segment driven by national immunization program scale-up in Sub-Saharan Africa. Recombinant proteins maintain stable demand through insulin and growth hormone procurement by Egypt's public health authorities.
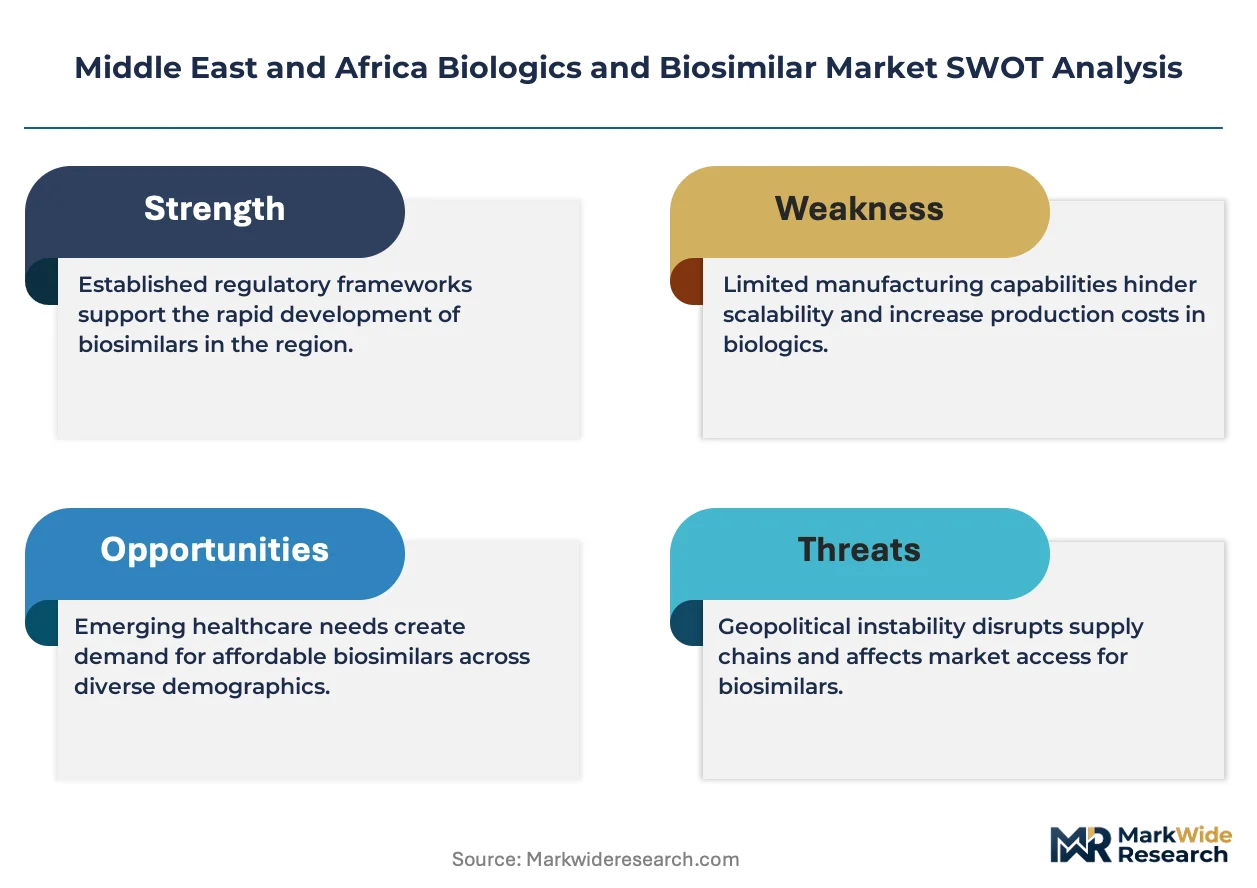
South Africa's SAHPRA operates under WHO prequalification frameworks to streamline biosimilar approval timelines, while Saudi FDA enforces GCC harmonized standards for biologics cold-chain integrity. Egypt's drug authority mandates local bioequivalence studies for biosimilar registration, creating regulatory bottlenecks that favor manufacturers with regional clinical trial infrastructure. Stakeholders must monitor evolving pharmacovigilance requirements across Gulf Cooperation Council states as these jurisdictions tighten post-market surveillance for immunogenicity reporting.
Market Dynamics
SAHPRA's WHO prequalification alignment is compressing biosimilar approval timelines across Southern Africa while Saudi FDA cold-chain mandates are reshaping distribution infrastructure requirements for temperature-sensitive biologics.
Growth Catalysts
- SAHPRA Harmonization:South Africa's medicines regulator adopted WHO prequalification frameworks, eliminating redundant clinical trial requirements for biosimilars already approved by stringent regulatory authorities.
- Oncology Infrastructure:Saudi Arabian tertiary hospitals are expanding dedicated biologics infusion centers, creating pull-through demand for monoclonal antibody therapies in immunology and hematology indications.
- Microbial Fermentation:Advances in single-use bioreactor technology are reducing capital barriers for regional biosimilar production, enabling contract manufacturers to serve North African tender markets.
Market Restraints
- Plasma Supply Concentration:Regional dependence on imported human plasma for immunoglobulin production creates vulnerability to US and European collection center output fluctuations.
- Egyptian Bioequivalence Mandate:Egypt's drug authority requires local pharmacokinetic studies for biosimilar registration, extending timelines and favoring manufacturers with existing clinical infrastructure.
- Substitute Therapy Displacement:Small-molecule JAK inhibitors in rheumatoid arthritis are eroding TNF-alpha inhibitor volumes in South African private medical schemes.
Strategic Opportunities
- Sub-Saharan Vaccine Manufacturing:WHO's mRNA technology transfer hub in South Africa creates regional fill-finish capacity for pandemic preparedness and routine immunization programs.
- Insulin Biosimilar Tenders:Egypt's public hospital procurement system represents concentrated demand for recombinant human insulin and insulin analog products.
- Continuous Bioprocessing Convergence:Integration of perfusion cell culture with real-time quality monitoring enables cost-competitive biosimilar output for Gulf Cooperation Council markets.
Industry Challenges
- Cell Culture Specialist Scarcity:Mammalian cell line development and upstream process optimization expertise remains concentrated in South Korean and European contract development organizations.
- Cold-Chain Capex Burden:Saudi FDA and MOHAP validation requirements for 2-8°C distribution create multimillion-dollar infrastructure commitments for logistics providers.
- Immunogenicity Surveillance Complexity:GCC pharmacovigilance systems lack standardized anti-drug antibody detection protocols, complicating post-market safety monitoring for biosimilar switching programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biologics and Biosimilar Market |
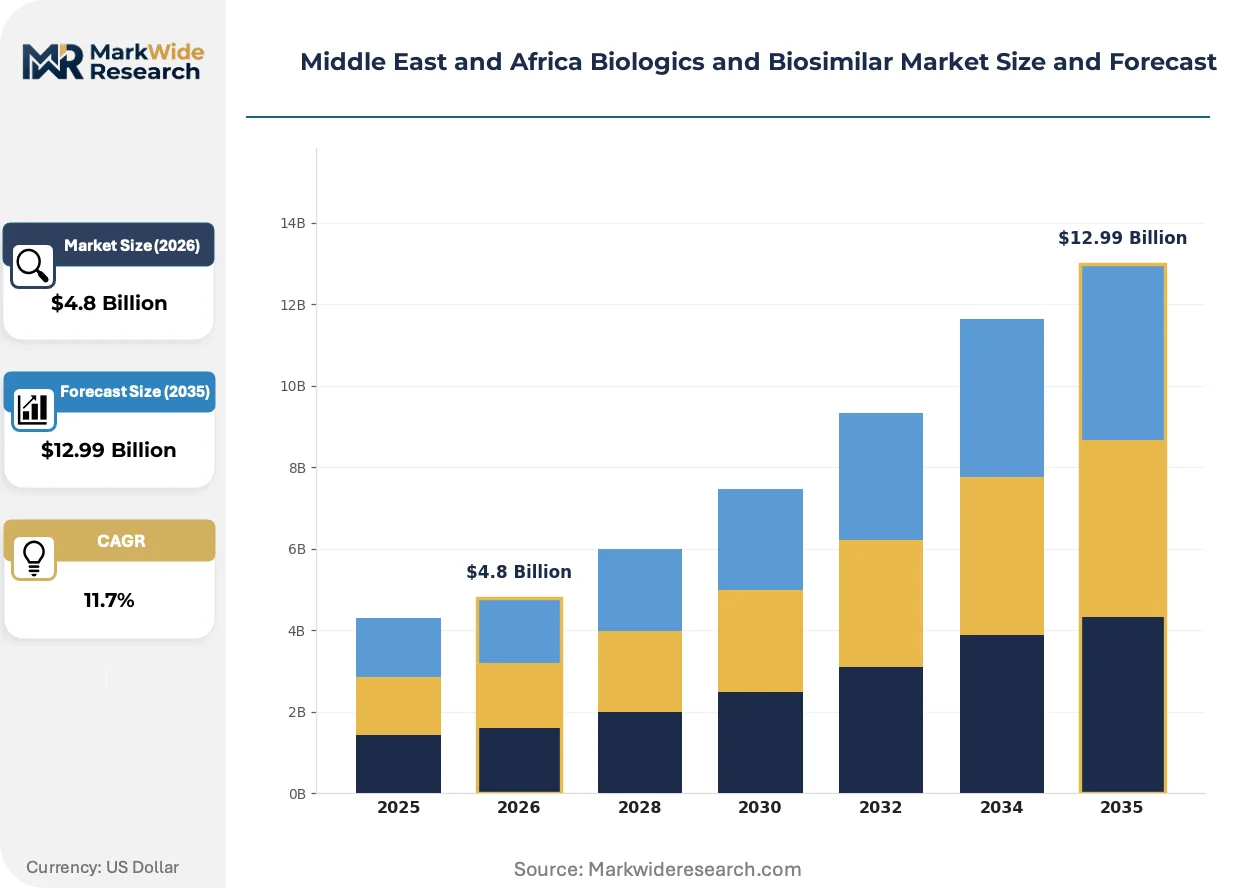
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Cell and Gene Therapy, Recombinant Proteins Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral End User: Hospitals, Clinics, Research Laboratories, Retail Pharmacies Therapy Area: Oncology, Immunology, Neurology, Infectious Diseases |
| Companies Covered | Pfizer Inc., AbbVie Inc., Amgen Inc., F. Hoffmann-La Roche Ltd, Celltrion Inc., Samsung Biologics Co Ltd, Sandoz, Johnson & Johnson, Hikma Pharmaceuticals, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biologics and Biosimilar Market Shifts & Advancements
Single-use bioreactor systems are overtaking stainless-steel infrastructure as the dominant production platform, while regulatory convergence and procurement centralization are compressing competitive timelines across the region.
Single-use bioreactor technology is overtaking traditional stainless-steel vessel systems in regional contract manufacturing. Saudi Arabian and South African production facilities are adopting disposable bag-based cell culture to reduce cross-contamination risks and enable rapid product changeovers. This shift is overtaking the economic advantage of large-scale stainless-steel investments for mid-volume biosimilar batches.
SAHPRA's adoption of WHO prequalification standards is streamlining biosimilar registration pathways for manufacturers with prior European Medicines Agency or US FDA approvals. The policy eliminates redundant local clinical trials, compressing time-to-market from 36 months to 18 months for eligible products. Egyptian and Moroccan regulators are observing this framework for potential harmonization, though Egypt maintains its local bioequivalence study requirement.
Centralized tender procurement through Egypt's Holding Company for Biological Products and Vaccines is consolidating purchasing power for insulin and growth hormone products. Hospital formulary committees in Saudi Arabia are adopting therapeutic interchange protocols for biosimilar substitution, displacing physician-driven brand selection. This concentration is most visible in Cairo's public hospital network, where annual insulin procurement volumes exceed 50 million units.
Middle East and Africa Biologics and Biosimilar Market Segmentation
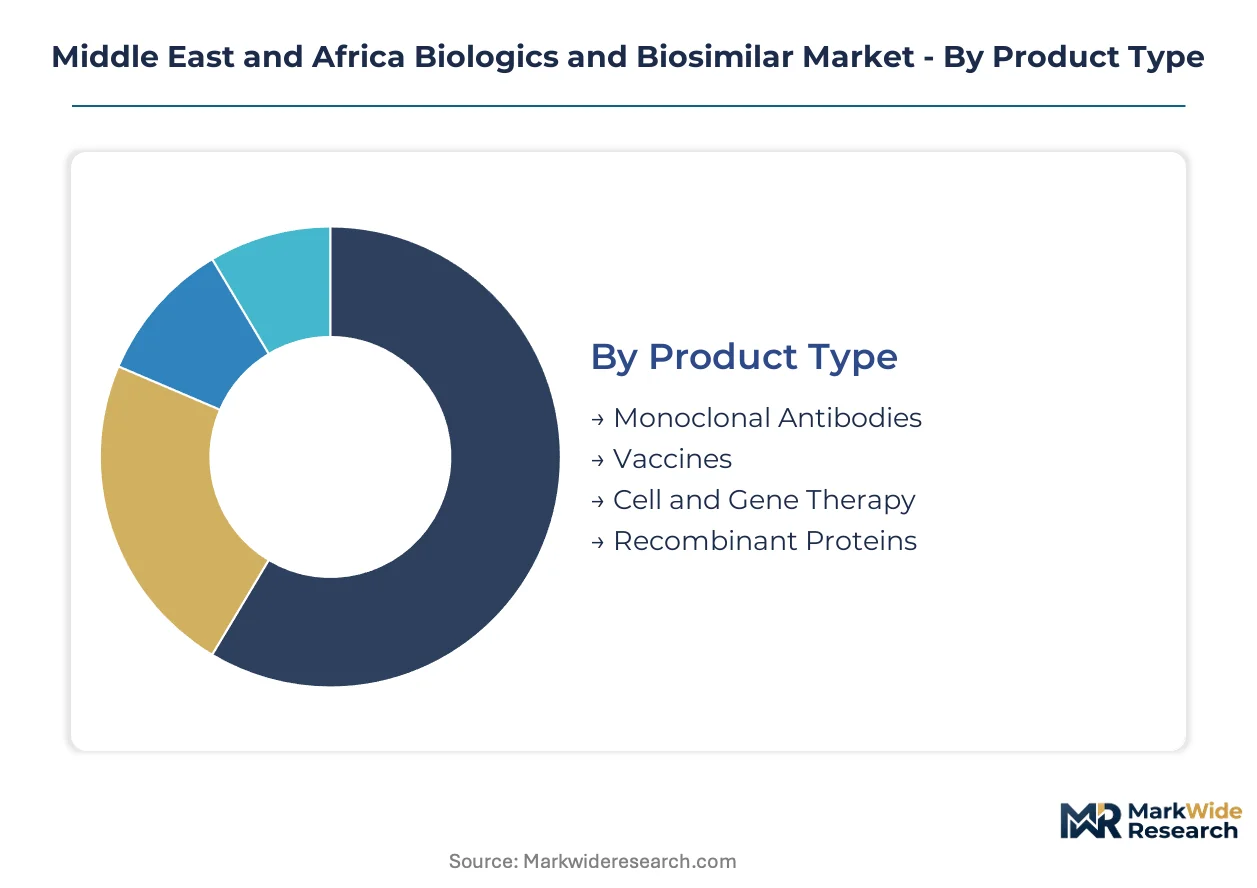
Segmentation in the Middle East and Africa biologics and biosimilar market reveals distinct procurement patterns across public health systems and private channels. Understanding these divides enables manufacturers to align cold-chain infrastructure, regulatory submissions, and tender strategies with specific buyer capabilities and priorities.
Product Type:
Hospital formulary committees differentiate products primarily by storage complexity and infusion infrastructure requirements, with tertiary centers in Saudi Arabia and South Africa possessing markedly different capabilities than regional facilities.
- Monoclonal Antibodies:Large glycoprotein therapeutics produced through mammalian cell culture, typically requiring 2-8°C cold-chain maintenance throughout distribution. Demand concentrates in Saudi Arabian oncology departments expanding dedicated infusion centers, though high per-dose costs strain Egypt's public procurement budgets.
- Vaccines:Antigen-based preventive products spanning recombinant subunit to mRNA platforms, with temperature sensitivity varying by formulation. Sub-Saharan African national immunization programs drive volume procurement through UNICEF and Gavi channels, while South Africa's WHO mRNA technology transfer hub builds regional fill-finish autonomy.
- Cell and Gene Therapy:Autologous and allogeneic cellular products requiring cryogenic logistics and specialized treatment centers. Egypt's Holding Company for Biological Products and Vaccines has limited procurement exposure given infrastructure constraints.
- Recombinant Proteins:Insulin, growth hormone, and interferon products manufactured via microbial fermentation or mammalian expression. Egyptian public hospitals represent concentrated demand for recombinant human insulin, with annual procurement volumes exceeding 50 million units through centralized tender.
Monoclonal antibodies lead volumes today; vaccines are gaining share fastest.
Delivery Mode:
Route selection tracks directly with care setting infrastructure, as home-based administration capability varies dramatically between South African private medical schemes and Egypt's public hospital network.
- Subcutaneous:Self-administered injection requiring patient training programs and cold-chain extension to retail pharmacies. South African private schemes favor subcutaneous TNF-alpha inhibitors for rheumatoid arthritis to reduce hospital day-ward burden.
- Intravenous:Infusion-dependent delivery mandating hospital-based administration with oncology nursing specialization. Saudi Arabian tertiary hospitals are expanding dedicated biologics infusion centers to accommodate rising monoclonal antibody volumes in hematology and immunology.
- Intramuscular:Vaccine-standard administration suited to mass immunization campaigns and routine pediatric schedules. Sub-Saharan African national programs drive concentrated demand for intramuscular delivery through primary health center networks.
- Oral:Limited applicability for large-molecule biologics due to gastrointestinal degradation; primarily relevant to biosimilar-related small-molecule adjuvants and supportive care medications.
Intravenous delivery dominates revenue today; subcutaneous formats are expanding most quickly.
End User:
Procurement authority fragmentation creates divergent commercial pathways, with centralized tenders in Egypt contrasting physician-driven formulary decisions in Saudi private hospitals.
- Hospitals:Tertiary and secondary acute care facilities with cold-chain infrastructure and specialist prescribing capacity. Saudi Arabian hospital formulary committees are adopting therapeutic interchange protocols that displace physician-driven brand selection with biosimilar substitution mandates.
- Clinics:Outpatient settings with limited biologics handling capability, primarily accessing vaccines and subcutaneous products. Egyptian primary health centers rely on central depot distribution for insulin and growth hormone products.
- Research Laboratories:Academic and clinical trial sites conducting local bioequivalence studies required by Egypt's drug authority for biosimilar registration.
- Retail Pharmacies:Community dispensing points with variable cold-chain integrity, concentrated in South African urban centers and Saudi Arabian pharmacy chains.
Hospitals command the largest share today; clinics are climbing the fastest as subcutaneous self-administration expands.
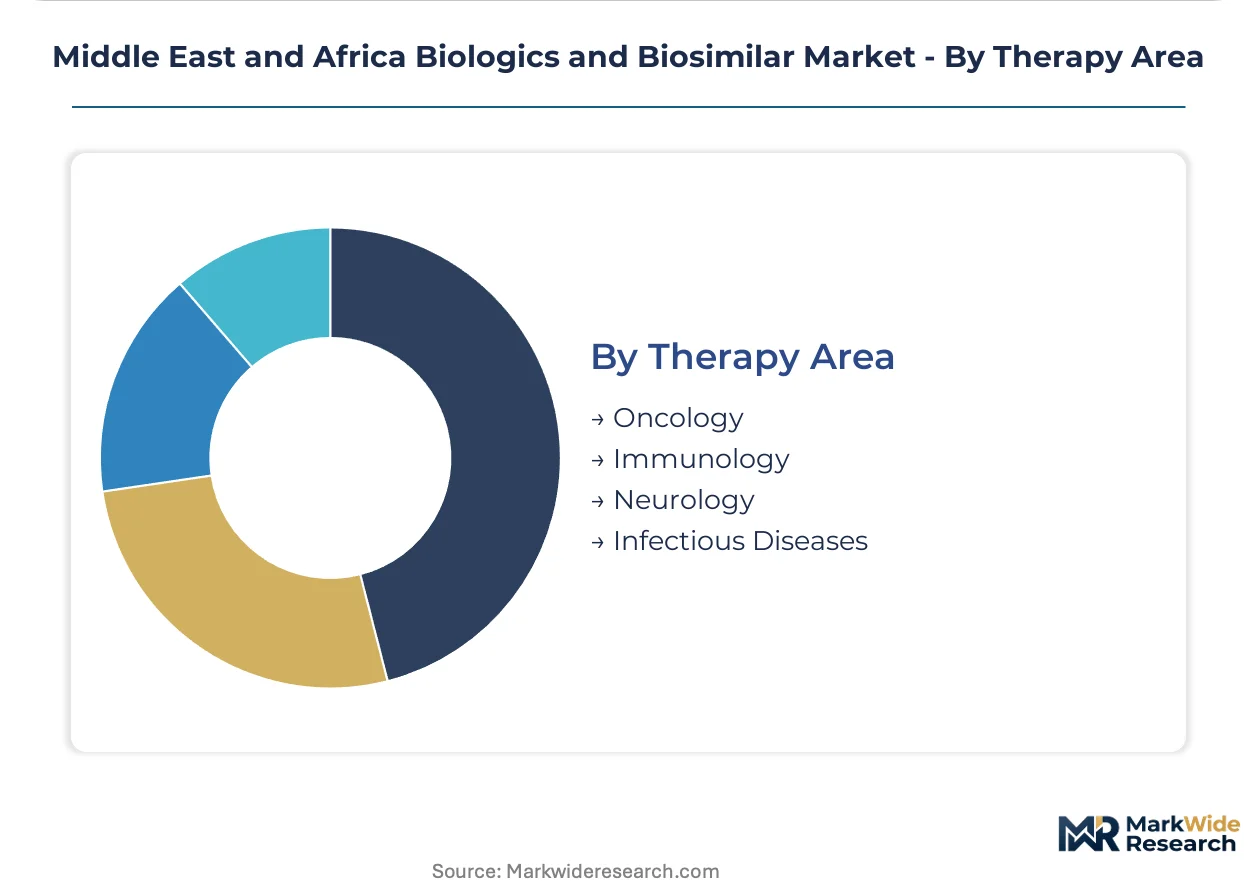
Therapy Area:
Reimbursement and tender prioritization reflect disease burden demographics and health system financing structures across the region's heterogeneous economies.
- Oncology:Solid tumor and hematologic malignancy treatments dominating monoclonal antibody utilization. Saudi Arabian tertiary hospitals are expanding dedicated biologics infusion centers, creating pull-through demand for checkpoint inhibitors and anti-CD20 therapies.
- Immunology:Autoimmune and inflammatory condition management spanning rheumatoid arthritis, psoriasis, and inflammatory bowel disease. South African private medical schemes are experiencing volume erosion as small-molecule JAK inhibitors displace TNF-alpha inhibitors in rheumatoid arthritis.
- Neurology:Multiple sclerosis and rare disease biologics with limited regional market penetration due to diagnostic capacity constraints and high therapy costs.
- Infectious Diseases:HIV, hepatitis, and emerging pathogen therapeutics including long-acting monoclonal antibodies. Sub-Saharan African programs concentrate demand through PEPFAR and Global Fund procurement channels.
Oncology leads volumes today; immunology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Gulf Cooperation Council harmonization and North African localization mandates is redirecting biologics manufacturing investment toward jurisdictions with streamlined approval pathways and established clinical trial infrastructure.
Saudi Arabia
Oncology departments at King Faisal Specialist Hospital and Research Centre are expanding dedicated biologics infusion centers for monoclonal antibody therapies. Saudi FDA enforces GCC harmonized standards for 2-8°C cold-chain integrity across distribution networks. Riyadh's King Abdullah International Medical Research Center anchors regional pharmacovigilance capabilities for post-market immunogenicity surveillance.
South Africa
SAHPRA's WHO prequalification alignment is compressing biosimilar approval timelines from 36 months to 18 months for products with prior stringent regulatory authority approvals. The country's national immunization program drives concentrated vaccine procurement through UNICEF and Gavi channels. Cape Town's WHO mRNA technology transfer hub is building regional fill-finish autonomy for pandemic preparedness and routine immunization scale-up.
Egypt
Egypt's public hospital procurement system represents concentrated demand for recombinant human insulin, with annual volumes exceeding 50 million units through centralized tender. The country's drug authority mandates local bioequivalence studies for biosimilar registration, creating regulatory bottlenecks that favor manufacturers with existing clinical infrastructure. Cairo's Holding Company for Biological Products and Vaccines consolidates purchasing power for insulin and growth hormone products.
United Arab Emirates
MOHAP validation requirements for temperature-sensitive biologics distribution are reshaping logistics infrastructure commitments across the Emirates. The country's pharmaceutical regulator maintains alignment with GCC standards while permitting accelerated access pathways for innovative therapies. Dubai's Jebel Ali pharmaceutical free zone clusters regional distribution operations for temperature-controlled biologics serving Gulf markets.
Morocco
The national medicines regulator is observing SAHPRA's WHO prequalification framework for potential harmonization, though maintaining independent assessment pathways. Public hospital procurement concentrates demand for recombinant proteins and established biosimilar products. Casablanca's pharmaceutical manufacturing zone is attracting contract manufacturing investment targeting North African tender markets and Francophone Sub-Saharan access.
Middle East and Africa Biologics and Biosimilar Market Competitive Landscape
South Korean producers anchor the contract manufacturing tier; European and US originators hold branded biologics positions. The market structure fragments across three distinct tiers: multinational pharmaceutical conglomerates with established oncology portfolios, specialized biosimilar developers leveraging cost-efficient manufacturing platforms, and regional contract manufacturers serving tender-driven procurement systems. Consolidation pressure operates through capacity expansion in mammalian cell culture and strategic technology licensing for single-use bioreactor platforms.
Within the contract manufacturing archetype, Samsung Biologics Co Ltd and Celltrion Inc. exemplify scale-driven production capabilities serving Middle East and Africa markets. Pfizer Inc. occupies a position among originator-tier multinationals with sustained hospital formulary recognition. These three entities represent divergent strategic postures: Korean CDMOs compete on cost-efficient output for regional tenders, while US-based incumbents defend positions through established infusion center relationships and oncology portfolio breadth.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| Celltrion Inc. |
| Samsung Biologics Co Ltd |
| Sandoz |
| Johnson & Johnson |
| Hikma Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Single-use bioreactor adoption across Saudi Arabian and South African production facilities simultaneously compresses per-batch manufacturing costs and fragments supply concentration away from large-scale stainless-steel investments. This technology shift enables mid-volume contract manufacturers to compete for North African tender contracts, redistributing pricing power toward regional players with flexible output capabilities.
Pricing Analysis
Distributor margins for cold-chain biologics in Egypt's public procurement system absorb substantial logistics validation costs mandated by the country's drug authority. Three-tier pricing structure across originator monoclonal antibodies, licensed biosimilars, and unbranded alternatives reflects certification grade and local bioequivalence study completion. Cost compression in the biosimilar tier intensifies as Celltrion and Samsung Biologics expand mammalian cell culture output for regional tenders. Egyptian public hospitals exhibit highest price sensitivity due to centralized annual procurement volumes exceeding 50 million insulin units, while Saudi Arabian private tertiary centers maintain lowest sensitivity through therapeutic interchange protocols that prioritize clinical outcomes over per-dose costs.
Supply Chain Analysis
Reverse-logistics capabilities for temperature-deviated biologics remain underdeveloped across Middle East and African distribution networks, forcing destruction protocols that inflate effective supply costs. Manufacturing concentration rests on South Korea for contract mammalian cell culture, India for microbial fermentation-derived recombinant proteins, and European Union member states for plasma-derived immunoglobulins. Raw material dependencies include imported cell culture media, single-use bioreactor bags, and US-sourced human plasma. Single-source vulnerability concentrates in plasma collection networks controlled by North American and European operators. Distribution runs through Dubai's Jebel Ali pharmaceutical free zone for Gulf Cooperation Council markets, with Johannesburg and Cairo anchoring Southern and North African hub operations respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa biologics market represents a late-cycle quality story as Saudi Arabian and South African hospital formulary committees pivot procurement criteria toward cold-chain integrity documentation and post-market immunogenicity surveillance capabilities.
For Market Incumbents: Anticipate margin compression in Egyptian insulin tenders as Samsung Biologics and Celltrion expand regional fill-finish partnerships. Defensive consolidation should prioritize backward integration into plasma collection networks to reduce dependence on US and European supply. Capacity addition in Casablanca's pharmaceutical manufacturing zone captures North African tender access while satisfying Moroccan regulatory observation of WHO prequalification frameworks. For New Entrants and Emerging Players: Begin with subcutaneous biosimilar formats for South African private medical schemes, where rheumatoid arthritis patient self-administration programs reduce hospital day-ward burden and unlock volume displacement of intravenous TNF-alpha inhibitors. The most penetrable segment sits in Egyptian recombinant human insulin procurement, where centralized tender volumes create scale economies for microbial fermentation specialists. Go-to-market execution should anchor on local bioequivalence study partnerships with Cairo-based research laboratories to satisfy Egypt's drug authority registration requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contract manufacturers with validated cold-chain infrastructure but limited originator portfolio breadth. Long-term viability across the analysis window hinges on regulatory convergence toward WHO prequalification standards compressing approval timelines and consolidating competitive positions. Acquisition targets should display mammalian cell culture capability paired with existing GCC distribution relationships. The signal to watch is SAHPRA's influence on Egyptian and Moroccan regulator harmonization, which would eliminate local clinical trial requirements and revalue manufacturers with prior stringent regulatory authority approvals.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Samsung Biologics' mammalian cell culture expansion secures regional monoclonal antibody supply for Saudi Arabian oncology infusion centers. |
| Regulatory Approval Pathway | SAHPRA's WHO prequalification alignment eliminates redundant clinical trials, compressing biosimilar time-to-market for eligible products. |
| Backward Integration | Plasma collection network investments reduce vulnerability to North American supply fluctuations for immunoglobulin manufacturers. |
| Licensing Agreement | Single-use bioreactor technology transfers enable regional contract manufacturers to serve North African tender markets. |
| Hospital System Partnership | Therapeutic interchange protocols with Saudi Arabian formulary committees displace physician-driven brand selection with biosimilar substitution. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down CDMO capacity tracking forms the analytical core of this study. Primary interviews with Saudi Arabian formulary directors, Egyptian public hospital procurement managers, South African private medical scheme pharmacy leads, and regional regulatory affairs specialists combined with secondary validation against SAHPRA registration databases, Saudi FDA guidance documents, Egypt's Holding Company for Biological Products and Vaccines tender records, and WHO prequalification listings. Triangulation across these sources ensures demand-side estimates align with supply-side manufacturing capacity disclosures.
Input-output matrices connect patient population epidemiology, treatment penetration rates, and dosing frequencies to derive volume forecasts across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end-user facility tier, therapy area, and regional regulatory cluster. CAGRs emerge from iterative reconciliation of bottom-up demand build and top-down supply capacity expansion trajectories. Forecast inputs incorporate single-use bioreactor adoption curves, cold-chain infrastructure investment pipelines, and regulatory harmonization probability assessments.
Several conditions sit outside the modeled scope, including pandemic-related supply disruptions, abrupt plasma collection network shutdowns, and geopolitical trade restrictions affecting Korean CDMO export licenses. Forecasts reflect assumptions around continued WHO prequalification framework adoption and stable GCC regulatory alignment. Practitioners should monitor SAHPRA's bilateral engagement with Egyptian and Moroccan regulators, plasma fractionation capacity announcements in North America and Europe, and Saudi FDA pharmacovigilance system upgrades for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biosimilars
Global Biosimilar Testing and Development Services Market
Biosimilars
Europe Generic Injectables Market
Biosimilars
Imatinib Drug Market
Biosimilars
Global Tofacitinib Market
Biosimilars
Retinal Biosimilars Market
Biosimilars
Biosimilar Contract Manufacturing Market
Biosimilars
Adalimumab Biosimilar Market
Biosimilars
Biosimilar and Follow-On Biologics Market
Biosimilars
Global Tumor Necrosis Factor (TNF) Inhibitor Drugs Market
Biosimilars
Biologics and Biosimilars Market
Biosimilars
Oncology Biosimilars Market
Biosimilars
Tumor Necrosis Factor Inhibitor Market
Biosimilars
Dasatinib Market
Biosimilars
Remicade Biosimilar Market
Biosimilars
US Biosimilars Market
Biosimilars
Biosimilar Testing Services Market