
 Enzymatic Cleaning Market | 2026-2036
Enzymatic Cleaning Market Size, Share, and Industry Trends Forecast 2026-2036
Enzymatic Cleaning Market Foresight
The capital-intensity divergence between large-scale fermentation-based enzyme producers and regional formulators is unwinding competitive stability in enzymatic cleaning. Novozymes A/S leverages its submerged fermentation infrastructure and strain development libraries to dominate industrial-grade protease and lipase supply. Ecolab Inc. anchors its position through captive distribution into healthcare and food processing accounts, bundling enzymatic chemistries with dispensing equipment and audit services.
Enzymatic cleaning refers to formulations incorporating specific protein catalysts—primarily proteases, amylases, lipases, and cellulases at typical concentrations of 0.5–5% active enzyme by weight—to hydrolyze organic soils at temperatures between 20°C and 60°C and pH ranges of 6.5–9.5, replacing or reducing alkaline chlorinated compounds in pre-cleaning and main wash cycles. Liquid cleaners lead product type demand due to dosing precision and compatibility with automated dispensing systems in hospitals and central sterile services, while gel cleaners represent the fastest-growing format where cling time and vertical surface application matter in endoscope and surgical instrument pre-soak protocols. Among applications, healthcare generates the deepest margin pools because validated cleaning chemistries command premium pricing tied to accreditation standards, whereas food processing offers volume scale driven by allergen control mandates and clean-in-place system retrofits.
The EPA regulates enzymatic cleaning products under FIFRA when antimicrobial claims attach, while OSHA bloodborne pathogen standards mandate effective pre-cleaning of contaminated instruments, directly shaping hospital procurement specifications. In Europe, the EU Green Deal and REACH restrictions on persistent organic pollutants are forcing reformulation away from quaternary ammonium adjuncts toward standalone enzymatic systems. Stakeholders must monitor regulatory divergence between jurisdictions on enzyme registration requirements and biodegradability certification thresholds to avoid supply chain fragmentation and reformulation cost spikes.
Market Dynamics
The enzymatic cleaning market is reconfiguring around supply-side concentration in industrial enzyme production and downstream formulation fragmentation, creating margin compression for regional blenders while fermentation-scale producers capture value from strain optimization and toll manufacturing contracts.
Growth Catalysts
- EPA Safer Choice program:The US EPA's surfactant restrictions are accelerating hospital procurement of biodegradable pre-soak formulations that replace chlorinated alkaline chemistries in surgical instrument reprocessing workflows.
- Healthcare infection control budgets:United States, Germany, and Japan are expanding dedicated line items for validated enzymatic detergents tied to Joint Commission, KRINKO, and JIS accreditation standards.
- Fermentation-scale enzyme production:Submerged fermentation infrastructure investments are lowering unit costs for protease and lipase concentrates, enabling formulators to hit performance parity with legacy chemistries at neutral pH.
Market Restraints
- Enzyme supply concentration:Three fermentation-based producers control approximately 70% of industrial-grade protease supply, creating vulnerability to strain contamination events or Danish agricultural input cost spikes.
- Temperature stability limitations:Lipase and cellulase activity degrades above 60°C, restricting application in high-temperature clean-in-place systems prevalent in dairy and beverage processing.
- REACH registration friction:ECHA's evolving requirements for enzyme protein respiratory sensitization data are extending reformulation timelines and elevating toxicology study costs for EU market entrants.
Strategic Opportunities
- India hospital sector:NABH accreditation expansion and CDSCO medical device rules are creating first-mover advantage for enzymatic pre-cleaning protocols in tier-2 and tier-3 cities.
- EU Green Deal bioeconomy incentives:Standalone enzymatic systems qualify for circular procurement preferences in public healthcare tenders, displacing quaternary ammonium adjuncts.
- Endoscope reprocessing automation:Integration of gel-format enzymatic cleaners with automated leak testers and washer-disinfectors is opening premium positioning in ambulatory surgery center channels.
Industry Challenges
- Enzymologist talent scarcity:Formulation chemistry expertise combining protein engineering with surfactant science concentrates in Copenhagen and Basel, constraining regional R&D expansion.
- Validation protocol timelines:FDA 510(k) clearance for enzymatic cleaners with antimicrobial claims requires 18-24 month efficacy studies against Mycobacterium terrae and Bacillus subtilis spores.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enzymatic Cleaning Market |
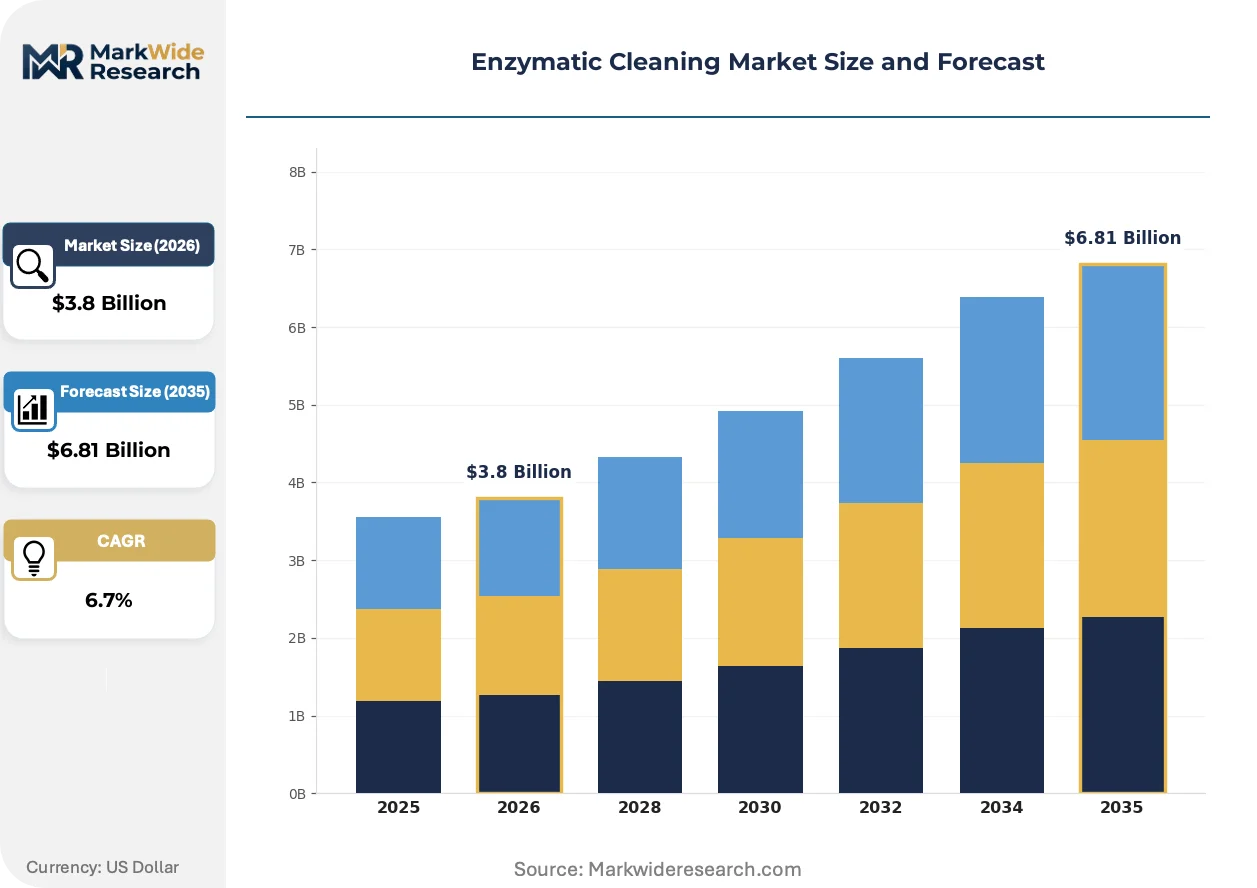
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cleaners, Powder Cleaners, Gel Cleaners, Foam Cleaners Application: Healthcare, Food Processing, Manufacturing, Automotive End User: Hospitals, Restaurants, Factories, Laboratories Technology: Biotechnology, Chemical Engineering, Microbial Technology, Green Technology |
| Companies Covered | Novozymes A/S, Ecolab Inc., Reckitt Benckiser Group PLC, BASF SE, Diversey Holdings, STERIS Corporation, Henkel, Clorox Company, SC Johnson Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enzymatic Cleaning Market Shifts & Advancements
Formulation chemistry is pivoting toward enzyme-surfactant synergy optimization and automated dosing compatibility, while regulatory pressure on persistent organic pollutants accelerates displacement of legacy active ingredients across healthcare and food processing verticals.
Engineered extremophile proteases derived from Antarctic and deep-sea microbial sources are displacing mesophilic enzymes in cold-water pre-soak applications. Hospital sterile processing departments in Germany and Japan are adopting these variants to reduce energy consumption in instrument reprocessing. The technology is displacing heated detergent baths and enabling accreditation-compliant cleaning at 20-30°C tap water temperatures.
REACH restrictions on quaternary ammonium compounds are forcing reformulation of hospital-grade disinfectant adjuncts across EU member states. ECHA's 2023-2025 substance evaluation roadmap targets benzalkonium chloride and didecyldimethylammonium chloride for respiratory and aquatic toxicity concerns. Healthcare procurement specifications in France and the Netherlands are responding by mandating standalone enzymatic systems without QAC boosters.
Outcome-based service contracts bundling enzymatic chemistry with dispensing equipment and compliance auditing are displacing transactional chemical supply in US hospital systems. Group purchasing organizations are consolidating vendor panels around full-service reprocessing partnerships. The shift is most visible in IDN-affiliated ambulatory surgery centers seeking to outsource sterile processing validation liability.
Enzymatic Cleaning Market Segmentation
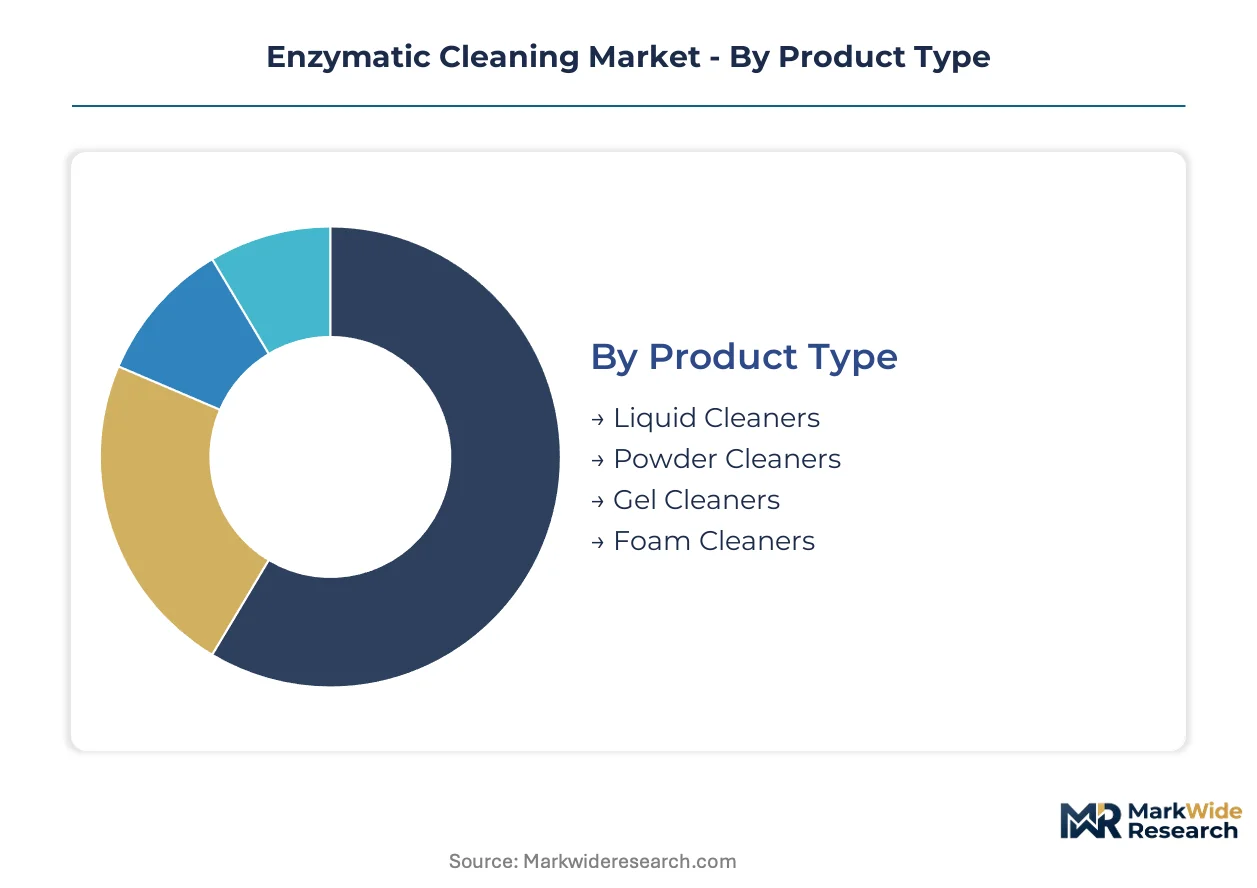
Segmentation in enzymatic cleaning reveals how formulation chemistry, application protocols, and procurement specifications create divergent margin structures. Understanding these divides exposes where fermentation-scale producers capture value versus where regional blenders face compression.
Product Type:
Premium pricing concentrates in formats compatible with automated dispensing infrastructure and validated reprocessing workflows.
- Liquid Cleaners:Aqueous formulations containing 0.5–5% active enzyme by weight enable precise dosing through peristaltic pumps and central sterile supply automation. Demand clusters in US and German hospital systems where Joint Commission and KRINKO accreditation mandate documented detergent delivery. The EPA Safer Choice program accelerates displacement of chlorinated alkaline pre-soaks in surgical instrument reprocessing.
- Gel Cleaners:Thixotropic formulations engineered for vertical surface adhesion and extended contact time on endoscope lumens and surgical instrument joints. Adoption is climbing fastest in ambulatory surgery centers and Japanese tertiary hospitals integrating automated leak testers with pre-soak stations.
- Powder Cleaners:Granular concentrates offering freight cost advantages for bulk institutional procurement in food processing and manufacturing sectors.
- Foam Cleaners:Aerosol or pump-dispensed surfactant-enzyme blends targeting spot-cleaning applications in automotive detailing and laboratory equipment maintenance.
The dominant share belongs to Liquid Cleaners, while Gel Cleaners are expanding most quickly through endoscope reprocessing automation.
Application:
Regulatory validation requirements and accreditation standards create steep margin tiers across end-use verticals.
- Healthcare:Surgical instrument reprocessing, endoscope pre-cleaning, and sterile supply department workflows demand enzymatic detergents validated against blood, tissue, and biofilm soils. US hospitals allocate dedicated infection control budgets for FDA-cleared or EPA-registered formulations tied to Joint Commission surveys.
- Food Processing:Clean-in-place system retrofits and allergen control protocols drive volume procurement of protease and lipase concentrates for dairy, beverage, and protein processing equipment. REACH restrictions on quaternary ammonium compounds are forcing standalone enzymatic adoption in EU member states.
- Manufacturing:Precision equipment cleaning and metalworking fluid maintenance utilize enzymatic degreasers for biodegradable soil removal without solvent exposure.
- Automotive:Parts washing and detailing applications employ enzymatic formulations for petroleum hydrocarbon degradation in wastewater-compliant operations.
Healthcare commands the steepest price premiums, with Food Processing delivering the deepest volume scale.
End User:
Procurement sophistication and compliance liability separate price-realization tiers across customer categories.
- Hospitals:Central sterile services departments and endoscopy units purchase through group purchasing organizations or integrated delivery networks, bundling enzymatic chemistry with equipment service contracts. Outcome-based partnerships are displacing transactional supply in US IDN-affiliated facilities.
- Restaurants:Commercial kitchen operations deploy enzymatic drain maintainers and grease trap treatments under municipal fat, oil, and grease ordinances.
- Factories:Industrial maintenance departments specify enzymatic cleaners for equipment hygiene without corrosion damage to sensitive alloys.
- Laboratories:Research and clinical diagnostic facilities require residue-free enzymatic detergents for glassware and analytical instrument cleaning.
Hospitals retain the largest value share, though procurement consolidation is compressing margins for non-integrated suppliers.
Technology:
Strain optimization capabilities and fermentation scale determine competitive moats within each technology pathway.
- Biotechnology:Recombinant DNA and protein engineering platforms enable tailored enzyme specificity for target soil substrates, with extremophile proteases from Antarctic microbial sources gaining traction for cold-water applications.
- Chemical Engineering:Surfactant-enzyme synergy optimization and formulation stability science concentrate expertise in Basel and Copenhagen technical centers.
- Microbial Technology:Solid-state and submerged fermentation infrastructure for bulk enzyme concentrate production.
- Green Technology:Biodegradability certification and renewable feedstock integration for circular procurement compliance.
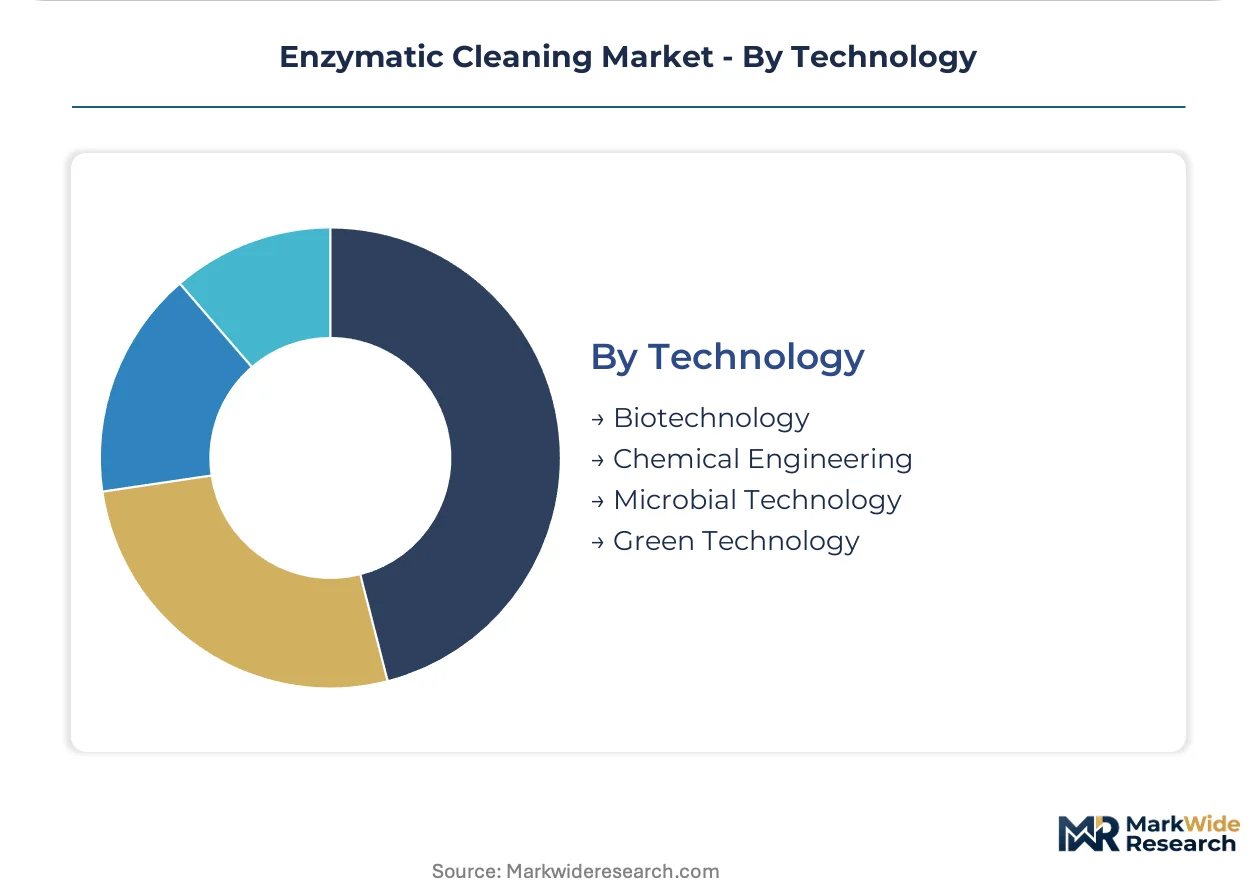
Biotechnology anchors the highest-margin segment, while Green Technology is gaining share fastest through EU public tender preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital infection control budgets in Japan and Germany absorb price premiums without volume elasticity, while procurement officers in India and Brazil negotiate aggressively on unit costs even as accreditation requirements tighten. This demand-elasticity contrast shapes where enzymatic cleaning suppliers capture margin versus where they compete on price.
United States
Joint Commission surveys and OSHA bloodborne pathogen standards mandate documented pre-cleaning protocols in over 6,000 hospitals. The EPA Safer Choice program restricts surfactants in institutional formulations, accelerating displacement of chlorinated alkaline chemistries. The Boston-Cleveland corridor concentrates sterile processing innovation, with IDN-affiliated ambulatory surgery centers bundling enzymatic chemistry with equipment service contracts.
Germany
KRINKO guidelines and EU Green Deal circular procurement preferences drive standalone enzymatic system adoption without quaternary ammonium adjuncts. REACH restrictions on benzalkonium chloride force reformulation timelines across hospital disinfectant portfolios. The Rhine-Ruhr and Baden-Württemberg clusters host central sterile services departments piloting cold-water extremophile protease protocols to reduce energy consumption.
Japan
JIS standards and METI industrial hygiene directives enforce stringent validation requirements for surgical instrument reprocessing chemistries. Hospital infection control budgets allocate dedicated line items for enzymatic detergents with documented efficacy against biofilm soils. The Kanto and Kansai metropolitan areas lead endoscope reprocessing automation, integrating gel-format enzymatic cleaners with washer-disinfector systems.
India
NABH accreditation expansion into tier-2 and tier-3 cities creates first-mover advantage for enzymatic pre-cleaning protocols in surgical centers. CDSCO medical device rules tighten cleaning validation requirements for imported and domestic instruments. Maharashtra and Karnataka hospital clusters represent the fastest-growing procurement volumes as private healthcare chains standardize sterile processing infrastructure.
United Kingdom
NHS procurement frameworks prioritize biodegradable cleaning chemistries aligned with net-zero carbon targets for hospital estates. Health Technical Memoranda specify enzymatic detergent performance standards for surgical instrument decontamination. The Greater Manchester and West Midlands hospital networks concentrate sterile processing department consolidation, driving volume contracts with full-service reprocessing partners.
Enzymatic Cleaning Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with fermentation-scale enzyme producers capturing upstream value while regional formulators face margin compression on blended products. The market structures around captive distribution networks in healthcare and toll manufacturing arrangements for industrial applications. Two dominant competitive moves are evident: backward integration into strain development libraries, and forward integration into outcome-based service contracts bundling chemistry with compliance auditing.
Among fermentation-based enzyme specialists, Novozymes A/S exemplifies the integrated leader archetype through submerged fermentation infrastructure and protein engineering platforms. Ecolab Inc. and STERIS Corporation occupy positions within the healthcare-focused formulation tier, anchoring their market presence through captive distribution into hospital sterile processing departments. These three companies represent the concentration of supply-side capability that shapes competitive dynamics for regional blenders.
| Leading Market Players |
|---|
| Novozymes A/S |
| Ecolab Inc. |
| Reckitt Benckiser Group PLC |
| BASF SE |
| Diversey Holdings |
| STERIS Corporation |
| Henkel |
| Clorox Company |
| SC Johnson Professional |
| Others |
Supply & Pricing Matrix
Fermentation-scale capacity utilization above 85% at Danish and German enzyme plants anchors supply-side pricing power for industrial-grade protease concentrates. Hospital procurement officers in the United States and Japan absorb premium pricing for validated formulations, while regional blenders in India and Brazil face margin compression from toll manufacturing contracts and concentrated upstream supply.
Pricing Analysis
Outcome-based service contracts bundling enzymatic chemistry with dispensing equipment and compliance auditing capture lifetime value exceeding standalone chemical sales by factors of three to five. Pricing stratifies across premium validated tiers for Joint Commission-accredited US hospitals, standard performance grades for European food processors, and economy concentrates for emerging market institutional buyers. Cost compression in the standard tier intensifies as toll manufacturers consolidate, while premium healthcare segments show minimal price elasticity due to liability exposure. Food processing procurement teams exhibit highest sensitivity, negotiating on per-kilogram enzyme activity metrics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for enzyme concentrate shipments from Chinese toll manufacturers to European formulators. Production gravity centers on Denmark, Germany, and the United States for submerged fermentation infrastructure, with India and China hosting growing solid-state fermentation capacity for regional supply. Raw material dependencies include corn steep liquor, soybean meal, and pharmaceutical-grade salts for fermentation media. Single-source vulnerability concentrates in strain development libraries held by three integrated producers. Distribution runs through captive direct sales forces for healthcare accounts and chemical distributors for industrial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic cleaning markets reward service-attach models where compliance auditing and equipment maintenance contracts expand recurring revenue faster than commodity chemical volumes. The shift from transactional supply to outcome-based partnerships in US hospital systems exemplifies this structural opportunity.
For Market Incumbents: Compound defensive moats by backward integration into extremophile strain libraries for cold-water protease variants, and by deepening captive distribution through exclusive GPO contracts with integrated delivery networks. The threat of regional toll manufacturers undercutting on standard-grade concentrates demands certification investment to maintain premium positioning. For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 hospital clusters where NABH accreditation expansion outpaces established supplier coverage. The penetrable segment lies in automated endoscope reprocessing systems for ambulatory surgery centers. A go-to-market angle bundling gel-format enzymatic cleaners with leak tester integration services bypasses entrenched chemical supply relationships. For Investors and Strategic Acquirers: Regional formulators with validated healthcare dossiers and established sterile processing department relationships represent the priority acquisition archetype. Long-term viability hinges on defensible regulatory filings rather than formulation chemistry alone. The signal to watch is CDSCO enforcement tightening on imported instrument cleaning validations in India, which would accelerate consolidation toward domestic-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captures margin from fermentation-scale protease supply concentrated in Copenhagen and Basel technical centers. |
| Outcome-Based Service Contract Expansion | Shifts revenue from commodity chemical sales to bundled compliance auditing in US IDN-affiliated facilities. |
| Cold-Water Extremophile Protease Launch | Displaces heated detergent baths in German hospitals seeking KRINKO-compliant energy reduction protocols. |
| India Hospital Sector Partnership | Establishes first-mover positioning in tier-2 cities where NABH accreditation mandates enzymatic pre-cleaning. |
| REACH-Compliant QAC-Free Reformulation | Qualifies for EU Green Deal circular procurement preferences displacing benzalkonium chloride adjuncts. |
Research Methodology
The analysis maps biotechnology-derived enzyme supply, chemical formulation tiers, healthcare sterile processing workflows, and food processing clean-in-place retrofits, each validated through sterile processing department managers, fermentation plant operations directors, hospital GPO contract specialists, and regulatory affairs leads at enzymatic detergent registrants. Primary interview findings were cross-checked against EPA Safer Choice product listings, FDA 510(k) clearance databases, ECHA REACH registration dossiers, and EU public healthcare tender awards. Bottom-up volume builds from hospital infection control budget allocations and top-down checks against industrial enzyme trade flows ensured consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product format, application vertical, end-user procurement sophistication, and technology pathway including extremophile strain engineering. CAGRs were derived from elasticity-adjusted adoption curves for accreditation-mandated cleaning protocols. Industry-specific forecast inputs incorporated Joint Commission survey timing, KRINKO guideline revision cycles, and NABH accreditation expansion trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Safer Choice enforcement and stable fermentation input costs; material deviation in regulatory divergence or agricultural commodity volatility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Europe Anaerobic Digestion Market
Environmental Biotechnology
Global Bio Decontamination Market
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
Bio-Detection Market