
 HIV Market | 2026-2036
HIV Market Size, Share, and Industry Trends Forecast 2026-2036
HIV Market Outlook
Sub-Saharan Africa's manufacturing capacity build-out is fragmenting as regional governments push localized production of generic antiretrovirals. Gilead Sciences leverages its patent estate to sustain dominance in tenofovir-based formulations across developed markets. ViiV Healthcare anchors the long-acting injectable segment through cabotegravir-rilpivirine development programs.
Human immunodeficiency virus represents a retroviral pathogen targeting CD4+ T lymphocytes, with therapeutic intervention requiring sustained viral load suppression below detectable thresholds through combination antiretroviral therapy. The pharmaceutical purpose centers on preventing AIDS progression, reducing transmission risk, and enabling near-normal life expectancy for infected individuals. Antiretrovirals occupy the largest revenue pool given decades of clinical validation and payer familiarity, while long-acting injectable solutions within delivery mode represent the fastest-expanding category as adherence challenges drive formulation innovation. Combination therapy leads prescription volumes by integrating multiple mechanistic classes into single-regimen convenience.
The FDA's Breakthrough Therapy designation and EMA's accelerated assessment pathways compress development timelines for novel integrase inhibitors, directly shaping R&D investment allocation across the industry. WHO prequalification requirements govern market access for low-income country procurement through the Global Fund and PEPFAR mechanisms. Stakeholders must monitor evolving patent cliff dynamics for blockbuster antiretrovirals and calibrate portfolio transitions toward next-generation modalities before generic erosion intensifies.
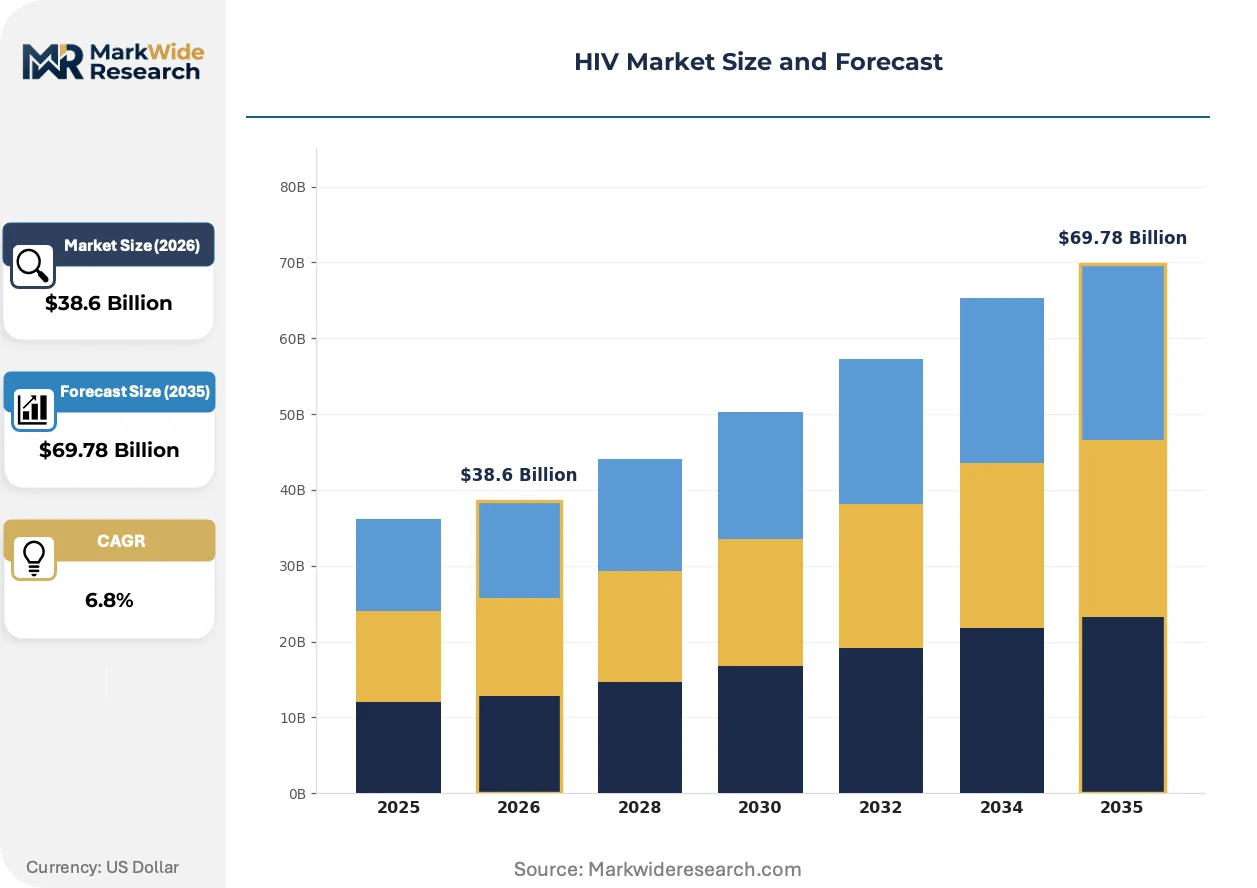
Market Dynamics
Long-acting injectable formulations are compressing dosing intervals from daily pills to monthly or quarterly administration, fundamentally altering adherence economics and reshaping competitive positioning across the HIV therapeutic landscape.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated review timelines for novel integrase inhibitors compress development cycles and redirect R&D capital toward high-potency candidates.
- Medicaid Expansion:State-level program growth in the United States is broadening patient access to advanced antiretroviral regimens through specialty clinic networks.
- Combination Therapy Integration:Single-tablet regimens incorporating multiple mechanistic classes streamline prescribing workflows and improve patient retention in care programs.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for tenofovir and emtricitabine concentrates in Indian and Chinese contract manufacturers, creating geopolitical exposure.
- Cold Chain Complexity:Long-acting injectable formulations require sustained temperature-controlled distribution, limiting reach into rural and resource-constrained settings.
- Patent Estate Barriers:Extended intellectual property protections on cornerstone molecules delay generic entry and sustain elevated pricing in developed markets.
Strategic Opportunities
- Sub-Saharan Africa Localization:Regional governments are mandating domestic production of generic antiretrovirals through technology transfer agreements with Indian manufacturers.
- Pre-Exposure Prophylaxis (PrEP) Expansion:Long-acting cabotegravir formulations are extending protection duration for high-risk populations beyond daily oral compliance requirements.
- WHO Prequalification Acceleration:Streamlined assessment pathways for generic manufacturers are unlocking access to Global Fund and PEPFAR procurement pools.
Industry Challenges
- Formulation Scientist Scarcity:Specialized expertise in nanoparticle drug delivery and polymer-based sustained-release systems remains concentrated among a limited pool of academic and industrial researchers.
- Legacy EHR Integration:Hospital systems struggle to incorporate long-acting injectable scheduling into existing electronic health record workflows designed around daily medication adherence tracking.
- Multipolar Regulatory Divergence:Misalignment between FDA risk evaluation strategies and EMA benefit-risk frameworks complicates simultaneous submission strategies for novel modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIV Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiretrovirals, Pre-Exposure Prophylaxis, Integrase Inhibitors, Non-Nucleoside Reverse Transcriptase Inhibitors Therapy Area: Combination Therapy, Maintenance Therapy, Preventive Therapy, Acute HIV Infection Management Delivery Mode: Oral Tablets, Injectable Solutions, Subcutaneous Implants, Topical Gels End User: Hospitals, Specialty Clinics, Home Care Providers, Research Institutions |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Merck & Co., Johnson & Johnson, Bristol-Myers Squibb, AbbVie, GlaxoSmithKline, Boehringer Ingelheim International GmbH, F. Hoffmann-La Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIV Market Strategic Shifts
Formulation science and digital adherence tools are converging to address the central clinical challenge of sustained viral suppression, with technology investments concentrating on reducing the cognitive and logistical burden of lifelong therapy.
Artificial intelligence-driven molecular design platforms are accelerating candidate selection for next-generation capsid inhibitors and maturation inhibitors. ViiV Healthcare and academic consortiums deploy these tools to identify compounds with improved resistance profiles. This computational approach is digitizing traditional high-throughput screening workflows and compressing preclinical timelines by eighteen to twenty-four months.
The European Medicines Agency's accelerated assessment pathway for medicines addressing unmet medical needs is shortening regulatory review periods for novel long-acting modalities. This framework prioritizes integrase strand transfer inhibitors and attachment inhibitors with demonstrated superiority over standard of care. Manufacturers are responding by front-loading European submission packages and establishing dedicated EMA liaison teams to navigate procedural requirements.
Specialty pharmacy networks are displacing traditional retail channels for antiretroviral distribution in the United States. These entities bundle medication delivery with adherence counseling, laboratory coordination, and prior authorization management. This channel migration is most pronounced in Medicaid-managed care populations and among patients initiating complex multi-drug salvage regimens.
HIV Market Segmentation
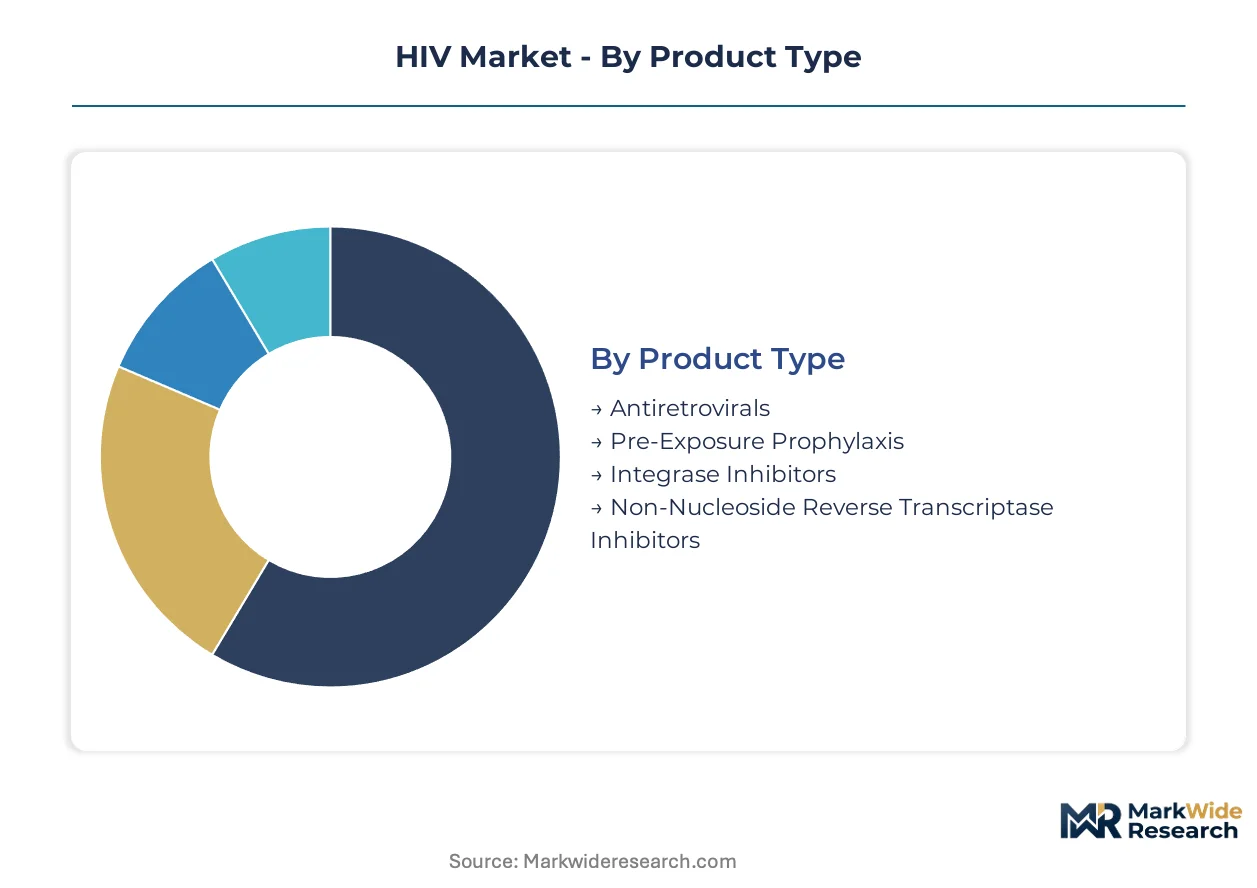
Segmentation in the HIV market reveals how therapeutic innovation, delivery technology, and care setting economics intersect to determine access patterns. Each dimension captures a distinct axis of competition—molecular mechanism, treatment phase, administration route, and institutional channel—that manufacturers must navigate simultaneously.
Product Type:
Cost tier determines reimbursement positioning and manufacturing scale across molecular categories, with patent status and bioequivalence requirements creating divergent margin structures.
- Antiretrovirals:Established nucleoside and non-nucleoside reverse transcriptase inhibitors form the backbone of first-line regimens. Demand concentrates in United States Medicaid programs and Global Fund procurement pools, where tenofovir-emtricitabine combinations face intensifying generic competition from Indian contract manufacturers.
- Pre-Exposure Prophylaxis:Daily oral tenofovir disoproxil fumarate-emtricitabine and emerging long-acting injectable alternatives target HIV-negative populations at elevated transmission risk. United States public health departments and community health centers in urban corridors drive adoption, supported by CDC guidelines expanding eligibility criteria.
- Integrase Inhibitors:High-potency strand transfer inhibitors deliver rapid viral suppression with favorable resistance profiles.
- Non-Nucleoside Reverse Transcriptase Inhibitors:Efavirenz and rilpivirine derivatives remain relevant in resource-limited settings with established supply chains.
Antiretrovirals hold installed capacity. Integrase inhibitors are rotating up the share rankings.
Therapy Area:
Application focus shifts with disease progression stage, from acute infection through lifelong maintenance, each phase demanding distinct clinical endpoints and monitoring intensity.
- Combination Therapy:Multi-class single-tablet regimens integrate two or three mechanistic classes to suppress viral replication and prevent resistance emergence. Specialty clinic networks in the United States and hospital outpatient departments in Germany and France concentrate demand, driven by treatment guidelines prioritizing complete viral suppression.
- Preventive Therapy:Pre-exposure and post-exposure prophylaxis extends HIV pharmaceutical intervention to uninfected populations. United States urban health departments and sexual health clinics in the United Kingdom anchor adoption, with long-acting injectable formulations climbing fastest as adherence barriers drive formulation preference.
- Maintenance Therapy:Simplified regimens for virologically suppressed patients emphasize tolerability and convenience.
- Acute HIV Infection Management:Intensive induction protocols target early viral reservoir reduction.
Combination therapy holds installed capacity. Preventive therapy is rotating up the share rankings.
Delivery Mode:
Volume distribution reflects the tension between oral familiarity and injectable adherence advantages, with cold chain requirements and administration infrastructure determining geographic reach.
- Oral Tablets:Daily single-tablet regimens dominate prescription volumes through decades of clinical familiarity and pharmacy distribution efficiency. United States retail and specialty pharmacy channels, alongside India's government procurement systems, sustain massive dispensing scale despite adherence limitations.
- Injectable Solutions:Long-acting intramuscular and subcutaneous formulations compress dosing intervals to monthly or quarterly intervals. United States hospital outpatient infusion centers and select European specialist clinics concentrate early adoption, with cabotegravir-rilpivirine leading clinical validation.
- Subcutaneous Implants:Polymer-based sustained-release devices promise multi-year protection with removable reversibility.
- Topical Gels:Microbicide formulations target user-controlled prevention in settings where systemic exposure raises concerns.
Oral tablets hold installed capacity. Injectable solutions are rotating up the share rankings.
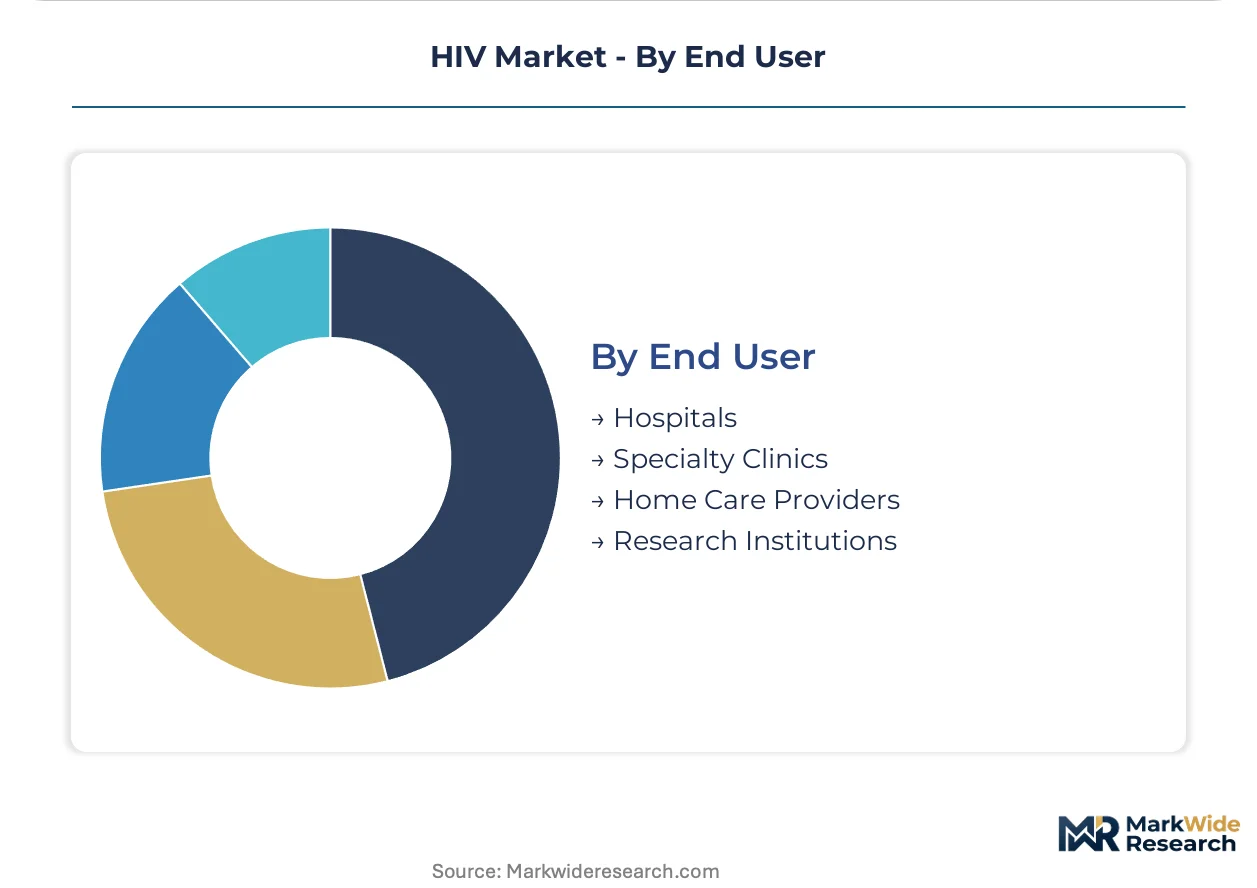
End User:
Customer type segmentation captures institutional capability gradients—clinical complexity management, laboratory integration, and patient navigation resources—that determine which settings can deploy advanced modalities.
- Hospitals:Academic medical centers and community hospital systems manage acute HIV presentations, treatment-naive patients, and complex multi-drug resistance. United States urban safety-net hospitals and National Health Service trusts in England anchor demand, integrating infectious disease specialists with laboratory theranostic capabilities.
- Specialty Clinics:Dedicated HIV treatment centers concentrate expertise in antiretroviral selection, resistance testing, and adherence support. Ryan White-funded clinics across the United States and hospital-affiliated infectious disease practices in Spain and Italy drive prescription volume for novel formulations.
- Home Care Providers:Nurse-administered long-acting injectable programs extend reach beyond traditional clinical settings.
- Research Institutions:Clinical trial sites and academic medical centers generate pipeline demand for investigational modalities.
Hospitals hold installed capacity. Specialty clinics are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors European distribution of temperature-sensitive biologics, while the US Interstate Highway System enables just-in-time delivery to specialty clinic networks across the continental United States.
United States
Medicaid expansion across 40 states broadens patient access to integrase inhibitor regimens. The FDA's Breakthrough Therapy designation compresses review timelines for novel long-acting formulations. Ryan White-funded specialty clinics in Atlanta, Houston, and Miami concentrate prescription volume for cabotegravir-rilpivirine programs.
Germany
Hospital outpatient departments in Berlin and Munich drive demand for single-tablet combination therapies. EMA accelerated assessment pathways prioritize integrase strand transfer inhibitors with demonstrated viral suppression superiority. The Rhine-Main biotechnology cluster hosts formulation development partnerships between academic medical centers and contract research organizations.
India
Government procurement systems in Maharashtra and Karnataka sustain massive dispensing scale for generic tenofovir-emtricitabine. CDSCO streamlined approval pathways for prequalified generic manufacturers unlock WHO procurement pools. The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates active pharmaceutical ingredient production for export to Sub-Saharan Africa.
South Africa
Provincial health departments in Gauteng and KwaZulu-Natal manage the continent's largest antiretroviral treatment program. Technology transfer agreements with Indian manufacturers mandate localized production of generic first-line regimens. The Durban-Pinetown industrial zone hosts tableting and packaging facilities serving SADC procurement pools.
Brazil
Ministry of Health distribution networks reach treatment-naive patients in São Paulo and Rio de Janeiro metropolitan areas. ANVISA streamlined registration pathways for WHO-prequalified generics accelerate market entry. The São Paulo-Guarulhos pharmaceutical cluster concentrates importation and secondary packaging for national universal access programs.
HIV Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying molecular entities and delivery technologies. The HIV therapeutic market consolidates around vertically integrated pharmaceutical conglomerates with patent-protected antiretroviral portfolios. Three archetypes dominate: originators with extended intellectual property estates, generic manufacturers with WHO prequalification status, and long-acting formulation specialists with polymer-based sustained-release capabilities. Competitive moves concentrate on patent lifecycle management and geographic licensing arrangements.
Among originator-tier developers, Gilead Sciences and ViiV Healthcare exemplify the patent-anchored archetype, occupying positions sustained by molecular estate breadth. Merck & Co. represents the diversified conglomerate model with antiretroviral assets integrated across broader infectious disease portfolios.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Merck & Co. |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| AbbVie |
| GlaxoSmithKline |
| Boehringer Ingelheim International GmbH |
| F. Hoffmann-La Roche |
| Others |
Value Chain & Pricing Dynamics
The Hyderabad-Visakhapatnam pharmaceutical corridor anchors global tenofovir API production, and its capacity utilization rates directly determine pricing leverage for downstream generic formulators across Sub-Saharan Africa procurement pools.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates originator integrase inhibitors from WHO-prequalified generics and regional tender products. Price differentiation hinges on FDA breakthrough designation status and cold chain delivery requirements. Pricing pressure stems from Indian contract manufacturers scaling emtricitabine output for Global Fund volume tenders. Medicaid managed care plans exhibit highest price sensitivity; private specialty clinics in the United States show lowest.
Supply Chain Analysis
Tariff exposure between India and the United States dominates supply chain risk calculations for API shipments. Active pharmaceutical ingredient manufacturing concentrates in India, China, and the United States. Formulation depends on tenofovir disoproxil fumarate, emtricitabine, and cabotegravir sodium inputs. Distribution runs through Rotterdam's pharmaceutical cold chain hub for European long-acting injectable reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as long-acting injectable demand splits between hospital outpatient capacity and emerging home-administration models, creating distinct service-layer niches beyond molecule supply.
For Market Incumbents: Harden patent estate defenses around integrase inhibitor formulations through secondary use claims and pediatric indication extensions. Indian generic manufacturers with WHO prequalification status threaten originator pricing in Global Fund tenders. Backward integration into polymer-based sustained-release excipient production secures formulation differentiation.
For New Entrants and Emerging Players: Pursue technology licensing agreements with academic medical centers holding polymer-based depot formulation IP. Sub-Saharan Africa localization mandates create the most penetrable geography for regional manufacturing joint ventures. Partner with national health departments on tender prequalification to bypass originator channel control.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors long-acting formulation specialists with demonstrated bioequivalence data and EMA accelerated assessment pathway experience. Five-to-ten year viability rests on pipeline depth beyond daily oral regimens. Watch FDA breakthrough therapy designation velocity for novel capsid inhibitors as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III cabotegravir-rilpivirine programs validate quarterly dosing superiority against daily oral standard. |
| Regulatory Approval Pathway | EMA accelerated assessment compresses review timelines for integrase strand transfer inhibitors with resistance profile advantages. |
| Manufacturing Scale-Up | Durban-Pinetown tableting facilities expand to serve SADC procurement pools under technology transfer terms. |
| Pipeline Diversification | Capsid inhibitor and maturation inhibitor candidates address emerging resistance mutations in salvage populations. |
| Licensing Agreement | Indian API producers secure technology transfer for generic tenofovir production under WHO prequalification standards. |
Study Parameters
Desk research of FDA approval databases, EMA assessment reports, and WHO prequalification listings preceded structured interviews with infectious disease specialists, hospital formulary directors, and Global Fund procurement officers. Primary fieldwork captured prescribing patterns across Ryan White-funded clinics and European hospital outpatient departments. Secondary validation drew from ClinicalTrials.gov filings, CMS Medicaid utilization data, and PEPFAR supply chain disclosures. Bottom-up patient volume estimates and top-down pharmaceutical revenue aggregates underwent cross-triangulation.
Fixed assumptions held regulatory approval timelines and reimbursement parity constant across the projection horizon, while patient adherence rates and generic entry timing varied as sensitivity inputs. Segmentation modeling incorporated treatment line, delivery mode, and regional regulatory cluster dimensions. CAGRs derived from patient population growth, therapy switching velocity, and price erosion curves for patent-expired molecules. Forecast inputs included Medicaid expansion state coverage rates and cold chain infrastructure development indices.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility for Indian rupee-denominated API contracts or disruptions to PEPFAR appropriations would shift the trajectory. Forecasts reflect documented assumptions about patent cliff sequencing and biosimilar substitution readiness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Mefentrifluconazole Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Echinocandins Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Global Bioengineered Protein Drugs Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Chronic Phase Markers Market