
 Linaclotide API Market | 2026-2036
Linaclotide API Market Size, Share, and Industry Trends Forecast 2026-2036
Linaclotide API Market Insights
Buyer concentration among pharmaceutical manufacturers is recalibrating contract structures for linaclotide API supply. Sun Pharmaceutical Industries Limited leverages integrated peptide manufacturing infrastructure to secure long-term supply agreements with branded and generic drug developers. Teva Pharmaceutical Industries anchors its position through specialized fermentation and solid-phase synthesis capabilities that reduce batch-to-batch variability. Zydus Lifesciences differentiates by controlling downstream purification stages that meet escalating pharmacopeial standards.
Linaclotide API is a 14-amino-acid peptide agonist of guanylate cyclase-C, synthesized through solid-phase peptide synthesis with N-terminal pyroglutamyl and C-terminal tyrosine amidation, used primarily to treat irritable bowel syndrome with constipation and chronic idiopathic constipation by increasing intestinal fluid secretion and transit. Capsule formulations dominate current offtake volumes due to established bioavailability profiles and patient compliance patterns, while oral suspensions represent the fastest-expanding product category as pediatric and geriatric dosing requirements gain regulatory traction. The irritable bowel syndrome therapy area commands the deepest margin pools owing to sustained prescription renewals and limited therapeutic alternatives within the guanylate cyclase-C agonist class.
FDA peptide impurity guidance and USP monograph revisions are elevating analytical validation burdens for API manufacturers seeking US market access. EMA's revised GMP Annex 1 and ICH Q7 guidelines impose comparable sterility and cross-contamination controls on European-bound production batches. CDSCO in India is aligning bioequivalence requirements for linaclotide generics with innovator reference standards, reshaping export qualification pathways. Stakeholders must monitor evolving pharmacopeial harmonization between FDA, EMA, and national regulators to anticipate qualification timeline shifts.
Market Dynamics
Peptide synthesis technology maturation and tightening pharmacopeial impurity thresholds are recalibrating supplier qualification requirements for linaclotide API procurement. Solid-phase synthesis automation and analytical method advances are compressing batch variability while FDA and EMA peptide quality guidelines elevate entry barriers for new market participants.
Growth Catalysts
- Guanylate cyclase-C agonist class expansion:Irritable bowel syndrome with constipation and chronic idiopathic constipation prescription volumes in the United States are sustaining offtake momentum as physicians consolidate therapy selection within this mechanism class.
- EMA revised GMP Annex 1 alignment:European manufacturing standards for sterile peptide production are harmonizing with FDA peptide impurity guidance, streamlining dual-market qualification pathways for compliant suppliers.
- Oral suspension formulation development:Pediatric and geriatric dosing requirements are opening new patient segments beyond capsule formulations, expanding addressable prescription pools for API manufacturers.
Market Restraints
- Specialized raw material concentration:Fmoc-protected amino acids and specialized resins for solid-phase synthesis concentrate among limited chemical suppliers, creating input cost volatility exposure.
- Peptide impurity analytical burden:FDA peptide impurity guidance and USP monograph revisions mandate extensive method validation investments that disproportionately burden mid-scale API manufacturers.
- Biologic constipation therapy competition:PEGylated compounds and other osmotic agents present established therapeutic alternatives that constrain pricing power for guanylate cyclase-C agonists in certain markets.
Strategic Opportunities
- CDSCO bioequivalence pathway alignment:India's national pharmaceutical regulator is harmonizing linaclotide generic requirements with innovator standards, creating export qualification advantages for domestic manufacturers serving regulated markets.
- Continuous flow peptide synthesis:Converging automation and real-time analytical technologies are enabling process intensification that reduces solvent consumption and batch cycle times.
- Japan PMDA pediatric indication expansion:Japanese regulatory frameworks for pediatric gastrointestinal therapies present underpenetrated demand pools as local prescribers seek alternatives to osmotic laxatives.
Industry Challenges
- Peptide analytical chemist scarcity:Specialized expertise in mass spectrometry method development and impurity profiling for complex peptides remains concentrated among experienced practitioners, constraining quality team scaling.
- Multi-regulatory filing synchronization:Staggered pharmacopeial updates across FDA, EMA, and national regulators force API manufacturers to maintain parallel validation protocols, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Linaclotide API Market |
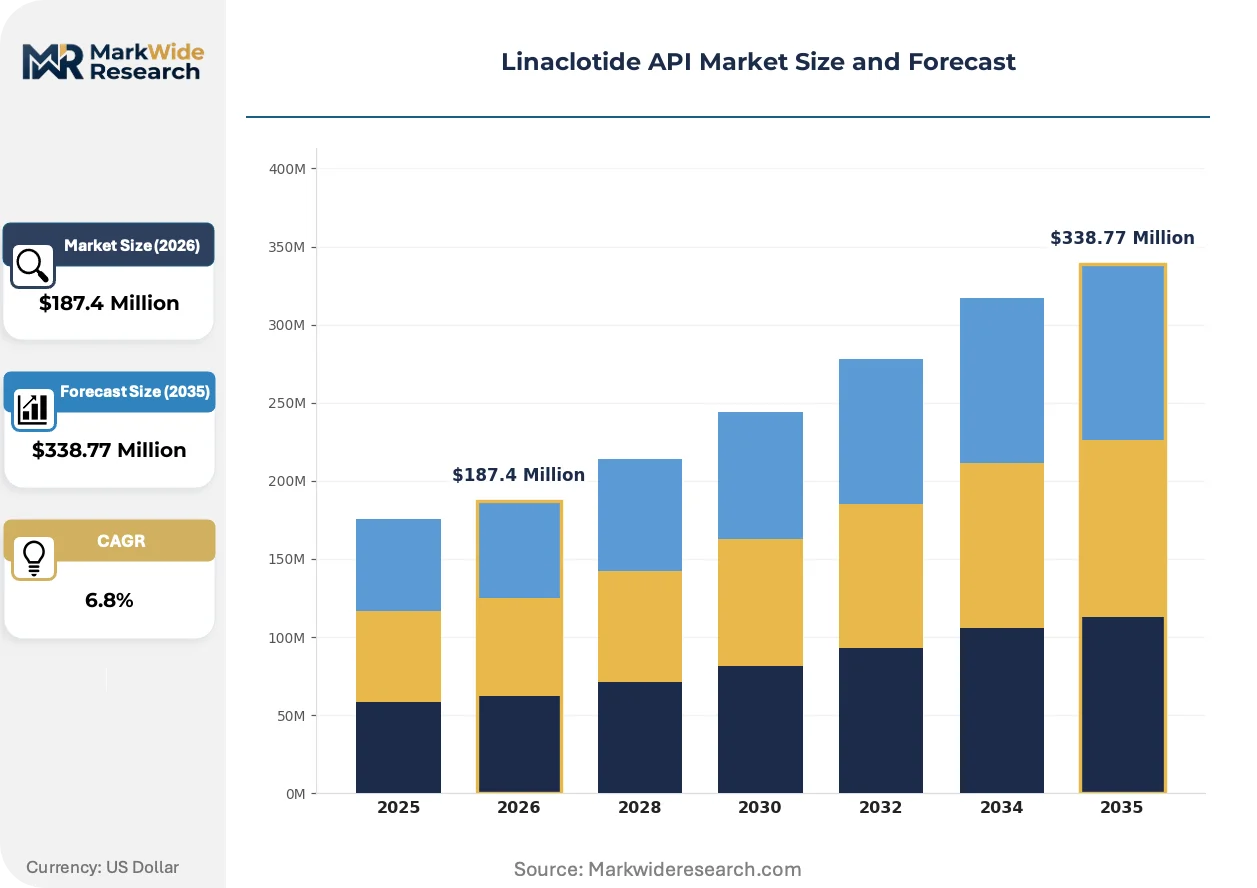
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Oral Suspensions, Solutions Therapy Area: Irritable Bowel Syndrome, Chronic Constipation, Gastroenterology, Functional Gastrointestinal Disorders End User: Pharmaceutical Manufacturers, Contract Research Organizations, Hospitals, Clinics Distribution Channel: Direct Sales, Distributors, Online Platforms, Pharmacies |
| Companies Covered | Sun Pharmaceutical Industries Limited, Alkem Laboratories, Hetero, Suzhou Tianma Pharma Group Co Ltd, Teva Pharmaceutical Industries, Viatris, Xiushi Biopharma, Yifan Pharmaceutical, Zydus Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Linaclotide API Market Trends and Innovations
Automation in solid-phase peptide synthesis and real-time process analytical technologies are compressing manufacturing variability while regulatory agencies synchronize quality standards across major pharmaceutical markets. These shifts are reconfiguring supplier competitive positioning and procurement evaluation criteria.
Continuous manufacturing platforms for peptide APIs are expanding into commercial-scale production as equipment vendors refine flow chemistry modules for 14-amino-acid sequences. Contract manufacturers in India and the United States are piloting these systems to reduce solvent waste and accelerate batch release timelines. This technology is expanding into quality-assured supply agreements with branded pharmaceutical developers seeking manufacturing flexibility.
EMA's revised GMP Annex 1 implementation is mandating enhanced environmental monitoring and closed-system processing for sterile peptide operations. European API manufacturers are retrofitting isolation technology and rapid microbial detection systems to maintain market access. Sterile peptide formulation capabilities are most affected, with suppliers consolidating production into purpose-built facilities rather than adapting legacy antibiotic manufacturing suites.
Pharmaceutical buyers are consolidating API procurement under long-term supply agreements with embedded quality metrics and volume commitments. Large generic developers are displacing spot-market purchasing with partnership structures that transfer analytical method validation responsibilities upstream to API manufacturers. This pattern is most visible in the United States, where abbreviated new drug application sponsors seek regulatory risk mitigation through supplier integration.
Linaclotide API Market Segmentation
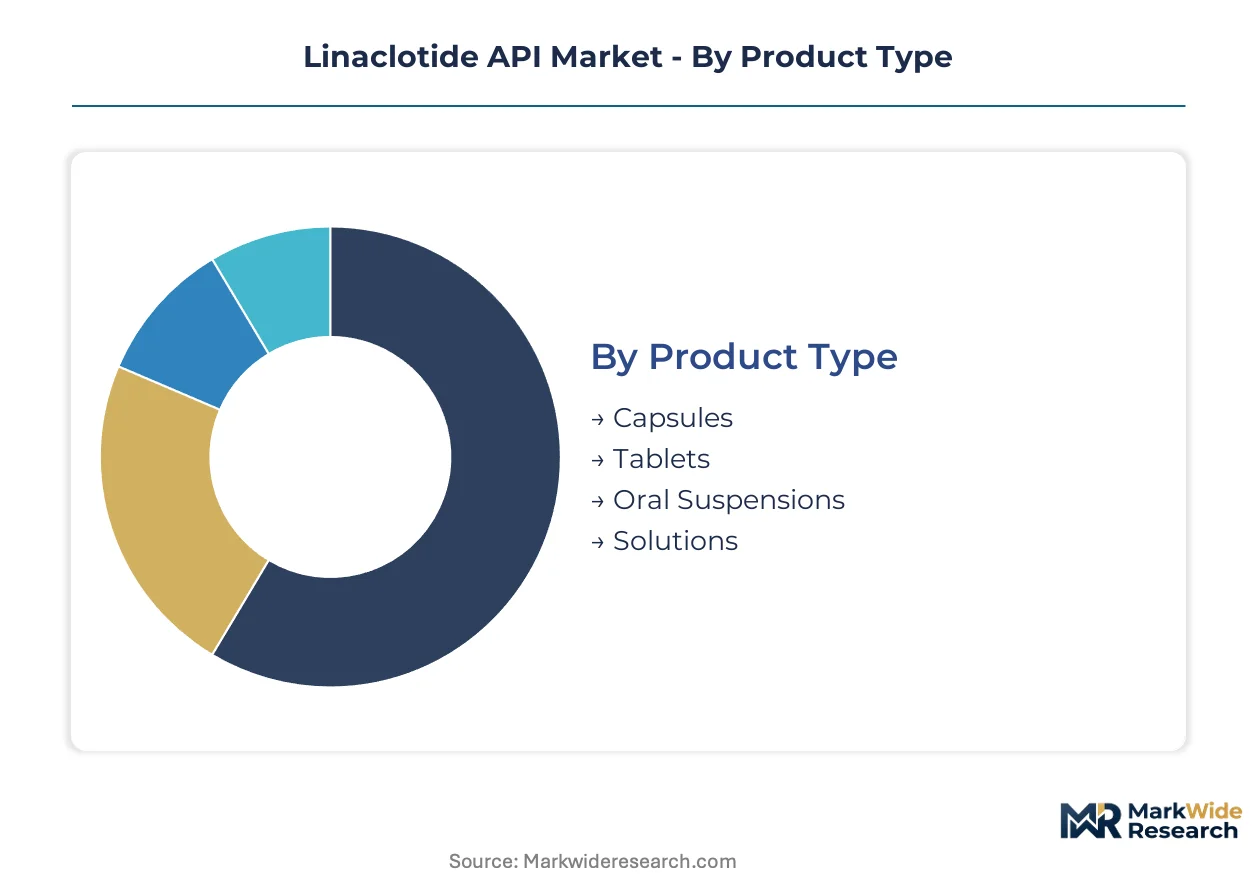
Peptide API procurement patterns diverge sharply across formulation types and therapeutic applications, with contract structures and qualification requirements varying by segment. Manufacturers align synthesis capacity and purification investments against specific end-use demand profiles to defend margin positions.
Product Type:
Supply concentration for finished dosage forms dictates API specification tiers and batch release protocols.
- Capsules:Hard gelatin and HPMC capsule formulations dominate current offtake due to established bioavailability profiles and patient compliance patterns. Demand concentrates among branded pharmaceutical developers in the United States seeking regulatory risk mitigation through supplier integration.
- Oral Suspensions:Liquid formulations with particle size-controlled API dispersion enable pediatric and geriatric dosing flexibility. This segment is expanding most quickly as PMDA pediatric indication pathways and FDA guidance on age-appropriate formulations gain traction.
- Tablets:Compressed solid dosage forms require modified release technologies to protect the peptide from gastric degradation.
- Solutions:Ready-to-use liquid presentations serve institutional dispensing and clinical trial supply chains.
Capsules absorb the bulk of installed capacity; oral suspensions are expanding most quickly.
Therapy Area:
Margin pools and prescription renewal patterns vary substantially across gastrointestinal indications, reshaping API contract valuation.
- Irritable Bowel Syndrome:Guanylate cyclase-C agonist therapy for IBS with constipation commands the deepest margin pools due to sustained prescription renewals and limited therapeutic alternatives within this mechanism class. Demand concentrates among specialty gastroenterology practices in the United States with favorable reimbursement frameworks.
- Chronic Constipation:Chronic idiopathic constipation indications face pricing pressure from osmotic laxative alternatives but maintain volume through primary care prescribing. This segment is gaining share fastest as European markets expand reimbursement for prescription constipation therapies.
- Gastroenterology:Broader GI practice prescribing spans functional and organic disorders with variable diagnostic coding.
- Functional Gastrointestinal Disorders:Overlapping symptom profiles with IBS create formulary positioning challenges for API specifications.
Irritable bowel syndrome therapy absorbs the bulk of margin concentration; chronic constipation is climbing the fastest.
End User:
Customer type determines validation burden distribution and long-term contract structure preferences.
- Pharmaceutical Manufacturers:Integrated branded and generic drug developers anchor API demand through multi-year supply agreements with embedded quality metrics. These buyers concentrate in the United States and India, transferring analytical method validation responsibilities upstream to API suppliers.
- Contract Research Organizations:CROs serving clinical trial material supply chains require flexible batch scales and accelerated release timelines. This segment shows steepest expansion trajectory as peptide therapy pipelines diversify across gastrointestinal indications.
- Hospitals:Institutional procurement of compounded formulations represents niche demand with specialized sterility requirements.
- Clinics:Outpatient gastrointestinal practices drive sampling and starter prescription volumes with limited API direct purchasing.
Pharmaceutical manufacturers absorb the bulk of contract value; contract research organizations are expanding most quickly.
Distribution Channel:
Channel configuration shapes working capital requirements and geographic market access patterns.
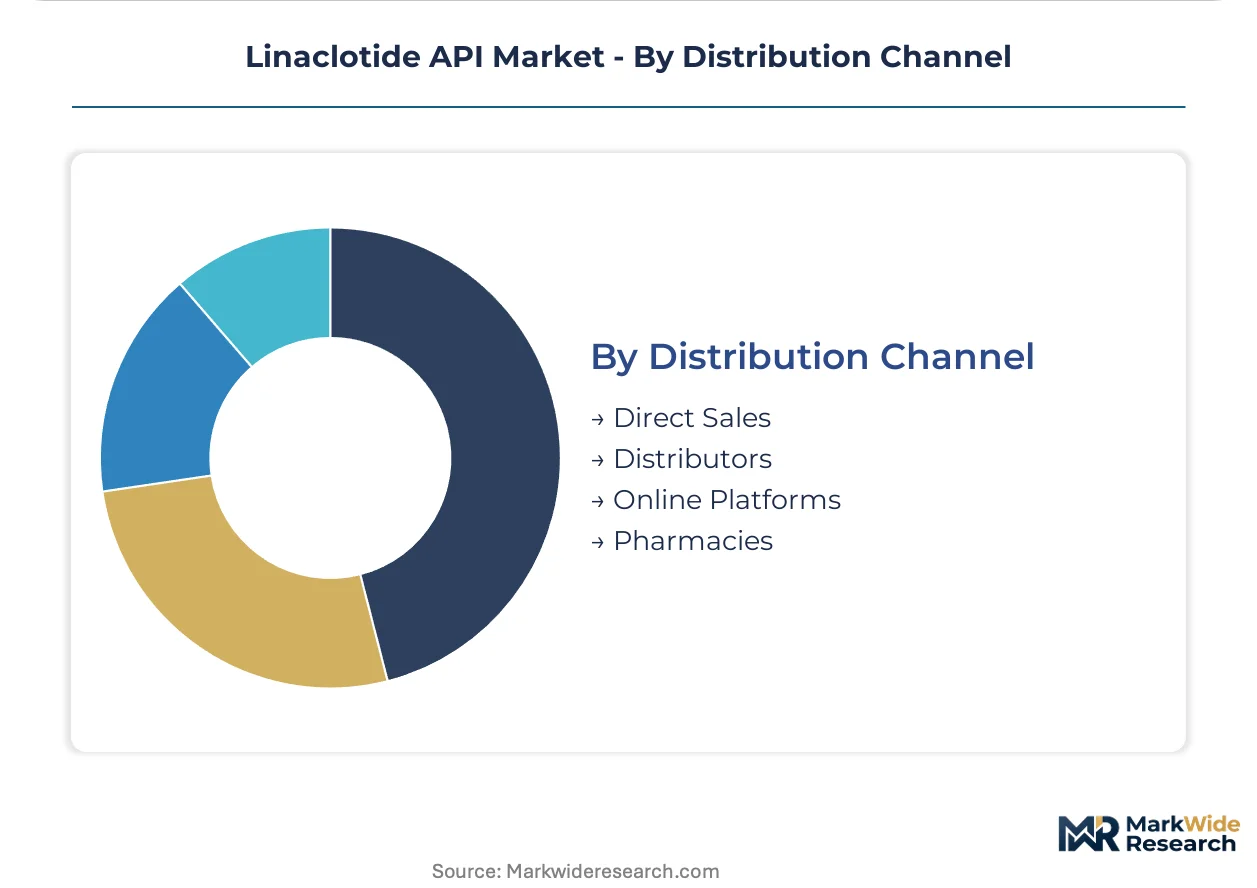
- Direct Sales:Manufacturer-to-manufacturer API supply agreements dominate high-volume procurement, enabling embedded quality audits and regulatory filing support. Demand concentrates among FDA and EMA-registered pharmaceutical developers seeking qualification pathway streamlining.
- Distributors:Specialized peptide and API distributors serve mid-scale generic developers and emerging market manufacturers with inventory aggregation and technical documentation bundling.
- Online Platforms:Digital procurement channels facilitate spot-market purchasing for research-grade and developmental quantities.
- Pharmacies:Compounding pharmacy API sourcing represents fragmented, specification-variable demand with limited commercial scale.
Direct sales absorb the bulk of transaction value; distributor channels are gaining share fastest in emerging market qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fmoc-protected amino acid suppliers cluster in Gujarat and Maharashtra, anchoring Indian API export capacity for peptide synthesis. Pharmaceutical buyers in the United States and Europe source from these feedstock localities while navigating divergent regulatory qualification pathways.
United States
Specialty gastroenterology practices in the United States sustain prescription volumes for guanylate cyclase-C agonists through favorable reimbursement frameworks. FDA peptide impurity guidance and USP monograph revisions elevate analytical validation burdens for API manufacturers seeking market access. Boston and Research Triangle Park host contract manufacturing organizations piloting continuous flow peptide synthesis for commercial-scale production.
India
Domestic generic developers in India expand linaclotide API capacity to serve regulated export markets as CDSCO aligns bioequivalence requirements with innovator standards. The PLI scheme incentivizes backward integration into specialized amino acid and resin production. Ahmedabad and Hyderabad concentrate solid-phase synthesis operations with integrated downstream purification infrastructure.
Germany
EMA revised GMP Annex 1 implementation drives retrofit investments in sterile peptide manufacturing across German production facilities. REACH compliance requirements for chemical inputs intersect with pharmaceutical quality standards for European market supply. Frankfurt-Rhine-Main and Bavaria host specialized distributors aggregating peptide API inventory for mid-scale generic developers.
Japan
PMDA pediatric indication expansion for gastrointestinal therapies creates underpenetrated demand pools as prescribers seek alternatives to osmotic laxatives. METI frameworks support process analytical technology adoption in peptide manufacturing. Osaka-Kobe and Tokyo-Yokohama clusters concentrate formulation development partnerships between domestic pharmaceutical developers and API suppliers.
Switzerland
Swissmedic quality standards for biologic-derived APIs attract specialized peptide manufacturers seeking premium-tier market positioning. Dual-market qualification capabilities for FDA and EMA jurisdictions concentrate in Basel and Zurich pharmaceutical corridors. Contract manufacturers here leverage existing sterile biologics infrastructure for guanylate cyclase-C agonist production.
Linaclotide API Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue differentiated purification technologies and continuous manufacturing platforms. The supplier base concentrates among integrated pharmaceutical manufacturers with captive peptide synthesis infrastructure and specialized contract manufacturers serving generic drug developers. Three archetypes dominate: vertically integrated Indian conglomerates with amino acid backward integration, Israeli-American specialists leveraging fermentation-to-synthesis capabilities, and mid-scale Chinese manufacturers competing on batch scale flexibility. Capacity expansion and strategic partnerships represent the dominant competitive moves, with API suppliers embedding quality metrics into multi-year supply agreements.
Among Indian integrated manufacturers, Sun Pharmaceutical Industries Limited and Zydus Lifesciences exemplify the vertically integrated archetype with peptide manufacturing infrastructure spanning synthesis through purification. Teva Pharmaceutical Industries occupies a position representing specialized fermentation and solid-phase synthesis capabilities developed across Israeli and American production networks. Suzhou Tianma Pharma Group Co Ltd anchors the Chinese specialist tier, while Alkem Laboratories and Hetero sit within the domestic generic API supplier segment serving regulated export qualification pathways.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Limited |
| Alkem Laboratories |
| Hetero |
| Suzhou Tianma Pharma Group Co Ltd |
| Teva Pharmaceutical Industries |
| Viatris |
| Xiushi Biopharma |
| Yifan Pharmaceutical |
| Zydus Lifesciences |
| Others |
Pricing and Supply Chain Analysis
Continuous flow peptide synthesis adoption is compressing production economics while redrawing competitive boundaries between batch-scale specialists and automation-capable manufacturers. This technology transition concentrates cost advantages among suppliers with capital depth for real-time analytical infrastructure, while contract structures increasingly bundle method validation services with API unit pricing.
Pricing Analysis
Warranty and service bundling separates API supply agreements into two distinct tiers: comprehensive packages embedding regulatory filing support and analytical method transfer versus unbundled transactional pricing for qualified generic developers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with FDA-registered manufacturers commanding substantial premiums over CDSCO-qualified suppliers. Cost compression in the standard tier is intensifying because EMA GMP Annex 1 retrofit investments are transferring downstream to API purchasers. Mid-scale generic developers in India exhibit the highest price sensitivity, while branded pharmaceutical manufacturers in the United States prioritize regulatory risk mitigation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Fmoc-protected amino acid suppliers concentrated in Gujarat and Maharashtra, where limited chemical manufacturers control critical synthesis inputs. Raw material dependencies draw from specialized resin producers in China, solvent suppliers in Germany, and analytical reference standard manufacturers in Switzerland. Tariff exposure on Chinese-sourced resins presents structural risk as pharmaceutical buyers dual-source to mitigate qualification timeline disruptions. Distribution runs through direct manufacturer-to-manufacturer agreements for high-volume procurement, with specialized distributors serving mid-scale emerging market developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-phase peptide synthesis automation is displacing legacy batch manufacturing, creating asymmetric returns for suppliers with integrated continuous processing capabilities versus conventional fermentation-dependent producers.
For Market Incumbents: Hedge against biologic constipation therapy competition by embedding quality metrics into long-term supply agreements that transfer analytical validation upstream. Prioritize backward integration into Fmoc-protected amino acid production to reduce input cost volatility exposure from Gujarat chemical suppliers. Capacity addition in Hyderabad and Ahmedabad production clusters defends margin position against emerging Chinese automation specialists. For New Entrants and Emerging Players: Contract research organizations serving clinical trial material supply chains represent the most penetrable buyer archetype, with flexible batch scale requirements and accelerated release timelines that favor agile manufacturing platforms. Target pediatric formulation developers seeking oral suspension API specifications as FDA guidance on age-appropriate dosing gains traction. A specialized purification technology go-to-market angle differentiates against established solid-phase synthesis incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by branded pharmaceutical developers seeking captive peptide synthesis capacity. Long-term viability favors suppliers with dual FDA-EMA qualification capabilities and continuous manufacturing platform investments. The signal to watch is PMDA pediatric indication expansion velocity, which indicates addressable prescription pool growth for guanylate cyclase-C agonist APIs.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Peptide Synthesis Adoption | Reduces solvent consumption and batch cycle times for 14-amino-acid sequences. |
| Backward Integration into Amino Acid Production | PLI scheme incentives in India support captive Fmoc-protected input supply. |
| Dual-Market Qualification Investment | FDA and EMA synchronization streamlines regulatory filing support for generic developers. |
| Pediatric Formulation Development Partnership | PMDA pathways for age-appropriate dosing expand addressable prescription pools. |
| Real-Time Process Analytical Technology Deployment | METI frameworks in Japan accelerate automation adoption for quality-assured supply. |
Research Methodology
Multi-period observation of prescription volume trends, regulatory filing patterns, and supplier qualification timelines anchored the trend analysis, supplemented by interviews with peptide synthesis chemists, regulatory affairs leads at API manufacturers, formulary directors at United States payers, and procurement managers at generic drug developers. Secondary validation drew from FDA peptide impurity guidance documents, EMA GMP Annex 1 revisions, CDSCO bioequivalence notifications, USP monograph updates, and clinical trial registration databases. Bottom-up capacity assessments across Indian and Chinese manufacturing facilities were triangulated against top-down prescription demand models.
Input-output matrices mapped synthesis capacity, raw material feedstock availability, and downstream formulation demand across product type, therapy area, and end-user segments over the projection horizon. CAGRs were derived from regression analysis of historical prescription volumes against manufacturing capacity expansion schedules. Forecast inputs incorporated regulatory timeline assumptions for pharmacopeial harmonization between FDA, EMA, and national regulators, as well as technology adoption curves for continuous flow peptide synthesis platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pharmacopeial impurity threshold revisions and competitive entry from biologic constipation therapies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
North America Plasma Fractionation Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market